
 Nigeria Automotive Lubricants Market | 2026-2036
Nigeria Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Automotive Lubricants Market Outlook
API SP and ACEA C-grade lubricant demand is rotating toward higher-specification formulations as Nigerian fleet operators and OEM workshops seek extended drain intervals and engine protection under harsh operating conditions. TotalEnergies leverages its blending facility in Apapa to sustain supply chain proximity to Lagos port traffic. MRS Oil Nigeria PLC anchors its position through retail network density across the Niger Delta. Ardova Plc competes via integrated fuel-and-lube forecourt operations that capture commercial vehicle traffic.
Automotive lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, prevent corrosion, and suspend contaminants in internal combustion engines and drivetrain systems; their viscosity grades and additive packages must withstand elevated thermal loads, particulate ingress, and extended service intervals common in tropical climates. Engine oil dominates value capture given its high-volume replacement cycle and premiumization toward synthetic and semi-synthetic grades among fleet operators. Transmission fluid represents the fastest-growing product category as automatic vehicle penetration rises in urban centers. Heavy-duty equipment application commands superior per-liter margins through specialized hydraulic and gear oil formulations serving construction and mining contractors.
The Standards Organisation of Nigeria mandates lubricant labeling and quality certification, while the Department of Petroleum Resources oversees petroleum product standards and environmental compliance for blending operations. Nigeria's automotive lubricant stakeholders must monitor regulatory enforcement intensity around counterfeit product interdiction and base oil import duty structures. Fleet operators and blenders need to decide between backward integration into base oil trading or deepening formulation partnerships with international additive suppliers.
Market Dynamics
The aging Nigerian vehicle parc and intensifying commercial transport activity are compressing lubricant replacement cycles while elevating specification requirements for API-certified formulations. Fleet operators now prioritize extended drain intervals and thermal stability under tropical operating conditions, forcing blenders to upgrade base stock quality and additive packages.
Growth Catalysts
- API SP Certification Mandate:The Standards Organisation of Nigeria enforces quality benchmarks that favor higher-grade lubricant formulations, compelling blenders to source premium base oils and advanced additive systems.
- Fleet Modernization Pressure:Commercial vehicle operators in Lagos and the South-West corridor are consolidating procurement around synthetic and semi-synthetic grades to reduce downtime and maintenance costs.
- Port Logistics Expansion:Dense industrial zones around Apapa and Tin Can Island are generating concentrated demand for heavy-duty hydraulic and gear oil formulations serving container handling equipment.
Market Restraints
- Base Oil Import Dependency:Nigeria lacks domestic Group II/III base oil production, exposing blenders to currency volatility and freight cost fluctuations on Asian and Middle Eastern supply.
- Counterfeit Product Infiltration:Substandard lubricant formulations mislabeled as API-certified drain value from compliant manufacturers and erode fleet operator trust in formal distribution channels.
- Group I Base Stock Obsolescence:Technical limitations of locally available Group I base oils prevent blenders from cost-effectively meeting ACEA C-grade specifications for modern diesel after-treatment systems.
Strategic Opportunities
- Niger Delta Industrial Corridor:Underpenetrated mining and oilfield services in Rivers and Bayelsa states present white space for specialized hydraulic fluid and compressor oil formulations.
- Automatic Transmission Penetration:Urban vehicle fleets in Abuja and Lagos are accelerating adoption of automatic gearboxes, creating demand for synthetic ATF with extended service life.
- Forecourt Integration Models:Fuel retail networks are capturing commercial vehicle traffic through combined diesel-and-lubricant procurement, reducing fleet operator transaction costs.
Industry Challenges
- Blending Technician Shortage:Formulation chemistry expertise and quality control laboratory capacity lag behind specification complexity, constraining product development timelines.
- SON Certification Bottlenecks:Laboratory testing backlogs and documentation requirements delay product registration, compressing effective selling seasons for seasonal formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Automotive Lubricants Market |
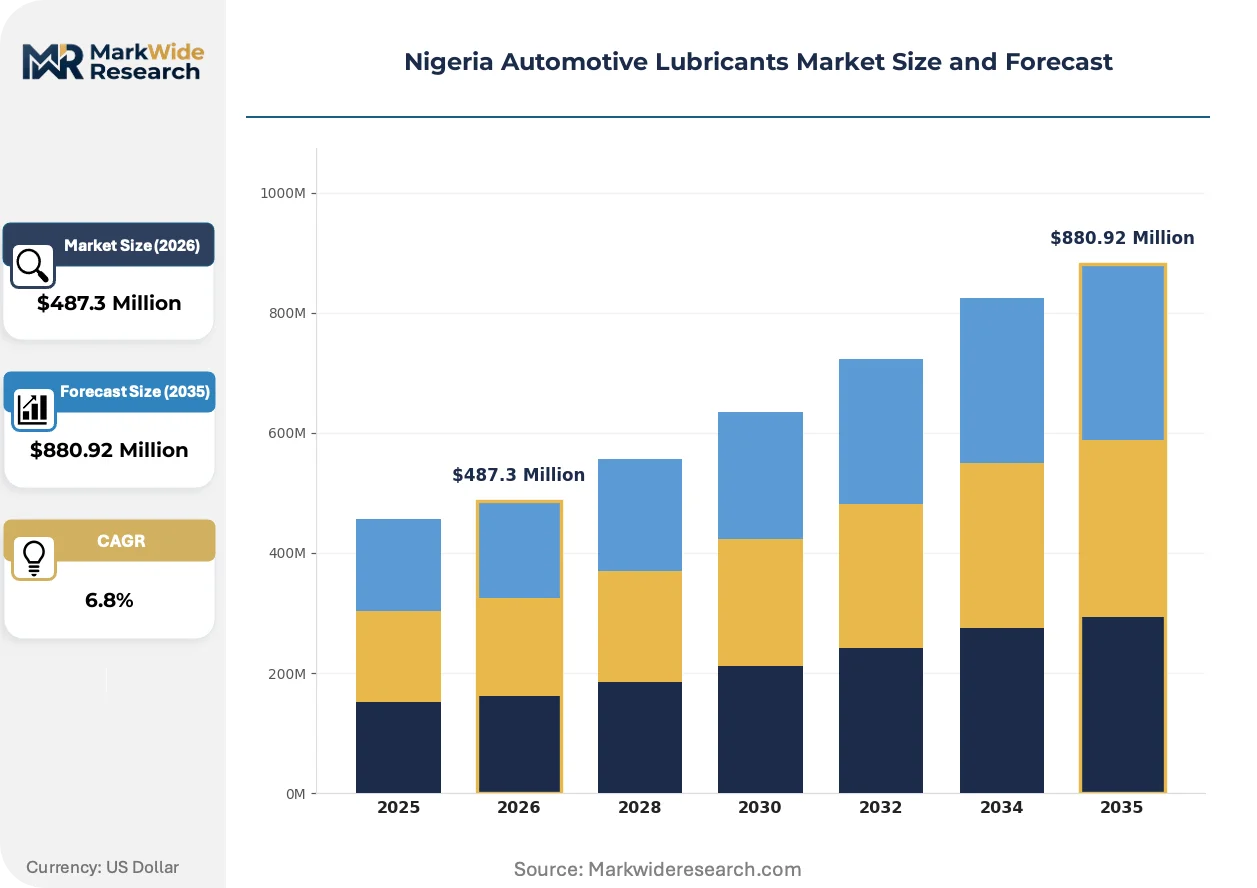
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Oil Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Equipment, Motorcycles Distribution Channel: Retail, Online, Wholesalers, Auto Parts Shops End User: Individual Consumers, Garages, Fleet Operators, OEMs |
| Companies Covered | BP Plc (Castrol), MRS Oil Nigeria PLC, 11 Plc, Eterna Plc, Ammasco International Limited, Ardova Plc, TotalEnergies, Conoil PLC, Oando PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Automotive Lubricants Market Strategic Shifts
Synthetic base oil technology and additive chemistry advances are fragmenting traditional mineral oil dominance while regulatory enforcement intensifies around product authentication and environmental compliance.
Group III synthetic base oil technology is decomposing the historical cost advantage of mineral formulations in heavy-duty diesel applications. Fleet operators running long-haul routes between Lagos and Kano are adopting synthetic 15W-40 and 5W-30 grades to achieve 50,000-kilometer drain intervals. This shift is decomposing blender margins on commodity mineral oils while rewarding suppliers with captive synthetic base stock sourcing arrangements.
SON's lubricant labeling and quality certification mandate is tightening enforcement around counterfeit interdiction, with random port inspections and retail market surveillance expanding. Blenders must now maintain chain-of-custody documentation from base oil import through finished product dispatch. Smaller regional blenders lacking laboratory accreditation face exclusion from formal procurement channels serving multinational fleet operators.
Fleet procurement consolidation is compressing distributor tiers as large transport cooperatives negotiate direct supply agreements with major blenders. Traditional lubricant distributors in Onitsha and Aba are losing volume to integrated fuel-and-lube forecourt operators and manufacturer-direct technical service programs. This disintermediation is most visible among cement and logistics fleets operating scheduled maintenance contracts with specified fluid brands.
Nigeria Automotive Lubricants Market Segmentation
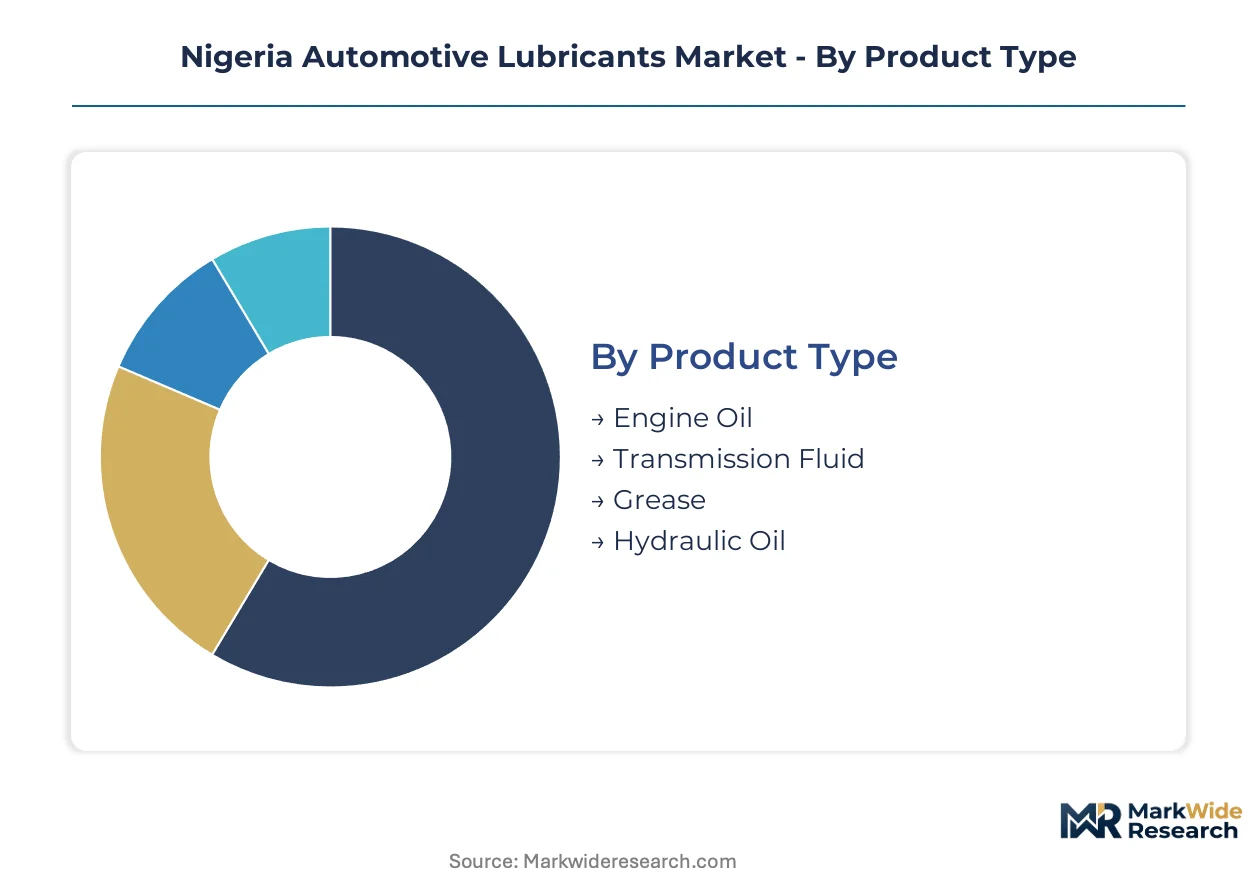
Segmentation reveals how lubricant procurement patterns diverge across vehicle classes, distribution channels, and end-user sophistication levels in Nigeria. Fleet operators, individual motorists, and industrial contractors each demand distinct viscosity grades, packaging formats, and technical support tiers. Understanding these divides exposes where blenders must configure separate formulation, pricing, and service architectures.
Product Type:
Domestic blending capacity concentrates on engine oil and hydraulic formulations serving Lagos port logistics and Niger Delta oilfield services. Export-oriented synthetic base oil formulations remain limited given import dependency on Asian and Middle Eastern supply chains.
- Engine Oil:Formulations span mineral, semi-synthetic, and full synthetic grades with API SP and ACEA C-grade certifications now mandatory under SON enforcement. Lagos fleet operators running long-haul routes to Kano prioritize 15W-40 synthetic blends achieving extended drain intervals under tropical thermal loads. This segment commands the established base.
- Transmission Fluid:Synthetic ATF formulations serve automatic gearbox penetration in Abuja and Lagos urban fleets, with specialized CVT and DCT variants emerging for premium passenger vehicle segments. The steepest expansion runs through this category.
- Grease:Lithium-complex and calcium-sulfonate thickeners protect chassis components, wheel bearings, and fifth-wheel couplings in commercial vehicle applications across South-West corridor operations.
- Hydraulic Oil:Anti-wear ISO VG 46 and 68 grades power container handling equipment at Apapa and Tin Can Island terminals, with fire-resistant formulations serving mining contractors in Plateau State.
Engine oil absorbs the majority of blender capacity investment. Transmission fluid claims the most aggressive formulation upgrade cycles as automatic vehicle penetration accelerates.
Application:
Cost tier stratification separates premium synthetic procurement by multinational fleet operators from commodity mineral oil purchases by informal motorcycle taxi operators.
- Passenger Vehicles:Urban middle-class vehicle owners in Lagos and Abuja migrate toward synthetic 5W-30 and 0W-20 grades for Japanese and Korean OEM compliance, though price sensitivity sustains mineral oil volume in secondary cities. This segment commands the established base.
- Commercial Vehicles:Haulage cooperatives and cement logistics fleets negotiate direct supply agreements with blenders for 15W-40 heavy-duty diesel engine oils, consolidating procurement around scheduled maintenance contracts. The steepest expansion runs through this category.
- Heavy-Duty Equipment:Construction and mining contractors in Rivers and Bayelsa states demand specialized hydraulic fluids, compressor oils, and gear lubricants with superior thermal stability and extended service life under continuous operation.
- Motorcycles:Okada operators and delivery fleets across Lagos, Ibadan, and Onitsha consume high-volume 20W-40 mineral formulations through informal retail channels, with limited specification awareness driving price-based purchasing.
Commercial vehicle lubricant procurement is consolidating around direct blender relationships. Motorcycle lubricant volume expands fastest but remains trapped in low-margin commodity tiers.
Distribution Channel:
Volume concentration favors wholesale and retail networks in Lagos and South-West industrial corridors, while online penetration remains nascent outside premium urban segments.
- Retail:Branded lubricant shops and service stations in Lagos, Ibadan, and Port Harcourt provide technical consultation and genuine product authentication for fleet operators wary of counterfeit infiltration. This segment commands the established base.
- Wholesalers:Distributors in Onitsha, Aba, and Kano break bulk for regional motor parks, mechanic villages, and independent garage networks across North-Central and South-East zones.
- Auto Parts Shops:Spare parts markets in Ladipo and Nnewi cluster lubricant sales with filter and consumable procurement, capturing transactional demand from independent repair technicians.
- Online:E-commerce platforms serve expatriate vehicle owners and premium segment consumers in Abuja and Lagos, with limited penetration beyond synthetic product categories requiring specification clarity.
Retail and wholesale channels anchor volume flows. Online distribution is climbing fastest from minimal base as urban consumers seek convenience and product traceability.
End User:
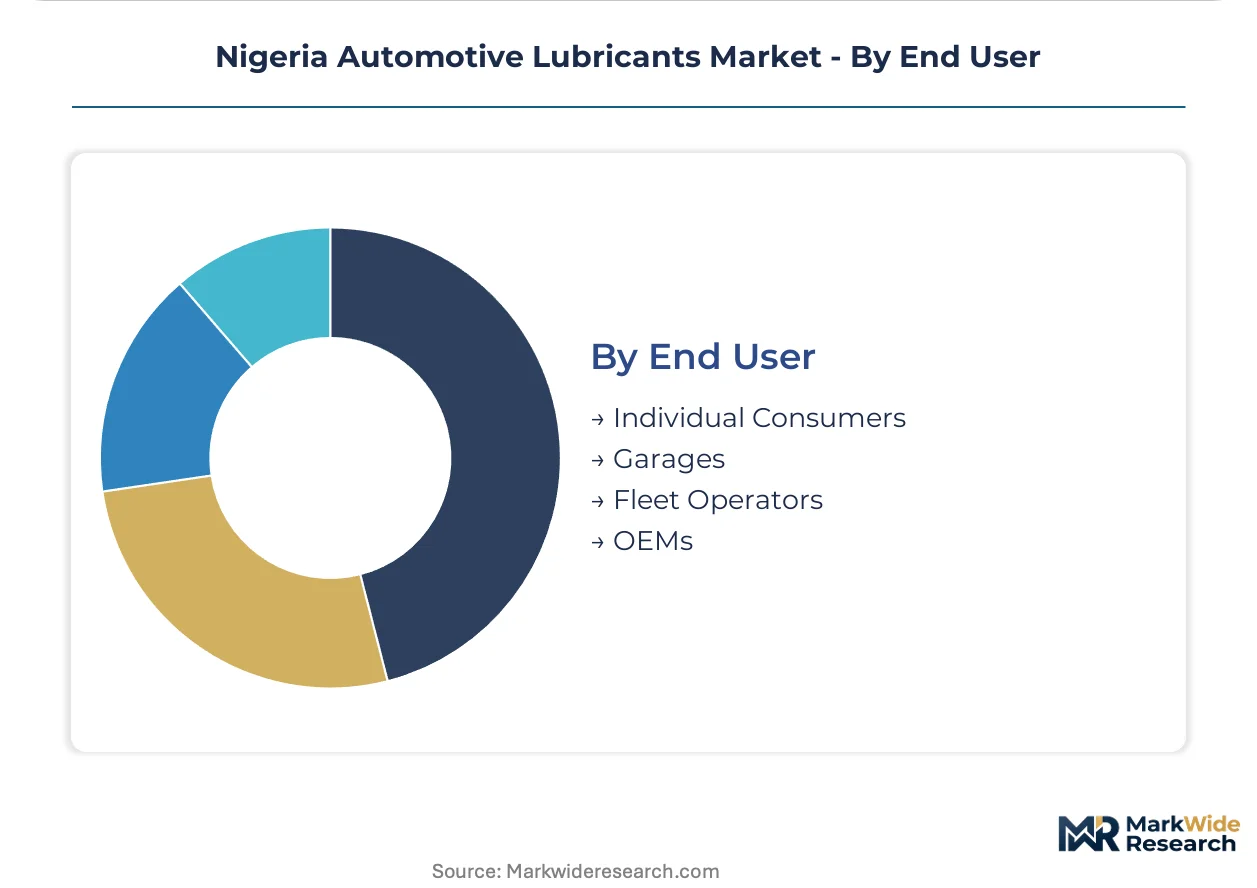
Customer type determines technical service intensity, with fleet operators demanding laboratory support and drain interval optimization while individual consumers prioritize accessibility and price.
- Fleet Operators:Transport cooperatives and logistics companies running scheduled maintenance programs specify API-certified formulations with chain-of-custody documentation, consolidating procurement through direct blender agreements or integrated fuel-and-lube forecourts. This segment commands the established base.
- Garages:Independent and OEM-affiliated workshops in Lagos and Abuja specify lubricant brands based on manufacturer warranty requirements, with technical training and bulk supply terms influencing supplier selection.
- OEMs:Vehicle assemblers and authorized dealer networks mandate proprietary lubricant specifications for warranty compliance, creating captive demand for approved supplier formulations.
- Individual Consumers:Private vehicle owners purchase through retail and auto parts channels with limited technical knowledge, exposing them to counterfeit risk and suboptimal specification matching.
Fleet operators and garages dominate procurement volume. OEM-authorized channels are gaining share fastest as vehicle financing expands formal dealership penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's lubricant trade deficit deepens as domestic blending capacity relies on imported Group II/III base oils from Asian and Middle Eastern refineries. Currency volatility and freight cost fluctuations compress blender margins while elevating landed costs for synthetic formulations. Fleet operators in Lagos and the South-West corridor absorb these premiums through consolidated procurement agreements.
Lagos and the South-West Corridor
Apapa and Tin Can Island ports generate concentrated demand for heavy-duty hydraulic and gear oil formulations serving container handling equipment. The Standards Organisation of Nigeria enforces lubricant labeling mandates through random port inspections and retail market surveillance. TotalEnergies leverages its blending facility in Apapa to sustain supply chain proximity to dense fleet operations and industrial zones.
Niger Delta Industrial Zone
Rivers and Bayelsa states present underpenetrated white space for specialized hydraulic fluid and compressor oil formulations serving mining and oilfield services. The Department of Petroleum Resources oversees petroleum product standards and environmental compliance for blending operations in this region. MRS Oil Nigeria PLC anchors its position through retail network density across Port Harcourt and Warri logistics corridors.
North-Central Transport Corridor
Haulage cooperatives running long-haul routes between Lagos and Kano prioritize 15W-40 synthetic blends achieving extended drain intervals under tropical thermal loads. SON certification requirements delay product registration for regional blenders lacking laboratory accreditation. Distributors in Onitsha and Aba break bulk for motor parks and mechanic villages across Kano and Kaduna states.
Abuja Federal Capital Territory
Urban vehicle fleets in Abuja accelerate adoption of automatic gearboxes, creating demand for synthetic ATF with extended service life. The country's national standards body mandates API-certified formulations for all commercial vehicle registrations in the capital region. OEM-affiliated workshops in the city center specify lubricant brands based on manufacturer warranty requirements for premium passenger segments.
Nigeria Automotive Lubricants Market Competitive Environment
Listed leaders compete with private specialists across formulation tiers and distribution reach. The market structure concentrates around integrated petroleum marketers with captive blending infrastructure and forecourt networks, while independent blenders survive through regional price positioning. Three archetypes dominate: multinational majors with synthetic base stock sourcing arrangements, Nigerian petroleum marketers with retail density advantages, and independent blenders serving commodity mineral oil segments. Competitive moves center on backward integration into base oil trading partnerships and forecourt integration models that capture combined diesel-and-lubricant procurement.
Within the multinational tier, TotalEnergies and BP Plc (Castrol) represent premium formulation anchors with established blending infrastructure near Lagos port traffic. Among Nigerian-listed petroleum marketers, MRS Oil Nigeria PLC and Ardova Plc exemplify integrated fuel-and-lube forecourt operators capturing commercial vehicle traffic through retail network density. These four entities occupy positions spanning synthetic certification leadership and distribution reach across the South-West and Niger Delta corridors.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| MRS Oil Nigeria PLC |
| 11 Plc |
| Eterna Plc |
| Ammasco International Limited |
| Ardova Plc |
| TotalEnergies |
| Conoil PLC |
| Oando PLC |
| Others |
Value Chain & Pricing Dynamics
Ninety-day base oil inventory cycles at Apapa blending facilities concentrate procurement leverage among three integrated petroleum marketers, compressing margin capture for independent blenders lacking captive storage infrastructure. SON certification delays extend effective lead times to one hundred twenty days for new product registrations, amplifying working capital intensity and pricing power asymmetry between accredited majors and regional challengers.
Pricing Analysis
Fleet operators anchor pricing stratification across premium, standard, and economy tiers, with synthetic 15W-40 formulations commanding three-to-four-fold premiums over mineral grades due to API SP certification requirements and extended drain interval guarantees. Price differentiation hinges on base oil Group classification and SON laboratory accreditation status, with unaccredited blenders trapped in commodity mineral segments. Cost compression in Group I formulations is intensifying because fleet procurement consolidation erodes distributor margins. Individual motorists and informal okada operators exhibit highest price sensitivity, while cement logistics cooperatives prioritize total cost of ownership over per-liter expenditure.
Supply Chain Analysis
Singapore, South Korea, and the United Arab Emirates anchor Group II and Group III base oil supply to Nigerian blenders, with no domestic production of API-certified feedstocks. Formulation chemistry draws from polyalphaolefin synthetic bases and detergent-dispersant additive packages imported through Rotterdam and Mumbai trading hubs. Single-source vulnerability concentrates in Asian refinery supply agreements, exposing blenders to freight cost volatility and currency fluctuation. Distribution runs through integrated fuel-and-lube forecourts, wholesale distributors in Onitsha and Kano, and informal retail channels serving motorcycle taxi operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement platforms are consolidating around API-certified supplier networks, creating interoperability requirements that favor blenders with integrated laboratory accreditation and direct technical service capabilities.
For Market Incumbents: Secure backward integration into base oil trading partnerships with Singapore and UAE refineries to buffer currency exposure and lock in Group III supply allocations. Defend market position by accelerating SON laboratory accreditation for regional satellite facilities, compressing product registration timelines that currently favor integrated majors with captive testing infrastructure. For New Entrants and Emerging Players: Lead with specialized hydraulic fluid formulations for mining contractors in Rivers and Bayelsa states, where multinational oilfield services demand fire-resistant ISO VG 68 grades with localized technical support. Target the Niger Delta industrial corridor through direct supply agreements with construction equipment lessors, bypassing entrenched wholesale distribution tiers in Lagos. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic base oil formulation segments as SON enforcement raises laboratory accreditation barriers to entry. Acquisition targets should exhibit captive blending infrastructure within one hundred kilometers of Apapa port traffic and established fleet maintenance contracts with cement or logistics operators. Monitor base oil import duty structure revisions as the primary inflection signal for margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Trading | Captive supply arrangements with Singapore refineries reduce currency volatility exposure for Nigerian blenders. |
| SON Laboratory Accreditation Expansion | Regional testing capacity accelerates product registration timelines and unlocks formal fleet procurement channels. |
| Forecourt Integration Model Deployment | Combined diesel-and-lubricant procurement at retail networks captures commercial vehicle traffic and reduces transaction costs. |
| Synthetic ATF Formulation Development | Automatic transmission penetration in Abuja and Lagos creates demand for extended-service-life fluid technologies. |
| Niger Delta Distribution Network Buildout | Underpenetrated mining and oilfield services in Rivers and Bayelsa states offer white space for specialized hydraulic fluids. |
Study Parameters
The analysis maps engine oil, transmission fluid, hydraulic oil, and grease sub-sectors, each validated through blending plant managers, fleet procurement officers, SON certification auditors, and aftermarket distribution partners. Primary interview data triangulates against customs import records for base oils, Department of Petroleum Resources environmental compliance filings, and Standards Organisation of Nigeria product registration databases. Bottom-up volume estimates from individual blender capacity assessments reconcile with top-down demand projections derived from vehicle parc aging curves and commercial transport activity indices.
Model outputs were validated against external benchmarks including regional petroleum product consumption surveys and base oil trade flow analyses from major Asian and Middle Eastern export terminals. Segmentation dimensions span product type, application category, distribution channel, and end-user sophistication tier, with vehicle class and OEM compliance requirements modeled as cross-cutting variables. CAGRs were derived from trend extrapolation of fleet modernization rates and synthetic formulation adoption curves, incorporating base oil import cost trajectories and SON enforcement intensity assumptions.
Forecasts assume regulatory continuity in SON certification mandates and Department of Petroleum Resources environmental standards; material policy shifts around counterfeit interdiction penalties or base oil tariff structures would require re-modeling. Specific risks include accelerated Group I base oil obsolescence, currency devaluation shocks, and laboratory accreditation bottlenecks that compress effective selling seasons. Recalibration cycles align with material shifts in fleet procurement consolidation patterns and synthetic base oil technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Speed Bump Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Automotive Electric Drivetrain Components Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Engine Oil Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Automotive Piston Engine System Market