
 Global Car Radar Detectors Market | 2026-2036
Global Car Radar Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car Radar Detectors Market Analysis
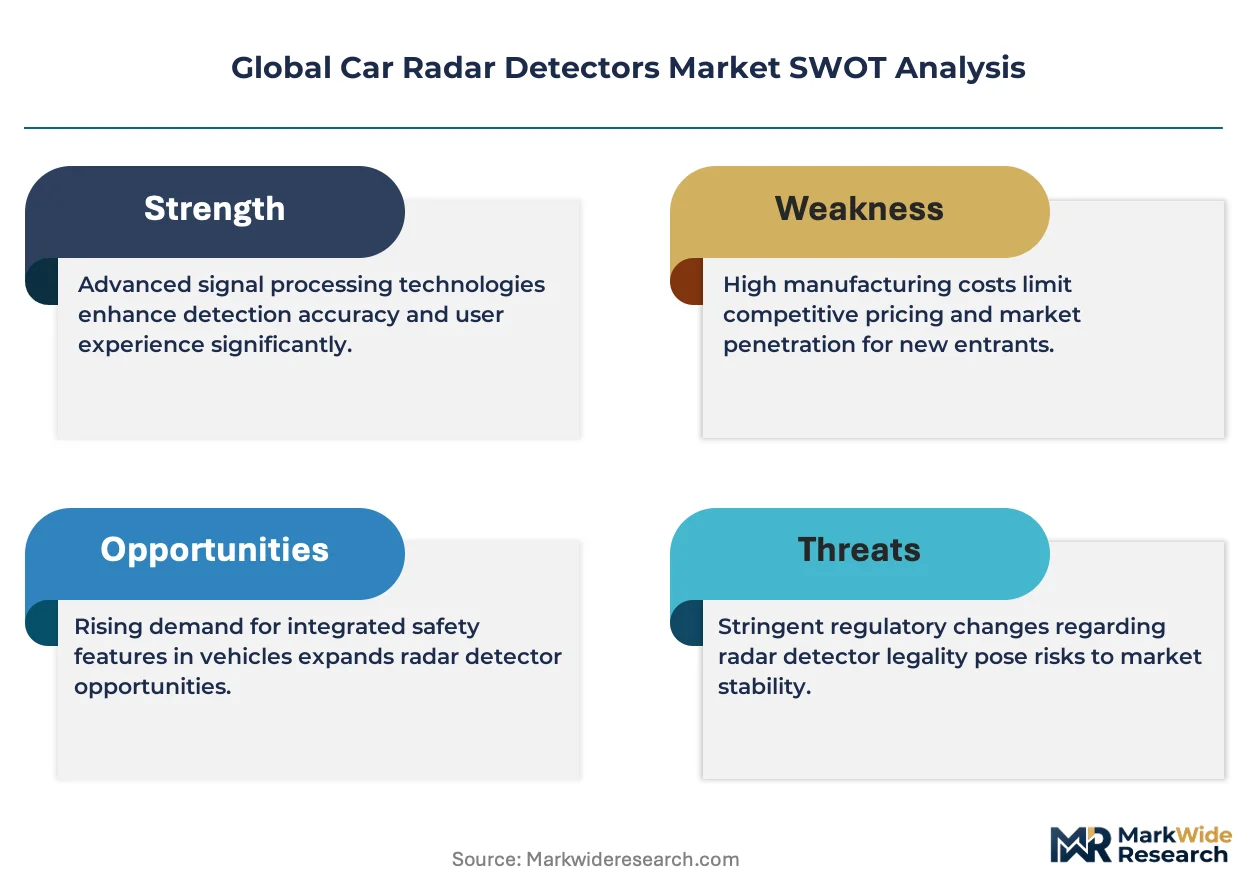
Subscription-based over-the-air feature unlocking is hardening as a revenue layer atop hardware sales in the car radar detector value chain. Aptiv PLC leverages its integrated sensor portfolio to bundle detection capabilities with advanced driver-assistance platforms. Continental AG anchors European supply through captive radar module production and OEM channel control. Denso Corporation dominates Japanese fitment rates with manufacturing scale that sustains cost positions across the Ka Band and laser detection categories.
Car radar detectors are electronic devices that sense radio frequency and laser signals emitted by traffic enforcement systems, typically operating across K Band (24 GHz), Ka Band (33-36 GHz), and X Band (10.5 GHz) frequencies with detection ranges extending from several hundred meters to over a kilometer depending on antenna configuration and signal processing architecture. Their primary commercial purpose is to alert drivers to active speed monitoring infrastructure, reducing citation risk while integrating with broader vehicle awareness systems. Portable units occupy the aftermarket entry tier where price sensitivity shapes margin pools, while built-in and integrated installations capture higher attachment rates among fleet operators seeking centralized compliance management. Laser detection technology leads growth velocity as law enforcement agencies deploy more lidar-based speed measurement across major highways.
FCC emission limits in the United States, ETSI spectrum regulations across European Union member states, and Japan's Radio Law administered by MIC constrain transmitter power and frequency allocation for radar detection devices, directly shaping product certification requirements and market access timelines. The EU AI Act introduces additional conformity obligations when detection systems interface with automated driving algorithms, while REACH compliance governs substance restrictions in printed circuit assemblies. Stakeholders must monitor evolving spectrum reallocation decisions and automotive cybersecurity mandates that will determine which detection architectures retain legal operability across major jurisdictions.
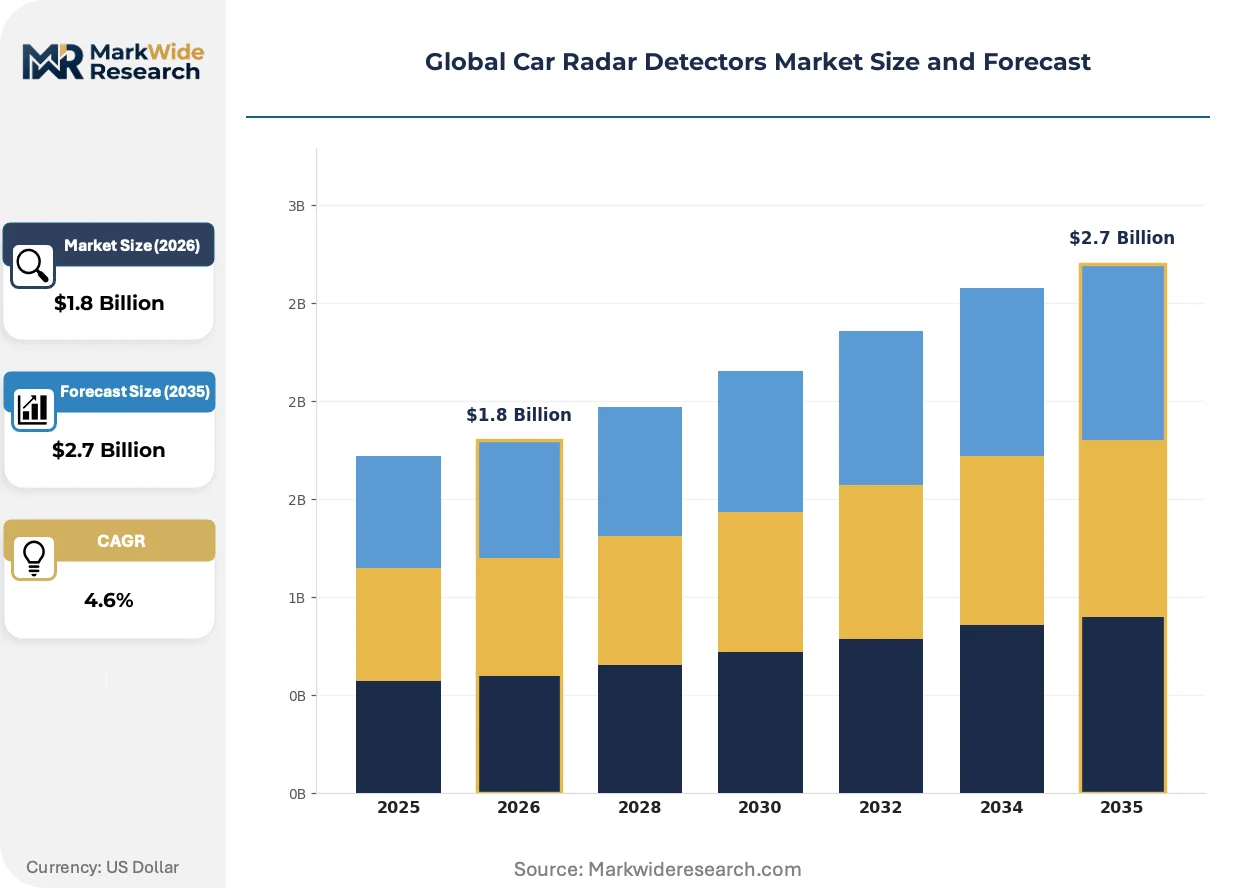
Market Dynamics
Subscription-based feature unlocking is restructuring revenue capture across hardware-centric supply chains, forcing incumbents to rebuild customer lifetime value models around recurring software monetization rather than single-transaction equipment sales.
Growth Catalysts
- Fleet operator centralization:Commercial vehicle operators in the United States are mandating built-in detection systems for unified compliance management across distributed driver pools.
- EU AI Act conformity pathways:Automated driving algorithm interfaces now require additional certification layers, creating captive demand for integrated sensor platforms that bundle detection with ADAS architectures.
- Laser detection technology maturation:Lidar-based speed measurement deployment on German and Japanese highways is accelerating replacement cycles for legacy K-band and X-band units.
Market Restraints
- Spectrum reallocation uncertainty:FCC decisions on 24 GHz band usage in the United States threaten obsolescence of existing K-band detection hardware.
- REACH substance restrictions:ECHA compliance for printed circuit assemblies raises material substitution costs across European manufacturing footprints.
- Integrated OEM lock-in:Continental AG's captive radar module production limits aftermarket access to vehicle-embedded installation channels.
Strategic Opportunities
- Underpenetrated Indian aftermarket:Highway infrastructure expansion and enforcement technology deployment create first-mover positioning for portable unit distributors.
- Automotive cybersecurity mandate convergence:ISO/SAE 21434 compliance requirements are opening integration partnerships between detection firmware developers and vehicle network security providers.
- Over-the-air subscription models:Feature unlocking via cellular connectivity is establishing recurring revenue streams atop hardware sales in Japanese and US markets.
Industry Challenges
- Multi-jurisdiction certification timelines:ETSI, FCC, and MIC approval processes for new frequency bands extend product launch windows by 12-18 months.
- RF engineering talent scarcity:Specialized antenna design and signal processing expertise concentrates among legacy defense contractors, constraining hiring pipelines for commercial detection manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car Radar Detectors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Built-in, Wireless, Laser Technology: K Band, Ka Band, Laser Detection, X Band Installation: DIY, Professional, Onboard, Integrated End User: Consumers, Fleet Operators, Law Enforcement, Commercial |
| Companies Covered | Aptiv PLC, ZF Friedrichshafen AG, Continental AG, NXP Semiconductors N.V., Infineon Technologies AG, Robert Bosch GmbH, Valeo SA, Mobileye N.V., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car Radar Detectors Market Emerging Trajectories
Detection hardware is fragmenting into interoperable subsystems that separate antenna arrays, signal processors, and user interfaces, enabling mix-and-match procurement across fleet operators and aftermarket installers.
Digital signal processing architectures are modularizing the traditional monolithic radar detector into discrete component layers. Fleet procurement teams in Germany and Japan are adopting antenna-agnostic base units that pair with third-party laser sensors. This decomposition is compressing replacement costs and accelerating technology refresh cycles across commercial vehicle segments.
ETSI spectrum harmonization directives are forcing hardware redesigns for European market access. Manufacturers must recertify transmitter power outputs across member states with divergent enforcement priorities. Ka-band equipment faces the tightest compliance windows, with producers accelerating R&D allocation toward software-defined radio platforms that adapt to regional frequency allocations.
Buying committees at US commercial fleets are consolidating vendor relationships around integrated platform providers. Discrete portable unit purchases are contracting as procurement authority shifts to fleet management departments seeking centralized device management. This concentration is visible most acutely in long-haul trucking verticals where compliance documentation requirements favor built-in installations over windshield-mounted alternatives.
Global Car Radar Detectors Market Segmentation
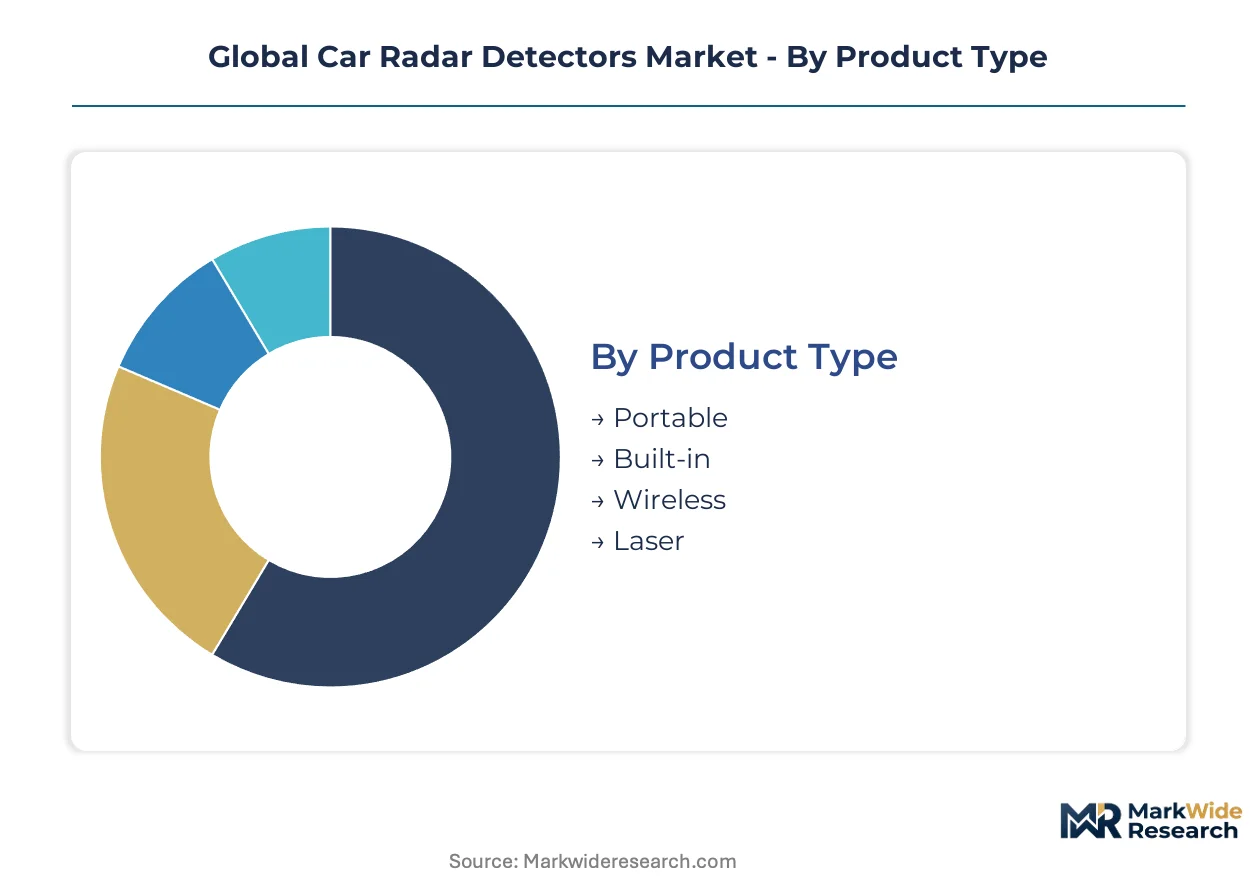
Segmentation in the car radar detector market tracks how hardware form factors, frequency technologies, and channel economics split purchasing authority across consumer retail, fleet procurement, and OEM integration pathways. Understanding these divides clarifies where pricing power concentrates and which installation modes capture recurring service revenue.
Product Type:
Integration depth separates segments that plug into vehicle power from those wired permanently into electrical architecture.
- Portable:Windshield-mounted units with 12V power adapters dominate aftermarket retail through electronics chains and online channels. Fleet operators in the United States are phasing out portable procurement in favor of centralized device management, compressing volume in long-haul trucking verticals.
- Built-in:Hardwired installations with concealed antennas and dashboard-integrated displays capture premium attachment rates among German and Japanese fleet operators seeking unified compliance documentation. This segment commands the steepest expansion trajectory as procurement authority shifts from individual drivers to fleet management departments.
- Wireless:Battery-operated or Bluetooth-connected units pair with smartphone applications for alert visualization. Japanese consumers favor these for motorcycle and rental vehicle applications where permanent installation is impractical.
- Laser:Dedicated lidar detection modules with specialized photodiode arrays address law enforcement technology upgrades on German Autobahnen and Japanese expressways. This segment climbs fastest as Ka-band and X-band hardware faces spectrum reallocation pressure.
Volume placements concentrate in Portable units through mass retail; the faster expansion belongs to Built-in systems as fleet centralization accelerates.
Technology:
Frequency allocation economics determine which detection architectures retain legal operability across FCC, ETSI, and MIC jurisdictions.
- K Band:Operating at 24 GHz, this legacy frequency faces obsolescence risk from FCC spectrum reallocation decisions in the United States. Existing hardware stocks dominate replacement demand in price-sensitive aftermarket segments.
- Ka Band:Spanning 33-36 GHz, this technology offers superior range and reduced false alerts through narrower beam detection. German and Japanese highway enforcement deployment drives fitment rates in premium built-in installations.
- Laser Detection:Photodiode-based lidar sensing responds to 904 nm wavelength emissions from speed measurement devices. This segment expands most quickly as law enforcement agencies in the United States and Germany replace radar with lidar infrastructure.
- X Band:The 10.5 GHz frequency retains niche presence in rural United States markets where older enforcement equipment persists. European ETSI harmonization has largely eliminated this technology from EU-sourced products.
Procurement volume clusters in Ka Band for new installations; Laser Detection claims the steepest growth curve as enforcement technology shifts.
Installation:
Channel control and margin capture diverge sharply between self-service retail and captive OEM supply relationships.
- DIY:Suction-cup windshield mounting and cigarette lighter power delivery characterize this consumer-accessible tier. Price compression is severe as Amazon and electronics retailers consolidate sourcing.
- Professional:Certified installer networks handle hardwired concealed installations with clean dashboard integration. German automotive electronics specialists command premium labor rates for this service layer.
- Onboard:Factory-fit detection systems installed during vehicle assembly capture the highest attachment rates among Japanese commercial vehicle operators. Denso Corporation's manufacturing scale dominates this channel.
- Integrated:Full sensor fusion with ADAS platforms requires EU AI Act conformity certification. Aptiv PLC bundles these capabilities with advanced driver-assistance architectures, creating captive demand from automated driving algorithm interfaces.
Unit economics favor Professional installation for aftermarket premium capture; Integrated systems are climbing fastest as OEM lock-in tightens.
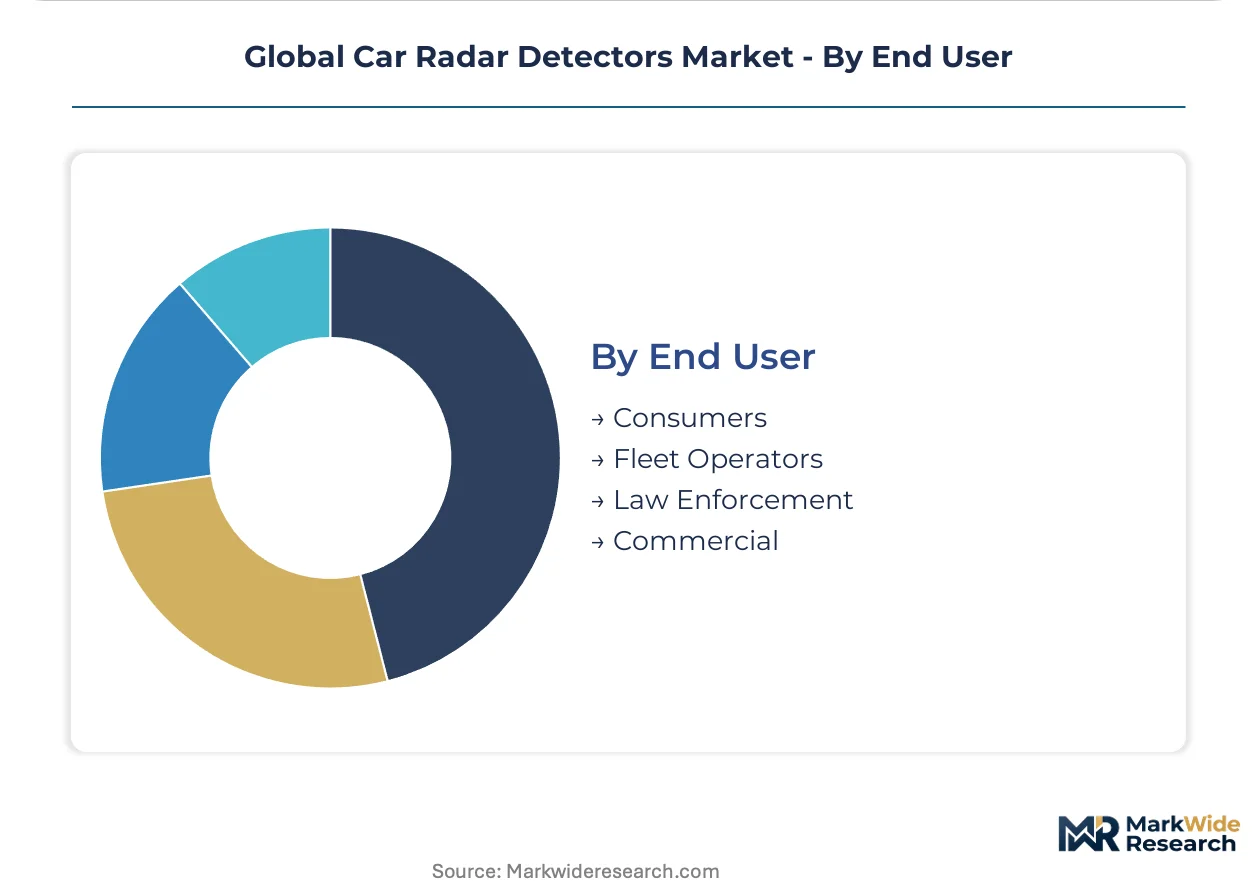
End User:
Purchasing authority fragmentation shapes whether transactions flow through retail, fleet procurement departments, or public sector tenders.
- Consumers:Individual drivers purchasing through retail channels or online marketplaces. This segment contracts in the United States as smartphone-based speed trap applications substitute for dedicated hardware.
- Fleet Operators:Commercial vehicle managers mandating built-in systems for distributed driver compliance. United States long-haul trucking fleets are consolidating vendor relationships around integrated platform providers.
- Law Enforcement:Agencies procuring detection hardware for counter-detection research or speed measurement calibration. This niche segment concentrates in German and Japanese national highway patrol budgets.
- Commercial:Ride-hail operators, delivery services, and rental fleets seeking damage mitigation through citation reduction. Indian highway infrastructure expansion is opening first-mover positioning for this user category.
Transaction volume tilts toward Consumers at retail; Fleet Operators are expanding most quickly as centralized procurement displaces driver-purchased equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of integrated radar modules consumed across European fleets, while the United States and Japan anchor aftermarket demand through distinct enforcement technology preferences. Production clusters concentrate where automotive electronics ecosystems overlap with highway infrastructure investment cycles.
United States
Long-haul trucking fleets mandate built-in detection systems for unified driver compliance documentation. FCC spectrum reallocation decisions on 24 GHz band usage threaten obsolescence of existing K-band hardware stocks. Detroit's automotive electronics corridor hosts engineering centers for fleet-integrated platform development.
Germany
Autobahn enforcement agencies deploy lidar-based speed measurement, accelerating replacement demand for laser detection modules. ETSI spectrum harmonization directives force hardware redesigns for Ka-band transmitter recertification. Stuttgart's automotive supplier cluster anchors Continental AG's captive radar module production.
Japan
Commercial vehicle operators favor factory-fit detection systems installed during assembly for centralized fleet management. METI-administered Radio Law constrains frequency allocation and transmitter power for aftermarket devices. Nagoya's manufacturing belt sustains Denso Corporation's dominance across Ka-band and laser detection categories.
India
Highway infrastructure expansion and enforcement technology deployment create first-mover positioning for portable unit distributors. BIS certification requirements for electronic devices extend product launch timelines for imported hardware. Maharashtra's industrial corridors attract aftermarket distribution networks targeting commercial vehicle segments.
South Korea
Domestic automotive OEMs integrate detection capabilities with native ADAS platforms for export markets. MFDS-equivalent spectrum regulations align with international harmonization standards for vehicle electronics. Seoul Capital Area engineering centers develop software-defined radio architectures for regional frequency adaptation.
Global Car Radar Detectors Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the car radar detector supply chain. Tier-1 automotive suppliers with captive semiconductor fabrication anchor the integrated OEM channel, while specialized detection firmware developers serve aftermarket retrofit demand. Three archetypes dominate: full-stack platform providers bundling hardware with ADAS integration; component specialists supplying antenna modules and signal processors to third-party assemblers; and subscription-based service layers monetizing over-the-air feature unlocking. Competitive moves concentrate on strategic partnerships for ISO/SAE 21434 cybersecurity compliance and geographic expansion into underpenetrated Indian aftermarket channels.
Among European-headquartered platform providers, Continental AG exemplifies the captive production archetype through in-house radar module manufacturing and OEM channel control. Aptiv PLC represents the integrated sensor portfolio approach, bundling detection capabilities with advanced driver-assistance architectures. Denso Corporation anchors the scale-driven manufacturing tier, with Japanese commercial vehicle fitment rates sustaining cost positions across frequency categories. These three entities collectively illustrate how regional production clusters and fleet procurement centralization reshape competitive positioning.
| Leading Market Players |
|---|
| Aptiv PLC |
| ZF Friedrichshafen AG |
| Continental AG |
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| Robert Bosch GmbH |
| Valeo SA |
| Mobileye N.V. |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
RF engineering talent scarcity in the United States and Germany widens pricing-tier spreads between economy-grade portable units and premium built-in systems, as specialized antenna design expertise concentrates among legacy defense contractors and commands compensation premiums that feed through to landed product costs.
Pricing Analysis
Margin tightening in the portable tier reflects Amazon-driven price compression as electronics retailers consolidate sourcing around offshore assemblers. Three-tier pricing structure across premium, standard, and economy levels separates laser-equipped built-in systems from Ka-band portables and entry-level X-band legacy units. Certification-grade differentiation—FCC Part 15 compliance versus full ETSI EN 300 440 recertification—commands 15-20 point spreads. Fleet procurement departments show lowest price sensitivity; individual consumers through online marketplaces exhibit highest.
Supply Chain Analysis
Gallium arsenide substrate supply rests on Japanese and Taiwanese specialty semiconductor producers, with photodiode arrays for laser detection drawing from German and South Korean optoelectronics specialists. Printed circuit assembly depends on China-based EMS providers for economy-tier units, while German automotive electronics clusters handle premium built-in integration. Single-source vulnerability concentrates in GaAs wafer supply. Distribution runs through OEM captive channels for integrated systems, certified installer networks for professional fitment, and mass retail e-commerce for portable tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineering talent scarcity props pricing for premium-tier detection hardware, as specialized signal processing expertise constrains capacity expansion across German and Japanese manufacturing clusters.
For Market Incumbents: Deepen backward integration into GaAs substrate supply to defend margin position against commodity photodiode cost volatility. Fortify ISO/SAE 21434 cybersecurity certification pipelines ahead of EU AI Act enforcement timelines to lock out unqualified competitors from integrated ADAS channels. For New Entrants and Emerging Players: Capture underpenetrated Indian commercial vehicle aftermarket through BIS-certified portable laser detection units targeting highway infrastructure expansion zones. Prioritize distributor partnerships with Maharashtra-based logistics operators over direct retail confrontation with established brands. For Investors and Strategic Acquirers: Re-rating potential sits with software-defined radio platform developers given FCC spectrum reallocation catalysts that will obsolete fixed-frequency hardware architectures. Watch ETSI harmonization directive timing as inflection signal for stranded asset risk in legacy K-band equipment stocks.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Development | Enables rapid frequency reconfiguration for FCC and ETSI compliance without hardware redesign. |
| ISO/SAE 21434 Cybersecurity Certification | Opens integration partnerships with Aptiv and Continental for ADAS-bound detection firmware. |
| GaAs Substrate Backward Integration | Reduces single-source dependency on Japanese specialty wafer producers for photodiode arrays. |
| Indian Distribution Network Expansion | Establishes first-mover positioning in commercial vehicle segments ahead of enforcement deployment. |
| Over-the-Air Subscription Infrastructure | Captures recurring revenue streams atop hardware sales in Japanese and US fleet markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributor operations heads, and fleet management compliance directors. FCC equipment authorization databases, ETSI harmonized standards documents, MIC Radio Law filings, and vehicle production registration statistics supplied validation triangulation. Bottom-up unit economics and top-down market sizing reconciled through iterative cross-checks.
Data-stream reconciliation across shipment volumes, installed base estimates, and replacement cycle assumptions shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product integration depth, frequency technology, installation channel, and end-user procurement authority. CAGRs derived from fitted growth curves against historical replacement patterns and enforcement technology deployment schedules. Fleet centralization rates and spectrum reallocation timelines served as key forecast inputs.
The model holds under stable regulatory enforcement technology deployment trajectories; deviation in FCC 24 GHz band reclamation timing or EU AI Act implementation severity would shift replacement demand curves. Forecasts reflect documented assumptions regarding fleet procurement centralization velocity and laser detection adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market