
 Africa and Middle East Airbag Systems Market | 2026-2036
Africa and Middle East Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Africa and Middle East Airbag Systems Market Outlook
Saudi Arabia's industrial capacity build-out for automotive component manufacturing is tilting procurement patterns across the Middle East. Autoliv Inc. leverages its regional distribution infrastructure to sustain supply continuity for major OEM assembly plants. ZF Friedrichshafen AG anchors its competitive stance through localized technical support and calibration services. Continental AG differentiates via integrated sensor-to-deployment architectures that reduce system complexity for vehicle assemblers.
Airbag systems comprise fabric cushions woven from polyamide yarns, paired with gas generators and electronic control units that deploy within milliseconds of crash detection to mitigate occupant injury. Frontal airbags dominate volume demand across the Africa and Middle East region due to baseline regulatory mandates, while side and curtain airbags represent the fastest-expanding category as Gulf safety standards tighten. Electronic technology leads the technology segment through precise multi-point crash sensing, whereas hybrid systems are gaining traction among cost-sensitive African vehicle assemblers seeking phased capability upgrades.
Saudi Standards, Metrology and Quality Organization (SASO) and the UAE's Ministry of Industry and Advanced Technology shape product certification requirements, while Egypt's Ministry of Trade and Industry administers import conformity protocols that filter non-compliant safety systems. South Africa's National Regulator for Compulsory Specifications enforces occupant protection benchmarks that influence supplier qualification across Sub-Saharan markets. Stakeholders must monitor divergent homologation timelines between Gulf harmonization initiatives and national African type-approval regimes to optimize market entry sequencing.
Market Dynamics
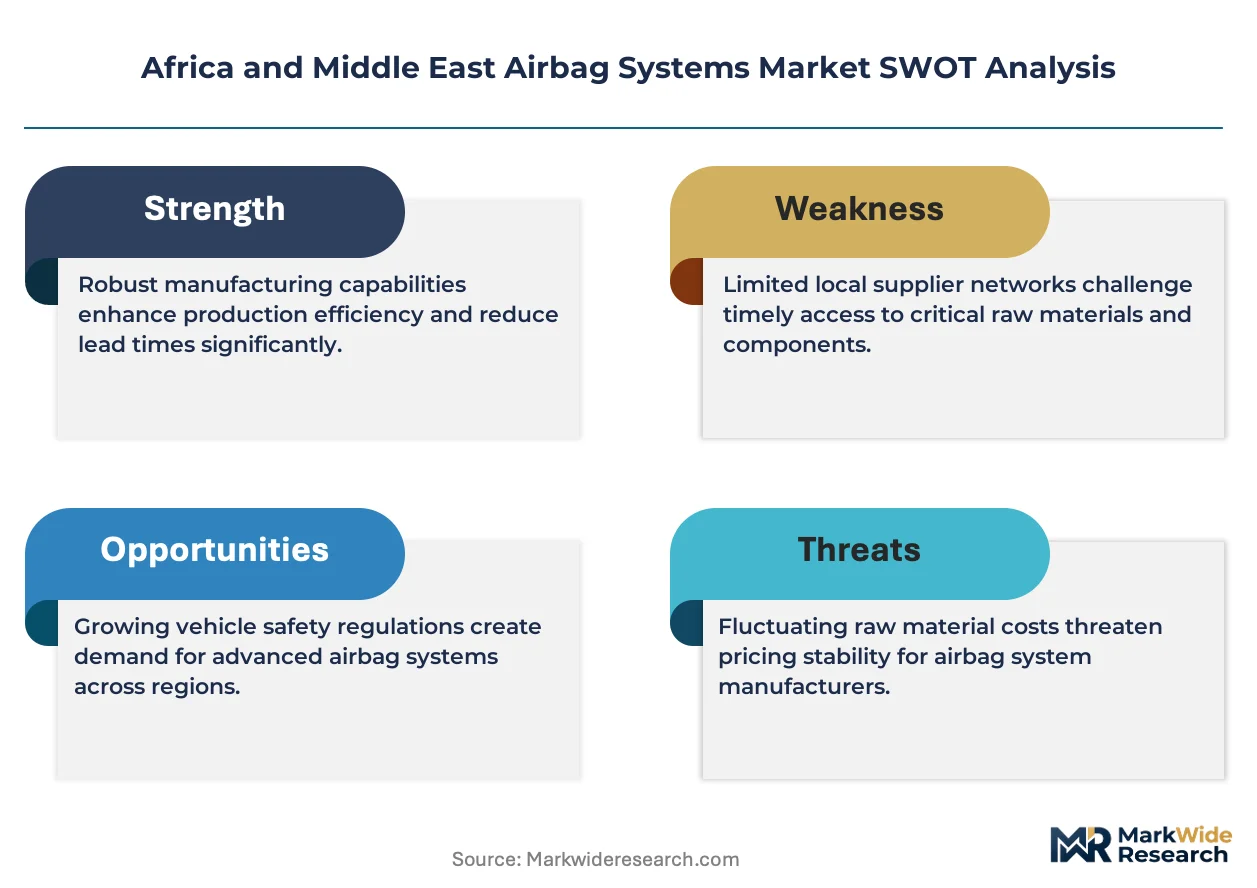
Saudi Arabia's SASO technical regulations are compressing deployment timelines for advanced occupant protection systems, forcing suppliers to accelerate sensor-to-deployment integration while simultaneously localizing production capacity within the Gulf Cooperation Council manufacturing corridor.
Growth Catalysts
- Frontal airbag mandates:Baseline regulatory requirements across Egypt, Saudi Arabia, and South Africa now require dual frontal airbag fitment in new passenger vehicles, creating standardized demand pull for OEM assembly plants.
- Side and curtain airbag adoption:Gulf safety standards are tightening occupant protection protocols, accelerating fitment rates across mid-range vehicle models previously equipped with frontal systems only.
- Polyamide yarn supply localization:Fabric cushion manufacturers are establishing weaving operations in the UAE and Saudi Arabia, reducing import dependency and compressing lead times for regional airbag module assemblers.
Market Restraints
- Gas generator input volatility:Sodium azide and alternative propellant chemical supplies face price instability due to concentrated global production in East Asian specialty chemical corridors.
- Electronic control unit supply concentration:Crash sensor and ECU fabrication remains concentrated in established East Asian and European manufacturing hubs, exposing African and Middle Eastern assemblers to extended shipping timelines and currency fluctuation risk.
- Homologation timeline divergence:Gulf harmonization initiatives under SASO and UAE Ministry of Industry protocols operate on accelerated schedules compared to Egypt's Ministry of Trade import conformity processes, creating certification friction for multi-market suppliers.
Strategic Opportunities
- Sub-Saharan aftermarket expansion:South Africa's National Regulator for Compulsory Specifications enforcement is filtering non-compliant safety systems, creating qualification barriers that favor certified suppliers in neighboring Zimbabwe, Botswana, and Namibian markets.
- Hybrid system adoption:Cost-sensitive African vehicle assemblers are pursuing phased capability upgrades through hybrid airbag architectures that combine mechanical and electronic triggering mechanisms.
- Sensor-to-deployment integration:Multi-point crash sensing convergence with single-unit deployment controllers is reducing wiring complexity and assembly labor for vehicle manufacturers in Saudi Arabia's emerging automotive cluster.
Industry Challenges
- Calibration technician scarcity:Precise sensor calibration and deployment timing verification require specialized technical skills that remain underdeveloped in regional workforce pipelines across the Middle East and North Africa.
- Legacy fleet retrofit complexity:Older vehicle architectures in African markets lack the electrical infrastructure and mounting provisions required for aftermarket airbag installation, limiting addressable volume outside factory-fit channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa and Middle East Airbag Systems Market |
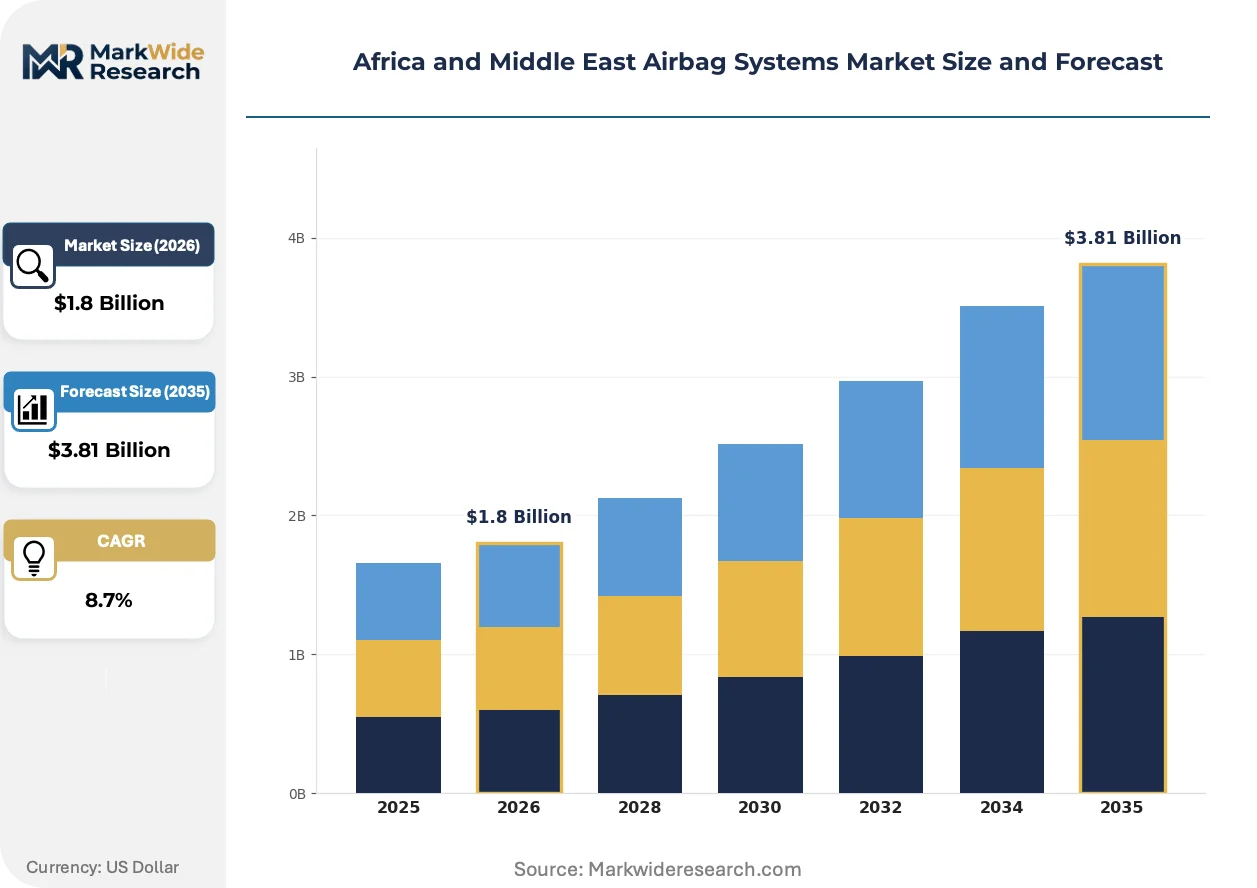
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags Technology: Mechanical, Electronic, Hybrid, Inflatable End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Manufacturers Installation: Factory Assembly, Retrofit, Custom Fit, Professional Installation |
| Companies Covered | SAMI Advanced Electronics Company, Arab Components Industries, SafeTech Automotive Systems, Emirates Automotive Technologies, Automotive Solutions, Autoliv Inc., ZF Friedrichshafen AG, Continental AG, Joyson Safety Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa and Middle East Airbag Systems Market Strategic Shifts
Crash sensing architectures are virtualizing signal processing functions, compressing hardware footprints while enabling faster deployment algorithms. Three developments are restructuring competitive capability requirements across the Africa and Middle East supply base.
Occupant classification systems are virtualizing passenger detection and weight-sensing functions through capacitive and pressure-mat technologies that replace mechanical seat sensors. Saudi Arabian OEM assembly plants are adopting these systems for 2026 model year vehicles to comply with SASO advanced protection mandates. This virtualization is enabling single-ECU architectures that consolidate frontal, side, and curtain deployment logic.
SASO's updated technical regulations for occupant protection systems now mandate multi-stage deployment capabilities and out-of-position detection for new vehicle categories entering Saudi Arabia. Industrial consequence includes forced module redesign for suppliers serving Gulf markets, with certification timelines compressed to twelve-month windows. Passenger vehicle OEMs in Riyadh and Jeddah assembly corridors are responding by pre-qualifying integrated sensor-to-deployment architectures that reduce homologation risk.
Fleet procurement for ride-hailing and corporate vehicle pools is consolidating airbag specification decisions into centralized technical committees rather than decentralized purchasing functions. Tier-1 suppliers are establishing direct technical relationships with Saudi and UAE fleet operators, bypassing traditional aftermarket distribution channels. This concentration is most visible in Dubai and Abu Dhabi, where government-backed mobility platforms are standardizing occupant protection specifications across multi-brand vehicle acquisitions.
Africa and Middle East Airbag Systems Market Segmentation
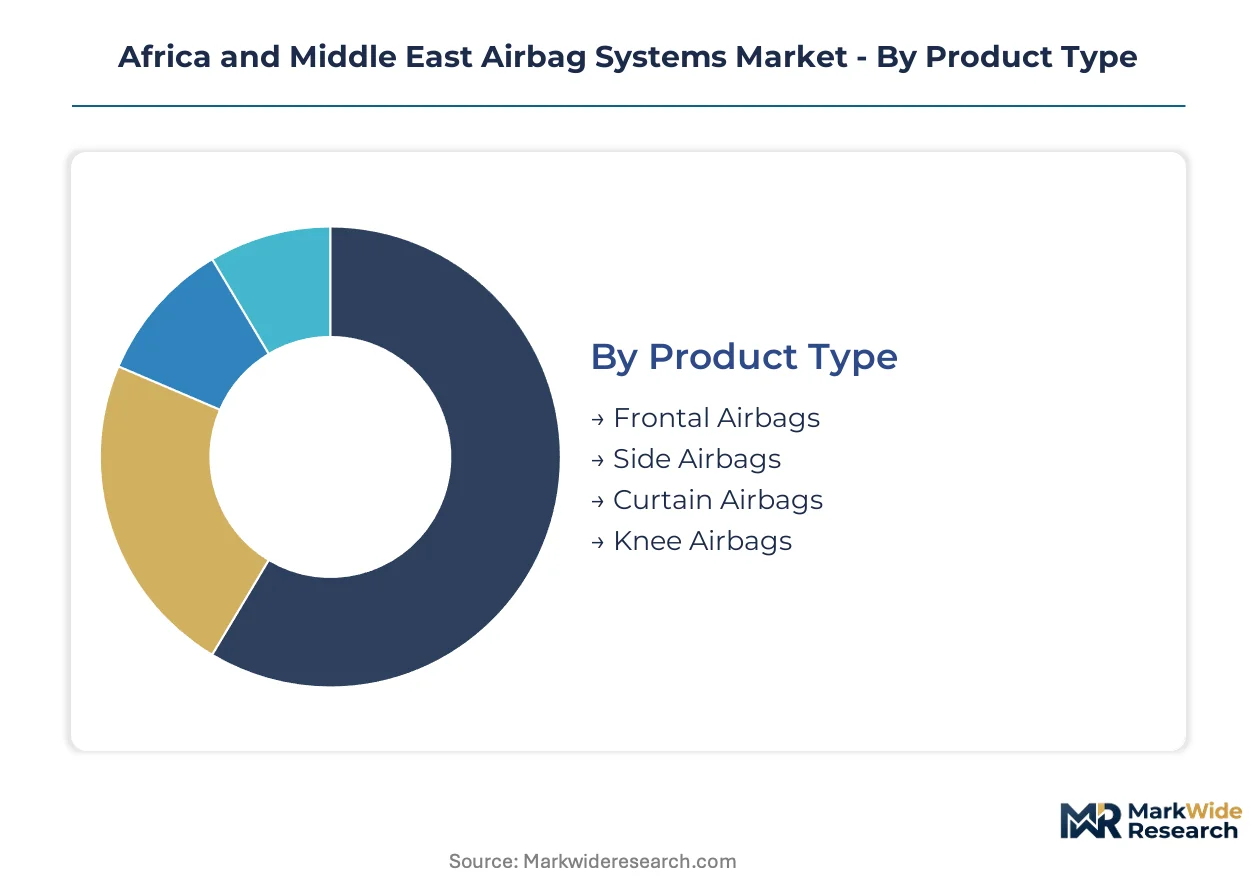
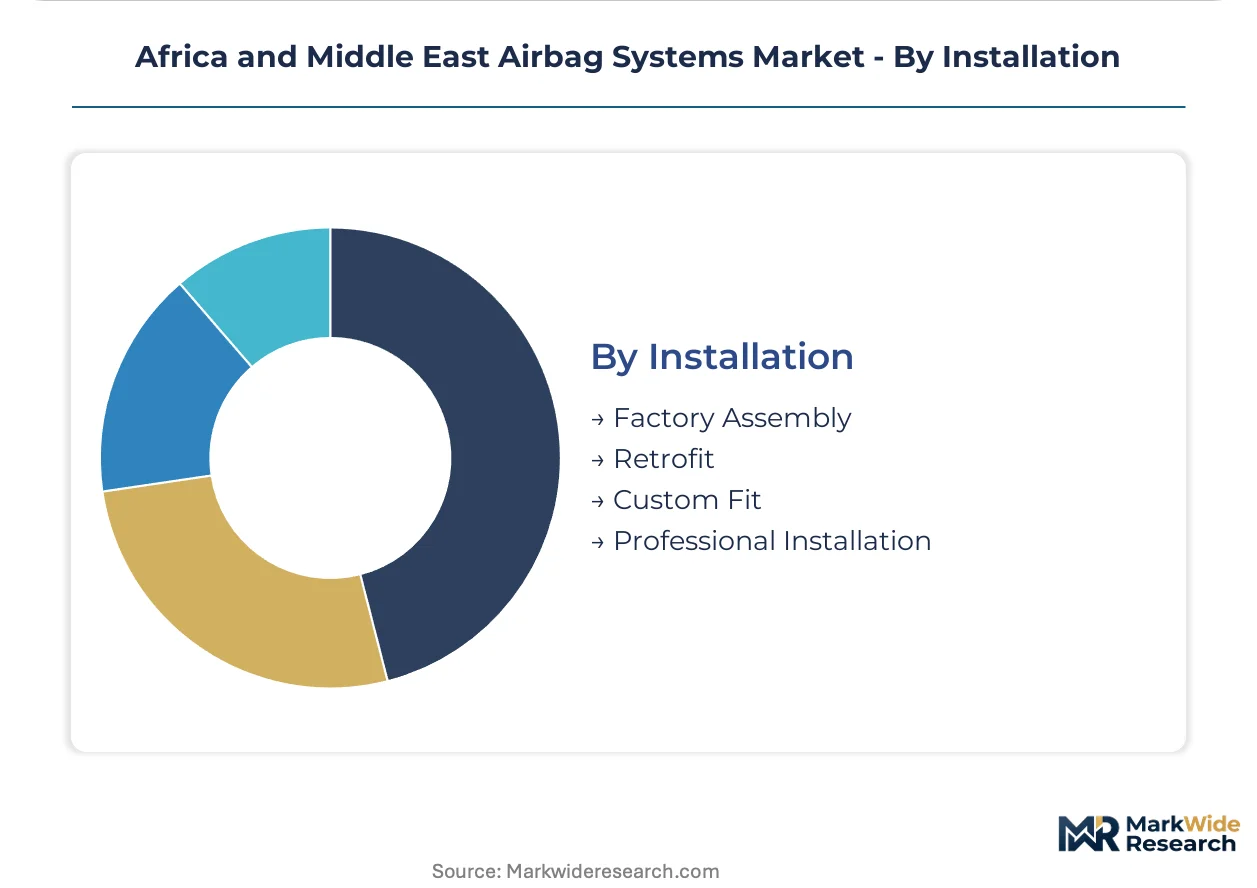
Airbag system procurement patterns across Africa and the Middle East diverge sharply by installation channel and technology sophistication. OEM assembly plants in Saudi Arabia and the UAE prioritize integrated electronic architectures, while cost-sensitive African vehicle assemblers gravitate toward phased capability upgrades.
Product Type:
Deployment location determines fabric cushion specifications, gas generator sizing, and mounting hardware requirements across regional vehicle platforms.
- Frontal Airbags:Dual-chamber cushions woven from high-tenacity polyamide 6,6 yarns deploy from steering wheel hubs and passenger-side instrument panels. Egyptian and South African OEM assembly plants standardize these systems across entry and mid-range passenger vehicles to satisfy baseline regulatory mandates.
- Curtain Airbags:Roof-rail mounted systems extend protection across side window apertures during rollover events. Gulf Cooperation Council safety standard tightening is accelerating fitment rates in Saudi Arabian and UAE-manufactured vehicles previously equipped with frontal systems only.
- Side Airbags:Seat-mounted or door-mounted modules protect thorax and pelvic regions in side-impact collisions.
- Knee Airbags:Lower dashboard deployment modules mitigate femur and patella injuries in frontal crashes.
The dominant share belongs to Frontal Airbags, while Curtain Airbags is closing the gap fastest.
Technology:
Cost tier and calibration complexity segment supplier qualification requirements across the regional manufacturing base.
- Electronic:Multi-point crash sensors feed deployment algorithms through centralized control units with millisecond response latency. Saudi Arabian OEM plants are pre-qualifying these architectures to satisfy SASO advanced occupant protection mandates for multi-stage deployment and out-of-position detection.
- Hybrid:Combined mechanical triggering with electronic sensing enables phased capability upgrades for African vehicle assemblers facing capital constraints. Zimbabwean and Namibian aftermarket channels favor these systems for their reduced calibration technician dependency.
- Mechanical:Ball-and-spring or mercury-switch triggers activate gas generators without electronic infrastructure.
- Inflatable:External airbag prototypes and pedestrian protection systems represent emerging deployment categories.
Electronic systems command the premium tier, though Hybrid configurations are expanding most quickly among cost-constrained assemblers.
End User:
Procurement concentration varies by channel control and technical specification authority.
- OEMs:Original equipment manufacturers in Riyadh and Jeddah assembly corridors consolidate airbag specification decisions through centralized technical committees. Direct supplier relationships with Autoliv, ZF, and Continental bypass traditional distribution tiers.
- Vehicle Assemblers:Contract manufacturing operations across Egypt and Morocco source modules through qualified Tier-1 distributors with localized technical support capabilities.
- Aftermarket Providers:South Africa's National Regulator for Compulsory Specifications enforcement is filtering non-compliant safety systems, creating qualification barriers that favor certified suppliers in neighboring markets.
- Manufacturers:Component fabricators and module integrators serve both captive OEM demand and open-market supply.
OEMs dominate procurement volume, while Aftermarket Providers are gaining share fastest through regulatory compliance filtering.
Installation:
Channel economics and technical feasibility separate factory-fit from post-assembly opportunities.
- Factory Assembly:Line-integrated module installation at Saudi Arabian and UAE OEM plants ensures sensor calibration precision and wiring harness integration. SASO certification timelines favor suppliers with established regional distribution infrastructure.
- Professional Installation:Authorized service centers in Dubai and Abu Dhabi handle fleet retrofit programs for government-backed mobility platforms standardizing occupant protection specifications.
- Retrofit:Aftermarket installation faces electrical infrastructure and mounting provision limitations in older African vehicle architectures.
- Custom Fit:Specialized applications for armored vehicles and modified commercial platforms require bespoke cushion geometries and deployment timing.
Factory Assembly captures the dominant share, though Professional Installation is climbing the fastest through fleet procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO technical regulations in Saudi Arabia are compressing deployment timelines for advanced occupant protection systems across the Gulf Cooperation Council manufacturing corridor. Procurement patterns now favor suppliers with localized production capacity and established regional distribution infrastructure.
Saudi Arabia
Passenger vehicle OEMs in Riyadh and Jeddah assembly corridors are expanding airbag fitment across mid-range models to satisfy SASO mandates for multi-stage deployment and out-of-position detection. The Saudi Standards, Metrology and Quality Organization updated technical regulations now require advanced occupant protection systems for new vehicle categories entering the market. Industrial capacity build-out in the Eastern Province is tilting procurement patterns toward suppliers with in-country module integration capabilities.
United Arab Emirates
The Ministry of Industry and Advanced Technology shapes product certification requirements that accelerate homologation timelines relative to other Middle Eastern markets. Dubai and Abu Dhabi serve as the primary logistics nodes for airbag module distribution across the GCC automotive manufacturing corridor. Fleet procurement for government-backed mobility platforms is consolidating airbag specification decisions into centralized technical committees in these emirates.
Egypt
Baseline regulatory mandates from the Ministry of Trade and Industry now require dual frontal airbag fitment in new passenger vehicles, creating standardized demand pull for OEM assembly plants in Cairo and Alexandria. Import conformity protocols filter non-compliant safety systems, extending certification timelines compared to Gulf harmonization initiatives. Contract manufacturing operations source modules through qualified Tier-1 distributors with localized technical support capabilities.
South Africa
The National Regulator for Compulsory Specifications enforces occupant protection benchmarks that influence supplier qualification across Sub-Saharan markets. Pretoria and Johannesburg anchor aftermarket channels where regulatory compliance filtering favors certified suppliers in neighboring Zimbabwe, Botswana, and Namibian markets. Enforcement actions are creating qualification barriers that redirect procurement toward pre-certified module providers.
Morocco
Vehicle assemblers in Casablanca and Tangier-Med industrial zones pursue phased capability upgrades through hybrid airbag architectures that combine mechanical and electronic triggering mechanisms. The country's automotive sector development strategy attracts module integrators seeking access to African markets with reduced tariff exposure. Technical workforce development programs address calibration technician scarcity that constrains deployment precision in regional assembly operations.
Africa and Middle East Airbag Systems Market Competitive Environment
Integrated-system specialists and regional fabricators split the market between premium electronic architectures and cost-optimized hybrid configurations. Three strategic archetypes define competitive positioning: multinational module integrators with Gulf distribution infrastructure, regional component manufacturers leveraging polyamide yarn supply localization, and aftermarket distributors navigating South Africa's compliance filtering regime. Consolidation pressure favors suppliers with captive sensor-to-deployment integration capabilities and established SASO certification track records.
Among multinational module integrators, Autoliv Inc., ZF Friedrichshafen AG, and Continental AG occupy positions that exemplify distinct competitive vectors. Autoliv represents the scale-driven archetype with regional distribution infrastructure sustaining supply continuity for major OEM assembly plants. ZF anchors its stance through localized technical support and calibration services that address workforce skill gaps. Continental exemplifies integrated-architecture positioning via sensor-to-deployment systems that reduce wiring complexity for vehicle manufacturers in Saudi Arabia's emerging automotive cluster.
| Leading Market Players |
|---|
| SAMI Advanced Electronics Company |
| Arab Components Industries |
| SafeTech Automotive Systems |
| Emirates Automotive Technologies |
| Automotive Solutions |
| Autoliv Inc. |
| ZF Friedrichshafen AG |
| Continental AG |
| Joyson Safety Systems |
| Others |
Value Chain & Pricing Dynamics
Sodium azide propellant price volatility and concentrated East Asian specialty chemical production determine both three-tier pricing spreads across premium electronic, standard hybrid, and economy mechanical systems and the elongated supply chain configurations that expose African and Middle Eastern assemblers to currency fluctuation risk.
Pricing Analysis
Price spreads between Gulf Cooperation Council markets and Sub-Saharan African markets exceed those within either region due to SASO certification premiums and logistics cost differentials. Three-tier pricing structure across premium electronic, standard hybrid, and economy mechanical levels separates OEM assembly plants in Saudi Arabia from cost-sensitive vehicle assemblers in Egypt and Morocco. Pricing pressure stems from polyamide yarn supply localization in the UAE and Saudi Arabia compressing import-dependent tiers. Fleet procurement consolidation in Dubai and Abu Dhabi exhibits lowest price sensitivity, while aftermarket channels in Zimbabwe and Namibia face acute cost constraints.
Supply Chain Analysis
Export control regimes governing crash sensor and electronic control unit fabrication limit technology flows from established East Asian and European manufacturing hubs to regional assembly operations. Component supply centers on Japan, South Korea, and Germany for precision sensors, while China and India anchor polyamide yarn and fabric cushion weaving. Raw material dependencies span sodium azide and alternative propellant chemicals, high-tenacity polyamide 6,6 yarns, and multi-layer sensor substrates. Single-source vulnerability concentrates in ECU fabrication, where limited qualified suppliers extend shipping timelines. Distribution runs through Dubai and Jeddah logistics nodes serving GCC manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Occupant classification system virtualization and single-ECU consolidation threaten standalone module suppliers with disintermediation, forcing incumbents to defend through integrated-architecture positioning.
For Market Incumbents: Build certification moats around SASO multi-stage deployment and out-of-position detection mandates to lock out unqualified competitors. Accelerate backward integration into polyamide yarn weaving within Saudi Arabia's Eastern Province to compress lead times and defend margin position against regional fabricators. Pre-qualify sensor-to-deployment architectures with Riyadh and Jeddah OEM technical committees to reduce homologation friction. For New Entrants and Emerging Players: Mid-range vehicle models in Egypt and Morocco previously equipped with frontal systems only represent the most penetrable entry point for side and curtain airbag expansion. Hybrid system configurations for Zimbabwean and Namibian aftermarket channels bypass calibration technician scarcity constraints. Direct technical relationships with government-backed mobility platforms in Dubai and Abu Dhabi bypass traditional distribution tiers. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors integrated-system specialists with captive sensor-to-deployment capabilities. Long-term viability hinges on qualification track records across divergent Gulf and African homologation regimes. Acquisition targets should demonstrate established SASO certification histories and localized production infrastructure. Watch for SASO timeline acceleration or Egyptian import conformity protocol harmonization as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Deployment Integration | Single-ECU architectures reduce wiring complexity for Saudi Arabian OEM assembly plants. |
| Polyamide Yarn Supply Localization | UAE and Saudi Arabia weaving operations compress lead times for regional module assemblers. |
| SASO Certification Pre-Qualification | Twelve-month certification windows favor suppliers with established regional track records. |
| Hybrid System Capability Buildout | Combined mechanical-electronic architectures address cost constraints in African markets. |
| Fleet Procurement Direct Relationships | Centralized technical committees in Dubai and Abu Dhabi consolidate specification authority. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and calibration technicians and refined through secondary validation against vehicle production databases, SASO technical regulation filings, customs and trade flow records, and IHS Markit registration data. Bottom-up module demand estimates triangulated against top-down vehicle production forecasts across the analysis window.
Demand-supply balance modeling anchored volume projections across product type, technology tier, end user channel, and installation mode segmentation dimensions. CAGRs derived from fitted growth curves calibrated to regulatory mandate implementation schedules and fleet procurement consolidation patterns. Industry-specific inputs included SASO compliance timeline acceleration rates and polyamide yarn supply localization progress indicators.
Practitioners should monitor SASO technical regulation expansion scope, Egyptian import conformity protocol harmonization progress, and sodium azide propellant price volatility for early signals of forecast deviation. Material shifts in Gulf-African homologation timeline convergence or East Asian ECU supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Stolen Vehicle Tracking System Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Biometric in the Automotive Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market