
 Lane Change Assist Systems Market | 2026-2036
Lane Change Assist Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lane Change Assist Systems Market Analytics
Subscription-based hardware leasing for advanced driver-assistance sensors is tilting competitive dynamics toward firms with asset-light balance sheets. Robert Bosch GmbH leverages its captive semiconductor foundry partnerships to sustain margin control across radar module production. Continental AG anchors European OEM supply relationships through integrated sensor fusion platforms that bundle lane change assist with adaptive cruise control. Denso Corporation dominates Japanese keiretsu supply chains, positioning its camera-based systems as factory-standard fitments for Toyota and Lexus nameplates.
Lane change assist systems comprise sensor arrays, processing units, and haptic or visual driver alert mechanisms that detect adjacent-vehicle proximity and trajectory conflicts during merging maneuvers; radar-based configurations operate at 77 GHz with detection ranges exceeding 70 meters, while camera-based alternatives process 30-frame-per-second video feeds through embedded neural accelerators to classify lane markings and vehicle boundaries. Radar-based systems currently lead unit shipments owing to all-weather reliability and established Tier-1 manufacturing scale, though camera-based systems represent the fastest-expanding segment as automakers pursue sensor-minimalist architectures for cost-sensitive vehicle classes. Factory installations command the dominant value share given OEM liability preferences and calibration precision requirements, yet aftermarket retrofit solutions are capturing incremental growth among aging fleet operators seeking compliance with evolving safety inspection protocols.
NHTSA's proposed automatic emergency braking mandate and Euro NCAP's lane support protocol revisions are compelling North American and European manufacturers to pre-certify lane change assist as baseline equipment. China's MIIT GB standards for intelligent connected vehicles and Japan's METI roadmap for automated driving level classifications further harmonize product specifications across export-oriented suppliers. Stakeholders must monitor regulatory divergence between camera-acceptable and radar-mandatory jurisdictions when allocating sensor platform development budgets.
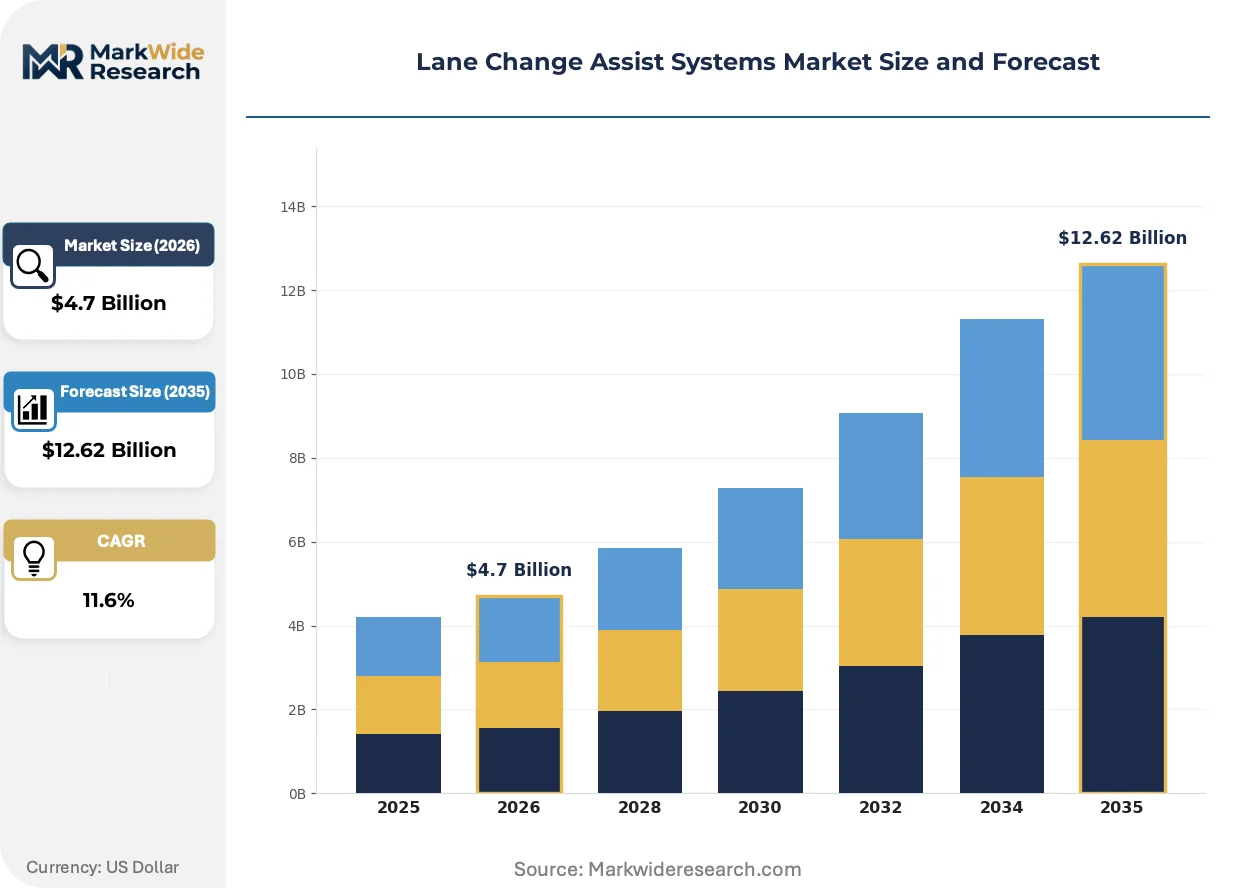
Market Dynamics
Euro NCAP's lane support protocol revisions are compelling OEMs to pre-certify lane change assist as baseline equipment ahead of 2026 model year deadlines, compressing supplier development cycles and accelerating factory-fit penetration rates across European nameplates.
Growth Catalysts
- Euro NCAP Safety Mandates:Stricter active safety ratings for new passenger vehicles in Germany are accelerating procurement timelines among premium manufacturers seeking five-star certifications.
- Sensor-Minimalist Architectures:Camera-based systems processing neural-accelerated video feeds are displacing radar configurations in cost-sensitive electric vehicle classes.
- Eastern China Demand Concentration:NIO, BYD, and Xpeng integrate lane change assist as standard equipment across their electric lineups, creating sustained volume anchors for component suppliers.
Market Restraints
- Semiconductor Supply Concentration:Captive foundry partnerships at Robert Bosch GmbH and select Tier-1 suppliers create allocation bottlenecks for radar module manufacturers without backward integration.
- Calibration Precision Requirements:Factory installations demand specialized alignment equipment and technician certification that aftermarket retrofit channels struggle to replicate at scale.
- Radar-Camera Regulatory Divergence:Jurisdictions with radar-mandatory specifications versus camera-acceptable alternatives fragment platform development budgets and delay homologation timelines.
Strategic Opportunities
- Aging Fleet Retrofit Demand:Commercial operators in North America seeking compliance with evolving safety inspection protocols represent an underpenetrated channel for aftermarket solutions.
- Subscription Hardware Leasing:Asset-light balance sheet structures enable sensor-as-a-service models that reduce upfront capital barriers for mid-tier fleet operators.
- Sensor Fusion Integration:Bundled platforms combining lane change assist with adaptive cruise control create stickier OEM relationships and expand per-vehicle content value.
Industry Challenges
- Neural Accelerator Talent Scarcity:Embedded vision processing expertise remains concentrated among semiconductor firms and select Tier-1 engineering centers, constraining camera-based system development velocity.
- Multi-Jurisdiction Homologation:Simultaneous certification against NHTSA protocols, Euro NCAP protocols, and China's MIIT GB standards extends validation timelines and inflates regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lane Change Assist Systems Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor-Based Systems, Camera-Based Systems, Radar-Based Systems, Lidar-Based Systems End User: Passenger Vehicles, Commercial Vehicles, Fleet Operators, Automotive Manufacturers Technology: Artificial Intelligence, Machine Learning, Internet of Things, Embedded Systems Installation Type: Aftermarket Installations, Factory Installations, Integrated Systems, Retrofit Solutions |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Valeo SA, Mobileye, ZF Friedrichshafen AG, Magna International, Delphi Technologies, Hitachi Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lane Change Assist Systems Market Evolving Landscape
Lane change assist technology is bifurcating into radar-dominant premium architectures and camera-centric cost-optimized configurations, with neural processing capabilities determining competitive positioning across both paths.
Sensor fusion platforms are collapsing discrete lane change assist and adaptive cruise control modules into unified processing units with shared radar and camera inputs. Continental AG and integrated Tier-1 suppliers are adopting these consolidated architectures for 2026 European nameplate programs. The compression of separate electronic control units into single-domain controllers is reducing wiring harness complexity and assembly labor content per vehicle.
NHTSA's proposed automatic emergency braking mandate is cascading into lane change assist pre-certification requirements across North American OEM supply chains. The rulemaking compresses supplier validation timelines and forces baseline feature inclusion even on entry-trim configurations. Light truck and SUV segments face disproportionate compliance cost absorption given their higher center-of-gravity handling characteristics.
Fleet procurement departments are unbundling sensor hardware from long-term maintenance contracts and negotiating direct relationships with Tier-1 suppliers. Large commercial operators in the United States are bypassing traditional dealer channels for lane change assist retrofits and sourcing calibration-equipped installation networks. This channel disintermediation concentrates buying power among asset-heavy logistics companies and squeezes margin capture at distribution intermediaries.
Lane Change Assist Systems Market Segmentation
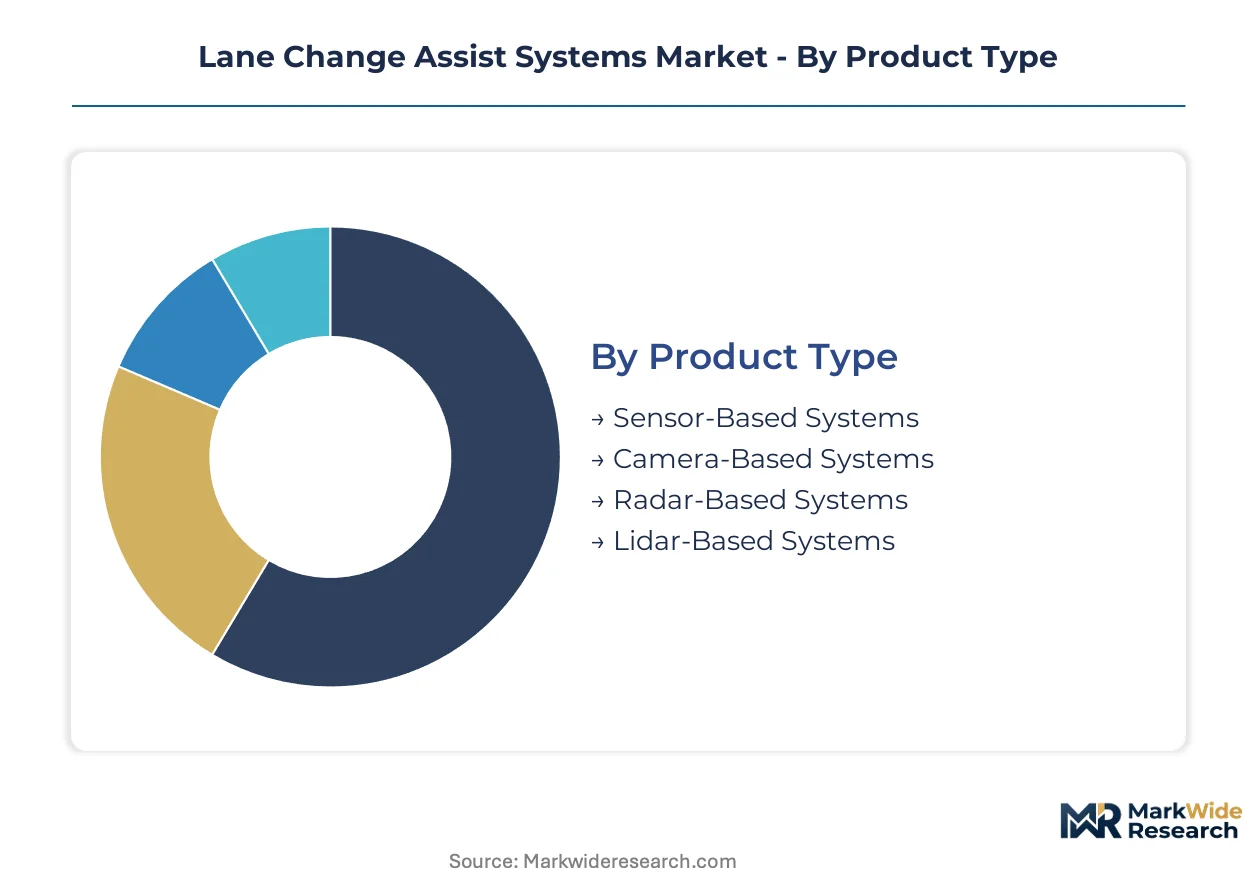
Lane change assist systems fragment across sensor modalities, customer procurement models, and integration depths that reshape competitive positioning. Each segmentation axis reveals distinct margin profiles and technical barriers that determine supplier viability across vehicle classes.
Product Type:
Use-case spectrum spans all-weather reliability demands through cost-optimized vision architectures.
- Radar-Based Systems:Operating at 77 GHz with detection ranges exceeding 70 meters, these configurations leverage established Tier-1 manufacturing scale and semiconductor foundry partnerships. Demand concentrates in German premium passenger vehicles where Euro NCAP mandates accelerate factory-fit procurement for five-star safety ratings.
- Camera-Based Systems:Processing 30-frame-per-second video feeds through embedded neural accelerators, these architectures enable sensor-minimalist designs for cost-sensitive electric vehicle classes. BYD, NIO, and Xpeng in China's eastern coastal provinces anchor volume expansion as standard equipment integration climbs across their lineups.
- Sensor-Based Systems:Multi-modal arrays combining radar, camera, and ultrasonic inputs for redundancy-critical applications in heavy commercial transport.
- Lidar-Based Systems:Emerging configurations targeting Level 3+ automated driving corridors with centimeter-precision ranging requirements.
The dominant share belongs to radar-based systems, while camera-based systems are closing the gap fastest.
End User:
Procurement authority concentrates differently across fleet-scale negotiations and captive OEM supply chains.
- Automotive Manufacturers:Captive engineering teams specify sensor fusion platforms that bundle lane change assist with adaptive cruise control, creating sticky Tier-1 relationships. Continental AG anchors European supply through integrated domain controllers that compress separate electronic control units.
- Passenger Vehicles:Factory installations command preference due to calibration precision requirements and liability exposure management, with premium nameplates in Germany leading specification intensity.
- Fleet Operators:Large commercial logistics companies in the United States are disintermediating dealer channels to negotiate direct Tier-1 relationships for retrofit procurement.
- Commercial Vehicles:Light truck and SUV segments face disproportionate compliance cost absorption given higher center-of-gravity handling characteristics under NHTSA protocols.
Automotive manufacturers capture the dominant value share, though fleet operators are gaining procurement leverage fastest.
Technology:
Processing architecture choices determine competitive moats across embedded vision and connected vehicle stacks.
- Embedded Systems:Real-time deterministic processing with hard latency constraints for safety-critical trajectory calculations in radar-dominant configurations.
- Artificial Intelligence:Neural network inference engines for multi-object tracking and lane marking classification under varying illumination conditions.
- Machine Learning:Continuous model refinement through fleet telemetry aggregation, constrained by data governance fragmentation across jurisdictions.
- Internet of Things:V2X communication layers enabling cooperative lane change coordination, currently limited by infrastructure deployment density.
Embedded systems retain the dominant installation base, while artificial intelligence is climbing the fastest.
Installation Type:
Channel economics diverge sharply between precision-calibrated factory workflows and aftermarket accessibility constraints.
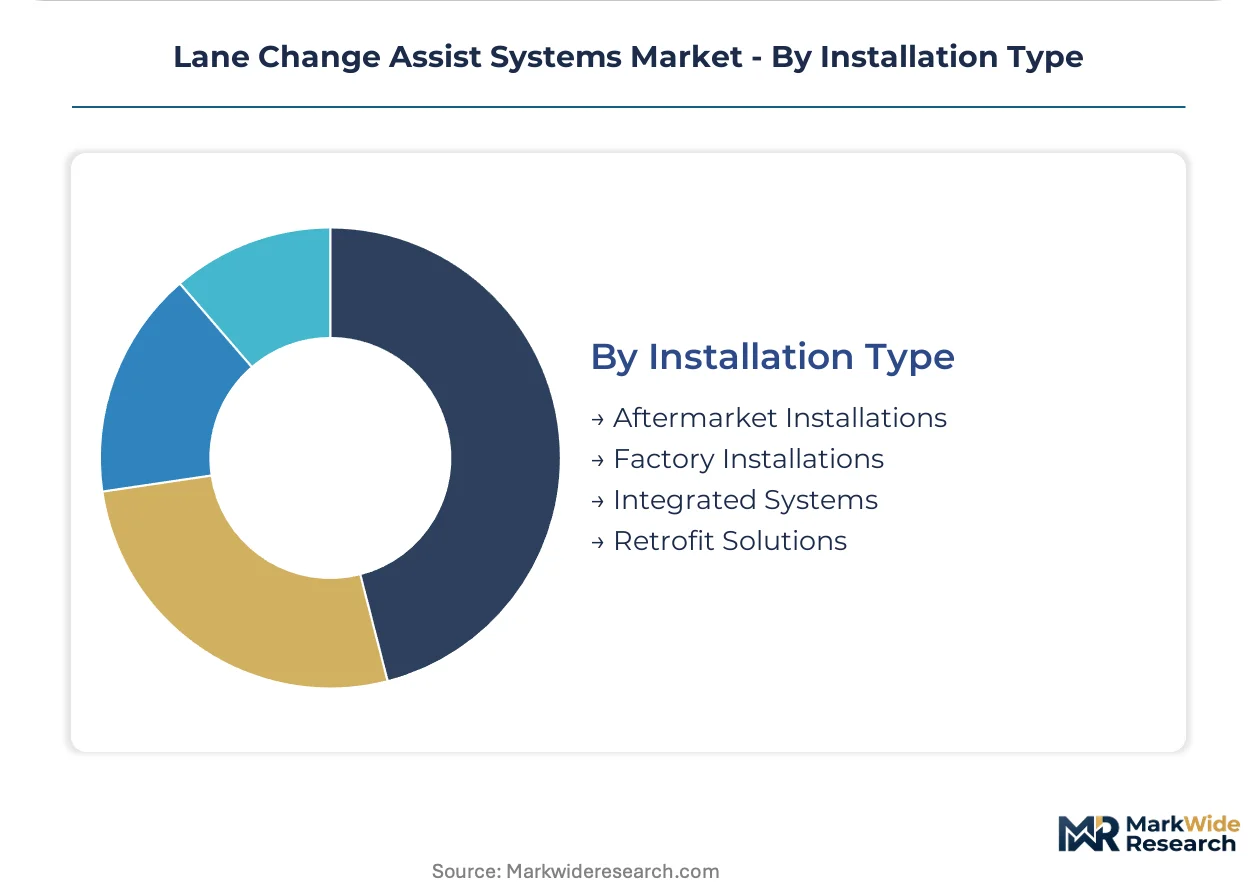
- Factory Installations:Specialized alignment equipment and technician certification ensure calibration precision that OEM liability frameworks demand, with wiring harness integration optimized during vehicle assembly.
- Integrated Systems:Domain controller consolidation collapsing discrete modules into unified processing units with shared sensor inputs, reducing assembly labor content per vehicle.
- Aftermarket Installations:Aging fleet operators in North America seeking compliance with evolving safety inspection protocols represent incremental growth, though calibration replication remains challenging at scale.
- Retrofit Solutions:Subscription-based hardware leasing models reducing upfront capital barriers for mid-tier fleet operators through asset-light balance sheet structures.
Factory installations hold the dominant share, while integrated systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented suppliers in Germany and China currently dominate component shipments, while import dependency for specialized semiconductors shapes procurement strategies across emerging manufacturing hubs.
Germany
Premium passenger vehicle manufacturers in Baden-Württemberg and Bavaria are accelerating procurement timelines to secure Euro NCAP five-star certifications ahead of 2026 model year deadlines. KBA homologation requirements for active safety systems compress supplier development cycles. Stuttgart's automotive engineering cluster anchors radar module integration programs for Mercedes-Benz and Porsche nameplates.
China
NIO, BYD, and Xpeng integrate lane change assist as standard equipment across electric vehicle lineups, concentrating demand in eastern coastal provinces. MIIT GB standards for intelligent connected vehicles harmonize product specifications for export-oriented suppliers. Shanghai's Yangtze River Delta manufacturing corridor hosts sensor fusion platform assembly for domestic and overseas markets.
United States
NHTSA's proposed automatic emergency braking mandate cascades into lane change assist pre-certification requirements across Detroit Three supply chains. Light truck and SUV segments face disproportionate compliance cost absorption under evolving protocols. Michigan's automotive R&D corridor validates multi-jurisdiction homologation timelines for North American deployment.
Japan
METI's automated driving level classification roadmap guides keiretsu supply chain specifications for camera-based system integration. Toyota and Lexus nameplates specify factory-standard fitments through captive supplier relationships. Nagoya's Chubu manufacturing region processes embedded neural accelerators for real-time trajectory calculations.
South Korea
Hyundai Motor Group and Kia Corporation specify lane change assist across mass-market electric vehicle platforms, driving sensor procurement volume. MFDS alignment with international automotive safety standards facilitates component export certification. Seoul Capital Area engineering centers develop sensor-minimalist architectures for cost-sensitive vehicle classes.
Lane Change Assist Systems Market Competitive Landscape
On the supply side, the industry is tiered between integrated domain controller specialists, captive semiconductor fabricators, and modular component suppliers. Tier-1 automotive suppliers with backward integration into radar module production occupy premium positioning, while camera-centric specialists compete on sensor-minimalist architectures. Consolidation pressures favor firms with asset-light balance sheets capable of subscription hardware leasing models. Dominant competitive moves include strategic partnerships for semiconductor allocation and geographic expansion through integrated sensor fusion platforms.
Within the integrated systems tier, Robert Bosch GmbH and Continental AG exemplify European engineering-heavy positioning, while Denso Corporation anchors Japanese keiretsu supply relationships. These three firms represent contrasting archetypes: the German pair leverage domain controller consolidation and OEM bundling strategies, whereas the Japanese supplier occupies a position defined by factory-standard fitment depth with domestic automakers. Each exemplifies how captive manufacturing relationships or foundry partnerships determine margin control in radar-dominant versus camera-centric technology paths.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Valeo SA |
| Mobileye |
| ZF Friedrichshafen AG |
| Magna International |
| Delphi Technologies |
| Hitachi Ltd |
| Others |
Value Network & Pricing Analysis
Semiconductor foundry capacity concentration in Taiwan and South Korea funnels margin capture toward Tier-1 suppliers with captive allocation agreements, while downstream OEMs absorb calibration and integration cost premiums. Radar module manufacturers without backward integration face persistent margin compression as wafer starts prioritize integrated domain controller specialists.
Pricing Analysis
Automotive OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on Euro NCAP certification grade and volume procurement scale, with five-star pre-certified systems commanding substantial premiums over baseline compliance configurations. Pricing pressure stems from sensor-minimalist architectures displacing radar-dominant designs in cost-sensitive electric vehicle classes. Fleet operators exhibit highest price sensitivity due to retrofit capital constraints, while German premium manufacturers demonstrate lowest sensitivity given liability-driven specification intensity.
Supply Chain Analysis
77 GHz radar chipsets, embedded neural accelerators, and automotive-grade image sensors feed from concentrated upstream capacity in Taiwan, South Korea, and Germany. Raw material dependencies center on silicon carbide substrates, specialized CMOS processes, and rare-earth magnet components for motor-actuated mirror assemblies. Single-source vulnerability around EUV lithography capacity at TSMC creates allocation risk for advanced processing nodes. Distribution runs through captive Tier-1 OEM supply chains with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lane change assist systems constitute a defensive-moat market where regulatory entrenchment creates substantial switching costs for OEMs once platform certifications are secured. Euro NCAP and NHTSA protocol alignment investments lock in supplier relationships across multiple model generations.
For Market Incumbents: Build sensor fusion integration depth as the primary moat against modular component suppliers. Deepen backward integration into radar semiconductor fabrication to defend allocation priority during foundry constraint periods. Pre-certify integrated domain controllers against evolving MIIT GB standards in China to capture NIO, BYD, and Xpeng volume expansion. Threat of camera-centric minimalist architectures from South Korean engineering centers demands accelerated neural accelerator talent retention. For New Entrants and Emerging Players: Aftermarket retrofit networks for aging North American commercial fleets represent the most penetrable entry point given dealer channel disintermediation trends. Subscription-based hardware leasing models for mid-tier logistics operators bypass upfront capital barriers that constrain incumbent transactional pricing. Direct Tier-1 relationships with fleet procurement departments offer faster volume accumulation than OEM qualification timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists possessing Euro NCAP pre-certification libraries but limited geographic diversification. Five-to-ten year viability hinges on sensor fusion platform consolidation rather than discrete module positioning. Acquisition target archetype: integrated domain controller developers with established foundry partnerships and Asian OEM relationships. Signal to watch: NHTSA final rule publication timing for automatic emergency braking mandate cascade effects.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Consolidation | Continental AG and Robert Bosch GmbH compress separate ECUs into unified domain controllers reducing wiring complexity. |
| Foundry Partnership Securement | Captive semiconductor allocation agreements at TSMC and Samsung sustain margin control during capacity constraint periods. |
| Multi-Jurisdiction Homologation Investment | Simultaneous Euro NCAP, NHTSA, and MIIT GB certification accelerates OEM platform adoption across export markets. |
| Neural Accelerator Talent Acquisition | Embedded vision processing expertise concentration at Mobileye and select Tier-1 centers constrains camera-based development velocity. |
| Fleet Channel Disintermediation | Direct Tier-1 relationships with U.S. commercial logistics operators bypass traditional dealer networks and concentrate buying power. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier production schedules anchors the qualitative findings. Primary interviews with automotive electronics procurement directors, sensor fusion architects, regulatory affairs specialists, and fleet maintenance operators combine with secondary validation from vehicle production databases, IHS Markit registration data, Euro NCAP test protocols, and SEC automotive segment filings. Bottom-up unit shipment modeling triangulates against top-down OEM platform content analysis.
Calibration against historical adoption curves for comparable active safety systems informs the projection framework across the analysis window. Segmentation dimensions span sensor modality, vehicle propulsion architecture, content per vehicle tier, OEM premium-mass positioning, and regional regulatory cluster. CAGRs derive from fitted diffusion models incorporating Euro NCAP mandate phase-in schedules and electric vehicle platform ramp timelines. Neural processing capability roadmaps and foundry capacity expansion announcements constitute key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor capital expenditure cycles, or lithium-ion battery cost trajectories would shift the trajectory. Forecasts reflect documented assumptions around regulatory implementation timing and OEM platform consolidation patterns. Cross-checking against NHTSA rulemaking dockets and KBA homologation publication schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Adaptive Headlights Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Global Automotive Backup Camera Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Global Automotive Radar Sensors Market