
 Ski Conveyor Lift Market | 2026-2036
Ski Conveyor Lift Market Size, Share, and Industry Trends Forecast 2026-2036
Ski Conveyor Lift Market Insights
Resort procurement channels is rewriting how conveyor lift manufacturers access mountain property owners. Sunkid leverages its Austrian manufacturing base to sustain long-term supply contracts with Alpine destination operators. Magic Carpet Lifts dominates the North American installer network, while Forbo Movement Systems anchors conveyor belt supply through its engineered polymer divisions.
A ski conveyor lift is a surface-mounted, continuous-loop transportation device that moves skiers and snowboarders up gentle slopes using a rubber or composite belt driven by an electric motor, typically operating at speeds under 1.5 meters per second to ensure passenger safety. Belt conveyor configurations lead product type demand due to their quieter operation and lower snow clearance requirements compared to roller alternatives. Motorized drive technology occupies the largest installed base, though electric drive systems are gaining share as resorts phase out hydraulic units to reduce fluid contamination risks. Application demand clusters around resort transport and ski training, where high passenger throughput justifies capital investment over rope tow alternatives.
The EU Machinery Directive and CE marking framework govern installation safety and operator liability across European ski areas, while OSHA standards shape workplace exposure limits for lift maintenance crews in United States operations. Health Canada and provincial regulators enforce comparable mechanical integrity rules at Canadian mountain resorts. Stakeholders must monitor evolving energy efficiency mandates and electrification subsidies, as these will determine replacement timing for legacy drive systems and influence vendor selection criteria across major ski destinations.
Market Dynamics
Mountain resorts across the Alpine corridor are modernizing surface lift infrastructure to capture family tourism segments, while the EU Machinery Directive tightens safety specifications and CE marking requirements reshape vendor qualification criteria.
Growth Catalysts
- EU Machinery Directive compliance mandates:Alpine destination operators must replace aging conveyor systems to meet updated CE marking requirements, accelerating replacement cycles for legacy installations in Austria and Switzerland.
- Electric drive technology:Resorts are phasing out hydraulic drive units to eliminate fluid contamination risks, creating pull-through demand for belt conveyor configurations with quieter operation profiles.
- Beginner terrain expansion:Family tourism segmentation strategies at Austrian and Swiss mountain properties prioritize conveyor lift density over rope tow alternatives to reduce learning-curve friction for first-time skiers.
Market Restraints
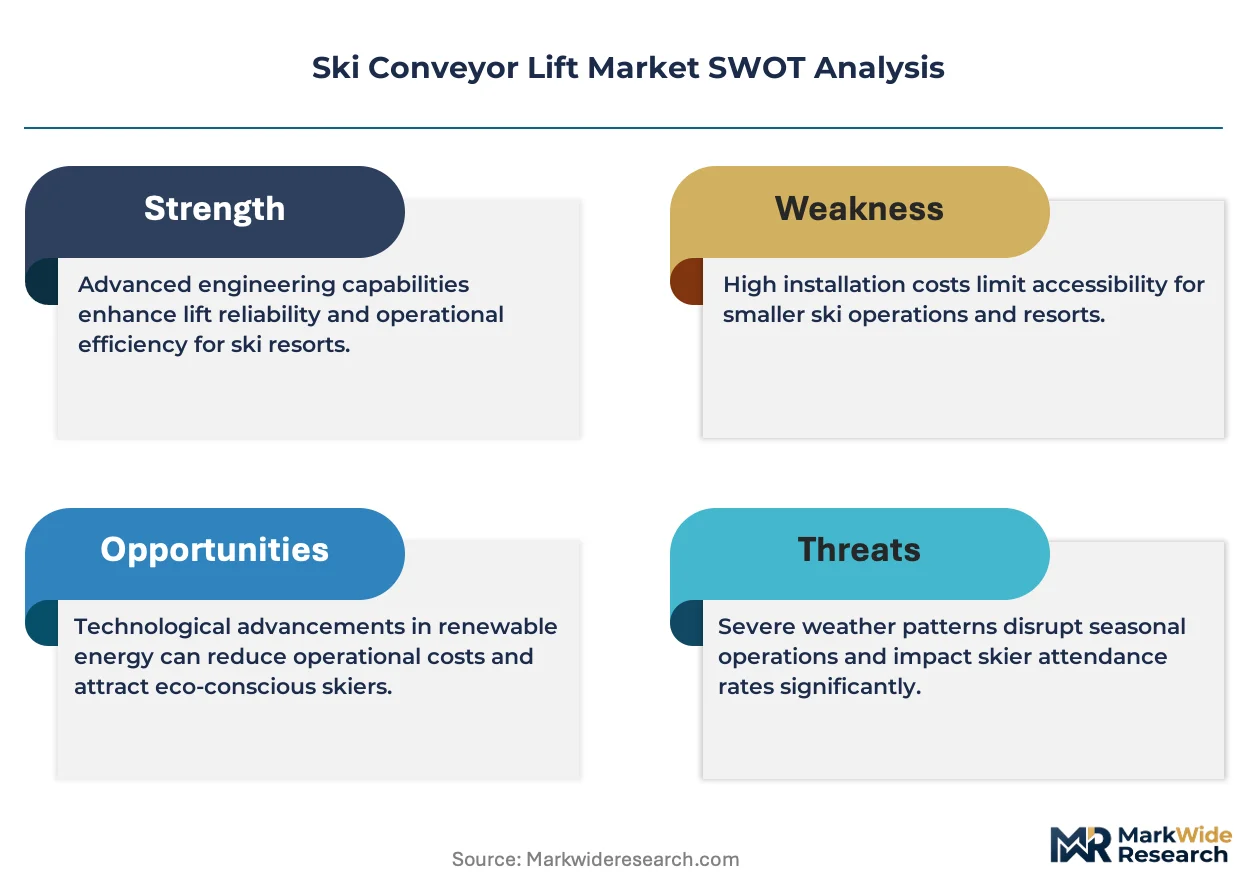
- Specialized polymer belt costs:Engineered composite belt materials face input cost volatility from petroleum-derived feedstocks, compressing margins for conveyor system fabricators.
- Alpine manufacturing concentration:Production gravity centers on Austrian and German component suppliers, exposing procurement channels to regional supply disruptions and extended lead times.
- Roller conveyor substitution:Lower-capital rope tow systems retain cost advantage at smaller ski training facilities, limiting addressable market expansion in price-sensitive segments.
Strategic Opportunities
- North American installer network gaps:Canadian mountain resorts outside Quebec and British Columbia show underpenetrated conveyor lift density relative to Alpine benchmarks, presenting white-space expansion potential.
- OSHA workplace exposure alignment:United States ski areas face mounting pressure to reduce maintenance crew injury rates, creating tailwinds for automated drive systems with remote monitoring capabilities.
- Photovoltaic-battery hybrid drives:Convergence of solar generation and lithium-ion storage technology enables off-grid conveyor installations at remote terrain parks previously uneconomical to electrify.
Industry Challenges
- Certification timeline compression:CE marking documentation requirements for modified drive systems extend approval cycles, delaying revenue recognition for system integrators serving European resorts.
- Legacy hydraulic integration:Resorts with mixed fleet infrastructure face operational complexity managing spare parts inventories across obsolete and current drive technologies.
- Snow clearance automation:Belt conveyor configurations require precise snow removal protocols, demanding specialized maintenance skill sets in short supply at seasonal mountain operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ski Conveyor Lift Market |
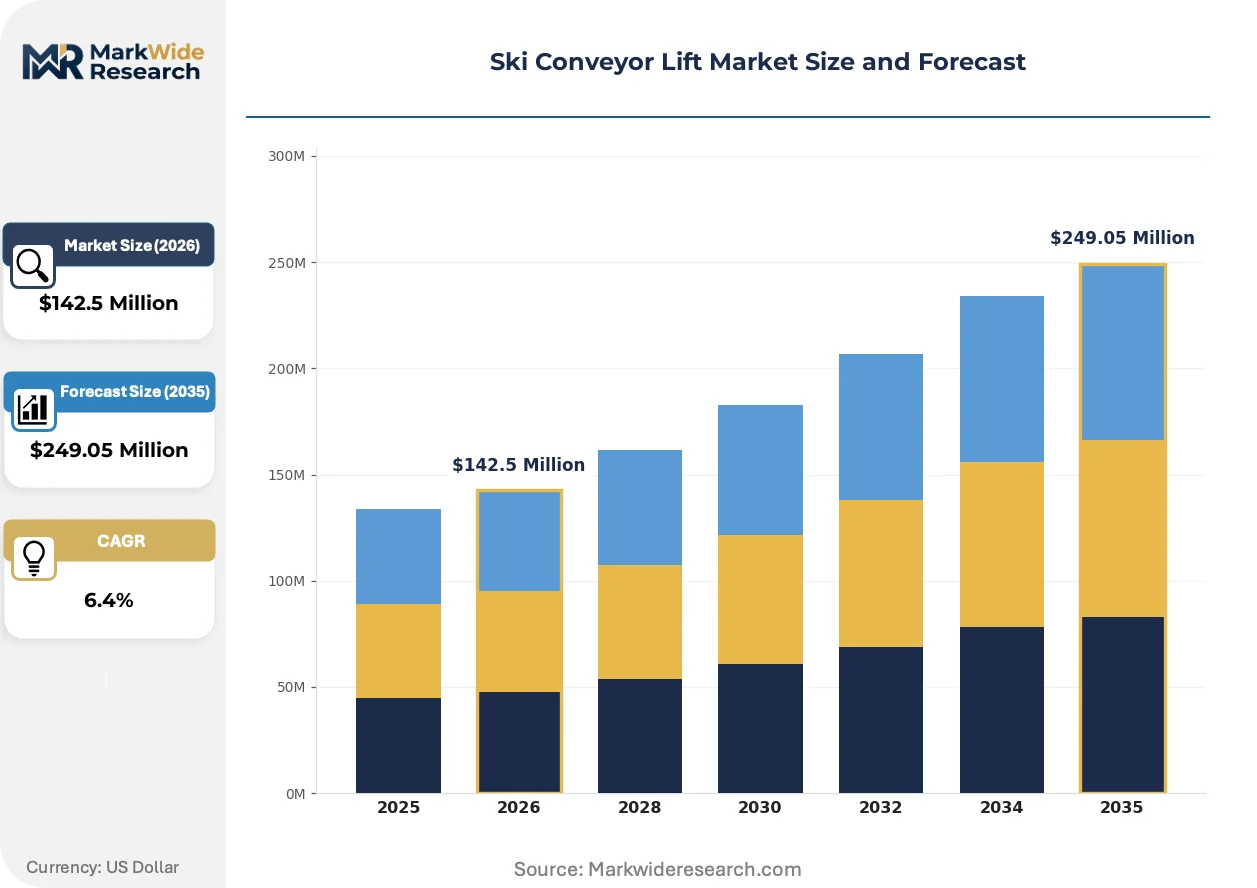
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Conveyor, Roller Conveyor, Chain Conveyor, Modular Conveyor, Portable Conveyor Technology: Motorized Drive, Gravity Operated, Pneumatic Drive, Hydraulic Drive, Electric Drive Application: Resort Transport, Ski Training, Snowboard Assistance, Equipment Loading, Terrain Park Access End User: Mountain Resorts, Ski Schools, Winter Sports Centers, Recreational Parks, Adventure Facilities |
| Companies Covered | Sunkid, Magic Carpet Lifts, Forbo Movement Systems, Esbelt, AMMERAAL BELTECH, SNOWMAX, MEB IMPIANTI, MND Group, Star Lifts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ski Conveyor Lift Market Trends and Innovations
Digital monitoring systems are virtualizing maintenance protocols across conveyor lift fleets, while regulatory pressure on energy efficiency and evolving procurement patterns reshape how mountain properties evaluate capital equipment.
Predictive maintenance platforms using vibration sensors and thermal imaging are virtualizing traditional scheduled service intervals. Alpine destination operators in Switzerland and Austria deploy these systems to reduce unplanned downtime during peak season. The technology is virtualizing labor allocation models, allowing smaller technical crews to monitor distributed lift networks from centralized control rooms.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration and ancillary mountain resort equipment, indirectly pressuring conveyor lift vendors to demonstrate supply chain decarbonization. Component suppliers must document embodied carbon in steel framing and polymer belts to maintain preferred vendor status. Belt conveyor manufacturers serving Austrian state-owned ski areas face procurement preference shifts toward suppliers with verified Scope 3 emissions disclosures.
Resort procurement departments are consolidating vendor relationships around full-lifecycle service agreements rather than transactional equipment purchases. North American mountain operators increasingly bundle conveyor lift installation with multi-year maintenance contracts. This pattern is most visible at Colorado and Utah destination resorts, where capital planning committees prioritize total cost of ownership metrics over upfront capital expenditure minimization.
Ski Conveyor Lift Market Segmentation
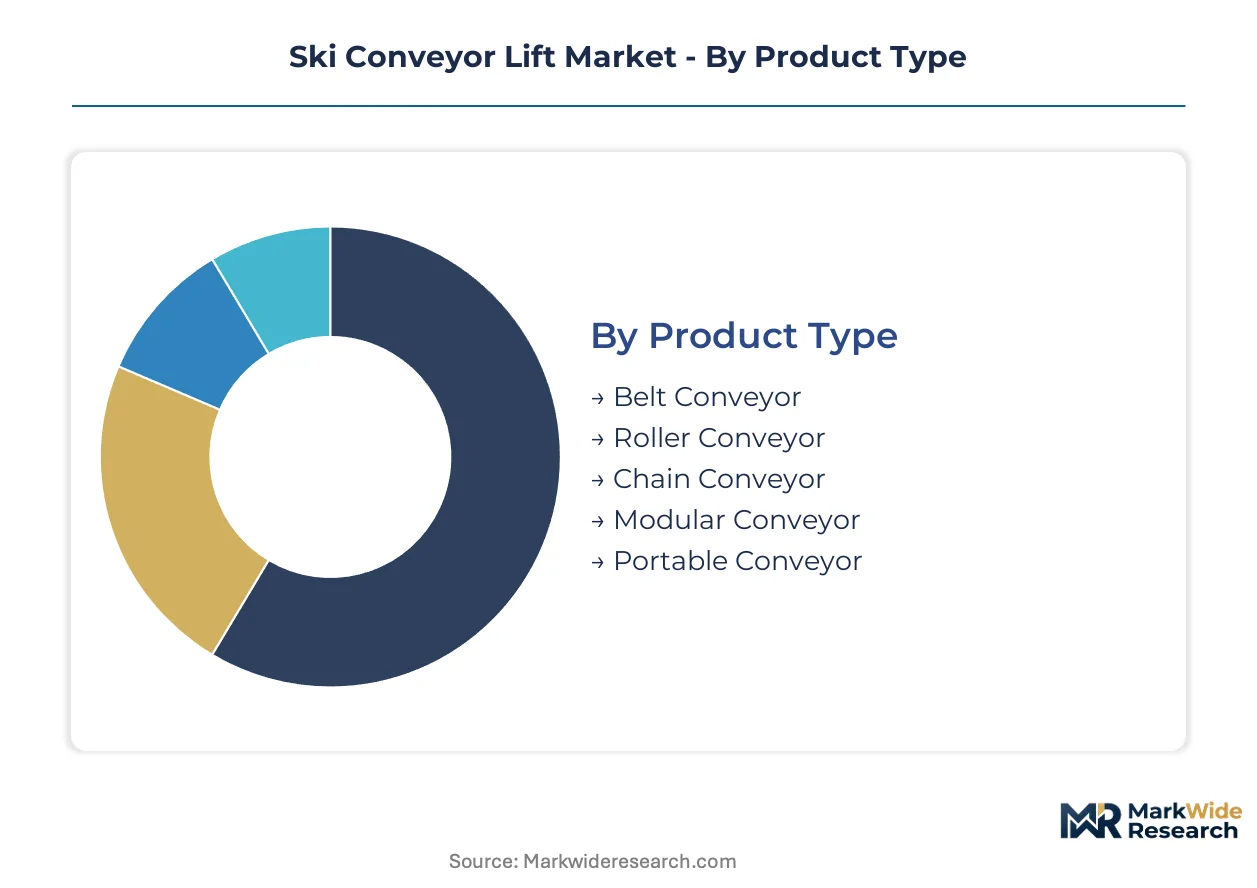
Ski conveyor lift segmentation reveals how equipment specifications align with distinct operational environments across mountain properties. Procurement decisions hinge on matching drive technology and belt configuration to passenger volume, terrain gradient, and maintenance capacity constraints.
Product Type:
Mature configurations dominate installed base economics while emerging formats address mobility and modularity demands.
- Belt Conveyor:Continuous rubber or composite belt surfaces operate below 1.5 meters per second for passenger safety. Austrian and Swiss Alpine resorts specify these for beginner terrain zones where noise reduction and minimal snow clearance justify premium procurement.
- Roller Conveyor:Interconnected rotating cylinders form the transport surface, tolerating heavier snow loads and requiring less precise alignment. Smaller ski training facilities in price-sensitive markets deploy roller systems where capital constraints outweigh operational noise concerns.
- Chain Conveyor:Metal link chains with attached crossbars provide positive drive engagement for steep approach angles. Compact footprint suits retrofit installations at legacy mountain properties with limited loading zone expansion potential.
- Modular Conveyor:Prefabricated section assemblies enable rapid deployment and seasonal relocation. Terrain park operators favor these for flexible configuration across evolving slope feature layouts.
- Portable Conveyor:Self-contained units on skids or trailers serve temporary events and mobile ski school operations. Rental fleet operators in North American mountain towns stock these for short-term capacity augmentation during peak holiday periods.
Belt Conveyor handles the majority of throughput; Portable Conveyor is the fastest mover on share.
Technology:
Cost tier stratification separates legacy hydraulic investments from electrification trajectories reshaping vendor qualification criteria.
- Motorized Drive:Electric motor and gearbox assemblies constitute the largest installed base across European ski areas. CE marking documentation requirements for modified drive systems extend approval cycles for system integrators serving Alpine destination operators.
- Electric Drive:Direct-drive permanent magnet motors eliminate gearbox maintenance and enable precise speed control. Swiss and Austrian state-owned ski areas prioritize these for Scope 3 emissions disclosure compliance under procurement preference shifts.
- Hydraulic Drive:Fluid power systems persist at older installations where complete replacement economics remain unfavorable. Mixed fleet operators face spare parts inventory complexity across obsolete and current drive technologies.
- Pneumatic Drive:Compressed air systems serve niche applications requiring explosion-proof certification or extreme temperature tolerance. Limited adoption outside specialized industrial training facilities.
- Gravity Operated:Unpowered inclined planes with manual or assisted loading function at minimal infrastructure sites. Backcountry access points and volunteer-operated community ski hills deploy these where electrification remains uneconomical.
Motorized Drive retains the largest installed footprint; Electric Drive is expanding most quickly as fluid contamination risks drive replacement decisions.
Application:
Volume concentration clusters around high-throughput transport functions while specialized use cases fragment across training and terrain access niches.
- Resort Transport:Primary uphill movement of guests from base areas to beginner and intermediate terrain. Family tourism segmentation strategies at Austrian and Swiss properties prioritize conveyor density over rope tow alternatives to reduce learning-curve friction.
- Ski Training:Dedicated beginner slopes with repetitive short-cycle uplift for instruction efficiency. North American mountain operators bundle installation with multi-year maintenance contracts to optimize total cost of ownership metrics.
- Snowboard Assistance:Low-friction surfaces accommodate single-foot strapping and sideways stance positioning. Terrain park designers specify these for feature approach zones where boarders require repeated attempts.
- Equipment Loading:Staff-assisted transport of rental fleets and grooming equipment. Operational labor reduction drives modernization at legacy Alpine installations.
- Terrain Park Access:Dedicated uplift for freestyle feature zones separate from main circulation patterns. Remote photovoltaic-battery hybrid installations enable off-grid deployment at previously uneconomical locations.
Resort Transport carries the highest passenger volume; Terrain Park Access is climbing the fastest as freestyle infrastructure expands.
End User:
Customer type determines procurement sophistication, with institutional buyers commanding lifecycle service agreements versus transactional equipment purchases.
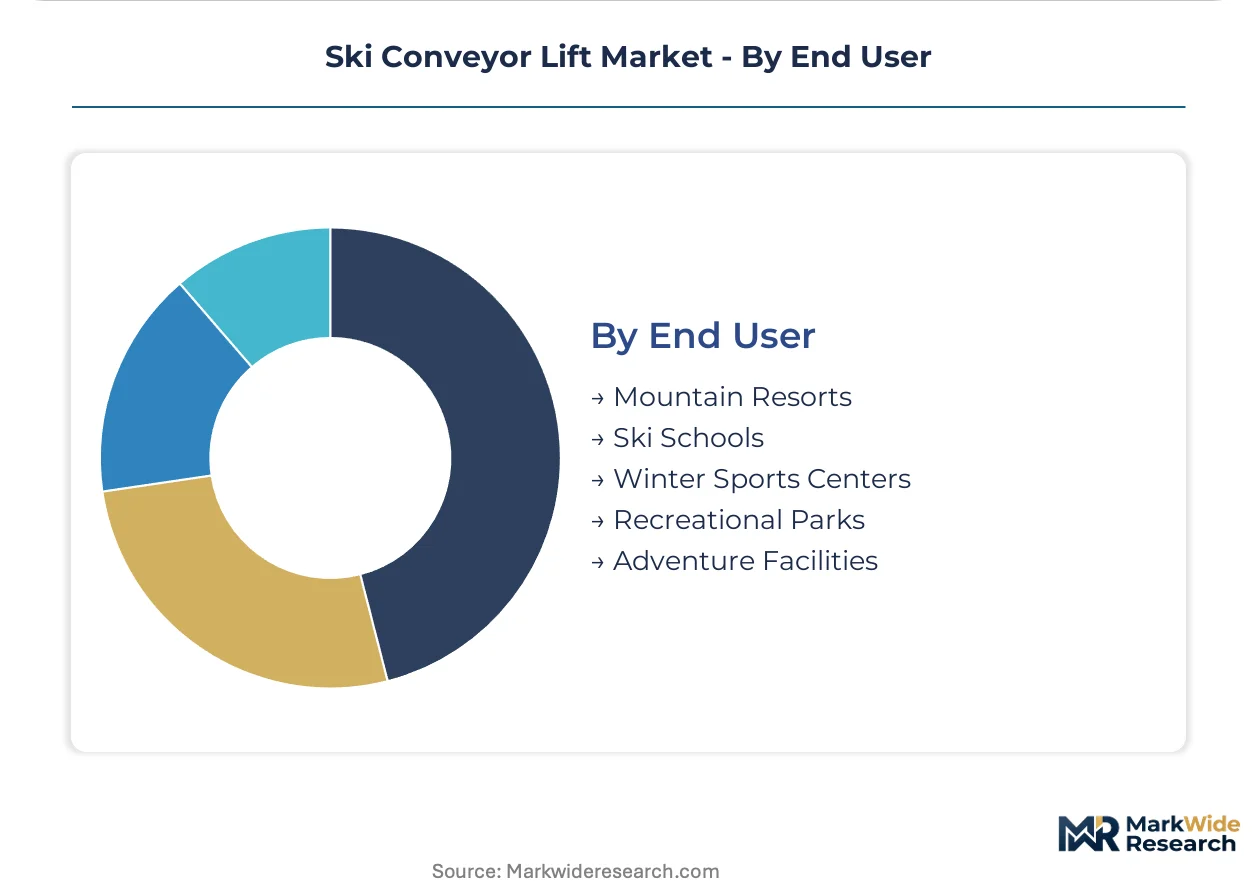
- Mountain Resorts:Integrated destination operators with capital planning committees and consolidated vendor relationships. Colorado and Utah properties prioritize total cost of ownership over upfront expenditure minimization.
- Ski Schools:Instruction-focused operations requiring high cycle frequency and reliability during lesson blocks. Predictive maintenance platforms using vibration sensors reduce unplanned downtime during peak season.
- Winter Sports Centers:Municipal and regional facilities with mixed programming across alpine and nordic disciplines. Budget constraints favor roller conveyor alternatives at smaller training sites.
- Recreational Parks:Seasonal and year-round outdoor entertainment venues with diversified activity portfolios. Procurement decisions integrate with broader snow sports infrastructure investments.
- Adventure Facilities:Private tubing hills, snow play zones, and experiential tourism operations. Mobile and modular configurations dominate given uncertain seasonal duration and relocation requirements.
Mountain Resorts command the largest capital deployment; Ski Schools are gaining share fastest as instruction-based tourism expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel and Tauern Railway corridor underpin Alpine conveyor lift demand by connecting Austrian and Italian destination markets. These transport arteries enable equipment logistics to mountain resorts across the Eastern Alps corridor.
Austria
Tyrolean and Salzburg state-owned ski areas prioritize conveyor density for family tourism capture. The EU Machinery Directive and CE marking requirements accelerate replacement cycles for legacy hydraulic installations. Innsbruck anchors component fabrication clusters where Sunkid maintains manufacturing operations.
Switzerland
Canton-owned mountain railways integrate conveyor systems into multimodal transport networks serving Zermatt and St. Moritz. Swissmedic-equivalent mechanical safety standards exceed baseline EU requirements. Zurich-Geneva industrial corridor hosts precision drive component suppliers serving Alpine destination operators.
United States
Colorado and Utah destination resorts bundle conveyor installations with multi-year service contracts. OSHA workplace exposure standards shape automated drive system specifications. Denver-based installer networks extend coverage across Rocky Mountain ski areas.
Canada
British Columbia and Quebec mountain properties show conveyor density gaps versus Alpine benchmarks. Health Canada mechanical integrity rules parallel federal workplace safety frameworks. Whistler-Blackcomb cluster drives procurement sophistication in western mountain operations.
France
Auvergne-Rhône-Alpes regional ski domains modernize surface lift infrastructure for cross-border tourism competition. ANSM-aligned safety inspections govern installation approval timelines. Grenoble engineering corridor supplies drive system integration expertise to Alpine destination operators.
Ski Conveyor Lift Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in belt and drive manufacturing. The vendor base stratifies across Austrian full-lifecycle service providers, North American installation networks, and European polymer belt fabricators. Three archetypes dominate: Alpine-anchored system integrators with manufacturing depth, regional installer networks with maintenance lock-in, and component suppliers with material science differentiation. Competitive moves concentrate on geographic expansion through installer acquisition and electrification portfolio diversification.
Among Alpine-anchored fabricators, Sunkid represents the vertically integrated archetype with captive manufacturing and long-term supply contracting. Magic Carpet Lifts exemplifies the North American installer-network model, capturing recurring revenue through maintenance bundling. Forbo Movement Systems occupies the component-specialist position, anchoring polymer belt supply through engineered materials divisions. These three patterns illustrate how procurement channel control determines competitive position across distinct mountain resort markets.
| Leading Market Players |
|---|
| Sunkid |
| Magic Carpet Lifts |
| Forbo Movement Systems |
| Esbelt |
| AMMERAAL BELTECH |
| SNOWMAX |
| MEB IMPIANTI |
| MND Group |
| Star Lifts |
| Others |
Pricing and Supply Chain Analysis
Innsbruck's component fabrication cluster concentrates precision drive manufacturing capacity, granting Austrian system integrators pricing leverage over North American mountain operators who must absorb transatlantic logistics premiums. This geographic asymmetry shapes procurement negotiations, with Alpine vendors commanding lifecycle service premiums while offshore alternatives compete on capital expenditure minimization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales bundling intensity. CE-marked electric drive systems with predictive maintenance integration command premium positioning against hydraulic retrofits sold on transactional terms. Price erosion runs through economy-tier roller conveyor configurations as Asian component suppliers expand belt fabrication capacity. Small ski training facilities in price-sensitive markets exhibit highest price sensitivity, while Colorado destination resorts prioritize total cost of ownership metrics over upfront expenditure.
Supply Chain Analysis
EU dual-use export controls on permanent magnet motor technology limit technology transfer to non-European fabrication partners, constraining supply expansion. Production gravity centers on Austria, Germany, and Switzerland for precision drive assemblies, with polymer belt fabrication drawing from Italian and Czech rubber processing hubs. Supply chain risk concentrates in single-source vulnerability for engineered composite belt materials facing petroleum feedstock volatility. Distribution runs through authorized installer networks that bundle equipment procurement with multi-year maintenance contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance subscriptions and lifecycle parts agreements expand faster than hardware shipments. Recurring revenue layers now determine vendor profitability more than initial equipment margins.
For Market Incumbents: Harden installer network control through exclusive territory agreements in underpenetrated Canadian mountain markets beyond British Columbia and Quebec. Deepen backward integration into polymer belt fabrication to offset petroleum input volatility threatening margin stability. Prioritize CE marking documentation capabilities as regulatory approval timelines extend competitive moats against emerging challengers. For New Entrants and Emerging Players: Canadian Prairie provinces and Maritime region ski facilities present white-space expansion potential given conveyor density gaps versus Alpine benchmarks. Target terrain park operators with photovoltaic-battery hybrid drive configurations addressing remote electrification constraints. Pursue modular conveyor rental fleet partnerships with North American mountain town operators seeking short-term capacity augmentation. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because installer network density and maintenance contract backlogs determine sustainable cash flow generation. Acquisition targets should demonstrate captive regional installer relationships and Scope 3 emissions disclosure readiness for Austrian and Swiss state-owned procurement channels. Monitor electrification subsidy program expansions across Alpine corridor jurisdictions as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Installer Network Acquisition | Captive maintenance contract backlogs lock in recurring revenue at Colorado destination resorts. |
| Electric Drive Portfolio Expansion | CE marking compliance positions vendors for Austrian state-owned ski area procurement preferences. |
| Predictive Maintenance Platform Launch | Vibration sensor deployments reduce unplanned downtime during Swiss peak season operations. |
| Photovoltaic-Battery Hybrid Development | Off-grid capability unlocks terrain park installations at previously uneconomical remote locations. |
| Polymer Belt Backward Integration | In-house composite fabrication insulates margins from petroleum feedstock price volatility. |
Research Methodology
Cross-validation between primary interviews with mountain resort operations directors, lift maintenance supervisors, and ski school program managers anchors the qualitative findings against secondary validation from EU Machinery Directive implementation records, OSHA workplace safety filings, and Health Canada mechanical integrity guidelines. Bottom-up triangulation aggregates individual resort capital expenditure patterns while top-down calibration incorporates Alpine tourism board infrastructure investment surveys.
Calibration against historical replacement cycle data and regulatory compliance deadline clustering shapes the projection framework across the analysis window. Segmentation dimensions span product type, drive technology, application function, and end-user procurement sophistication. CAGRs derive from equipment shipment tracking and service contract value aggregation. Forecast inputs incorporate electrification subsidy program announcements and F-Gas Regulation phase-down timelines affecting ancillary mountain resort equipment procurement.
Practitioners should monitor EU Machinery Directive amendment proposals and OSHA automated drive system rulemakings for early signals of compliance-driven replacement acceleration. Forecasts reflect assumptions regarding continued Alpine family tourism segmentation strategies and sustained petroleum-derived polymer input cost structures. Material shifts in electrification subsidy generosity or engineered composite material substitution breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Poland Road Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
US Transportation and Logistics Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
UAE Cold Chain Logistics Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Intermodal Freight Transportation Market
Transportation & Logistics
Russia Road Freight Transport Market
Transportation & Logistics
Weigh in Motion Market