
 Dog Shampoo Market | 2026-2036
Dog Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
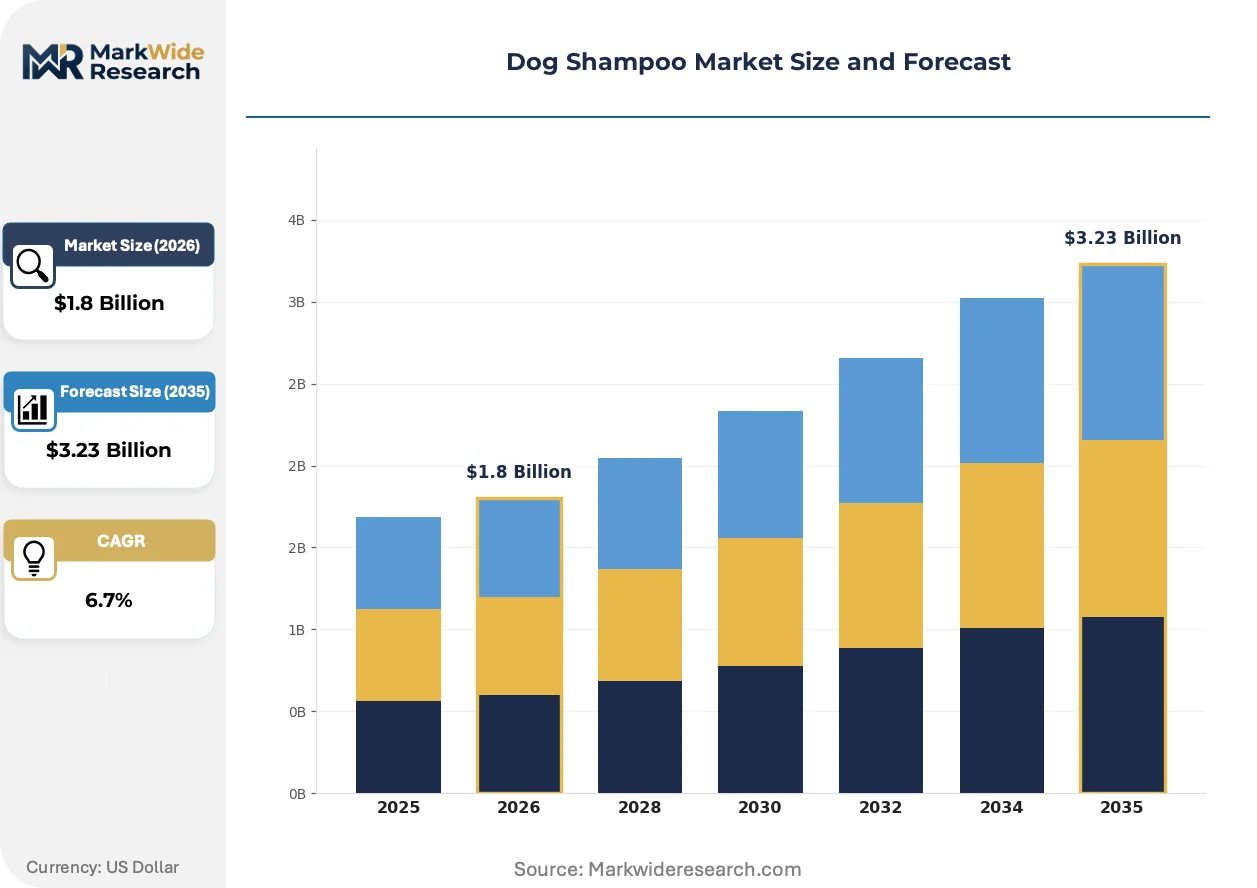
Dog Shampoo Market Analytics
A capital-intensity divergence between contract manufacturers and brand owners is rotating competitive advantage toward upstream formulation control. PURUS.PET leverages captive R&D labs to develop pH-balanced veterinary formulations. Biocrown Biotechnology Co., Ltd. anchors its position through integrated surfactant synthesis and toll-manufacturing scale. Private Label Dynamics competes by offering turnkey SKU development for emerging direct-to-consumer brands.
Dog shampoo comprises surfactant-based cleansing formulations engineered to canine skin pH, typically incorporating mild anionic or amphoteric agents, conditioning polymers, and functional actives for dermatological or parasitic indications. These products serve veterinary clinics, professional grooming operations, and retail consumers seeking coat hygiene, odor management, or therapeutic skin intervention. The ingredient-type dimension shows organic and natural formulations capturing margin pools as pet owners reject synthetic preservatives, while hypoallergenic SKUs within the product-type category lead volume growth due to rising canine atopic dermatitis diagnoses. Antiparasitic variants remain a mature, price-competitive segment tethered to seasonal tick and flea cycles.
The US EPA regulates topical pet care products under FIFRA pesticide provisions, requiring efficacy substantiation for antiparasitic claims and restricting active ingredient concentrations. The FDA Center for Veterinary Medicine oversees medicated shampoos with therapeutic intent, while state-level California Proposition 65 and emerging clean-label statutes in New York and Massachusetts force reformulation transparency. The EU REACH framework and ECHA substance restrictions govern export-bound formulations, adding compliance layers for multinational suppliers. Stakeholders must monitor evolving state ingredient blacklists and veterinary channel certification requirements to preserve market access and pricing power.
Market Dynamics
Formulation transparency mandates from California Proposition 65 and emerging clean-label statutes in New York and Massachusetts are forcing surfactant reformulation cycles that compress product development timelines and elevate R&D spend across the competitive set.
Growth Catalysts
- Veterinary channel certification:Clinic endorsement requirements under FDA Center for Veterinary Medicine oversight create pull-through demand for pH-balanced therapeutic formulations.
- Canine atopic dermatitis prevalence:Rising veterinary diagnoses of skin conditions in urban companion animal populations sustain volume growth for hypoallergenic SKUs.
- REACH compliance as export enabler:EU ECHA substance restrictions and registration frameworks allow compliant US manufacturers to access premium European grooming salon channels.
Market Restraints
- Coconut-derived surfactant price volatility:Lauryl glucoside and decyl glucoside input costs fluctuate with Philippine and Indonesian agricultural output cycles.
- Contract manufacturer concentration:Toll-manufacturing capacity clusters in Guangdong and Zhejiang provinces expose brands to single-source supply risk.
- FIFRA efficacy substantiation burden:US EPA pesticide registration requirements for antiparasitic claims extend time-to-market by 18-24 months.
Strategic Opportunities
- Direct-to-consumer subscription models:Emerging DTC brands bypass veterinary and retail intermediaries through automated replenishment platforms.
- Waterless cleansing formats:Foam and wipe delivery systems address apartment-dwelling pet owner constraints in dense urban markets.
- Biodegradable polymer conditioning agents:Convergence of green chemistry and veterinary dermatology opens premium positioning for marine-safe formulations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in amphoteric surfactant stability and canine skin microbiome compatibility commands premium compensation.
- Multi-jurisdiction label harmonization:Reconciling California Proposition 65 warnings, EU REACH SDS requirements, and state-level ingredient blacklists strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Shampoo Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hypoallergenic, Antiparasitic, Deodorizing, Moisturizing Application: Bathing, Grooming, Treatment, Conditioning Ingredient Type: Organic, Natural, Synthetic, Herbal Packaging Type: Bottle, Tube, Jar, Sachet |
| Companies Covered | PURUS.PET, TY Cosmetic, Natural Pet Innovations, Biocrown Biotechnology Co., Ltd., Bo International, Tropical Products, Inc., Metro Private Label, Private Label Dynamics, Pure Source, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Shampoo Market Evolving Landscape
Active ingredient delivery systems and surfactant chemistry are converging with digital commerce infrastructure to reshape how therapeutic and maintenance formulations reach end users.
Microencapsulated essential oil blends are decomposing the traditional antiparasitic shampoo category by enabling extended-release tick and flea protection without pyrethroid residues. Veterinary clinics in Texas and Florida are piloting these formulations for seasonal prevention programs. The technology is decomposing conventional monthly topical applicator revenue models and compressing repurchase cycles into quarterly bathing routines.
California Assembly Bill 496 and New York Senate Bill S4265A mandate ingredient disclosure thresholds for pet grooming products, forcing reformulation of legacy preservative systems. Manufacturers serving these states must replace formaldehyde-releasing compounds with phenoxyethanol or sodium benzoate alternatives. Professional grooming salons in Los Angeles and New York City metro areas are now requiring supplier certification of compliance before contract renewal.
Subscription-based replenishment platforms are capturing urban millennial and Gen Z pet owners who prioritize convenience over retail browsing. Direct-to-consumer brands bypass veterinary recommendation channels through influencer-driven education on skin pH and coat type matching. This behavioral shift concentrates in coastal metropolitan markets where apartment living limits home bathing infrastructure and professional grooming frequency rises.
Dog Shampoo Market Segmentation
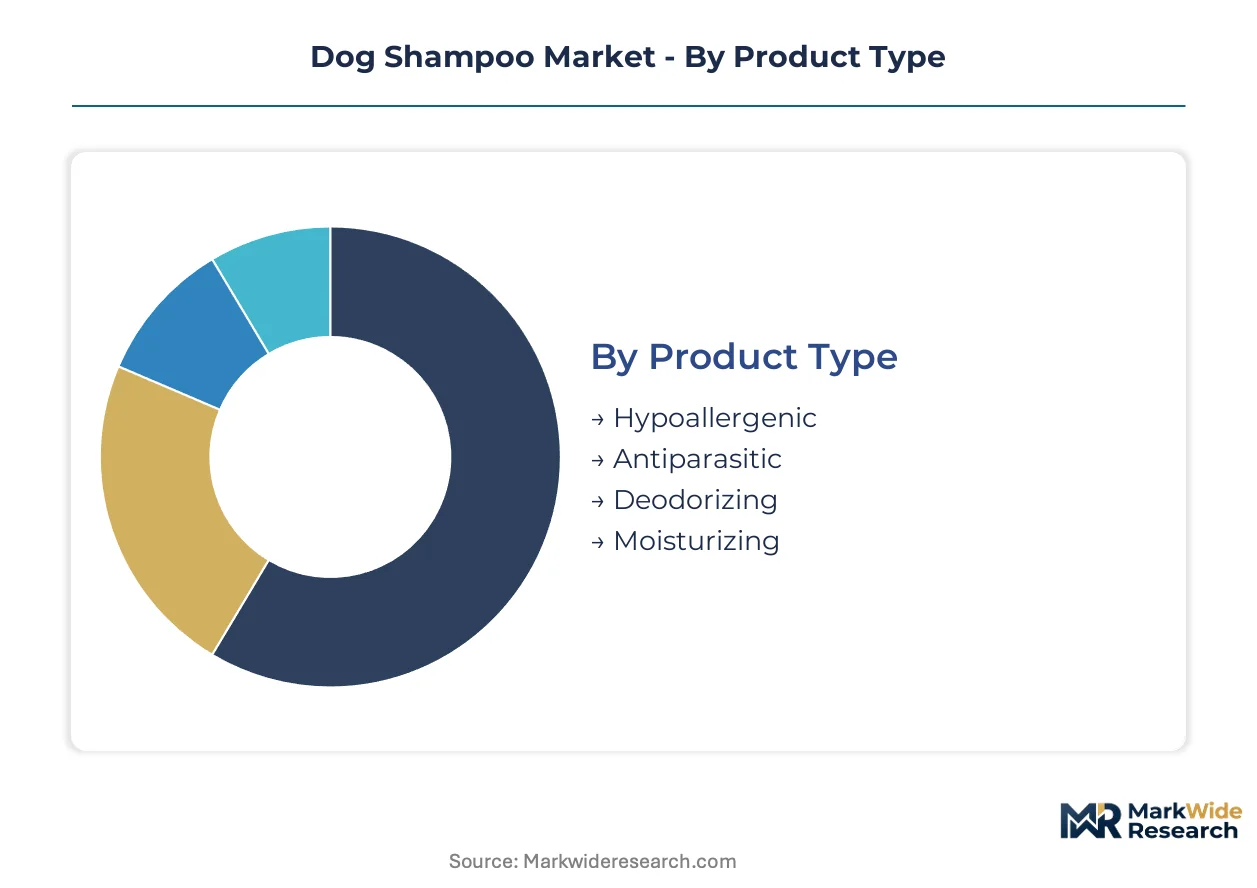
Segmentation in dog shampoo markets determines margin capture and channel access. Formulation chemistry, packaging format, and end-use application each create distinct competitive battlegrounds with divergent regulatory exposure and pricing power.
Product Type:
Waterless foam cleansers and veterinary-grade therapeutic rinses are displacing conventional bathing formats in urban households, compressing volume for legacy surfactant-heavy SKUs.
- Hypoallergenic:pH-balanced formulations exclude common sensitizers including synthetic fragrances and sulfates. Veterinary clinics in California and New York metro areas are mandating these SKUs for atopic dermatitis protocols, with clinic endorsement creating pull-through into retail.
- Antiparasitic:Pyrethroid and permethrin-based formulations require EPA FIFRA registration for efficacy claims. Florida and Texas veterinary networks drive seasonal demand spikes tied to tick population cycles, though microencapsulated essential oil alternatives are eroding this segment's growth trajectory.
- Deodorizing:Enzymatic and zinc-based odor neutralizers target apartment-dwelling owners in dense urban markets.
- Moisturizing:Oatmeal and ceramide-enriched conditioners serve double-coated breeds in dry climate regions.
Antiparasitic formulations anchor the volume base while hypoallergenic SKUs gain share at the steepest rate.
Application:
Professional grooming salon procurement is concentrating spend on multi-functional products that collapse treatment and conditioning steps, pressuring single-purpose maintenance formulations.
- Bathing:Core cleansing function using mild anionic surfactants adjusted to canine skin pH of 6.2-7.5. Demand concentrates in suburban households with home bathing infrastructure, though apartment living trends in coastal cities are constraining this segment's expansion.
- Grooming:Pre-show preparation and coat finishing products serve competitive breeding and exhibition circuits. Los Angeles and New York City metro grooming chains are specifying salon-exclusive SKUs with concentrated actives to justify service premiums.
- Treatment:Medicated formulations addressing bacterial, fungal, or parasitic conditions require veterinary prescription or clinic dispensing in regulated channels.
- Conditioning:Post-bath detangling and static control for long-coated breeds.
Bathing maintains the largest installed base while grooming applications are climbing the fastest as professional service frequency rises.
Ingredient Type:
Clean-label statutes in California, New York, and Massachusetts are accelerating substitution away from synthetic preservative systems toward botanically-derived alternatives.
- Organic:USDA-certified organic surfactants and actives command 40-60% price premiums over conventional equivalents. Supply chains source coconut-derived glucosides from Philippine and Indonesian cooperatives, exposing margins to agricultural commodity cycles.
- Natural:Plant-derived formulations without synthetic preservatives. Massachusetts and emerging state-level disclosure mandates are forcing reformulation of legacy products, with phenoxyethanol replacing formaldehyde-releasing compounds.
- Synthetic:Petrochemical-derived surfactants and preservatives with established stability profiles.
- Herbal:Traditional botanical extracts including neem, tea tree, and chamomile targeting specific coat conditions.
Synthetic ingredients still dominate tonnage while organic certification is expanding most quickly in premium veterinary channels.
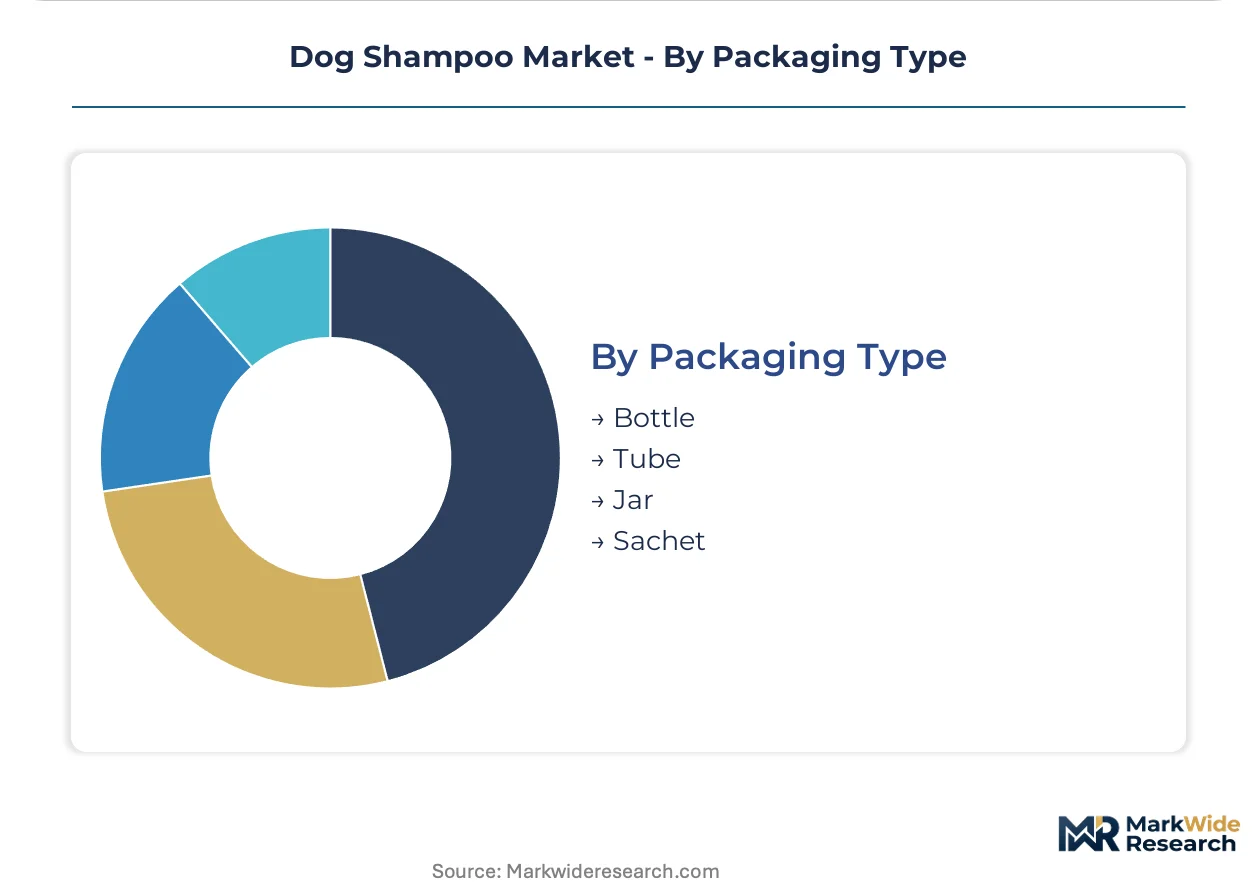
Packaging Type:
Direct-to-consumer subscription models are favoring formats that minimize shipping weight and enable precise dosing, disadvantaging rigid containers in urban last-mile delivery.
- Bottle:Standard HDPE or PET containers dominate retail shelf presence. Professional grooming salons in Texas and Florida are specifying bulk pump formats to reduce per-service material cost.
- Tube:Collapsible aluminum or laminate tubes suit travel and trial sizes. Coastal metropolitan DTC brands are adopting tube formats for subscription sampling programs targeting apartment-dwelling millennials.
- Jar:Wide-mouth containers for mask and treatment formulations requiring scoop application.
- Sachet:Single-use pouches for veterinary clinic dispensing and grooming salon backbar.
Bottle formats retain the volume anchor position while tube packaging is gaining share fastest through e-commerce subscription penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany while manufacturing scale clusters in coastal Chinese provinces. This asymmetry shapes regional strategies for formulation control versus toll-manufacturing access.
United States
Urban pet owners in Los Angeles and New York metro areas drive premium demand for veterinary-recommended hypoallergenic formulations. The US EPA enforces FIFRA pesticide registration requirements for antiparasitic claims, extending product development timelines. Texas and Florida veterinary networks anchor seasonal demand spikes tied to tick population cycles.
Germany
Professional grooming salon chains in Munich and Hamburg specify REACH-compliant formulations for export-bound private-label programs. The EU ECHA substance restrictions govern active ingredient concentrations, forcing reformulation transparency. Baden-Württemberg hosts integrated surfactant synthesis operations serving premium European channels.
China
Contract manufacturing capacity clusters in Guangdong and Zhejiang provinces, exposing brands to single-source supply risk. The country's national chemical safety regulator enforces GB standards for cosmetic-grade surfactants. Shenzhen and Hangzhou toll-manufacturers anchor global supply for mid-tier private-label brands.
United Kingdom
London and Southeast England grooming chains demand salon-exclusive SKUs with concentrated actives to justify service premiums. The UK's national veterinary medicines regulator oversees medicated shampoo distribution through clinic channels. Midlands-based formulators develop pH-balanced products for double-coated breeds.
Canada
Health Canada and the Pest Management Regulatory Agency jointly regulate antiparasitic pet care products, requiring efficacy substantiation parallel to US EPA frameworks. Ontario and Quebec urban markets concentrate demand for subscription-based DTC replenishment models. Vancouver grooming salons prioritize marine-safe biodegradable formulations.
Dog Shampoo Market Competitive Landscape
Concentration sits with contract manufacturers and captive R&D specialists rather than brand aggregators. The vendor base spans three tiers: integrated surfactant producers with captive formulation labs, toll-manufacturers offering turnkey SKU development, and direct-to-consumer brands bypassing traditional channels. Strategic moves center on backward integration into surfactant synthesis and automated replenishment platform deployment.
Among integrated biotechnology specialists, Biocrown Biotechnology Co., Ltd. anchors the manufacturing tier through captive production infrastructure. PURUS.PET occupies a position within the veterinary-formulation archetype, leveraging in-house R&D capabilities for pH-balanced development. Private Label Dynamics exemplifies the toll-manufacturing model, serving emerging direct-to-consumer brands with rapid SKU turnaround.
| Leading Market Players |
|---|
| PURUS.PET |
| TY Cosmetic |
| Natural Pet Innovations |
| Biocrown Biotechnology Co., Ltd. |
| Bo International |
| Tropical Products, Inc. |
| Metro Private Label |
| Private Label Dynamics |
| Pure Source, LLC |
| Others |
Value Network & Pricing Analysis
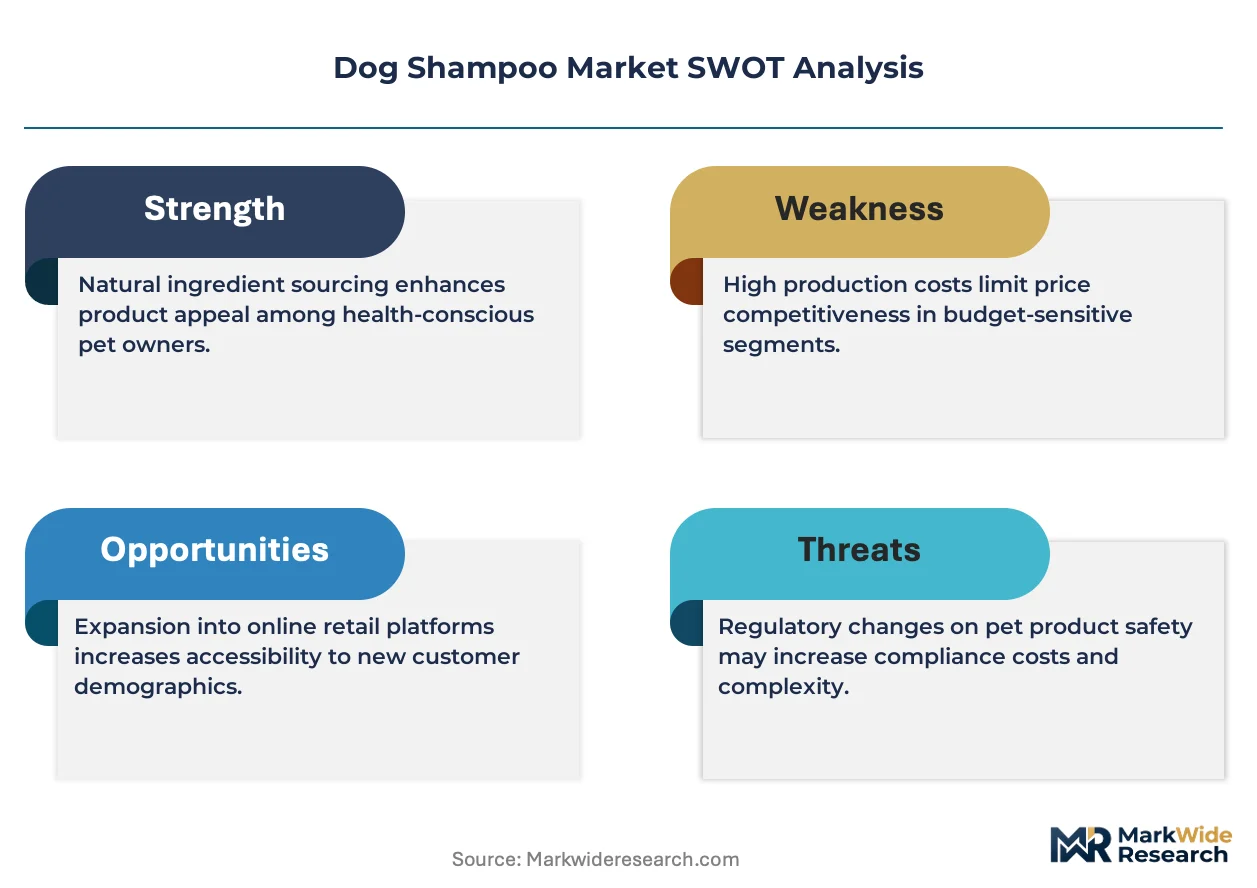
Captive surfactant synthesis capacity in Guangdong and Zhejiang provinces creates scale economies that compress per-unit formulation costs while elevating price floors for brands lacking upstream integration. This asymmetry concentrates margin capture with toll-manufacturers and integrated biotech specialists, forcing brand owners to absorb input volatility or surrender pricing power through long-term supply commitments.
Pricing Analysis
The customization-premium spread separates veterinary-certified therapeutic formulations from commodity maintenance SKUs by a factor of three to five. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel endorsement, with FDA Center for Veterinary Medicine oversight and clinic dispensing authorization commanding the highest tier. Cost compression in the antiparasitic segment is intensifying because microencapsulated essential oil alternatives erode pyrethroid-based legacy margins. Professional grooming salons exhibit the least price sensitivity due to service-bundling economics, while mass-market retail consumers gravitate toward subscription-discounted economy tiers.
Supply Chain Analysis
China and the Philippines anchor global supply for coconut-derived glucoside surfactants and integrated formulation manufacturing. Philippine and Indonesian agricultural output cycles feed lauryl glucoside and decyl glucoside feedstock streams, while Guangdong and Zhejiang toll-manufacturers concentrate finished goods production. Single-source vulnerability clusters in coastal Chinese provinces expose brands to logistics disruption and regulatory inspection backlogs. Distribution runs through professional grooming salon networks, veterinary clinic dispensing channels, and direct-to-consumer subscription platforms with divergent service-level requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity and captive R&D infrastructure gaps separate viable competitors from margin-compressed assemblers. The market rewards upstream control over surfactant chemistry and pH-balanced veterinary expertise while punishing pure brand plays dependent on contract manufacturing.
For Market Incumbents: Fortify position through backward integration into surfactant synthesis or exclusive toll-manufacturing partnerships in Zhejiang and Guangdong. Acquire formulation chemist teams with amphoteric stability expertise to defend against microencapsulated essential oil substitutes eroding antiparasitic revenue. Prioritize California Proposition 65 compliance certification to preempt salon contract non-renewals. For New Entrants and Emerging Players: Lead with waterless foam and wipe formats targeting apartment-dwelling millennials in Los Angeles and New York metro areas where home bathing infrastructure constraints concentrate demand. The direct-to-consumer subscription channel remains the most penetrable white space, bypassing veterinary recommendation gatekeepers through influencer-driven skin pH education. Deploy automated replenishment platforms with tube-format sampling programs to capture coastal urban cohorts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated biotech specialists with captive surfactant synthesis and FDA Center for Veterinary Medicine submission capabilities over pure-play brand aggregators. Long-term viability hinges on formulation transparency compliance and REACH export access for European salon channel penetration. Monitor state-level ingredient blacklist expansions beyond California, New York, and Massachusetts as inflection indicators for reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Synthesis | Captive supply of lauryl glucoside insulates margins from Philippine agricultural volatility. |
| Veterinary Channel Certification Investment | FDA Center for Veterinary Medicine oversight creates pull-through demand and pricing power. |
| Direct-to-Consumer Subscription Launch | Automated replenishment captures urban millennials bypassing retail and veterinary intermediaries. |
| Waterless Format Development | Foam and wipe delivery systems address apartment-dwelling constraints in dense coastal metros. |
| REACH Compliance Certification | ECHA substance registration unlocks premium European grooming salon export channels. |
Research Methodology
Initial hypotheses were tested against primary input from formulation chemists at contract manufacturers, procurement leads at professional grooming salon chains, regulatory affairs specialists navigating FDA and EPA frameworks, and veterinary dermatologists prescribing therapeutic protocols. Secondary validation drew from EPA FIFRA registration databases, state-level ingredient disclosure statutes, EU ECHA substance restriction lists, and customs trade data tracking coconut-derived surfactant flows. Bottom-up SKU volume estimates and top-down market sizing triangulated across channel checks and import-export records.
Variance decomposition separates volume growth drivers from price-mix effects across the projection horizon. The analytical framework models product type, ingredient certification tier, packaging format, application channel, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from regression analysis against veterinary diagnosis rates, urban pet ownership density, and clean-label statute adoption timelines. Canine atopic dermatitis prevalence curves and surfactant input cost indices feed forecast sensitivity scenarios.
The analysis sits within stated boundaries; outcomes outside sustained EPA and state-level disclosure enforcement, stable Philippine coconut harvests, and continued veterinary channel consolidation would require recalibration. Forecasts reflect assumptions about regulatory inspection capacity, toll-manufacturer quality consistency, and subscription platform customer acquisition economics. Recalibration cycles align with material shifts in state-level ingredient blacklists, REACH substance restriction updates, and microencapsulation technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Pet Stairs Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
South America Pet Treats Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Dog Clothing and Accessories Market