
 Dog Clothes Market | 2026-2036
Dog Clothes Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Clothes Market Analytics
Subscription-based replenishment services for seasonal dog apparel is consolidating around recurring revenue models that lock in customer lifetime value. Canada Pooch leverages direct-to-consumer channels to control pricing and brand narrative across North America. Ruffwear sustains technical differentiation through performance-oriented designs built for outdoor canine activities. Hurtta anchors its position with weatherproof engineering standards that appeal to Nordic and North American climates.
Dog clothes constitute functional and decorative garments engineered from woven or knitted textiles, typically incorporating water-resistant membranes, reflective trims, or thermal insulation layers measured in grams per square meter, designed to protect canines from environmental stressors or express owner identity. Cotton and polyester dominate material inputs due to cost scalability and dye compatibility, though wool blends command margin premiums in cold-climate applications. Coats and sweaters occupy the largest volume share as seasonal essentials, while raincoats represent the fastest-expanding category as urban pet owners prioritize all-weather walkability. Pricing stratifies across budget, mid-range, premium, and luxury tiers, with luxury segments capturing disproportionate margin pools through limited-edition designer collaborations.
The US Consumer Product Safety Commission and the EU's REACH framework govern textile chemical content and flammability standards that manufacturers must satisfy for market access, while the OEKO-TEX Standard 100 certification increasingly functions as a de facto procurement filter for premium retailers. China's GB standards for textile safety and labeling create additional compliance layers for supply chains sourcing from or selling into that manufacturing base. Stakeholders must monitor how proliferating sustainability disclosure requirements across multiple jurisdictions reshape material sourcing economics and brand positioning thresholds.
Market Dynamics
The US Consumer Product Safety Commission's flammability standards for pet textiles and the EU's REACH chemical safety framework are forcing manufacturers to reconfigure material sourcing and testing protocols across supply chains.
Growth Catalysts
- REACH chemical compliance:The EU's textile safety requirements are accelerating certified material adoption among premium European retailers seeking OEKO-TEX Standard 100 validation for canine apparel.
- Millennial pet ownership clusters:Urban concentrations of younger pet owners in metropolitan United States markets are normalizing seasonal wardrobe rotation for companion animals.
- Reflective trim integration:Visibility-enhancing materials originally developed for human athletic wear are migrating into dog coat designs for nighttime urban walking safety.
Market Restraints
- Cotton price volatility:Input cost swings for natural fibers compress margin predictability for mid-tier manufacturers dependent on commodity textile sourcing.
- Chinese GB standard compliance:Manufacturers selling into or sourcing from China face additional testing layers for textile safety and labeling that extend product development timelines.
- Seasonal demand compression:Weather-dependent purchase cycles concentrate revenue into narrow quarterly windows, straining working capital for inventory-heavy business models.
Strategic Opportunities
- Subscription replenishment models:Recurring delivery services for size-adjusted seasonal apparel are capturing predictable revenue streams from urban United States households with multiple dogs.
- Wool blend premiumization:Natural fiber thermal insulation measured in grams per square meter commands pricing power in cold-climate Nordic and northern United States markets.
- CSRD sustainability disclosure:The EU's corporate sustainability reporting requirements are creating procurement preference for transparent supply chain documentation among European retail buyers.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous compliance with US CPSC flammability rules, EU REACH chemical limits, and Chinese GB standards extends product launch cycles by months.
- Size standardization fragmentation:Absence of universal canine measurement protocols forces retailers to manage excessive SKU complexity for breed-specific fit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Clothes Market |
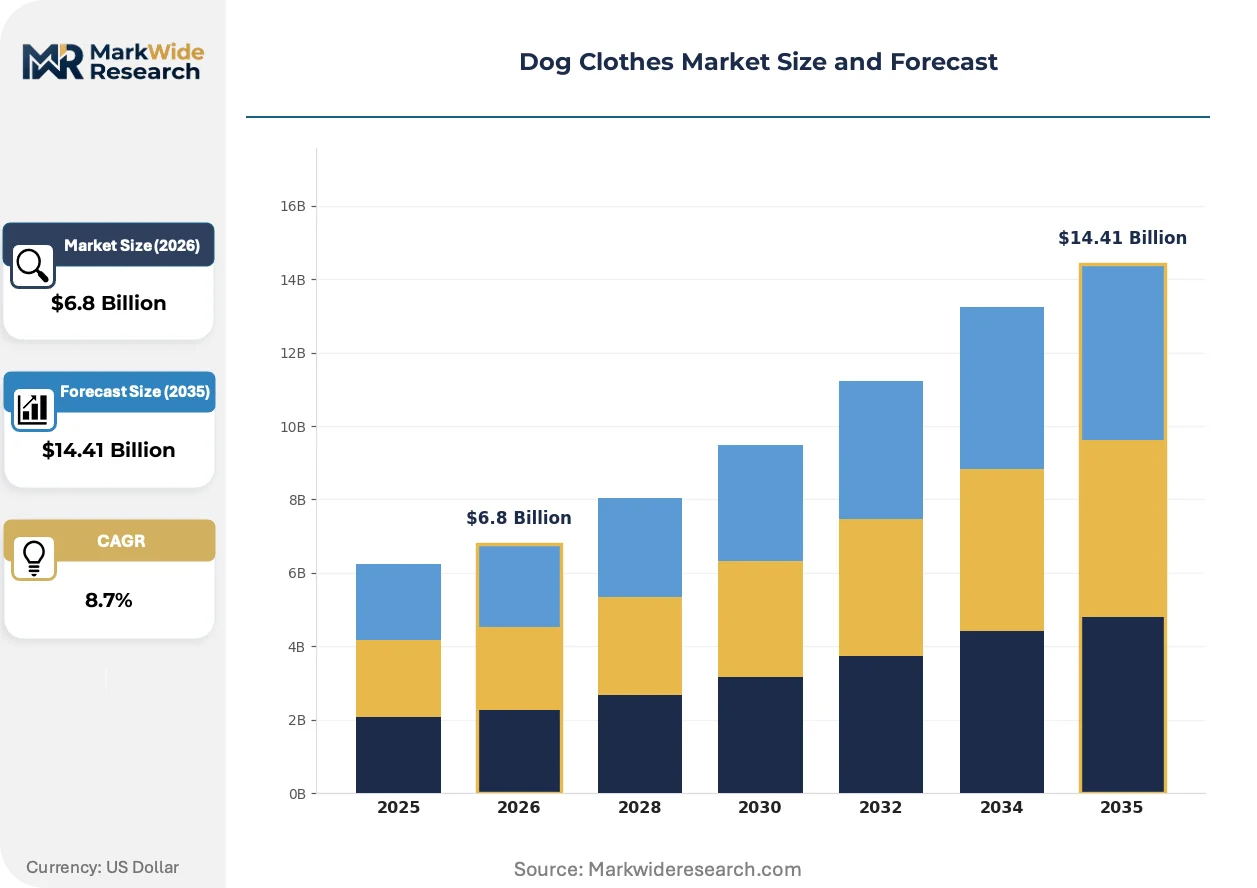
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coats, Sweaters, T-Shirts, Raincoats Material: Cotton, Polyester, Nylon, Wool Size: Small, Medium, Large, Extra Large Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Canada Pooch, Moshiqa, Ruffwear, Milk & Pepper, PetRageous Designs, Hurtta, Bitch New York, TRIXIE Heimtierbedarf GmbH & Co. KG, Weatherbeeta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Clothes Market Evolving Landscape
Material science advances and regulatory disclosure mandates are compressing traditional competitive advantages built on opaque supply chains, while direct-to-consumer channels are disintermediating conventional retail gatekeepers.
Water-resistant membrane technologies originally engineered for human outdoor apparel are overtaking conventional coated fabrics in premium dog raincoat construction. Urban pet owners in Seattle, Portland, and Vancouver are adopting these garments at accelerating rates for daily walkability regardless of precipitation. This shift is compressing margins for manufacturers dependent on basic polyester shells without bonded waterproofing layers.
The EU's Corporate Sustainability Reporting Directive is mandating supply chain transparency disclosures for large apparel retailers operating in European markets. Manufacturers must now document fiber origins, chemical treatment processes, and carbon intensity metrics to maintain procurement relationships with major European distributors. Premium and luxury tier dog apparel segments are responding fastest, using certification as competitive differentiation against budget alternatives.
Size-matched replenishment subscriptions are replacing episodic seasonal purchasing among multi-dog households in dense United States metropolitan areas. Direct-to-consumer platforms with fit-prediction algorithms are capturing customer lifetime value that traditional pet specialty retailers previously controlled. This behavioral shift is most visible in New York, Los Angeles, and Chicago, where convenience prioritization overrides price sensitivity for time-constrained professional pet owners.
Dog Clothes Market Segmentation
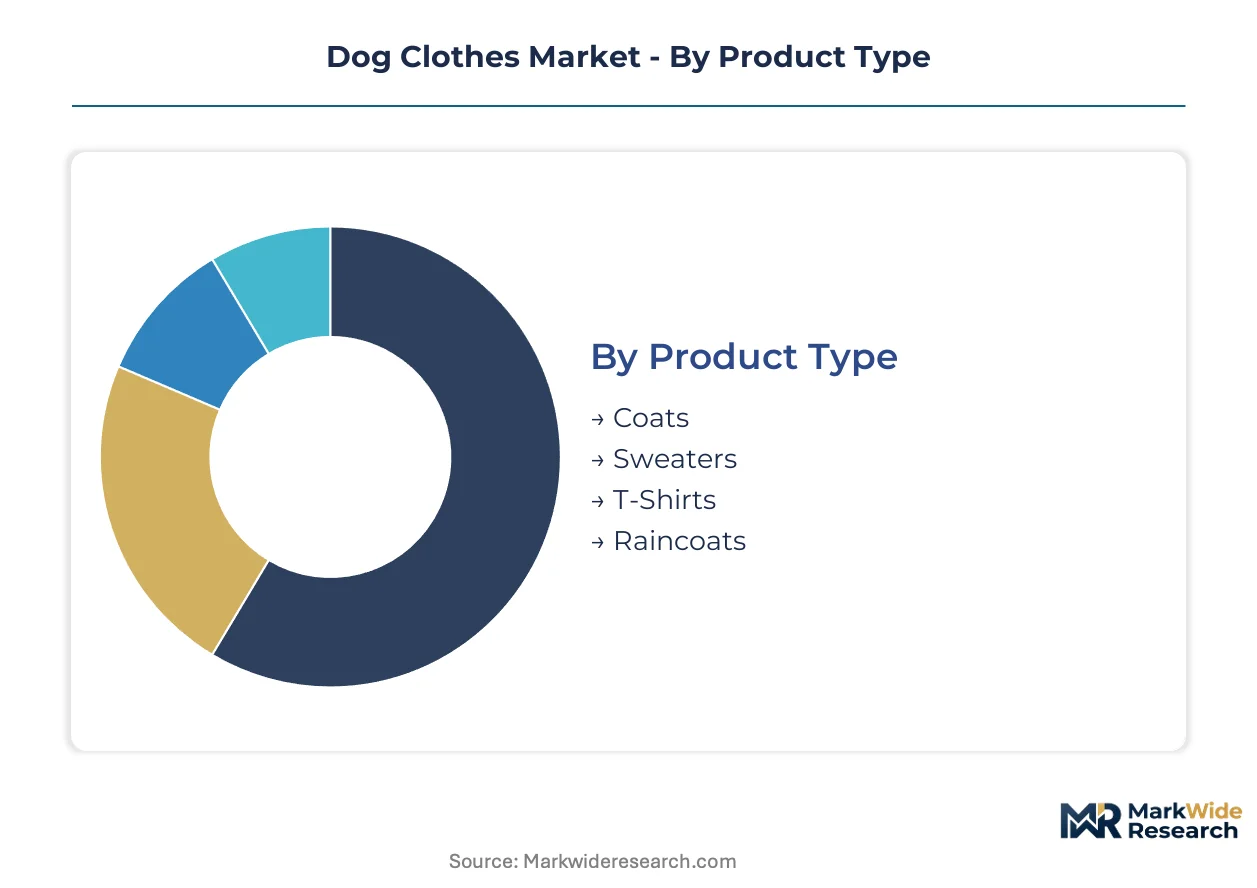
Dog apparel manufacturers navigate fragmented demand across functional needs, aesthetic preferences, and breed-specific requirements. Segmentation discipline determines inventory risk exposure and margin capture potential in a market where fit precision drives return rates.
Product Type:
Capital intensity escalates sharply with technical complexity, as bonded waterproof membranes and thermal insulation layers require specialized lamination equipment.
- Coats:Outerwear engineered with water-resistant membranes measured in grams per square meter dominates cold-climate urban markets. Demand concentrates in Chicago, Minneapolis, and Toronto where winter walkability necessitates thermal protection.
- Sweaters:Knitted garments utilizing wool blends or acrylic yarns occupy the highest volume tier. Metropolitan United States households with toy breeds and short-coated terriers drive seasonal replenishment cycles.
- T-Shirts:Lightweight cotton or cotton-poly blends serve decorative and sun-protection functions in warm-weather markets.
- Raincoats:Bonded waterproof fabrics with reflective trim integration are gaining share fastest among Pacific Northwest urban owners prioritizing year-round outdoor activity.
Most installed capacity flows through Coats. Expansion is steepest in Raincoats.
Material:
Raw material selection dictates compliance burden, as natural fibers face distinct chemical testing protocols under REACH and CPSC frameworks versus synthetic alternatives.
- Cotton:Natural fiber commanding cost scalability and dye compatibility across budget and mid-range tiers. Price volatility at commodity exchanges compresses margin predictability for manufacturers lacking forward contracts.
- Polyester:Petroleum-derived synthetic dominating mass-market production through supply security and moisture-wicking properties. Chinese GB standard compliance adds certification layers for imported finished goods.
- Nylon:High-tenacity polymer preferred for abrasion-resistant outer shells in performance-oriented designs.
- Wool:Premium natural insulation commanding margin premiums in Nordic markets and northern United States cold-climate applications.
Volume leadership sits with Polyester. Wool captures the steepest pricing power trajectory.
Size:
SKU proliferation intensity peaks in this dimension, as absence of universal canine measurement protocols forces retailers to stock breed-specific inventory.
- Small:Apparel designed for dogs under 25 pounds including Chihuahuas, Yorkshire Terriers, and French Bulldogs. Urban United States multi-pet households drive the highest replenishment frequency in this tier.
- Medium:Mid-weight garments fitting 25-50 pound breeds including Beagles, Cocker Spaniels, and Border Collies. This segment captures the broadest breed coverage and inventory turnover efficiency.
- Large:Outerwear for 50-90 pound working and sporting breeds requiring reinforced construction.
- Extra Large:Specialized patterns for giant breeds above 90 pounds with limited manufacturer participation due to low addressable volume.
Inventory investment concentrates in Medium. Customer acquisition costs run highest in Extra Large.
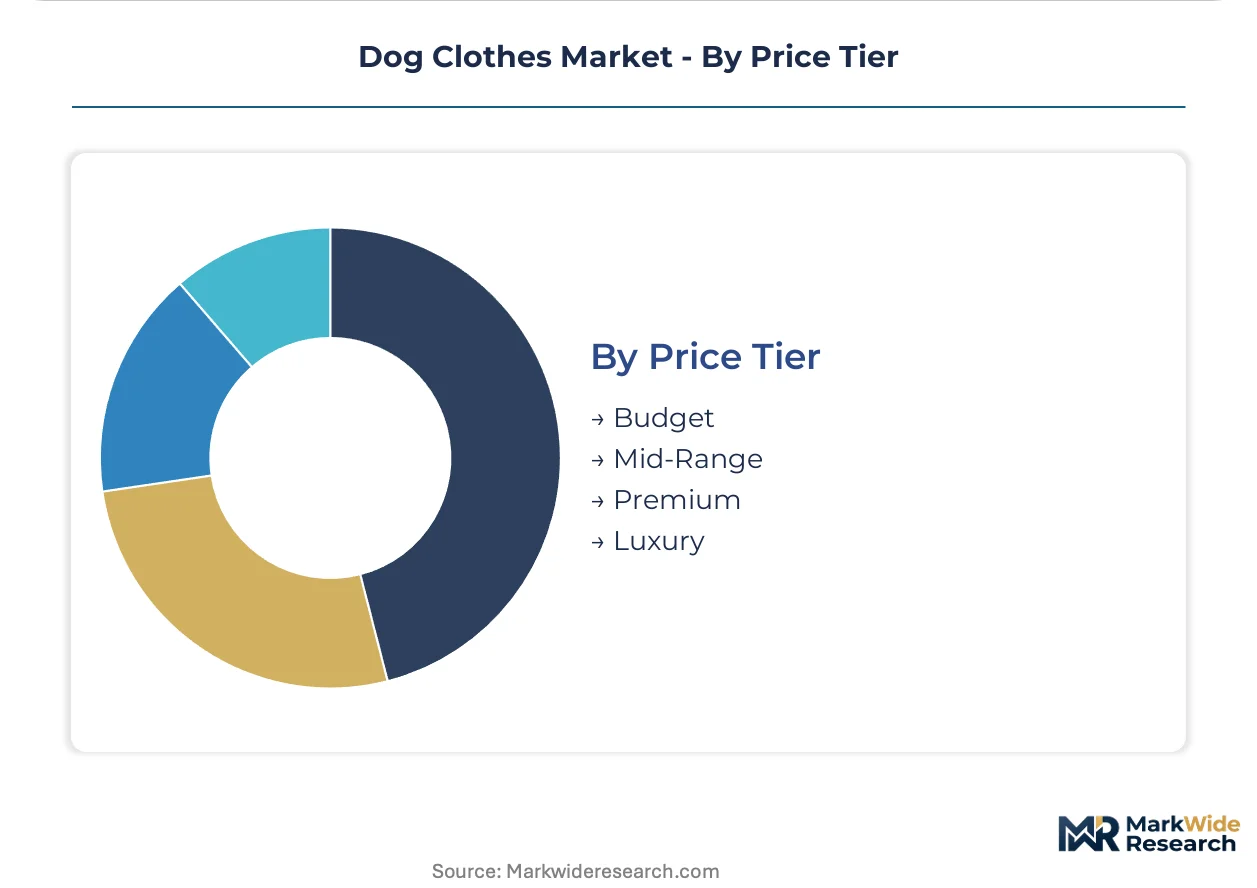
Price Tier:
Margin architecture stratifies sharply, with luxury segments capturing disproportionate profit pools through scarcity engineering and designer collaborations.
- Budget:Entry-level polyester and basic cotton constructions sold through mass-market retail and online marketplaces. Cotton price volatility directly threatens unit economics in this tier.
- Mid-Range:Balanced quality-positioning incorporating branded hardware and modest technical features. This tier absorbs the most competitive pressure from direct-to-consumer private labels.
- Premium:Technical performance fabrics with OEKO-TEX Standard 100 certification and weatherproof engineering. European retail buyers increasingly mandate supply chain documentation at this threshold.
- Limited-Edition Luxury:Designer collaborations and artisanal constructions with restricted production runs. CSRD sustainability disclosure requirements are accelerating procurement preference for transparent documentation in this tier.
Revenue volume flows through Mid-Range. Margin expansion is steepest in Limited-Edition Luxury.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting manufacturing footprints as REACH compliance expenses in Europe push production toward lower-burden zones. Manufacturers now arbitrage between US CPSC testing requirements, EU chemical disclosure mandates, and Chinese GB standard layers to optimize landed costs.
United States
Millennial and Gen Z pet owners in New York, Los Angeles, and Chicago drive seasonal wardrobe replenishment for companion animals. The US Consumer Product Safety Commission enforces flammability standards for pet textiles that extend product development timelines. Pacific Northwest metropolitan clusters including Seattle and Portland accelerate bonded waterproof raincoat adoption for year-round walkability.
Germany
ECHA-administered REACH chemical safety requirements reshape material sourcing for premium retailers seeking OEKO-TEX Standard 100 validation. The EU's Corporate Sustainability Reporting Directive mandates supply chain transparency disclosures that favor manufacturers with documented fiber origins. Bavarian and North Rhine-Westphalian retail buyers increasingly filter procurement through sustainability documentation thresholds.
China
GB standards for textile safety and labeling create compliance layers for manufacturers sourcing from or selling into the domestic manufacturing base. The Ministry of Ecology and Environment enforces dual carbon goals that elevate carbon intensity tracking requirements. Yangtze River Delta and Pearl River Delta production clusters face extended certification timelines as multi-jurisdiction testing protocols proliferate.
United Kingdom
London and Southeast England concentrate discretionary spending on limited-edition designer collaborations in the luxury tier. Post-Brexit regulatory divergence from EU REACH frameworks creates parallel compliance tracks for UK-bound shipments. Midlands-based distributors manage SKU complexity from fragmented size standardization across breed-specific requirements.
Canada
Toronto and Vancouver urban households normalize technical outerwear for winter walkability in sub-zero conditions. Health Canada and PMRA administer chemical safety standards that align partially with US CPSC frameworks but retain distinct testing protocols. Prairie Provinces cold-climate demand concentrates margin premiums for wool blend thermal insulation measured in grams per square meter.
Dog Clothes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer channels disintermediating traditional retail gatekeepers in mid-range and premium tiers. The vendor base organizes around three strategic archetypes: technical performance specialists, fashion-forward lifestyle brands, and private-label contract manufacturers serving mass-market retailers. Consolidation pressure concentrates among mid-tier players facing margin compression from cotton price volatility and seasonal demand compression. Dominant competitive moves include backward integration into certified material sourcing and subscription-based customer lifetime value capture.
Within the technical performance tier, Ruffwear and Hurtta exemplify engineering-driven positioning built around weatherproof standards and outdoor activity specialization. Canada Pooch occupies a direct-to-consumer position controlling pricing and brand narrative across North American metropolitan markets. TRIXIE Heimtierbedarf GmbH & Co. KG represents European-based fabrication serving multi-channel distribution with compliance-ready documentation for REACH and OEKO-TEX procurement filters.
| Leading Market Players |
|---|
| Canada Pooch |
| Moshiqa |
| Ruffwear |
| Milk & Pepper |
| PetRageous Designs |
| Hurtta |
| Bitch New York |
| TRIXIE Heimtierbedarf GmbH & Co. KG |
| Weatherbeeta |
| Others |
Value Network & Pricing Analysis
Urban multi-dog households in dense United States metropolitan clusters anchor the dominant subscription-based pricing model, locking in recurring revenue streams that buffer manufacturers against seasonal demand compression. This buyer concentration forces mid-tier producers toward direct-to-consumer channels or private-label contract arrangements to escape margin erosion.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for polyester-based budget tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by OEKO-TEX Standard 100 certification status and bonded waterproof membrane integration. Cost compression in cotton-dependent mid-range segments is intensifying because commodity exchange volatility lacks forward-contract hedging. Budget-tier mass-market buyers exhibit highest price sensitivity, while limited-edition luxury purchasers show near-zero elasticity.
Supply Chain Analysis
Skilled textile workforce availability in Yangtze River Delta and Pearl River Delta manufacturing zones anchors production concentration for bonded waterproof lamination equipment. Raw material inputs draw from petroleum-derived polyester fiber, natural cotton bales, and merino wool imports from Australia. Single-source vulnerability concentrates in Chinese GB standard-certified dye houses serving multiple brand clients. Distribution runs through direct-to-consumer platforms, pet specialty retail chains, and mass-market big-box channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA-administered REACH chemical safety milestones and EU CSRD sustainability disclosure mandates are accelerating procurement preference for documented supply chain transparency.
For Market Incumbents: Deploy backward integration into OEKO-TEX Standard 100 certified material sourcing to defend against private-label contract manufacturers capturing mid-range share. Lock in multi-year fiber origin documentation to satisfy European retail buyer CSRD filtering. Channel control through proprietary fit-prediction algorithms preserves customer lifetime value against episodic seasonal purchasing. For New Entrants and Emerging Players: Enter via wool blend thermal insulation specialization for Nordic and northern United States cold-climate applications where incumbent technical performance coverage is thin. Target extra-large breed segments where SKU complexity deters established players and customer acquisition costs run highest. Launch through subscription replenishment platforms with size-adjusted seasonal algorithms. For Investors and Strategic Acquirers: Direct-to-consumer pet apparel specialists with captive fit-technology are the most active acquirer targets in this space. Five-to-ten year viability hinges on regulatory compliance infrastructure amortization across multi-jurisdiction certification timelines. Monitor cotton futures contract coverage ratios as inflection indicator for margin stress in commodity-exposed manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Material Sourcing | OEKO-TEX Standard 100 documentation satisfies ECHA REACH procurement filters for European retail buyers. |
| Subscription Replenishment Platform Launch | Recurring revenue models capture urban United States multi-dog household lifetime value from traditional retailers. |
| Bonded Waterproof Membrane Capacity Addition | Pacific Northwest metropolitan demand for year-round walkability outstrips basic polyester shell supply. |
| Direct-to-Consumer Channel Expansion | Proprietary fit-prediction algorithms disintermediate pet specialty retail gatekeepers in mid-range tiers. |
| Sustainability Documentation Investment | CSRD-aligned fiber origin tracking creates procurement preference among European premium retail buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at direct-to-consumer apparel platforms, category buyers at pet specialty retail chains, supply planners at contract manufacturers, and technical R&D directors at waterproof membrane suppliers with secondary validation against customs textile trade data, SEC apparel retailer filings, and OEKO-TEX certification registries. Bottom-up SKU-level demand modeling and top-down macroeconomic consumption indicators were triangulated for convergence.
Segment-weighted analytical frameworks applied product type, material composition, size tier, and price positioning dimensions across the projection horizon. CAGRs were derived from fitted growth curves incorporating pet ownership demographic shifts, seasonal wardrobe rotation normalization rates, and multi-jurisdiction compliance cost escalations. Industry-specific inputs included cotton futures volatility indices and bonded waterproof technology adoption curves in Pacific Northwest metropolitan clusters.
Inputs from brand manager interviews and certification database records were available through the study window; gaps in real-time SKU-level sell-through data from direct-to-consumer platforms introduce uncertainty bands around replenishment frequency assumptions. Practitioners should monitor ECHA REACH enforcement intensity and cotton commodity exchange volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Supplement Market
Pet Care Products
UK Dog Food Market
Pet Care Products
Cat Litter Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Pet Food Market
Pet Care Products
Toy Dog Market
Pet Care Products
Interactive Dog Toys Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Robotic Pets Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Dog Vest Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
Cat Condos and Indoor Houses Market
Pet Care Products
Global Cat Trees and Towers Market