
 OEM Shoe Manufacturer Service Market | 2026-2036
OEM Shoe Manufacturer Service Market Size, Share, and Industry Trends Forecast 2026-2036
OEM Shoe Manufacturer Service Market Insights
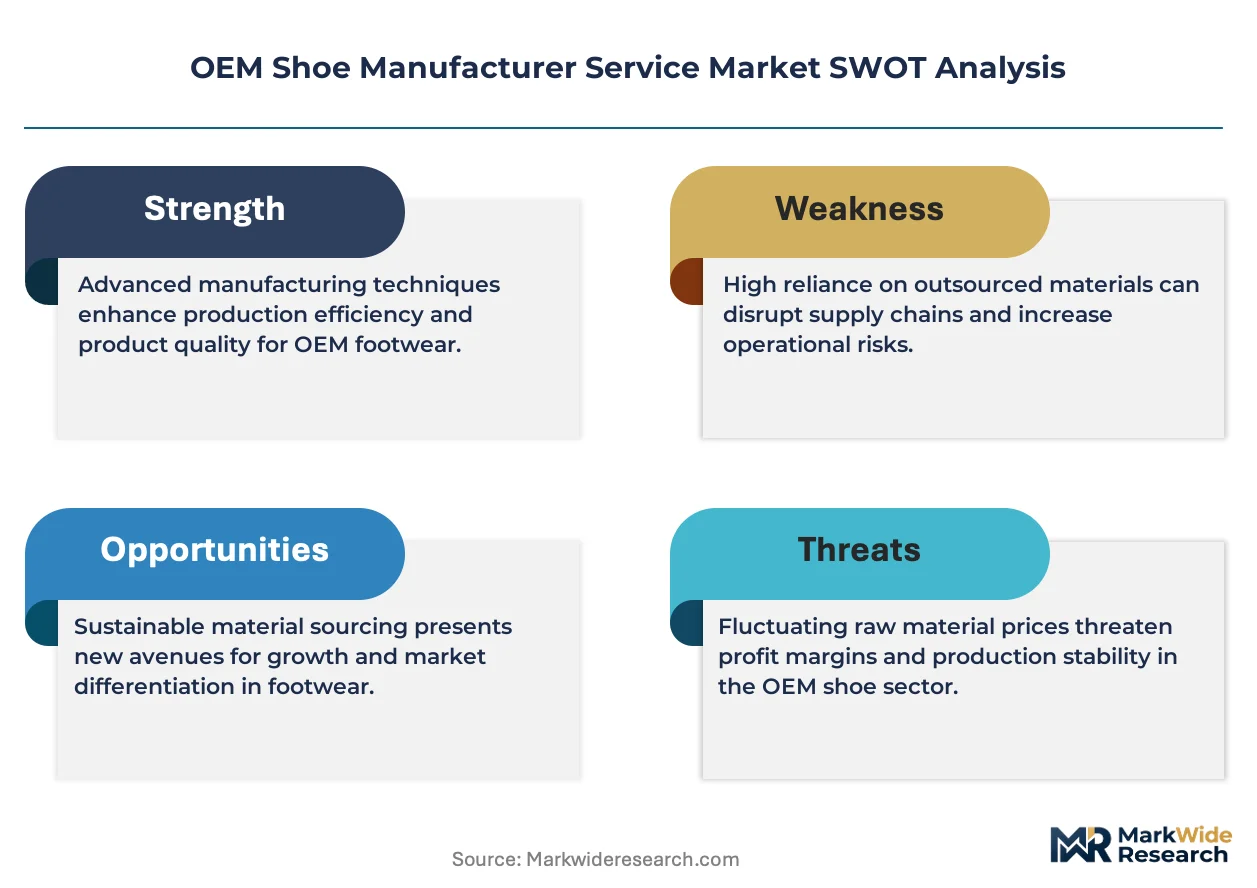
The gap between premium and commodity tiers is shifting from brand positioning into manufacturing capability itself. Pou Chen Corporation anchors high-volume sports production through integrated material science labs and captive rubber compounding facilities. Yue Yuen Industrial Holdings differentiates via geographic diversification across Vietnam, Indonesia, and India, reducing single-country exposure. Taekwang Industrial specializes in automated lasting and cementing lines that serve mid-tier fashion brands seeking cost predictability.
OEM shoe manufacturer services encompass the full outsourced production cycle from pattern engineering and last development through cutting, stitching, lasting, and finishing, typically governed by buyer-specified upper materials, sole hardness measured in Shore A durometer, and adhesion strength thresholds. The primary purpose is enabling brand owners to scale footwear output without capital-intensive factory ownership or direct labor management. Production capacity segmentation reveals that high-volume contracts concentrate margin pools among vertically integrated operators with captive outsole molding, while custom orders and low-volume prototyping are gravitating toward agile manufacturers in Portugal and Mexico that serve nearshoring fashion brands. Material segmentation shows synthetic uppers and recycled rubber compounds gaining specification share as sports brands enforce sustainability scorecards.
REACH restricts phthalate plasticizers and chromium VI in leather tanning across European-bound production, compelling manufacturers to certify chemical management systems through third-party audits. EPA TSCA Section 6 rules on per- and polyfluoroalkyl substances are eliminating water-repellent chemistries from US-market footwear, forcing reformulation of synthetic upper treatments. Stakeholders must monitor how dual carbon targets in China and extended producer responsibility laws in France reshape factory energy sourcing and end-of-life collection obligations.
Market Dynamics
Speed-to-market imperatives are compressing development cycles from 18 months to 8-10 weeks, forcing OEM manufacturers to reconfigure pattern engineering and last development workflows around rapid sampling capabilities rather than traditional seasonal production calendars.
Growth Catalysts
- REACH Phase-Out of Chromium VI:European-bound leather tanning is pivoting toward vegetable-tanned and metal-free alternatives, creating specification demand for certified chemical management systems that compliant OEMs can capture.
- Automated Lasting Lines:Robotics-enabled cementing and lasting equipment is reducing labor dependency in high-volume sports production, allowing manufacturers to absorb demand spikes without proportional workforce expansion.
- Vietnam Production Absorption:Brands diversifying beyond legacy Chinese clusters are redirecting volume toward Vietnamese facilities with established outsole molding and captive rubber compounding infrastructure.
Market Restraints
- Petroleum-Derived Synthetic Pricing:TPU and PU upper material costs fluctuate with crude oil indices, compressing margin predictability for manufacturers locked into fixed-price annual contracts.
- Single-Country Exposure Limits:Concentrated production in Vietnam creates vulnerability to typhoon disruptions and electricity rationing events that halt multi-factory operations simultaneously.
- Adhesion Chemistry Reformulation:EPA TSCA Section 6 restrictions on PFAS-based water repellents eliminate proven synthetic upper treatments, forcing performance degradation or costly fluorine-free alternatives.
Strategic Opportunities
- Portuguese Agile Manufacturing:Nearshoring fashion brands seeking sub-500 unit prototyping runs are gravitating toward Porto and Felgueiras facilities with digital pattern-to-sample workflows.
- Extended Producer Responsibility:France's mandatory footwear take-back schemes create service revenue streams for OEMs offering end-of-life collection and material recovery logistics.
- Digital-Physical Convergence:3D foot scanning combined with AI-generated last libraries is compressing fit trial iterations from weeks to days for custom performance brands.
Industry Challenges
- Pattern Engineering Talent Scarcity:Experienced last developers and grading technicians command premium wages in Vietnam and Indonesia as training pipelines fail to match automation deployment rates.
- Dual Certification Burden:Manufacturers serving both European and US markets must maintain parallel chemical testing protocols for REACH and EPA compliance, doubling laboratory audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OEM Shoe Manufacturer Service Market |
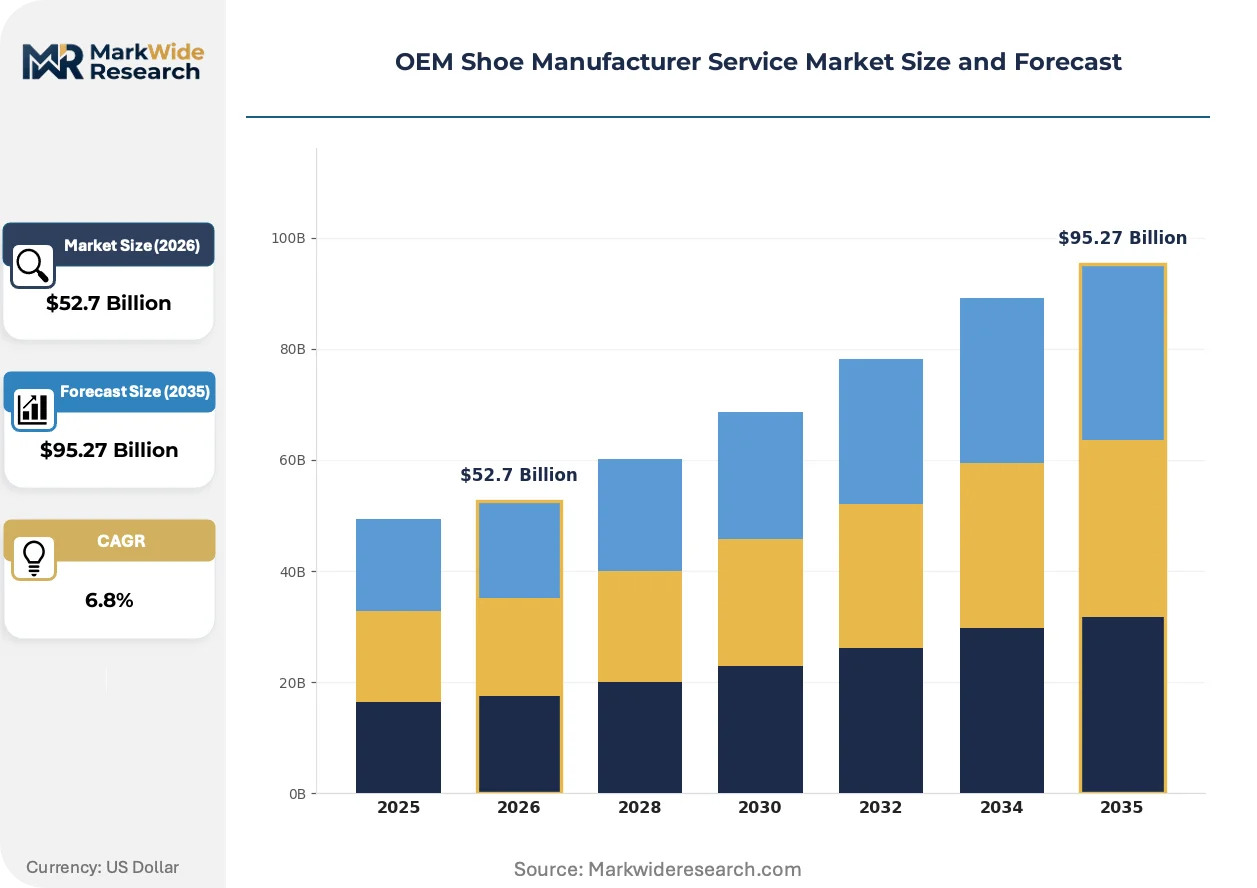
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Prototyping, Production, Quality Assurance Material: Leather, Synthetic, Rubber, Fabrics Target Market: Fashion Brands, Sports Brands, Retail Chains, E-commerce Platforms Production Capacity: Low Volume, Medium Volume, High Volume, Custom Orders |
| Companies Covered | Pou Chen Corporation, Yue Yuen Industrial Holdings, Taekwang Industrial, Baocheng International Group, PAN Group, Saiqi Sports, Ching Luh Group, OLICOM Shoes, XUJUN Shoes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OEM Shoe Manufacturer Service Market Trends and Innovations
Manufacturing capability itself is becoming the primary competitive differentiator as brands outsource not merely labor but material science, sustainability certification, and regional logistics orchestration to specialized OEM partners.
Digital twin technology is integrating physical factory workflows with virtual simulation environments. Sports brands now require OEM partners to provide 3D-rendered sample validation before cutting physical materials, compressing approval cycles. This capability gap is separating technology-enabled manufacturers from commodity assemblers.
EPA TSCA Section 6 rules on per- and polyfluoroalkyl substances are eliminating water-repellent chemistries from US-market footwear. Manufacturers serving American-bound production must reformulate synthetic upper treatments with fluorine-free alternatives or risk shipment rejection. The transition timeline is compressing reformulation investment into 18-month windows.
Brand procurement departments are consolidating vendor lists from 40-plus suppliers to 8-12 strategic manufacturing partners capable of delivering integrated material science, regional agility, and sustainability scorecard compliance. This concentration favors vertically integrated OEMs with captive outsole molding and certified chemical management systems over pure assembly operators.
OEM Shoe Manufacturer Service Market Segmentation
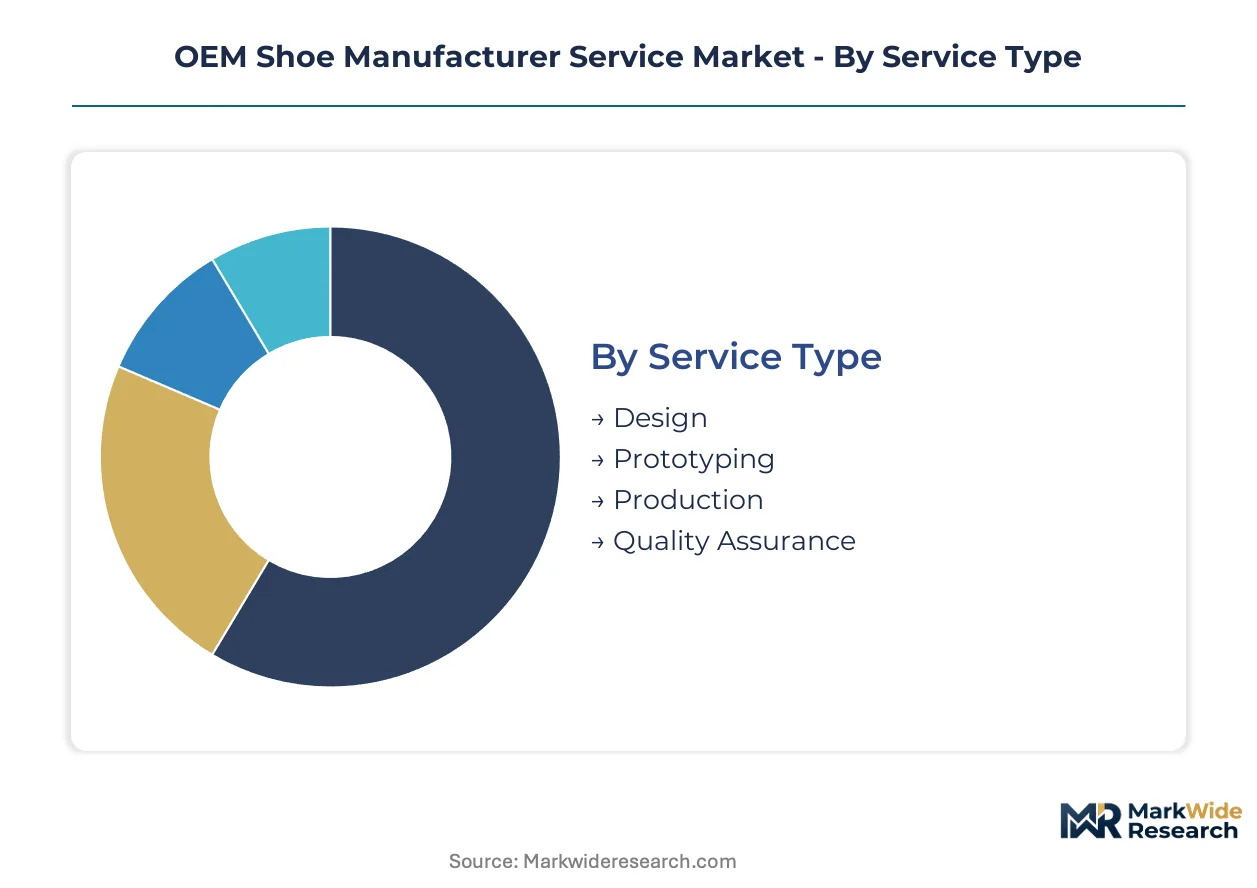
OEM shoe manufacturing services fragment across technical capability tiers and volume thresholds. Brand procurement teams select manufacturing partners based on where their product portfolio sits between rapid prototyping agility and mass-production scale.
Service Type:
Customization intensity varies sharply across this spectrum, from fully bespoke pattern engineering to standardized quality protocols.
- Design:Pattern engineering and last development services command premium positioning as sports brands compress development cycles. Demand concentrates among Vietnamese and Indonesian facilities investing in 3D scanning and AI-generated last libraries to serve performance footwear brands.
- Prototyping:Rapid sample production with digital-to-physical workflows enables sub-500 unit validation runs. Portuguese manufacturers in Porto and Felgueiras capture nearshoring fashion brands requiring speed-to-market over unit economics.
- Production:Full-scale manufacturing from cutting through finishing represents the volume core of OEM services.
- Quality Assurance:Third-party certification and chemical testing services address REACH and EPA TSCA compliance requirements.
Leading the category by volume: Production. Expanding most quickly: Prototyping.
Material:
Cost structures and regulatory compliance burdens diverge substantially across input categories.
- Leather:Vegetable-tanned and metal-free alternatives are displacing chromium VI processes under ECHA REACH Phase-Out mandates. Italian and Portuguese tanneries capture specification demand from European-bound luxury and fashion brands.
- Synthetic:TPU and PU upper materials dominate sports footwear but face margin pressure from petroleum price volatility. Manufacturers locked into fixed-price annual contracts absorb cost fluctuations.
- Rubber:Recycled compounds gain specification share as brands enforce sustainability scorecards.
- Fabrics:Knitted and woven textile uppers serve performance running and lifestyle categories.
Dominant by procurement volume: Synthetic. Steepest specification shift: Leather.
Target Market:
Customer type determines capability requirements across speed, certification, and geographic proximity.
- Sports Brands:Technical performance demands and compressed development cycles require integrated material science labs and captive rubber compounding. Vietnamese facilities with automated lasting lines absorb rising volume from brands diversifying beyond legacy Chinese clusters.
- Fashion Brands:Seasonal velocity and aesthetic flexibility prioritize agile manufacturing and nearshoring options. Mexican and Portuguese OEMs serve sub-500 unit prototyping with digital pattern-to-sample workflows.
- Retail Chains:Private-label programs demand cost predictability and scale consistency.
- E-commerce Platforms:Direct-to-consumer brands require flexible minimum order quantities and rapid replenishment.
Highest contract value concentration: Sports Brands. Fastest customer acquisition: E-commerce Platforms.
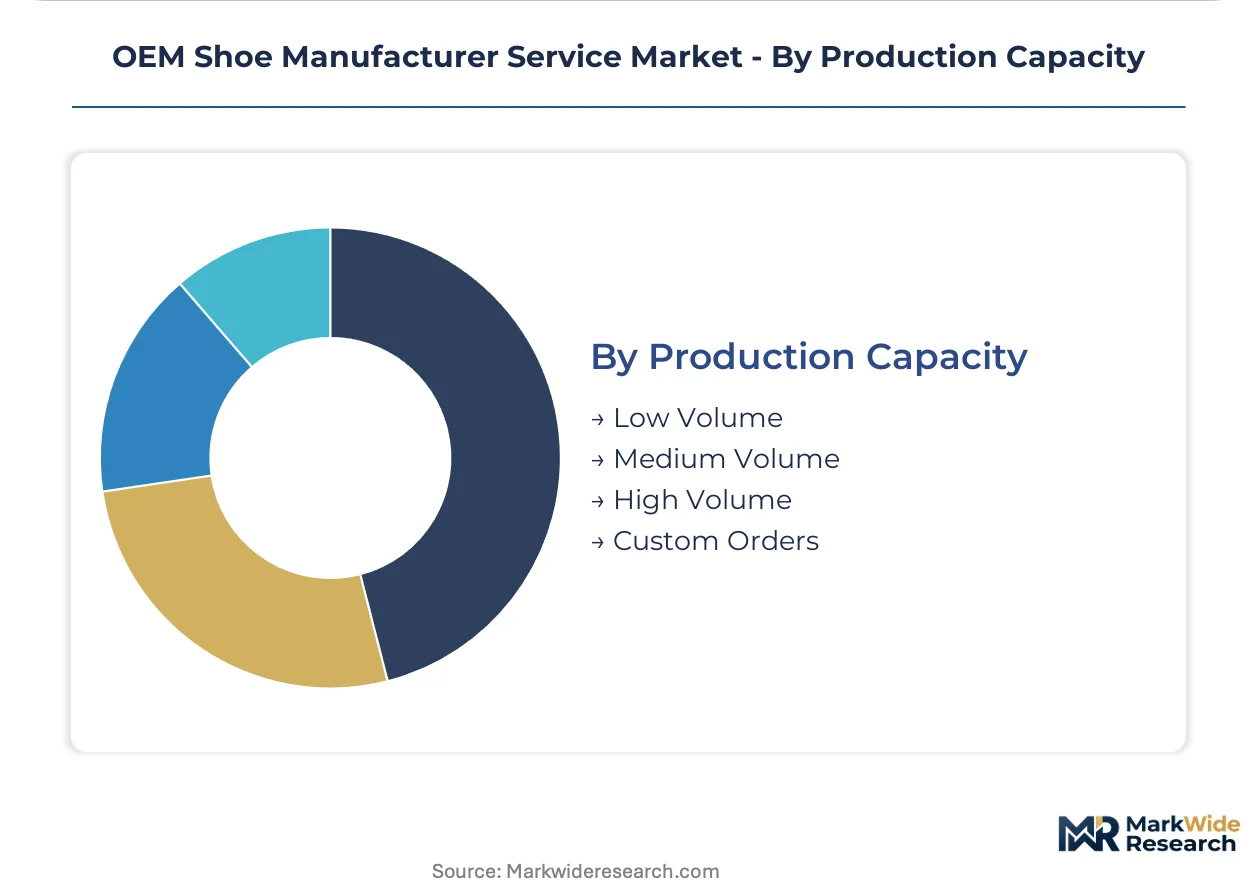
Production Capacity:
Volume segmentation maps directly to factory infrastructure investment and labor configuration.
- High Volume:Automated cementing and lasting equipment reduces labor dependency for sports production. Vertically integrated operators with captive outsole molding capture margin pools as brand procurement consolidates vendor lists.
- Custom Orders:Low-volume, specification-heavy production gravitates toward agile manufacturers. Portuguese and Mexican facilities serve nearshoring brands with rapid sampling capabilities rather than seasonal production calendars.
- Medium Volume:Balanced automation and manual assembly serves mid-tier fashion brands.
- Low Volume:Manual-intensive production accommodates niche and emerging brand requirements.
Revenue concentration leader: High Volume. Gaining share fastest: Custom Orders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan anchors the world's densest concentration of footwear OEM capacity, with integrated outsole molding and automated lasting corridors serving sports brands that have diversified beyond this legacy cluster into Vietnam and Indonesia.
Vietnam
Ho Chi Minh City and Binh Duong Province absorb rising volume from brands exiting legacy Chinese manufacturing, with facilities investing in captive rubber compounding and automated cementing lines. ECHA REACH compliance requirements for European-bound production drive certification demand at third-party laboratories in the region. The Dong Nai industrial corridor concentrates high-volume sports production for Nike and Adidas procurement teams.
Indonesia
Java's footwear belt around Jakarta and Bandung captures diversification flows seeking lower labor costs than Vietnam, particularly for mid-tier fashion brands. The country's national industrial regulator enforces chemical safety standards aligned with export market requirements. The Tangerang manufacturing zone hosts facilities with integrated material science labs serving performance footwear specifications.
China
Dongguan and Putian retain premium technical capacity for complex performance uppers and rapid prototyping despite volume migration southward. MEE dual carbon targets reshape factory energy sourcing in Guangdong Province, accelerating solar installation and grid decarbonization mandates. The Jinjiang cluster in Fujian Province maintains specialized strength in automated lasting equipment and digital pattern engineering workflows.
Portugal
Porto and Felgueiras serve nearshoring fashion brands with sub-500 unit prototyping runs and digital-to-physical sample workflows. EU Green Deal extended producer responsibility frameworks create service revenue opportunities for end-of-life collection logistics. The Norte Region concentrates agile manufacturers with 3D scanning capabilities that compress fit trial iterations from weeks to days.
Mexico
Guadalajara and León attract North American brands seeking tariff-advantaged production and compressed shipping lanes versus Asian origins. EPA TSCA Section 6 restrictions on PFAS-based water repellents force reformulation of synthetic upper treatments for US-market output. The Guanajuato footwear corridor develops rapid sampling capabilities to serve direct-to-consumer brands with flexible minimum order quantities.
OEM Shoe Manufacturer Service Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where vertically integrated operators capture margin pools while specialized assemblers fight for commodity contracts. The vendor base concentrates among three strategic archetypes: integrated material science operators with captive outsole molding, geographic diversifiers with multi-country footprints, and agile specialists serving nearshoring prototyping demand. Dominant competitive moves include backward integration into rubber compounding and synthetic upper production, plus strategic partnerships with brands for co-developed sustainability scorecards.
Among Taiwan-based integrated operators, Pou Chen Corporation and Yue Yuen Industrial Holdings exemplify the scale-driven archetype with multi-facility networks spanning Vietnam, Indonesia, and India. Taekwang Industrial occupies a position within the automation-specialist tier, representing manufacturers that have invested in robotics-enabled cementing and lasting lines to reduce labor dependency. These three entities anchor the competitive structure through their respective emphases on geographic diversification, vertical integration, and automated production workflows.
| Leading Market Players |
|---|
| Pou Chen Corporation |
| Yue Yuen Industrial Holdings |
| Taekwang Industrial |
| Baocheng International Group |
| PAN Group |
| Saiqi Sports |
| Ching Luh Group |
| OLICOM Shoes |
| XUJUN Shoes |
| Others |
Pricing and Supply Chain Analysis
Skilled last developers concentrated in Vietnam's Dong Nai corridor and Indonesia's Tangerang zone command premium wages that widen pricing spreads between automated high-volume sports production and manual-intensive fashion runs.
Pricing Analysis
Outcome-based pricing tied to on-time delivery rates and defect-free throughput anchors contract structures for sports brands with compressed development cycles. Three-tier pricing structure across premium, standard, and economy levels separates vertically integrated operators with captive rubber compounding from pure assembly contractors. Pricing pressure stems from petroleum-derived TPU and PU cost volatility that manufacturers locked into fixed-price annual contracts must absorb. Retail chains and private-label programs exhibit highest price sensitivity, while performance sports brands prioritize certification compliance and speed-to-market over unit economics.
Supply Chain Analysis
TPU pellet supply rests on petrochemical producers in South Korea, Taiwan, and Thailand, with specialty grades for footwear applications requiring qualified supplier relationships. Chromium-free leather tanning chemicals draw from Italian and Portuguese specialty chemical houses, while recycled rubber compounds source from certified reclaim facilities in Vietnam and Indonesia. Single-country concentration in Vietnam creates typhoon and electricity rationing vulnerability that disrupts multi-factory operations simultaneously. Distribution runs through brand-controlled consolidation centers in destination markets rather than manufacturer-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated lasting and cementing robotics are displacing manual assembly workflows, compressing the technology-transition window for manufacturers to reconfigure labor-dependent operations.
For Market Incumbents: To counter margin compression from petroleum-derived synthetic pricing volatility, backward integration into captive rubber compounding secures supply stability and cost predictability. Capacity expansion across Indonesian facilities diversifies single-country exposure while capturing mid-tier fashion brand volume migrating from legacy Chinese clusters.
For New Entrants and Emerging Players: The pricing gap between Portuguese agile prototyping and Vietnamese mass production creates entry space for Mexican facilities serving North American direct-to-consumer brands with sub-500 unit minimums and rapid replenishment cycles. Target Guanajuato corridor positioning with digital pattern-to-sample workflows and EPA TSCA-compliant fluorine-free treatment capabilities.
For Investors and Strategic Acquirers: Re-rating potential sits with automation-enabled mid-tier specialists given procurement consolidation from 40-plus suppliers to 8-12 strategic partners. Long-term viability favors manufacturers with integrated material science labs and multi-country footprints. Watch brand sustainability scorecard enforcement as inflection indicator for certified chemical management system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive outsole molding secures margin pools as procurement consolidates vendor lists. |
| Automated Lasting Line Deployment | Robotics-enabled cementing reduces labor dependency for demand spike absorption. |
| Multi-Country Geographic Expansion | Vietnam-Indonesia-India footprints mitigate typhoon and electricity rationing risks. |
| REACH and EPA Dual Certification Investment | Parallel chemical testing protocols capture European and US-bound production contracts. |
| Digital Pattern-to-Sample Workflow Implementation | 3D scanning and AI-generated last libraries compress fit trial iterations for fashion brands. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with footwear brand procurement directors, OEM factory operations managers, chemical compliance auditors, and logistics coordinators at consolidation centers. ECHA REACH substance restriction databases, EPA TSCA Section 6 rulemaking dockets, Vietnam Ministry of Industry and Trade export statistics, and Indonesian industrial zone authority reports provided validation benchmarks. Bottom-up facility capacity assessments and top-down brand procurement spend estimates were triangulated to calibrate market sizing.
Segment-level modeling tracked service type, material category, target customer archetype, and production capacity tier across the projection horizon. CAGRs derived from volume trajectory analysis incorporating brand diversification patterns, automation deployment rates, and regulatory compliance cost pass-through assumptions. Footwear brand vendor consolidation trends and sustainability scorecard adoption curves informed growth allocation across manufacturing capability tiers.
Inputs from Vietnamese and Indonesian factory associations were available through the study window; gaps in proprietary brand procurement spend data introduce uncertainty bands around customer segment splits. Forecasts reflect assumptions on automation deployment timelines and regulatory enforcement intensity. Typhoon frequency, petroleum price volatility, and dual carbon target acceleration in China warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Slip Resistant Shoes Market
Footwear
High Heels Footwear Market
Footwear
Refurbished Running Shoes Market
Footwear
Womens Footwear Market
Footwear
Sports Footwear Market
Footwear
Casual Shoes Market
Footwear
Global Recovery Footwear Market
Footwear
North America Footwear Market
Footwear
Snow Boots for Women Market
Footwear
Gypsy Jazz Shoes Market
Footwear
North America Athletic Footwear Market
Footwear
Leather Footwear Market
Footwear
US Slip Resistant Shoes Market
Footwear
Flip Flops Market
Footwear
Platform Boots Market
Footwear
Premium Shoes Market