
 Saudi Arabia Dog Food Market | 2026-2036
Saudi Arabia Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Dog Food Market Intelligence
The gap between premium nutrition and commodity feeding is realigning product portfolios across Saudi Arabia. Mars Incorporated leverages its global R&D infrastructure to sustain shelf dominance in hypermarkets and pet specialty channels. Nestle SA anchors its position through Purina-branded formulations that compete on protein specificity and palatability benchmarks. Royal Canin differentiates via veterinary-endorsed breed-specific lines that command premium positioning in Riyadh and Jeddah clinics.
Dog food encompasses formulated nutritional products manufactured through extrusion, canning, or freeze-drying processes, with macronutrient profiles typically specifying crude protein minimums between 18% and 32% depending on life-stage targeting. Dry food occupies the volume core due to storage convenience and lower per-kilogram logistics costs across Saudi Arabia's distributed retail network. Wet food captures margin concentration among urban pet owners seeking hydration-integrated feeding solutions. Functional ingredient types, spanning probiotics and joint-support additives, represent the fastest-expanding margin pool as veterinary clinics endorse therapeutic nutrition.
SFDA and the Saudi Food and Drug Authority regulate imported pet food through ingredient safety protocols and label compliance requirements that shape market access for international suppliers. The General Authority for Food and Drug Administration enforces halal-adjacent sourcing standards that influence protein ingredient selection and supplier qualification processes. Stakeholders must monitor evolving feed-grade versus food-grade classification debates that could recalibrate import duty structures and domestic manufacturing incentives.
Market Dynamics
SFDA tightening on imported pet food ingredients is compressing supplier qualification timelines while veterinary clinics in Riyadh and Jeddah amplify therapeutic nutrition prescriptions. This regulatory-demand convergence is restructuring procurement priorities across Saudi Arabia's distributed retail network.
Growth Catalysts
- Disposable income expansion:Urban households in Riyadh and Jeddah are reallocating expenditure toward premium formulations with elevated protein specificity and functional additives.
- SFDA safety protocols:Enhanced label compliance requirements for imported pet food are elevating quality benchmarks that favor established suppliers with documented supply chain transparency.
- Veterinary channel endorsement:Breed-specific and therapeutic nutrition lines receive prescriptive support from clinical networks, creating pull-through demand in metropolitan corridors.
Market Restraints
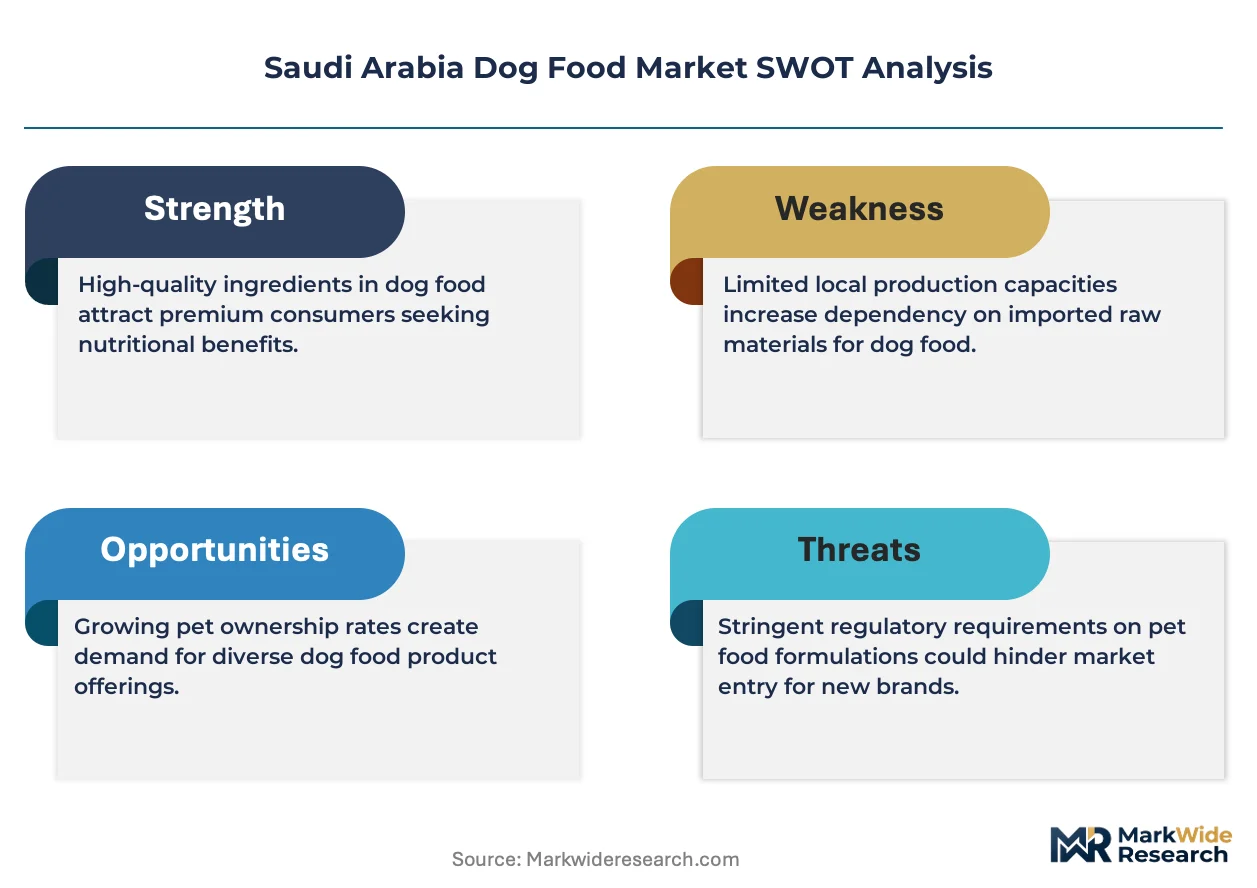
- Import dependency concentration:Heavy reliance on European and North American suppliers exposes distributors to shipping cost volatility and currency fluctuation risks.
- Halal-adjacent sourcing friction:Protein ingredient selection faces qualification constraints under General Authority for Food and Drug Administration standards, limiting supplier pools.
- Feed-grade classification ambiguity:Ongoing debates over feed-grade versus food-grade categorization threaten to recalibrate import duty structures and erode margin predictability.
Strategic Opportunities
- Eastern Province penetration:Dammam and Khobar exhibit underdeveloped pet specialty retail density relative to Riyadh, presenting whitespace for clinic-anchored distribution.
- E-commerce subscription models:Direct-to-consumer platforms with automated replenishment are capturing urban pet owners seeking convenience and formulation consistency.
- Freeze-dried raw convergence:Cold-chain logistics improvements are enabling premium raw nutrition formats previously constrained by storage limitations in Saudi Arabia's climate.
Industry Challenges
- Veterinary nutritionist scarcity:Qualified professionals capable of endorsing therapeutic formulations remain concentrated in Riyadh and Jeddah, constraining clinical channel expansion.
- SFDA registration timelines:Extended product approval cycles for novel functional ingredients delay market entry and compress innovation return windows.
- Cold-chain capex requirements:Wet food and fresh format distribution demands refrigerated logistics infrastructure that hypermarket partners are slow to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Dog Food Market |
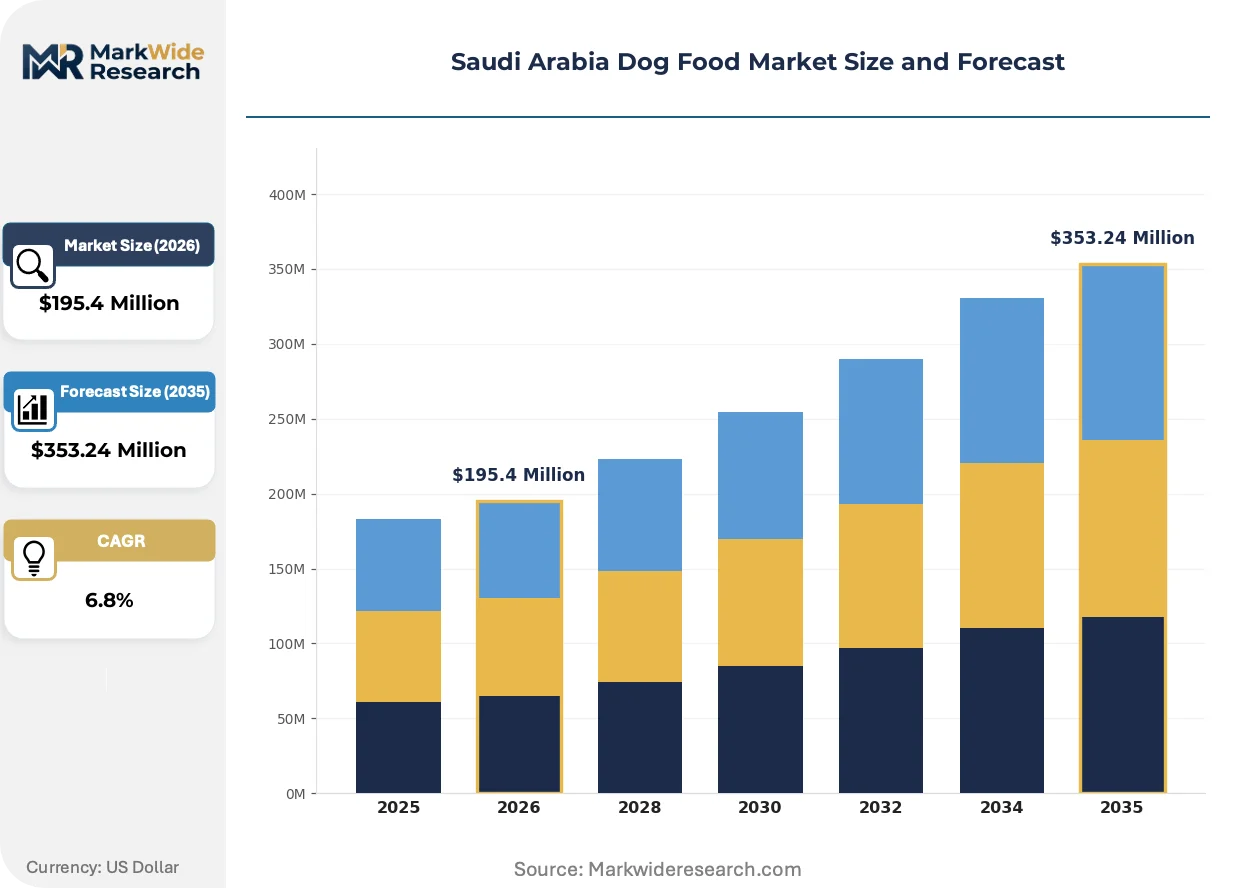
| Market Size in 2026 | $195.4 Million |
| Market Size in 2035 | $353.24 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food End User: Pet Owners, Kennels, Veterinary Clinics, Shelters Ingredient Type: Meat-Based, Grain-Free, Organic, Functional Distribution Channel: Online Retail, Supermarkets, Pet Stores, Wholesale |
| Companies Covered | Mars Incorporated, Nestle SA, Colgate-Palmolive Company, Royal Canin, JM Smucker Co, General Mills, Bayt Al Aleefa, Delicious Food Factory, Hills Pet Nutrition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Dog Food Market Strategic Shifts & Innovations
Formulation science and channel architecture are undergoing parallel transformation as Saudi pet owners demand precision nutrition and frictionless replenishment. Three developments are restructuring competitive positioning across the Kingdom.
Cold-pressed and minimally processed kibble is integrating gentle thermal treatment that preserves amino acid bioavailability while achieving shelf stability. Premium-focused breeders and show-dog handlers in Riyadh are adopting these formats at accelerated pace. This processing shift is integrating artisanal positioning into mass-market distribution, compressing the traditional premium-commodity divide.
SFDA's evolving stance on novel ingredient notifications is tightening documentation requirements for probiotic strains and botanical additives. Manufacturers must now submit comprehensive safety dossiers before label claims receive approval. Therapeutic nutrition segments face the steepest compliance burden, with veterinary-exclusive lines requiring extended pre-market validation cycles.
Subscription-based replenishment through pet specialty apps is displacing episodic hypermarket purchasing among dual-income households. Automated delivery locks in formulation loyalty while reducing stockout frequency. Jeddah's coastal urban districts exhibit the highest adoption velocity, where time-constrained professionals prioritize convenience over price comparison.
Saudi Arabia Dog Food Market Segmentation
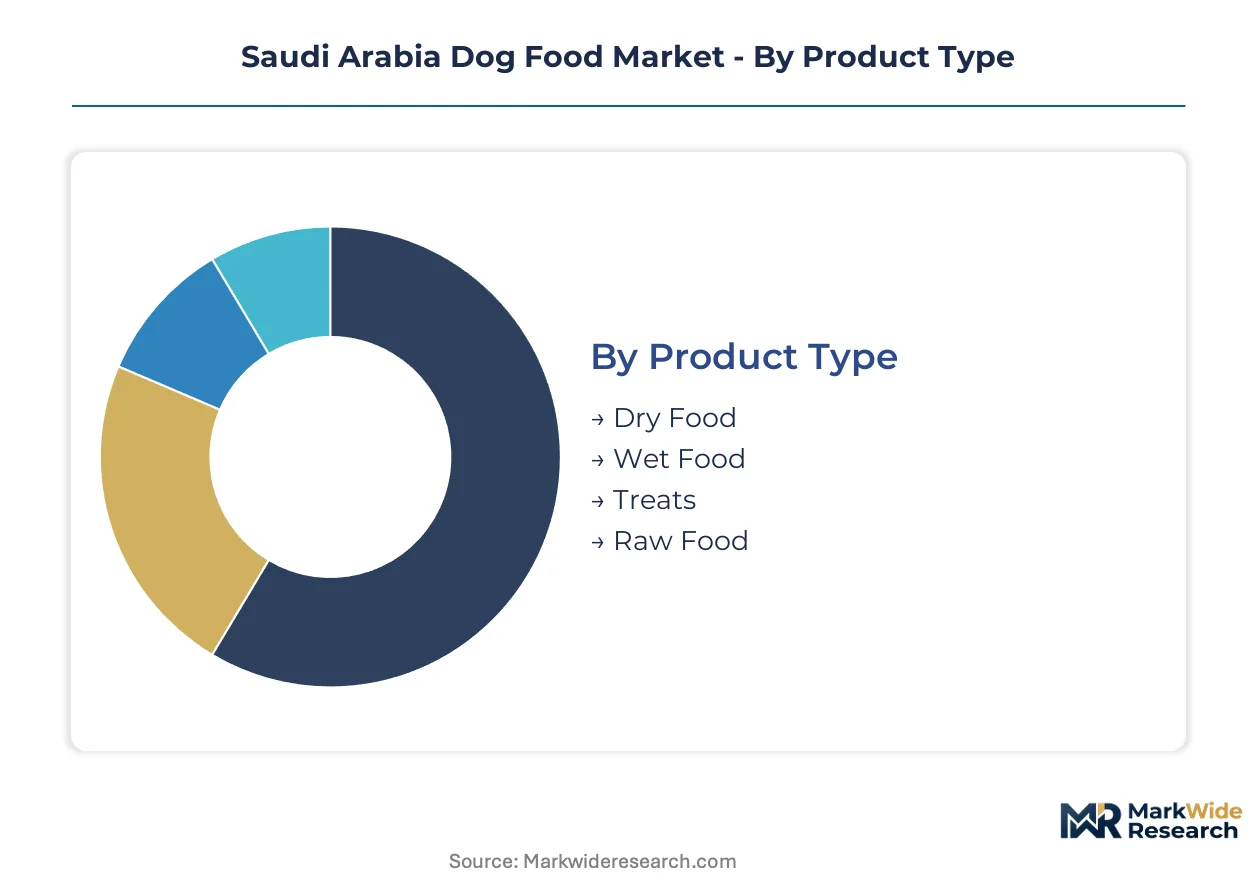
Segmentation reveals how Saudi Arabia's dog food market stratifies across feeding preferences, procurement channels, and nutritional philosophies. Distinct buyer profiles in Riyadh and Jeddah drive divergence between convenience-oriented and precision-nutrition segments.
Product Type:
Customization intensity spans from mass-manufactured extruded formats to bespoke raw nutrition protocols requiring cold-chain integrity.
- Dry Food:Extruded kibble formulations achieve 18-32% crude protein through thermal processing, with shelf stability enabling distributed retail penetration across Saudi Arabia's hypermarket network. Volume concentrates among cost-conscious households in secondary cities where storage convenience outweighs premium positioning.
- Wet Food:Canned or pouch formats integrate hydration at 75-85% moisture content, commanding margin premiums in Jeddah and Riyadh where veterinary clinics prescribe therapeutic moisture integration for renal and urinary health management.
- Treats:Functional reward formats with dental or training applications occupy impulse-purchase positioning in pet specialty channels.
- Raw Food:Freeze-dried or fresh-frozen formats requiring strict cold-chain protocols serve breeder and show-dog communities with uncompromising nutritional specifications.
Most installed capacity flows through Dry Food. Expansion is steepest in Raw Food.
End User:
Procurement sophistication escalates from individual household purchasing to institutional volume contracts with formulation specifications.
- Pet Owners:Individual households in Riyadh and Jeddah drive premiumization through breed-specific and life-stage targeted purchases, with disposable income growth enabling therapeutic nutrition adoption previously confined to veterinary prescription.
- Veterinary Clinics:Clinical networks function as gatekeepers for therapeutic formulations, with prescriptive authority creating pull-through demand for renal, digestive, and joint-support diets in metropolitan corridors.
- Kennels:Commercial breeding and boarding operations prioritize cost-optimized bulk procurement with consistent supply security over formulation complexity.
- Shelters:Municipal and charitable operations represent price-sensitive volume demand with minimal specification requirements.
Volume concentrates with Pet Owners. Margin expansion is fastest in Veterinary Clinics.
Ingredient Type:
Ingredient philosophy divides markets between ancestral-diet emulation and science-backed functional intervention.
- Meat-Based:Protein-first formulations emphasizing named animal sources satisfy halal-adjacent sourcing requirements under General Authority for Food and Drug Administration protocols, with lamb and poultry proteins dominating supplier qualification.
- Functional:Probiotic, prebiotic, and joint-support additive integration targets aging dog populations and digestive sensitivity cases, with SFDA notification requirements extending registration timelines for novel strain introductions.
- Grain-Free:Carbohydrate-restricted formulations address allergy-management demand among purebred owners in Riyadh's show-dog community.
- Organic:Certified ingredient sourcing remains nascent due to limited domestic organic protein supply and import dependency constraints.
Most formulations incorporate Meat-Based positioning. Functional ingredients are gaining share fastest.
Distribution Channel:
Channel selection reflects trade-offs between tactile product evaluation and replenishment convenience.
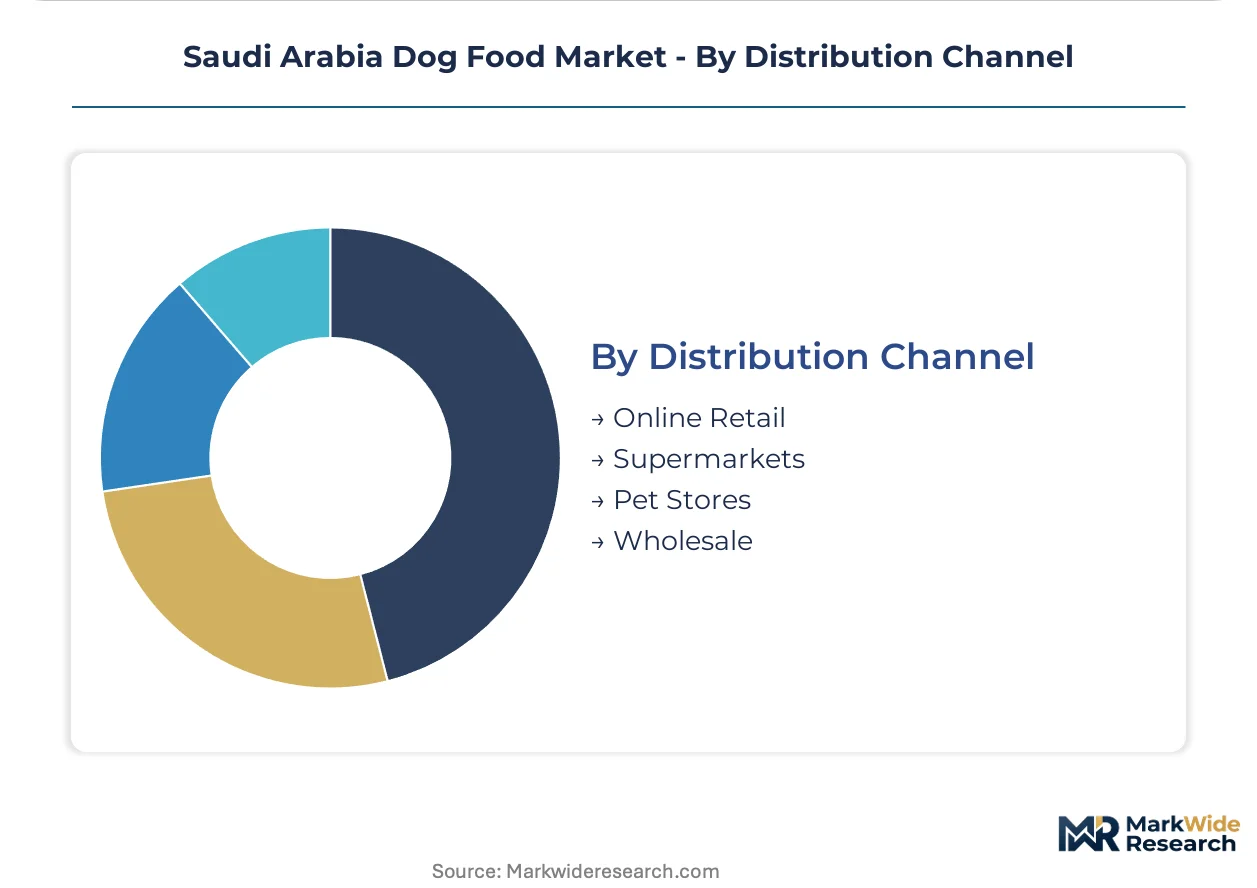
- Supermarkets:Hypermarket chains anchor mass-market volume through shelf-stable dry food dominance, with Carrefour and Panda leveraging foot traffic from grocery consolidation to capture episodic pet food purchases.
- Online Retail:Direct-to-consumer platforms with subscription automation capture dual-income households in Jeddah's coastal districts, locking in formulation loyalty through replenishment algorithms that reduce stockout frequency.
- Pet Stores:Specialty retailers provide tactile evaluation and staff consultation for premium format consideration, particularly in Riyadh's upscale districts.
- Wholesale:Distributor networks serve kennel and shelter institutional demand with pallet-scale logistics efficiency.
Volume flows predominantly through Supermarkets. Online Retail exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary nutritionist talent concentrates in Riyadh and Jeddah, anchoring clinical channel development while procurement sophistication escalates across Saudi Arabia's metropolitan corridors.
Riyadh
Dual-income households and show-dog breeders drive premiumization through breed-specific formulations and functional additive demand. SFDA registration timelines for novel ingredients compress innovation windows for suppliers targeting the capital. The Riyadh pet specialty retail cluster anchors therapeutic nutrition distribution through veterinary clinic partnerships.
Jeddah
Coastal urban professionals prioritize subscription-based replenishment and convenience-oriented purchasing over price comparison. The General Authority for Food and Drug Administration enforces halal-adjacent sourcing standards that shape protein ingredient qualification for Red Sea port imports. Jeddah's hypermarket and e-commerce channels exhibit the steepest wet food margin expansion.
Eastern Province
Dammam and Khobar present whitespace opportunity with underdeveloped pet specialty retail density relative to Riyadh. Municipal zoning for veterinary clinics is accelerating, enabling clinical-anchored distribution expansion. The Dammam logistics corridor facilitates cold-chain infrastructure for freeze-dried raw format penetration.
Western Region
Makkah and Madinah municipalities exhibit emerging pet ownership growth among expatriate communities and affluent local households. Regional distributor networks prioritize cost-optimized dry food bulk procurement over premium format complexity. The Taif highland cluster supports breeder operations with climate-advantaged kennel facilities.
Saudi Arabia Dog Food Market Key Industry Players
Top-tier vendors anchor hypermarket and veterinary clinic channels, while mid-tier regional specialists compete on halal-certification proximity and import agility. Mars Incorporated, Nestle SA, and Royal Canin occupy the premium-prescription intersection through R&D infrastructure and clinical endorsement networks. Strategic archetypes separate global nutrition science leaders, regional sourcing specialists, and private-label contract manufacturers. Competitive moves concentrate on portfolio diversification into functional ingredients and e-commerce subscription platform partnerships.
Within the global nutrition science tier, Mars Incorporated and Nestle SA exemplify multinational scale advantages in SFDA compliance documentation and veterinary relationship depth. Royal Canin occupies the breed-specific therapeutic position. Among regional specialists, Bayt Al Aleefa and Delicious Food Factory represent halal-adjacent sourcing agility and import partnership flexibility that compresses lead times for metropolitan retail replenishment.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestle SA |
| Colgate-Palmolive Company |
| Royal Canin |
| JM Smucker Co |
| General Mills |
| Bayt Al Aleefa |
| Delicious Food Factory |
| Hills Pet Nutrition |
| Others |
Cost & Logistics Intelligence
Halal-adjacent sourcing standards under the General Authority for Food and Drug Administration gate qualified protein supply and premium-tier pricing access, compressing supplier pools while elevating compliance costs that feed into formulation premiums across Saudi Arabia's metropolitan corridors.
Pricing Analysis
Service bundling separates veterinary-endorsed therapeutic formulations from unbundled commodity dry food, with Mars Incorporated and Royal Canin commanding premium positioning through prescriptive channel integration. Price differentiation rests on protein specificity grade and SFDA certification tier, with breed-specific lines capturing margin premiums while economy extruded kibble faces cost compression from import duty volatility. Pricing pressure intensifies in standard-tier segments as regional specialists exploit halal-certification proximity to undercut multinational markups. Kennel and shelter buyers exhibit highest price sensitivity; show-dog breeders and veterinary clinic networks demonstrate lowest.
Supply Chain Analysis
Warehouse-distribution layers anchor on Riyadh and Jeddah hub-and-spoke patterns, with Dammam emerging as Eastern Province logistics consolidation. Protein ingredient sourcing draws from European Union, United States, and Australian suppliers, with lamb and poultry inputs dominating qualified vendor lists. Single-source vulnerability concentrates in freeze-dried raw formats dependent on European cold-chain partnerships. Distribution runs through hypermarket chains for volume, pet specialty retail for premium, and direct-to-consumer platforms for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Saudi Arabia's dog food market stems from therapeutic nutrition premiumization and e-commerce subscription automation that locks in recurring revenue while reducing customer acquisition costs.
For Market Incumbents: Lock in veterinary clinic channel control through exclusive therapeutic formulation partnerships that preempt regional specialist encroachment. Deepen backward integration into halal-certified protein sourcing to deflect SFDA qualification timeline risk and compress landed cost structures. Prioritize R&D investment in probiotic strain documentation to accelerate pre-market approval cycles. For New Entrants and Emerging Players: Dual-income coastal professionals in Jeddah represent an underserved buyer archetype seeking convenience-optimized subscription replenishment with formulation consistency guarantees. Penetrate the Eastern Province whitespace through Dammam-anchored cold-chain infrastructure partnerships that enable freeze-dried raw distribution. Deploy direct-to-consumer platform launches with automated replenishment algorithms to bypass hypermarket shelf-space barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier regional halal-certification specialists because SFDA compliance documentation creates acquisition synergies that accelerate product registration timelines. Five-to-ten year viability hinges on therapeutic nutrition portfolio depth and veterinary relationship density. Monitor SFDA feed-grade versus food-grade classification rulings as inflection signal for import duty structure recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Prescriptive authority from Riyadh and Jeddah clinics creates pull-through demand for therapeutic formulations. |
| Halal-Certification Investment | General Authority for Food and Drug Administration compliance accelerates supplier qualification and reduces import friction. |
| E-Commerce Platform Integration | Subscription automation captures Jeddah's time-constrained professional demographic with formulation loyalty lock-in. |
| Cold-Chain Infrastructure Expansion | Dammam logistics corridor enables freeze-dried raw format penetration previously constrained by climate limitations. |
| Functional Ingredient R&D | Probiotic and joint-support additive development targets aging dog populations with veterinary endorsement requirements. |
Research Approach
Multiple input streams — structured interviews with veterinary nutritionists and pet specialty retail buyers, customs and import documentation analysis, and SFDA regulatory filing review — were reconciled through bottom-up volume modeling and top-down value triangulation. Primary fieldwork engaged clinical network directors, hypermarket category managers, regional distributor procurement leads, and breeder association representatives across Riyadh, Jeddah, and Dammam. Secondary validation incorporated Saudi Customs Authority trade data, SFDA product registration databases, and veterinary clinic network expansion records.
Historical consumption patterns were cross-referenced against panel input from supply-side executives to construct projection frameworks across the modeling period. Segmentation dimensions modeled include product type, end-user sophistication tier, ingredient philosophy, and distribution channel architecture. CAGRs were derived from elasticity-adjusted demand curves and import volume trajectory analysis, with therapeutic nutrition premiumization and subscription platform penetration serving as key forecast inputs.
Underlying measurement precision varies by segment; dry food volume estimates carry tighter precision than raw food projections given cold-chain opacity. Forecasts reflect documented assumptions regarding SFDA regulatory trajectory and disposable income growth patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Pet Gadgets Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
Global Pet Supplies Market