
 Kids Tablet Market | 2026-2036
Kids Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Tablet Market Intelligence
Subscription-based leasing and refresh programs for school districts is tilting competitive dynamics toward vendors with balance-sheet capacity to carry hardware receivables. Amazon leverages its Fire OS ecosystem to anchor institutional procurement cycles through managed device fleets. Samsung competes on manufacturing scale, sustaining cost advantages in large-format touchscreen production that lower per-unit pricing for education buyers.
Kids tablets are portable computing devices engineered with durable enclosures, parental control firmware, and display specifications calibrated for reduced blue-light emission and limited viewing angles. Their primary commercial purpose is to deliver curated educational content and supervised entertainment to users in developmental age brackets. Learning tablets dominate volume flows through educational suppliers, while hybrid tablets capture margin pools as parents seek dual-purpose devices that transition from schoolwork to media consumption. Android and Fire OS installations lead unit shipments, though iOS maintains premium positioning through tighter integration with school IT infrastructure.
The US Children's Online Privacy Protection Act and the EU's GDPR jointly constrain how platforms collect behavioral data from minors, forcing hardware OEMs to embed privacy-by-design architectures. The EU AI Act adds emerging compliance burdens for adaptive learning algorithms that personalize content delivery. Stakeholders must monitor how fragmented regulatory timelines across Washington, Brussels, and Beijing reshape software development roadmaps and certification costs.
Market Dynamics
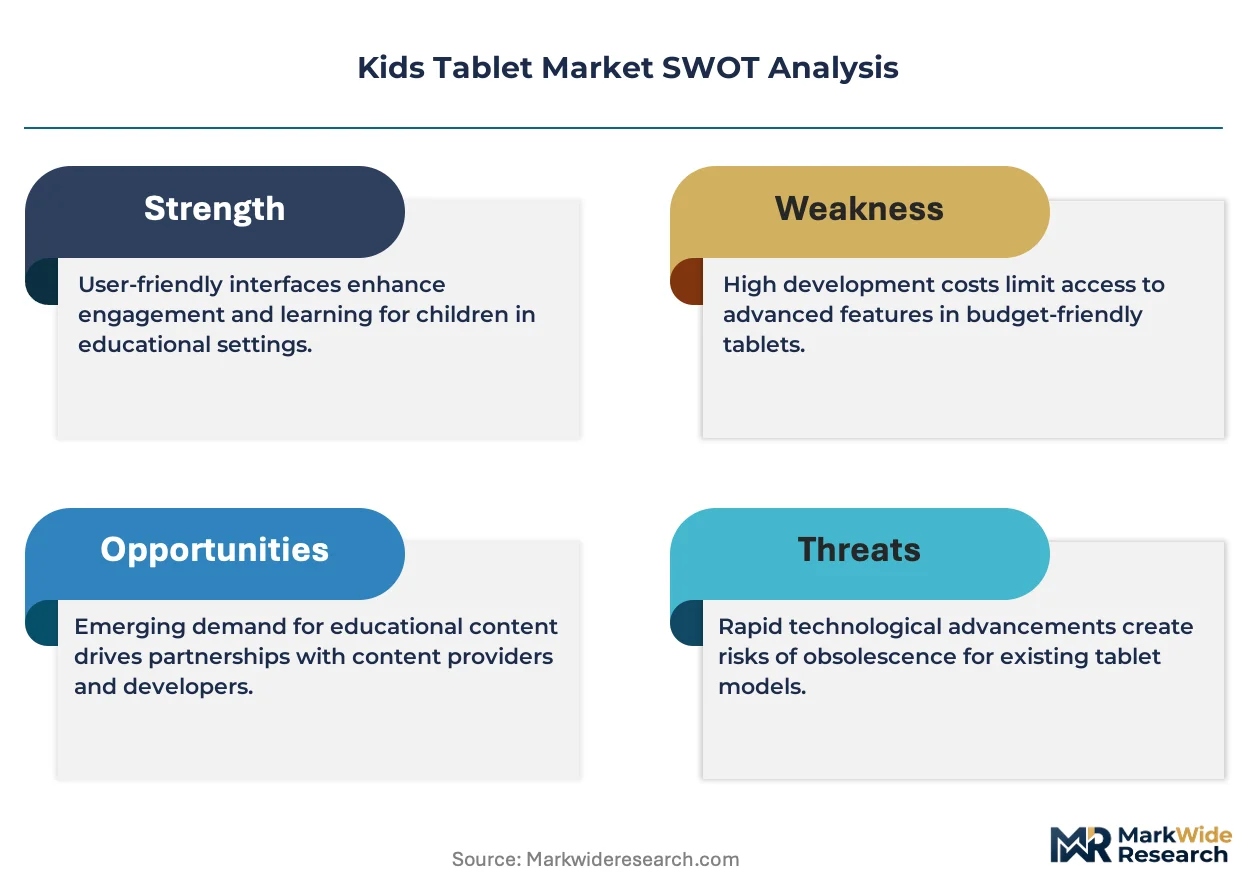
Educational procurement consolidation is compressing vendor margins while elevating balance-sheet requirements for hardware financing programs that lock districts into multi-year refresh cycles.
Growth Catalysts
- GDPR-KIDS and COPPA enforcement:Stricter data collection rules for minors are mandating privacy-by-design hardware architectures that certified OEMs can monetize through compliance premiums.
- Blue-light reduction displays:Eye-safe screen technologies are becoming procurement prerequisites for school districts prioritizing student health metrics in RFP evaluations.
- Germany's education digitization fund:Federal tablet subsidies for primary schools are accelerating replacement of aging desktop labs with mobile computing fleets.
Market Restraints
- Panel supply concentration:Large-format touchscreen production clusters in South Korea and Taiwan create input cost volatility when display foundry capacity tightens.
- EU AI Act algorithmic constraints:Adaptive learning personalization engines face certification delays that extend product development timelines by 12-18 months.
- Smartphone substitution:Parent-owned handsets with parental control apps are cannibalizing standalone tablet demand in household entertainment use cases.
Strategic Opportunities
- India's PM SHRI school scheme:Federal infrastructure upgrades for 14,500 model schools include dedicated ed-tech hardware budgets with local assembly incentives.
- Refurbishment-as-a-service:Circular economy programs for school district fleet renewal create recurring revenue streams separate from new unit sales.
- Speech-to-text literacy tools:Converging voice AI with handwriting recognition is opening early-childhood segments previously inaccessible to keyboard-dependent devices.
Industry Challenges
- Firmware security talent scarcity:Embedded systems engineers with child-data protection expertise command premium compensation that strains R&D budgets.
- Multi-jurisdiction certification stacking:Simultaneous FCC, CE marking, and BIS approvals for a single hardware SKU extend time-to-revenue by 8-10 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Tablet Market |
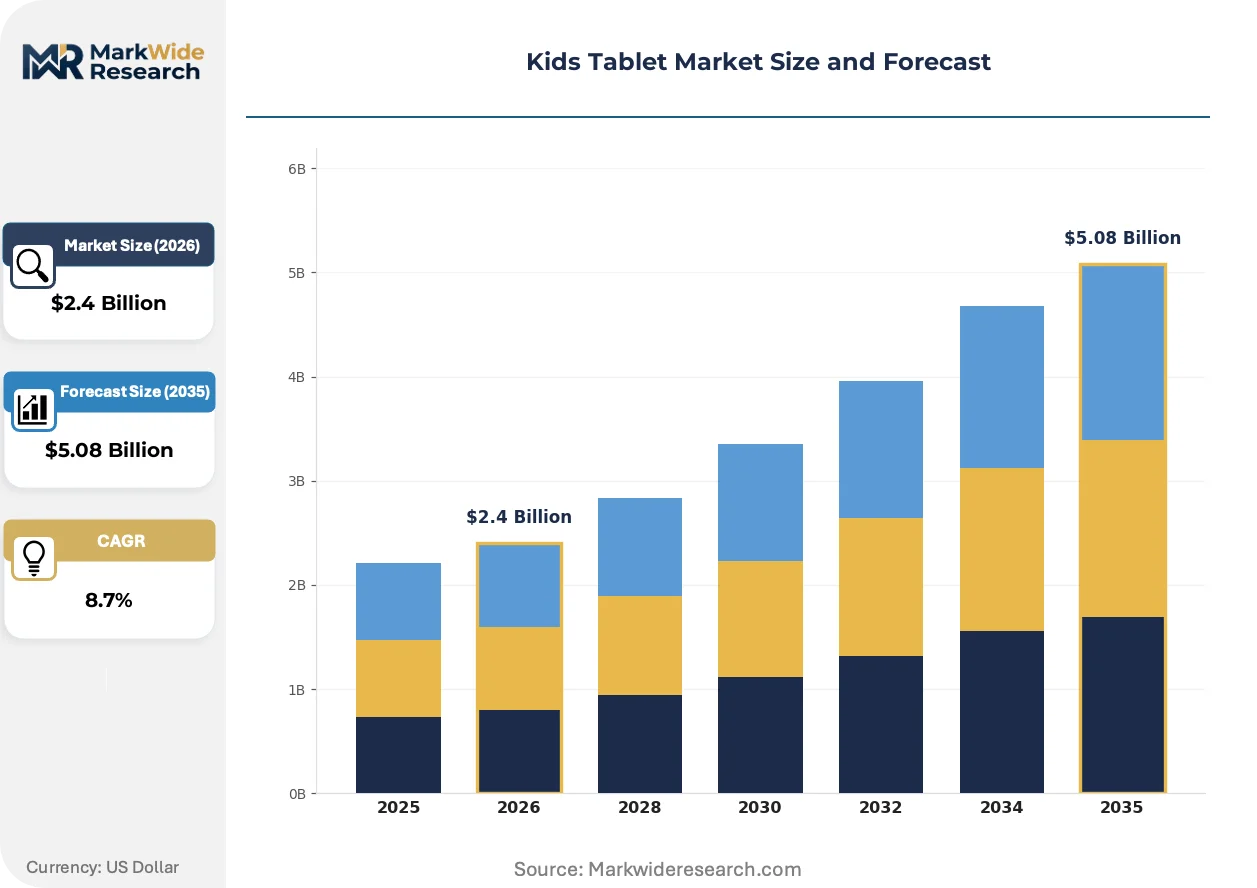
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Tablets, Entertainment Tablets, Hybrid Tablets, Graphics Tablets, Audio Tablets Operating System: Android, iOS, Fire OS, Windows, Proprietary OS Age Group: Toddlers 2-5, Early Childhood 6-8, Preteens 9-12, Teens 13-15 Distribution Channel: Online Retailers, Specialty Stores, Mass Merchandisers, Educational Suppliers |
| Companies Covered | Lenovo, XP-Pen, Apple, Google, Microsoft, Amazon, LeapFrog, Xiaomi, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Tablet Market Strategic Shifts & Innovations
Hardware-software integration depth is becoming the primary competitive differentiator as districts reject generic Android tablets in favor of vertically controlled ecosystems with built-in classroom management.
Passive stylus digitizers with palm-rejection algorithms are rendering obsolete capacitive-touch-only tablets in K-5 handwriting instruction. Finland's national curriculum mandates cursive practice on pressure-sensitive screens. Publishers are discontinuing content licenses for non-stylus devices, compressing the addressable market for basic touch-only hardware.
The EU Digital Services Act's content moderation duties are forcing OEMs to pre-install age-gating firmware that filters app store access by developmental stage. Hardware vendors now carry liability for platform content that school IT administrators previously managed. German and French education ministries are requiring DSA compliance certificates in procurement specifications ahead of full enforcement.
Bulk purchasing cooperatives organized by state education agencies are displacing individual district RFPs across the US Mountain West and Southeast. Texas and Florida regional buying consortia negotiate standardized terms that freeze out smaller vendors lacking scale to meet volume-price commitments. District technology directors report reduced vendor optionality but simplified fleet uniformity.
Kids Tablet Market Segmentation
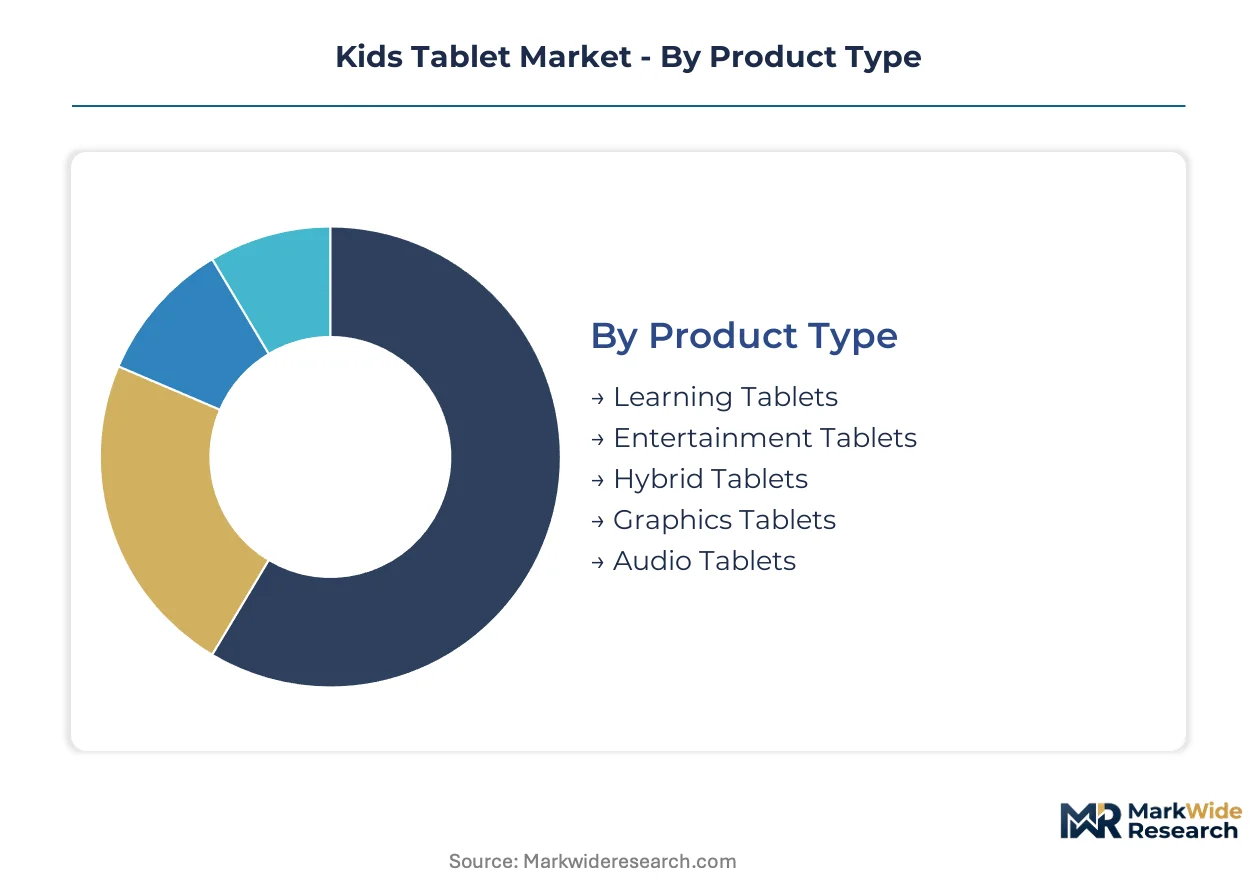
Segmentation in kids tablets determines procurement pathways, compliance obligations, and margin structures. School districts, parents, and institutional buyers prioritize different attribute bundles, fragmenting vendor go-to-market strategies across hardware specifications and channel economics.
Product Type:
Mature segments dominate institutional procurement while emerging formats capture household premium spending.
- Learning Tablets:Purpose-built devices with ruggedized enclosures, pre-loaded educational content libraries, and locked-down app ecosystems. Volume concentrates through educational suppliers serving US school districts and Germany's federal digitization programs, where bulk purchasing mandates eye-safe displays and COPPA-compliant data architectures.
- Hybrid Tablets:Dual-purpose hardware bridging schoolwork and media consumption with adjustable parental controls and detachable keyboards. Demand clusters in affluent US suburban households seeking single-device solutions, driven by parent preference for equipment that transitions across home and classroom environments without redundant purchases.
- Entertainment Tablets:Content-forward devices optimized for streaming and gaming with lighter educational integration.
- Graphics Tablets:Pressure-sensitive digitizers supporting stylus-based creativity and handwriting instruction.
- Audio Tablets:Voice-centric form factors emphasizing audiobooks and speech-to-text literacy tools.
Learning tablets handle the majority of throughput; hybrid tablets are gaining share fastest as household consolidation pressures single-purpose device purchases.
Operating System:
Cost tier alignment shapes competitive positioning from budget institutional fleets to premium consumer segments.
- Fire OS:Amazon's vertically controlled ecosystem anchors managed device programs through centralized fleet administration, content filtering, and subscription-based hardware refresh cycles. US school districts with limited IT staffing favor this stack for simplified procurement and unified billing.
- Android:Open-source foundation enabling OEM customization for regional compliance and price-tier flexibility. India's PM SHRI scheme drives assembly-localized Android deployments with BIS certification and Hindi-language interface requirements.
- iOS:Tight integration with existing school IT infrastructure and superior app curation commands premium positioning.
- Windows:Enterprise-grade security protocols appeal to secondary education administrators managing cross-platform environments.
- Proprietary OS:Closed stacks from specialized vendors targeting single-use literacy and early-childhood segments.
Fire OS captures the institutional volume base; Android climbs fastest on public-sector localization mandates in emerging procurement markets.
Age Group:
Application intensity varies sharply across developmental stages, dictating hardware durability requirements and content licensing complexity.
- Early Childhood 6-8:Peak institutional procurement segment with curriculum-mandated handwriting practice driving pressure-sensitive stylus adoption. Finland's national curriculum requirements and publisher content licensing restrictions favor digitizer-equipped hardware, compressing capacitive-touch-only addressable markets.
- Preteens 9-12:Transition segment where school-issued devices face household entertainment use, requiring robust parental control firmware. EU Digital Services Act age-gating obligations fall on OEMs for this bracket, extending liability to hardware vendors for platform content moderation.
- Toddlers 2-5:Durable, simplified interfaces with physical button navigation and drop-resistant construction.
- Teens 13-15:Near-adult feature sets with graduated content access and productivity tool integration.
Early Childhood 6-8 handles the majority of throughput; Preteens 9-12 expands most quickly on dual-use household penetration.
Distribution Channel:
Customer type concentration determines margin capture and working capital intensity across fragmented versus consolidated buying pools.
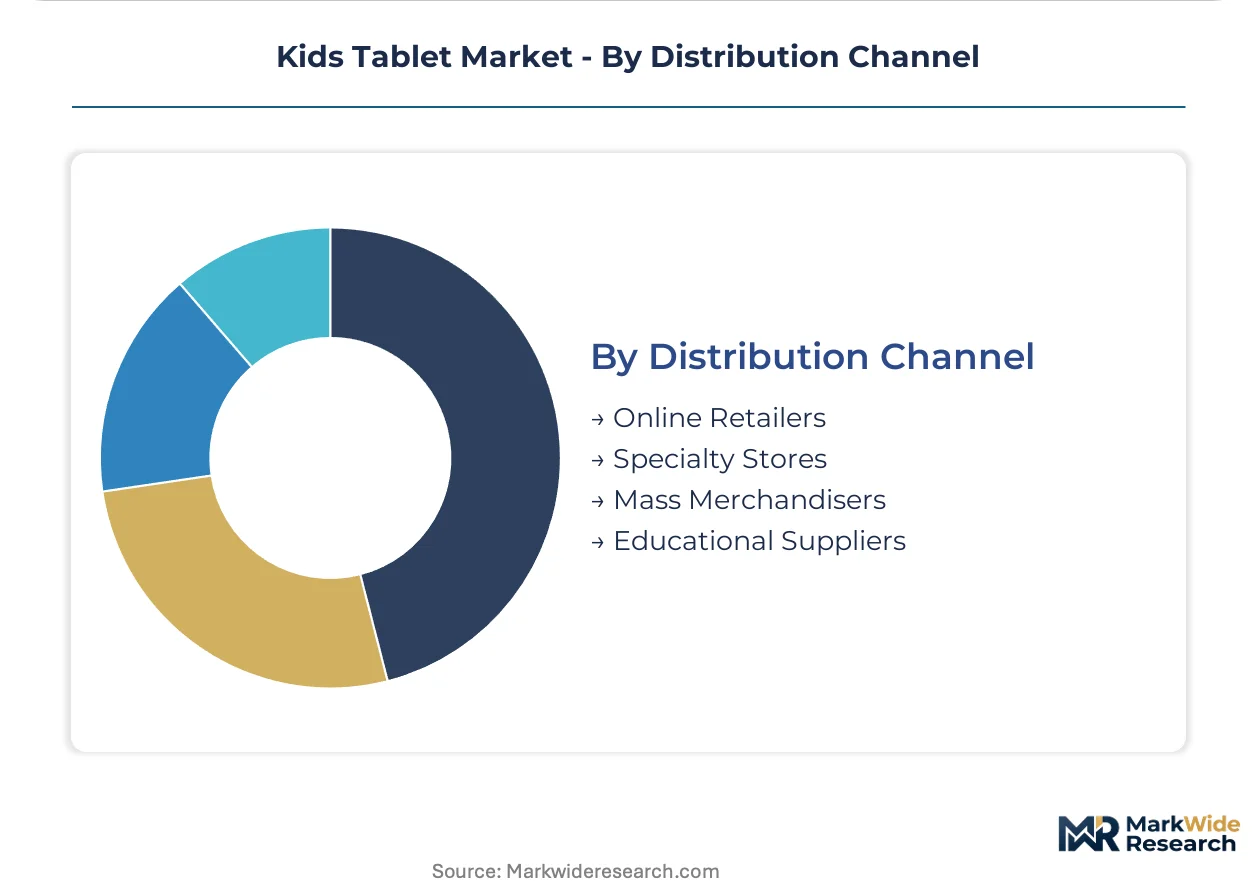
- Educational Suppliers:Specialized distributors with curriculum alignment expertise and multi-year fleet financing programs. Texas and Florida regional buying consortia negotiate standardized terms that compress vendor margins while locking in volume commitments.
- Online Retailers:Direct-to-consumer platforms capturing parent-driven replacement cycles and gift purchasing with rapid delivery expectations.
- Specialty Stores:Hands-on demonstration environments supporting premium positioning and stylus-input validation.
- Mass Merchandisers:High-volume, low-touch distribution for entry-level hardware with limited support infrastructure.
Educational suppliers handle the majority of throughput; online retailers are climbing fastest on household convenience preferences and subscription bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The kids tablet trade flows reflect divergent national digitization priorities, with net importers in Western Europe and North America sourcing hardware from East Asian manufacturing clusters while domestic content providers capture recurring software revenue.
United States
School district bulk purchasing drives institutional volume through regional buying consortia in Texas and Florida. COPPA enforcement mandates privacy-by-design firmware architectures that certified OEMs monetize through compliance premiums. Seattle and Austin host fleet management software providers coordinating multi-year refresh cycles for district IT administrators.
Germany
Federal education digitization funds subsidize tablet procurement for primary schools replacing aging desktop labs. GDPR-KIDS and the EU Digital Services Act impose content moderation duties on hardware vendors through pre-installed age-gating firmware. Berlin-Brandenburg clusters host adaptive learning algorithm developers facing EU AI Act certification delays.
China
Domestic manufacturing scale supports cost-competitive export supply to emerging procurement markets. MIIT standards and GB certification requirements shape hardware specifications for both domestic consumption and overseas shipment. Shenzhen and Dongguan concentrate touchscreen assembly capacity serving global education technology brands.
India
The PM SHRI school scheme dedicates ed-tech hardware budgets to 14,500 model schools with local assembly incentives driving BIS-certified Android deployments. TRAI guidelines influence child-data protection expectations for connected devices. Karnataka and Tamil Nadu host electronics manufacturing zones producing region-localized tablet variants.
South Korea
Display foundry concentration in Samsung and LG supply chains creates input cost leverage for large-format touchscreen production. MFDS and national standards bodies coordinate with international certification regimes for education hardware exports. Seoul Capital Area anchors R&D for blue-light reduction display technologies now mandated in European procurement specifications.
Kids Tablet Market Key Industry Players
On the supply side, the industry is tiered between vertically integrated ecosystem operators, manufacturing-scale specialists, and regional assembly-localized challengers. Consumer electronics conglomerates and dedicated education technology firms represent distinct strategic archetypes. Competitive dynamics center on hardware financing program capacity and multi-jurisdiction certification velocity rather than unit cost alone.
Among ecosystem-integrated operators, Amazon and Apple occupy positions anchoring contrasting procurement segments. Amazon's Fire OS vertical control exemplifies the institutional fleet management archetype, while Apple's premium positioning represents the school IT infrastructure integration tier. Samsung sits within the manufacturing-scale tier, leveraging captive display supply for cost-advantaged education market penetration.
| Leading Market Players |
|---|
| Lenovo |
| XP-Pen |
| Apple |
| Microsoft |
| Amazon |
| LeapFrog |
| Xiaomi |
| Samsung |
| Others |
Cost & Logistics Intelligence
Display foundry undercapacity in South Korea and Taiwan is compressing margins for education hardware vendors while forcing procurement officers toward longer-term offtake commitments that lock in price stability against spot-market volatility.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Fire OS fleet subscriptions command premium positioning through bundled compliance certification and centralized management, while BIS-certified Android tablets compete on landed cost for India's PM SHRI tenders. Price differentiation hinges on COPPA/GDPR certification grade and volume scale commitments. Pricing pressure stems from smartphone substitution in household segments as parental control apps cannibalize standalone tablet demand. School districts exhibit lowest price sensitivity due to federal subsidy absorption, while mass-market parents drive cost compression.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor lithography equipment are constraining display driver IC availability for large-format touchscreens. Manufacturing gravity centers on China, South Korea, and Taiwan for panel assembly, with India and Vietnam gaining share for final device integration under local content mandates. The supply chain draws from indium tin oxide sputtering targets, Gorilla Glass substrates, and ARM-based SoC architectures. Single-source vulnerability concentrates in Samsung and LG Display foundry capacity for blue-light reduction panels. Distribution runs through educational suppliers with multi-year financing programs rather than spot retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone substitution represents the primary displacement threat that tablet incumbents must neutralize through hardware-software integration depth that parental control apps cannot replicate.
For Market Incumbents: Insulate institutional revenue streams by embedding privacy-by-design architectures that preempt COPPA enforcement actions and command compliance premiums. Deepen backward integration into pressure-sensitive stylus digitizer supply to capture Finland's curriculum-mandated handwriting segment before publisher licensing restrictions freeze out capacitive-touch competitors. Counter smartphone encroachment through fleet management software lock-in that district IT administrators cannot replicate with bring-your-own-device policies. For New Entrants and Emerging Players: Build out refurbishment-as-a-service capabilities for US regional buying consortia seeking circular economy compliance without balance-sheet strain. Target India's PM SHRI scheme with BIS-certified Android variants featuring Hindi-language localization and Karnataka-based assembly. Penetrate through speech-to-text literacy tools for early childhood segments previously inaccessible to keyboard-dependent hardware. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across subscription-based hardware financing programs as districts demand multi-year refresh cycles. Long-term viability favors vendors with captive display supply or ecosystem control rather than assembly-only positioning. Monitor EU AI Act certification timelines for adaptive learning algorithms as the signal for which personalization engines achieve market clearance.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Hardware Certification | GDPR-KIDS and COPPA enforcement create compliance premiums for certified OEM architectures. |
| Stylus Digitizer Integration | Finland's cursive mandate and publisher licensing restrictions favor pressure-sensitive screen vendors. |
| Fleet Management Platform Development | Fire OS-style centralized administration locks districts into multi-year refresh cycles with unified billing. |
| Regional Assembly Localization | India's PM SHRI local content incentives and BIS certification requirements favor domestic integration. |
| Refurbishment-as-a-Service Launch | Circular economy programs for school district fleet renewal generate recurring revenue separate from unit sales. |
Research Approach
The analysis maps learning tablets, hybrid tablets, and graphics tablets, each validated through procurement directors at US regional buying consortia, district IT administrators, ed-tech hardware OEMs, and educational content publishers. Primary interviews with these stakeholders combined secondary validation through FCC equipment authorization databases, BIS certification registries, EU Digital Services Act implementation guidance, and SEC 10-K filings from consumer electronics conglomerates. Bottom-up unit shipment estimates triangulated against top-down education budget allocation data from federal digitization programs.
Assumptions held fixed include current COPPA enforcement intensity, EU AI Act certification timelines, and display foundry capacity utilization rates across the projection horizon. The analytical framework modeled operating system, age group, and distribution channel segmentation alongside hardware-software integration depth as an industry-specific dimension. CAGRs derived from regression analysis against historical education technology procurement cycles, incorporating blue-light display mandate adoption curves and federal subsidy program renewal patterns as forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by smartphone vendors into managed device management would shift outcomes. Material shifts in EU AI Act algorithmic certification requirements or display panel tariff regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Wrist Watch Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Latin America Consumer Electronics Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
Smart Phones Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market
Consumer Electronics
Headset Market
Consumer Electronics
4K Television Market
Consumer Electronics
Nanopresso Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Ultra-Portable Speakers Market