
 Restroom Cleaning Supplies Market | 2026-2036
Restroom Cleaning Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Restroom Cleaning Supplies Market Analytics
Janitorial labor shortages across commercial cleaning services is rotating procurement priorities toward concentrated and no-rinse formulations that reduce dwell time and retraining burdens. Ecolab leverages its institutional channel dominance to bundle dispensing equipment with recurring chemical supply contracts. Procter & Gamble sustains consumer brand recognition that extends into away-from-home segments through licensed professional lines. SC Johnson anchors its competitive stance with fragrance-integrated deodorizer systems that command shelf space in retail and contract channels.
Restroom cleaning supplies encompass chemically formulated agents engineered to remove organic soils, mineral deposits, and pathogenic microorganisms from ceramic, porcelain, stainless steel, and synthetic surfaces, with active ingredients ranging from quaternary ammonium compounds and hydrogen peroxide to citric acid and surfactant blends, typically requiring specific contact times and dilution ratios to achieve sanitization or disinfection claims against EPA-registered organism lists. The primary commercial purpose centers on maintaining hygienic conditions in high-traffic facilities while minimizing surface degradation and occupational exposure risks. Disinfectants command the largest revenue share within product type segmentation due to healthcare and foodservice compliance requirements, while wipes represent the fastest-expanding form factor as pre-saturated formats eliminate mixing errors and reduce worker chemical handling. Facilities Management as a consumer type concentrates purchasing power through national service contracts that standardize product selection across distributed property portfolios.
The EPA regulates antimicrobial efficacy claims through registration requirements under FIFRA, while OSHA's Hazard Communication Standard governs worker exposure documentation and safety data sheet distribution for cleaning chemical handlers. State-level procurement policies, particularly California's Green Cleaning Act and New York's procurement guidelines for schools and public buildings, restrict volatile organic compound content and mandate third-party environmental certifications such as Green Seal or UL Ecologo. Stakeholders must monitor evolving state-level chemical disclosure requirements and building certification standards such as LEED v4.1 that increasingly credit low-emitting cleaning product specifications.
Market Dynamics
Hospital-grade disinfectant procurement is concentrating purchasing power among national facilities management networks, compressing supplier margins while elevating compliance documentation requirements across acute care and foodservice verticals.
Growth Catalysts
- California's Green Cleaning Act:Mandates for low-VOC formulations in K-12 schools and state buildings accelerate reformulation investments by chemical manufacturers serving public sector contracts.
- Healthcare-associated infection protocols:Joint Commission accreditation standards for acute care networks drive recurring demand for EPA-registered sporicidal disinfectants with sub-ten-minute contact times.
- No-rinse surfactant chemistry:Advances in quaternary ammonium-peroxide blends eliminate secondary wipe-down steps, reducing labor hours per restroom in high-throughput transportation hubs.
Market Restraints
- Isopropyl alcohol feedstock volatility:Petrochemical derivative pricing fluctuations compress margin stability for aerosol and wipe manufacturers dependent on solvent-based formulations.
- EPA registration timelines:FIFRA antimicrobial claim approval processes extending eighteen to thirty-six months delay new active ingredient commercialization and SKU expansion.
- Peracetic acid substitution:Foodservice and beverage processing facilities pivot toward chlorine dioxide systems for equipment sanitization, eroding traditional restroom chemical adjacency sales.
Strategic Opportunities
- LEED v4.1 cleaning product credits:Building certification point systems for low-emitting maintenance supplies create specification pathways for third-party certified formulations in commercial real estate portfolios.
- Pre-saturated hydrogen peroxide wipes:Convergence of non-bleach chemistry with metered-dispense packaging addresses healthcare worker safety concerns while eliminating dilution error liability.
- Texas and Florida school district procurement:Underpenetrated Sun Belt education facilities present volume expansion potential as state enrollment growth outpaces legacy supplier contract coverage.
Industry Challenges
- Commercial cleaning technician certification:ISSA CMI and OSHA Hazard Communication training gaps slow workforce deployment, extending onboarding cycles for contract cleaning services.
- Legacy dispensing equipment retrofit:Concentrate dilution system upgrades require capital coordination between chemical suppliers and facilities managers with competing maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restroom Cleaning Supplies Market |
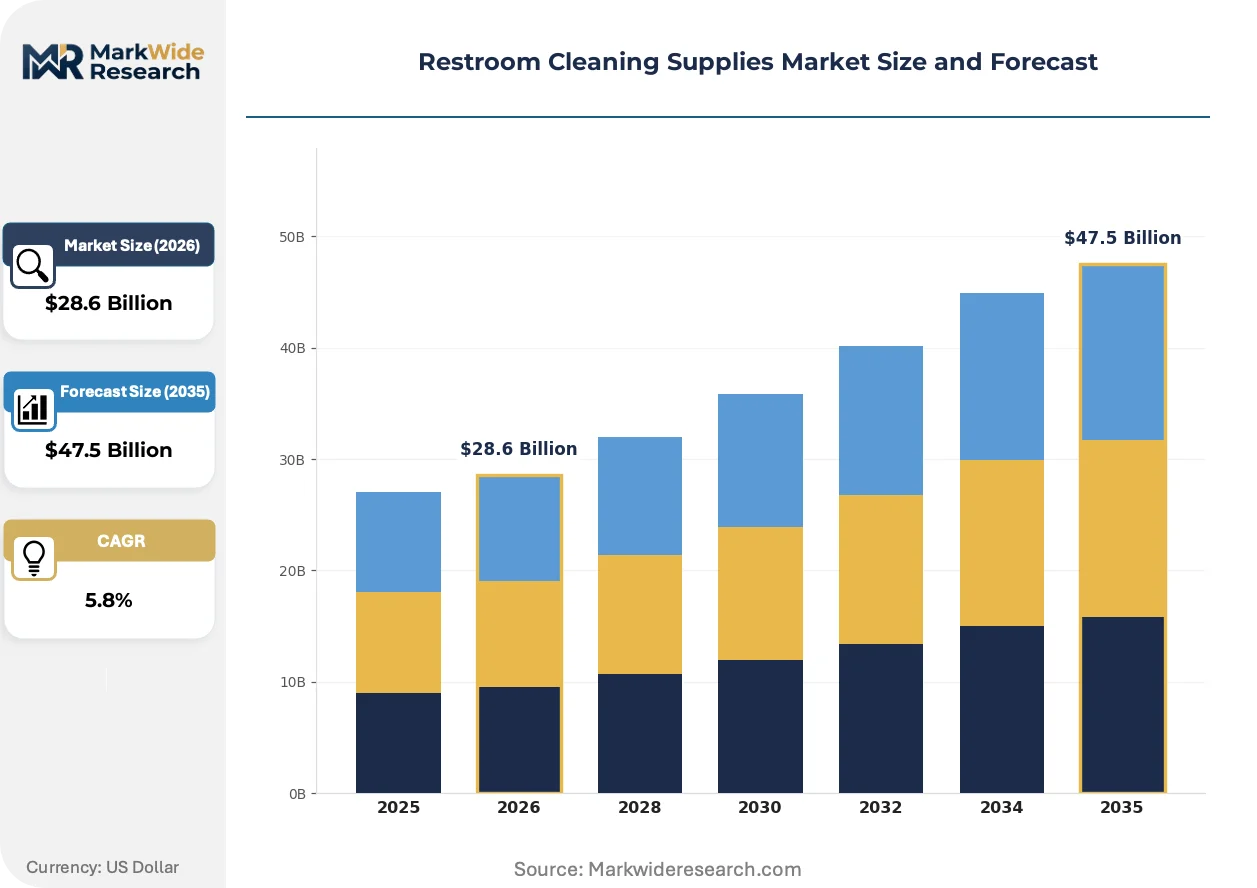
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectants, Toilet Bowl Cleaners, Surface Cleaners, Deodorizers Application: Commercial, Residential, Industrial, Institutional Consumer Type: Hospitality, Education, Healthcare, Facilities Management Form: Liquid, Spray, Gel, Wipes |
| Companies Covered | Procter & Gamble, Church & Dwight, Clorox Company, Reckitt Benckiser, SC Johnson, Henkel, Unilever, Ecolab, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restroom Cleaning Supplies Market Evolving Landscape
Electrochemical activation systems and on-site generation hardware are compressing traditional chemical distribution economics while reformulation chemistry races to satisfy overlapping disinfection efficacy and environmental compliance mandates.
On-site sodium hypochlorite generators are bifurcating the institutional supply chain by enabling facilities to produce disinfectant at point-of-use, eliminating drum handling and transportation costs. Large hospital systems in the Upper Midwest and Pacific Northwest are piloting these installations to secure supply continuity. The technology is bifurcating procurement relationships between chemical manufacturers and capital equipment vendors, forcing legacy suppliers to bundle hardware with recurring service contracts.
The EPA's Safer Choice program and state-level disclosure requirements in New York are mandating full ingredient transparency for cleaning products sold to public institutions. Formulators must now submit quantitative structural activity relationship data and aquatic toxicity profiles alongside traditional efficacy submissions. Contract manufacturers serving municipal and educational buyers are restructuring R&D workflows to front-load toxicological screening, compressing product development cycles for non-certified competitors.
Subscription-based replenishment models are displacing traditional distributor-led stocking programs in multi-site retail and hospitality chains. Facilities managers at quick-service restaurant networks and budget hotel portfolios now specify auto-replenishment thresholds tied to occupancy sensors and usage analytics. This behavioral shift concentrates purchasing authority with national procurement teams in Atlanta and Dallas, marginalizing regional chemical distributors who lack integrated inventory management platforms.
Restroom Cleaning Supplies Market Segmentation
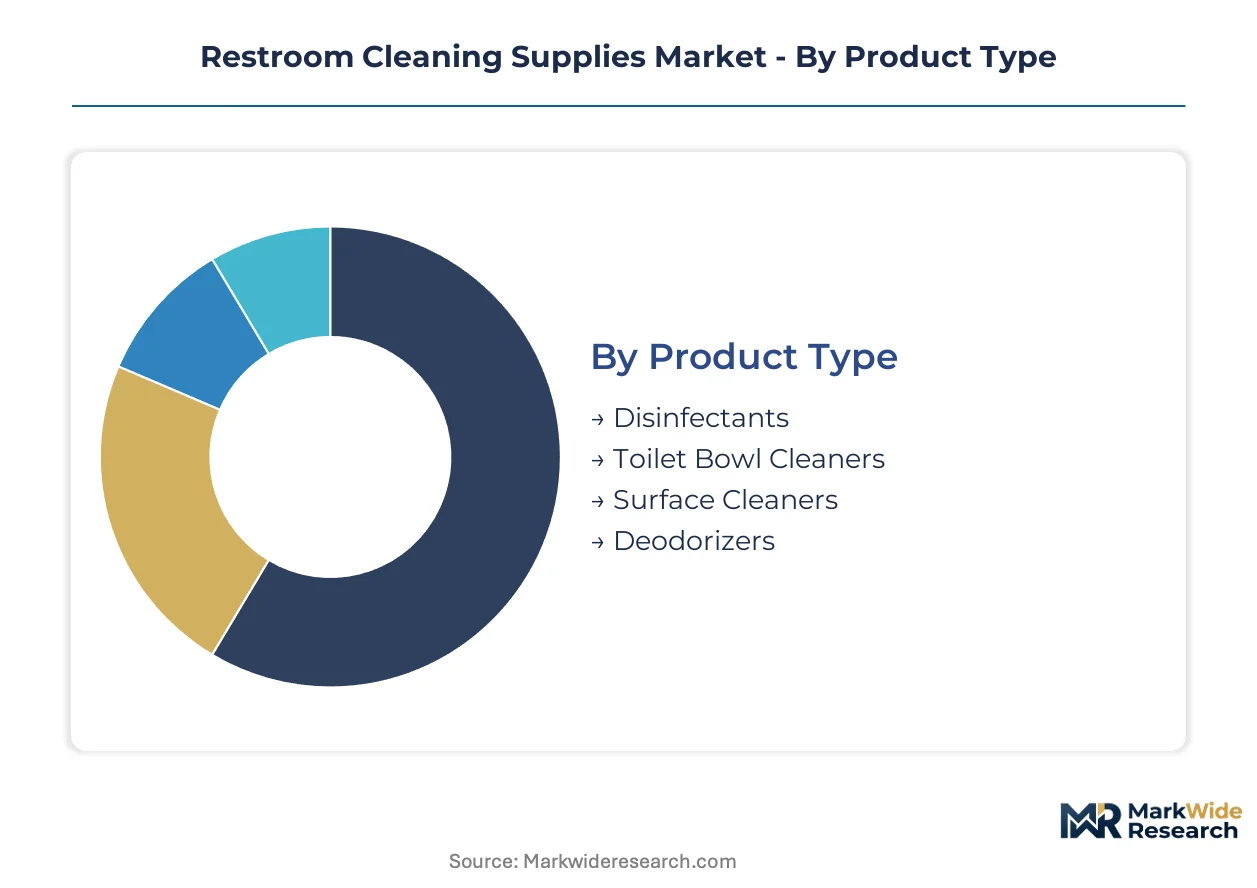
Segmentation in restroom cleaning supplies determines compliance pathways, procurement channels, and reformulation priorities. EPA registration categories and state-level green mandates create divergent product specifications across end-use verticals. Understanding these divides reveals where pricing power concentrates and where volume expansion faces regulatory friction.
Product Type:
EPA FIFRA registration tiers separate hospital-grade disinfectants from general-purpose cleaners, creating distinct commercialization timelines and liability profiles for manufacturers.
- Disinfectants:Quaternary ammonium compounds and hydrogen peroxide blends dominate hospital-grade formulations requiring sub-ten-minute contact times against EPA-registered organism lists. Acute care networks in the United States concentrate procurement through national GPO contracts, elevating documentation burdens for sporicidal claims.
- Surface Cleaners:No-rinse surfactant chemistry eliminates secondary wipe-down steps, reducing labor hours in high-throughput transportation hubs. California's Green Cleaning Act restricts volatile organic compound content below 10 grams per liter for K-12 procurement.
- Toilet Bowl Cleaners:Acid-based formulations target mineral deposits and urinary scale in porcelain fixtures.
- Deodorizers:Fragrance-integrated systems mask malodors through timed-release mechanisms in retail and contract channels.
Disinfectants handle the majority of throughput; surface cleaners are expanding most quickly on share as labor costs rise.
Application:
Facility throughput intensity and occupancy patterns drive formulation concentration and packaging format selection across verticals.
- Commercial:Office complexes, retail centers, and transportation terminals demand concentrated dilution systems compatible with automated dispensing equipment. Facilities management networks standardize product selection across distributed property portfolios through national service contracts.
- Healthcare:Joint Commission accreditation standards mandate EPA-registered sporicidal disinfectants with documented contact times. Infection prevention protocols in acute care networks drive premium product uptake and compliance documentation.
- Industrial:Manufacturing facilities prioritize heavy-duty degreasers for restroom-adjacent maintenance areas.
- Residential:Consumer preference for convenience formats sustains spray and wipe demand in away-from-home segments.
Commercial applications absorb the dominant procurement volume; healthcare commands the steepest expansion trajectory on compliance intensity.
Consumer Type:
Purchasing authority centralization varies sharply—healthcare consolidates through GPOs while education fragments across district-level procurement.
- Healthcare:Hospital systems leverage group purchasing organization contracts to compress supplier margins while elevating efficacy documentation requirements. EPA-registered sporicidal claims with hydrogen peroxide chemistry address worker safety and surface compatibility concerns.
- Facilities Management:National service providers bundle dispensing equipment with recurring chemical supply contracts, locking in multi-year procurement relationships. Ecolab's institutional channel dominance exemplifies this vertical integration strategy.
- Hospitality:Quick-service restaurant networks specify auto-replenishment thresholds tied to occupancy analytics.
- Education:California and New York school districts mandate third-party environmental certifications such as Green Seal or UL Ecologo.
Facilities management controls the largest contract value; healthcare is climbing the fastest on infection prevention investment.
Form:
Packaging innovation addresses worker safety, dilution error elimination, and inventory automation priorities.
- Wipes:Pre-saturated hydrogen peroxide formats eliminate mixing errors and reduce chemical handling liability in healthcare settings. Metered-dispense packaging convergence addresses Joint Commission documentation requirements while simplifying training for contract cleaning technicians.
- Liquid:Concentrated formulations reduce transportation costs and plastic waste for high-volume commercial accounts. Dilution control systems require capital coordination between chemical suppliers and facilities managers.
- Spray:Aerosol and trigger formats serve residential and light commercial maintenance needs.
- Gel:Viscous formulations cling to vertical surfaces in toilet bowl and urinal applications.
Liquid formats retain the dominant procurement volume; wipes are gaining share fastest on safety and convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes restroom cleaning supplies through acute care networks and national facilities management contracts, while Germany and Japan prioritize chemical safety dossiers and automated dispensing integration. China concentrates volume in transportation infrastructure and hospitality buildouts. Brazil and India expand from commercial cleaning services adoption.
United States
Hospital-grade disinfectant procurement dominates through Group Purchasing Organizations serving acute care networks. The EPA's Safer Choice program and California's Green Cleaning Act restrict volatile organic compound content in public sector contracts. The Upper Midwest hospital systems pilot on-site sodium hypochlorite generators to secure supply continuity.
Germany
Industrial facilities and commercial real estate portfolios drive concentrated formulation demand compatible with automated dispensing. The EU Green Deal and REACH chemical registration requirements mandate comprehensive toxicological screening for institutional buyers. The North Rhine-Westphalia chemical manufacturing cluster supplies reformulated low-VOC chemistry to neighboring Benelux markets.
Japan
Transportation hubs and hospitality chains prioritize no-rinse surfactant chemistry to reduce labor hours per restroom. METI energy efficiency standards influence dispensing equipment specifications in large commercial portfolios. The Kansai region's Osaka-Kobe industrial corridor concentrates contract manufacturing for pre-saturated wipe formats.
China
Railway stations, airports, and new hotel construction absorb bulk liquid concentrates through state procurement frameworks. MEE environmental compliance inspections accelerate shifts away from high-VOC formulations in coastal provinces. The Yangtze River Delta manufacturing belt supplies hydrogen peroxide-based disinfectants to domestic healthcare expansion projects.
Brazil
Commercial cleaning services and quick-service restaurant networks expand pre-saturated wipe adoption amid workforce training gaps. ANVISA antimicrobial registration requirements extend product commercialization timelines for imported formulations. The São Paulo metropolitan area concentrates distribution infrastructure serving Southeast region facilities management contracts.
Restroom Cleaning Supplies Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with institutional channel dominance separating multinational chemical suppliers from regional formulators. The upper tier bundles dispensing hardware with recurring chemical supply contracts, locking in multi-year procurement relationships. Three archetypes prevail: integrated hygiene solutions providers, consumer brand licensors extending into professional segments, and fragrance-integrated deodorizer specialists. Competitive moves concentrate on strategic partnerships with facilities management networks and portfolio diversification into on-site generation equipment.
Within the integrated hygiene tier, Ecolab and Procter & Gamble exemplify divergent channel strategies. Ecolab anchors institutional dominance through captive supply of dispensing systems tied to chemical replenishment. Procter & Gamble occupies a position bridging consumer recognition with licensed professional lines. SC Johnson sits within the fragrance-integrated specialist tier, leveraging deodorizer systems to secure shelf space across retail and contract channels.
| Leading Market Players |
|---|
| Procter & Gamble |
| Church & Dwight |
| Clorox Company |
| Reckitt Benckiser |
| SC Johnson |
| Henkel |
| Unilever |
| Ecolab |
| Kao Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at concentrated hydrogen peroxide manufacturing sites in the United States and Germany shapes both supply concentration and price floors for hospital-grade disinfectants. Scale advantages in quaternary ammonium compound production create tiered entry barriers that compress margins for regional formulators while elevating procurement leverage among national facilities management networks.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between chemical manufacturers and national facilities management networks, with subscription-based replenishment models displacing spot purchasing in multi-site hospitality and retail chains. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered sporicidal formulations from general-purpose cleaners and commodity surfactants. Cost compression in standard-tier concentrates is intensifying because procurement teams at GPO-served hospital systems demand documented contact-time performance without brand premiums. Education facilities in California and New York exhibit highest price sensitivity due to green mandate compliance costs, while acute care networks prioritize efficacy documentation over unit economics.
Supply Chain Analysis
The United States and Germany anchor bulk active ingredient manufacturing for quaternary ammonium compounds and hydrogen peroxide blends serving institutional buyers. Feedstock supply draws from petrochemical derivatives and electrochemical activation hardware components, with formulation chemistry resting on surfactant and chelating agent inputs. Single-source vulnerability concentrates in isopropyl alcohol supply chains for aerosol and wipe manufacturers exposed to derivative pricing volatility. Distribution runs through national chemical distributors and direct institutional contracts, with regional players losing share to integrated inventory management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities concentrate in underpenetrated Sun Belt education facilities and on-site generation equipment services, where procurement centralization has not yet eliminated regional supplier niches. Demand-side shift toward auto-replenishment thresholds tied to occupancy analytics creates service-layer gaps that specialized platforms can exploit.
For Market Incumbents: Shield institutional channel dominance by bundling electrochemical activation hardware with recurring chemical supply contracts, locking in multi-year procurement relationships before capital equipment vendors capture specification authority. Accelerate backward integration into captive surfactant manufacturing to offset feedstock volatility and compress regional formulator margins. Prioritize Green Seal and UL Ecologo certification investments to defend specification position in California and New York public sector contracts against emerging low-VOC specialists. For New Entrants and Emerging Players: On-site sodium hypochlorite generation service gaps in Upper Midwest hospital systems offer white-space entry where legacy suppliers under-invest in capital equipment integration. Target Texas and Florida school district procurement as volume expansion terrain where enrollment growth outpaces legacy supplier contract coverage. Pursue direct-to-facilities sales model bypassing regional distributors lacking integrated inventory management platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with front-loaded toxicological screening capabilities and third-party certification infrastructure. Long-term viability over the projection horizon rests on acquiring formulators with established EPA Safer Choice program relationships and state-level disclosure compliance workflows. Monitor Joint Commission accreditation standard revisions as inflection indicator for sporicidal contact-time requirements that would elevate hydrogen peroxide chemistry premiums.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Generation Equipment Partnership | Bifurcates procurement relationships between chemical manufacturers and capital vendors in hospital systems. |
| Green Chemistry Certification Investment | Secures specification pathways in California's Green Cleaning Act and New York school procurement. |
| Subscription Replenishment Platform Launch | Captures procurement authority from regional distributors in quick-service restaurant networks. |
| Pre-Saturated Wipe Format Expansion | Eliminates dilution error liability while addressing healthcare worker safety documentation requirements. |
| Concentrate Dilution System Retrofit Program | Locks multi-year chemical supply relationships through captive dispensing equipment installation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with procurement directors at national facilities management networks, infection prevention specialists at acute care systems, and chemical formulator R&D leads; alongside secondary validation through EPA FIFRA registration databases, state procurement policy filings, and trade data on surfactant and disinfectant active ingredient flows. Bottom-up triangulation cross-referenced SKU-level pricing intelligence with top-down market sizing from institutional channel shipment patterns.
Across the analysis window, the forecasting framework modeled demand trajectories by product type tier, application vertical, consumer purchasing authority concentration, and packaging format innovation velocity. CAGRs were derived from segment-level volume elasticities tied to healthcare construction spending, education enrollment projections, and green mandate adoption curves. Industry-specific inputs included Joint Commission accreditation standard revision timelines and EPA Safer Choice program expansion patterns.
Forecasts assume regulatory continuity in EPA FIFRA registration requirements and state-level green procurement mandates; material policy shifts in volatile organic compound restrictions or antimicrobial claim documentation would require re-modeling. Recalibration cycles align with material shifts in healthcare-associated infection prevention investment and electrochemical activation technology adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Global Janitorial Cart Market
Cleaning Equipment
US Cleaning Products Market
Cleaning Equipment
Floor Cleaning Device Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Sponge Cloth Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Carpet Cleaner Market