
 Pet Slow Feeder Bowl Market | 2026-2036
Pet Slow Feeder Bowl Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Slow Feeder Bowl Market Analytics
China is rewriting manufacturing dynamics for pet accessories as Guangdong and Zhejiang provinces expand injection-molding and silicone-forming capacity. Outward Hound leverages direct-to-consumer channels to sustain margin control across North America. PetSafe anchors its position through veterinary endorsement programs that build professional credibility. JASGOOD competes aggressively on Amazon marketplace visibility with algorithm-optimized listings.
A pet slow feeder bowl is a purpose-engineered feeding vessel incorporating raised ridges, maze patterns, or compartmentalized channels that extend meal duration from seconds to several minutes, typically constructed from food-grade polymers, stainless steel, or silicone. The device reduces gastric dilatation-volvulus risk in large-breed dogs and addresses feline obesity by mimicking natural foraging behavior. Plastic variants dominate unit volume due to cost accessibility, though stainless steel commands premium shelf positioning in specialty retail. Interactive designs incorporating puzzle elements attract the highest per-unit margins as enrichment-focused consumers trade up from standard configurations. Online retail channels capture the fastest growth trajectory, though pet stores retain tactile advantage for first-time purchasers seeking physical product assessment.
FDA Center for Veterinary Medicine guidelines on food-contact material safety and CPSC lead-content standards directly constrain material selection and supplier qualification processes for brands selling into the United States. The EU REACH framework and California Proposition 65 compliance requirements add parallel testing burdens that favor larger manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving state-level packaging waste legislation and biodegradable material mandates that could force rapid substrate transitions before the forecast horizon concludes.
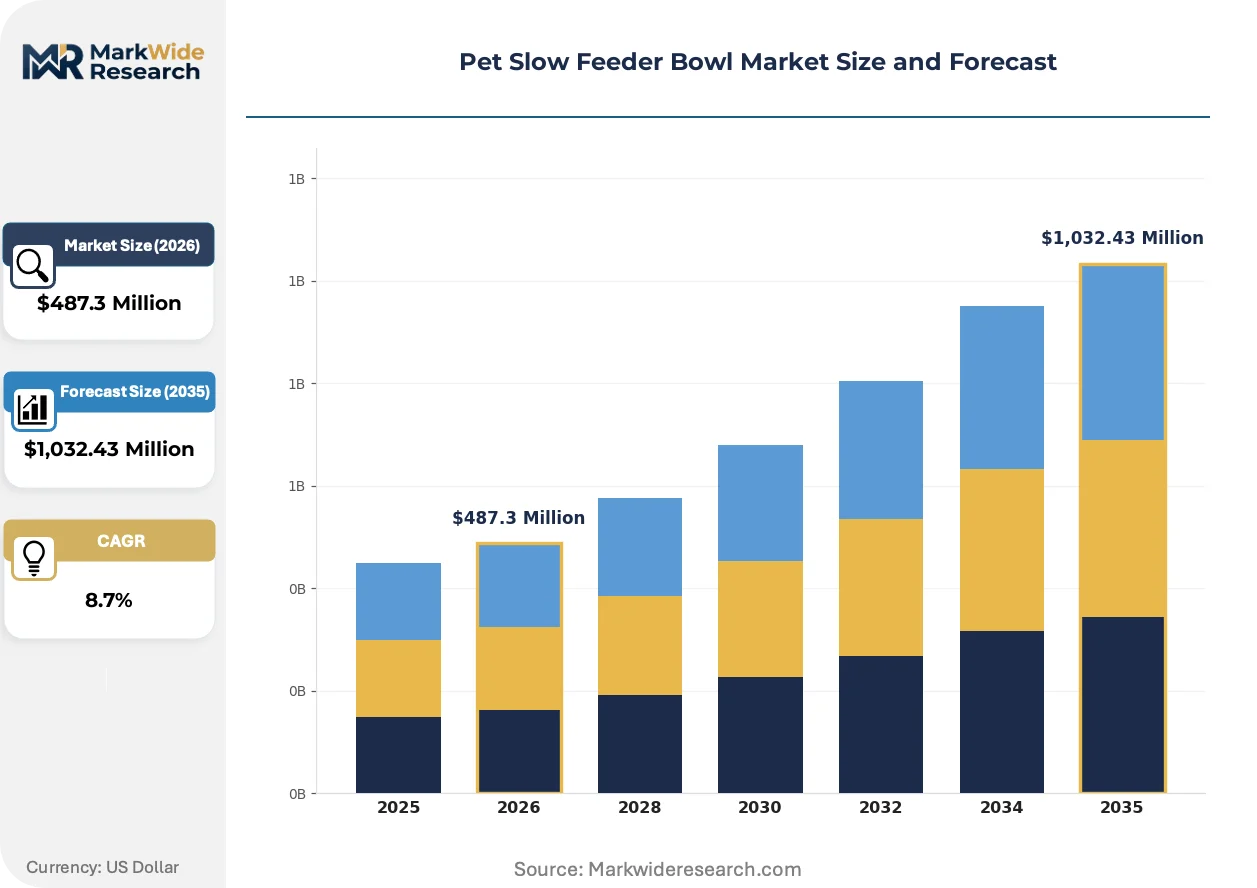
Market Dynamics
Pet humanization is compressing purchase cycles for slow feeder bowls as owners trade single-use plastic for enrichment-grade silicone and stainless steel configurations, forcing manufacturers to recertify material supply chains under tightening FDA and REACH food-contact protocols.
Growth Catalysts
- Veterinary endorsement protocols:Professional recommendation programs build credibility among first-time buyers seeking gastric dilatation-volvulus prevention for large-breed dogs.
- REACH food-contact compliance:EU material safety standards are accelerating supplier qualification investments that lock out low-cost competitors and consolidate shelf positioning for certified brands.
- Guangdong injection-molding clusters:Concentrated tooling capacity in China's Pearl River Delta is collapsing production lead times for maze-pattern and puzzle-element designs.
Market Restraints
- Food-grade silicone input volatility:Medical-grade silicone supply competition from healthcare sectors constrains raw material allocation for pet accessory manufacturers.
- California Proposition 65 litigation exposure:Warning-label requirements for trace chemical content create liability friction that discourages new market entrants.
- Stainless steel price premiums:Alloy cost differentials versus polymer substrates limit mass-market penetration despite superior durability credentials.
Strategic Opportunities
- Biodegradable mandate tailwinds:California and EU packaging waste legislation is creating first-mover advantage for PLA and hemp-composite substrate developers ahead of compliance deadlines.
- Veterinary clinic channel expansion:Direct distribution through animal hospitals captures post-diagnosis recommendation moments for obesity management and bloat prevention.
- Smart bowl convergence:Integration of pressure sensors and mobile-app connectivity with traditional slow-feeder geometry opens subscription-service revenue models.
Industry Challenges
- FDA Center for Veterinary Medicine certification timelines:Extended food-contact material approval cycles delay product launches and compress effective selling seasons.
- Algorithm-dependent marketplace visibility:Amazon A9 search ranking volatility forces continuous advertising expenditure to maintain discoverability against private-label competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Slow Feeder Bowl Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Ceramic, Stainless Steel, Silicone Design Feature: Interactive, Puzzle, Elevated, Standard End User: Dog Owners, Cat Owners, Pet Shelters, Veterinarians Distribution Channel: Online Retail, Pet Stores, Supermarkets, Specialty Shops |
| Companies Covered | Outward Hound, LickiMat, PetSafe, Company of Animals, JASGOOD, Neater Pet Brands, JW Pet Company, Petmate, UPSKY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Slow Feeder Bowl Market Evolving Landscape
Material science advances and channel restructuring are simultaneously elevating product performance expectations and fragmenting how owners discover and purchase feeding accessories.
Medical-grade liquid silicone rubber is collapsing the durability-versus-cost tradeoff that historically segmented premium and mass-market tiers. Specialty retailers and direct-to-consumer brands are adopting this substrate for its temperature resistance and dishwasher safety. The technology is collapsing replacement-frequency assumptions that previously sustained plastic-volume business models.
EU REACH Annex XVII restrictions on phthalates and heavy metals are forcing substrate transitions across export-oriented manufacturers. Compliance testing burdens favor producers with dedicated regulatory affairs capacity and existing laboratory relationships. Small-batch importers serving the United States market are most affected, with many exiting rather than absorbing certification costs.
Subscription-box curation is displacing single-item search-and-purchase behavior among millennial and Gen-Z pet owners. BarkBox and similar services bundle slow feeders with treats and toys, reducing direct brand discovery through traditional retail. This pattern concentrates most visibly in coastal United States metropolitan markets where pet humanization indices run highest.
Pet Slow Feeder Bowl Market Segmentation
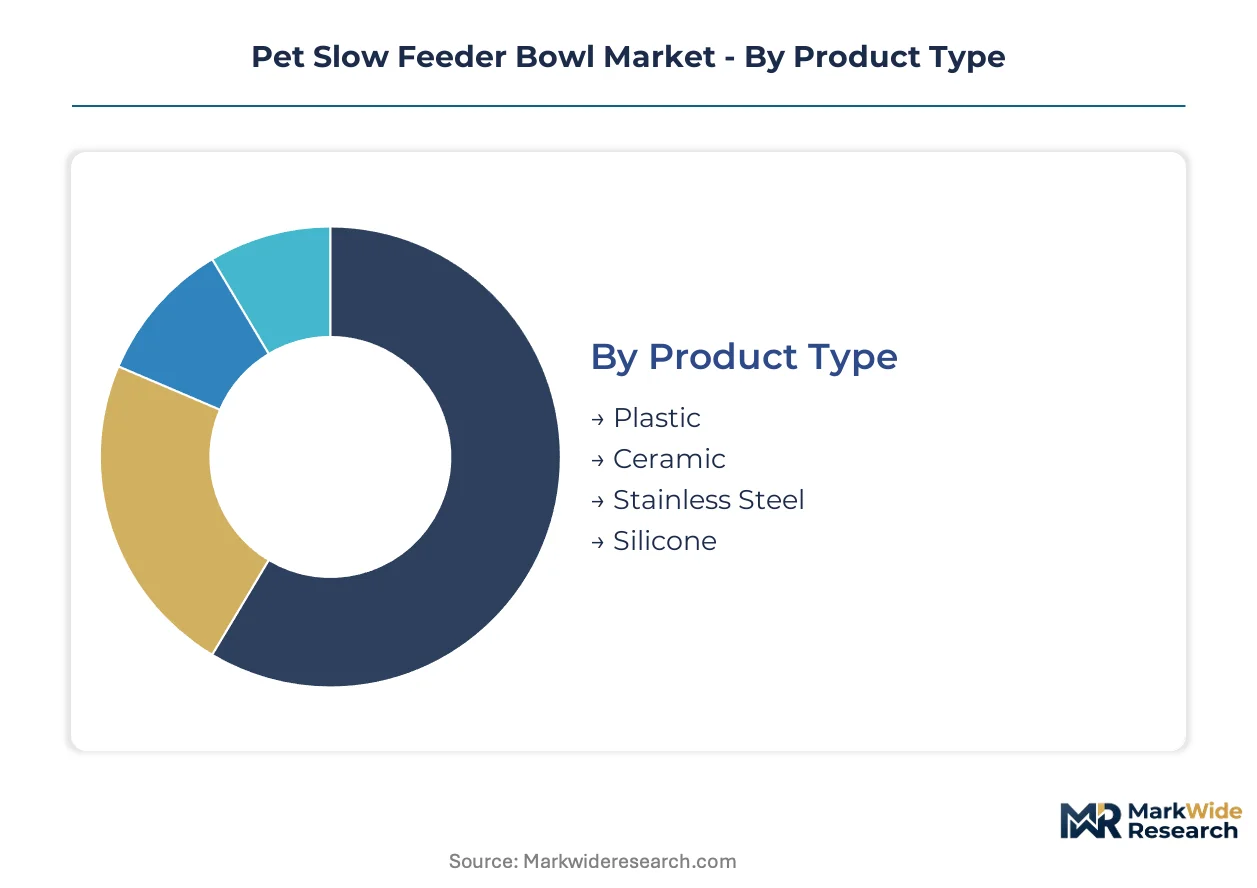
Segmentation in the pet slow feeder bowl market reveals how material science, behavioral design, and channel economics fragment purchasing decisions. Manufacturers must align substrate certifications, veterinary endorsement strategies, and retail format capabilities to capture value across distinct buyer workflows.
Product Type:
After-sales-service intensity varies sharply by substrate durability and replacement frequency, with warranty claims and customer support demands scaling inversely with material longevity.
- Plastic:Injection-molded polypropylene and ABS variants dominate unit shipments through mass-market channels. Demand concentrates in price-sensitive households and multi-pet environments where frequent replacement is acceptable; CPSC lead-content testing adds compliance overhead that favors larger importers with established laboratory relationships.
- Stainless Steel:Food-grade 304 and 316 alloys deliver dishwasher-safe durability with minimal bacterial retention. Veterinary clinics and premium pet hotels in the United States specify this substrate for large-breed gastric dilatation-volvulus prevention programs; alloy cost premiums constrain penetration below the mass-market tier.
- Silicone:Medical-grade liquid silicone rubber offers temperature resistance from -40°C to 230°C with collapsible designs for travel. FDA food-contact certification requirements favor manufacturers with dedicated regulatory affairs capacity.
- Ceramic:Glazed stoneware appeals to design-conscious owners seeking aesthetic integration with home décor. Weight and fragility limit commercial and travel applications.
Plastic holds the largest share; momentum sits with silicone as pet humanization trends compress replacement cycles toward enrichment-grade substrates.
Design Feature:
Margin structures diverge dramatically by cognitive engagement level, with puzzle-element configurations commanding three to five times the per-unit contribution of basic ridge patterns.
- Interactive:Motorized or sensor-activated dispensers that respond to paw pressure or nose contact, extending feeding duration through adaptive difficulty. Smart bowl convergence with pressure sensors and mobile-app connectivity is opening subscription-service revenue models in coastal United States metropolitan markets.
- Puzzle:Static maze patterns requiring sequential problem-solving to access kibble, mimicking natural foraging behavior most intensively. Veterinary obesity management protocols in Germany and France increasingly specify these designs for post-diagnosis dietary intervention.
- Elevated:Raised platforms angled at 15-30 degrees to reduce neck strain and improve digestion posture. Geriatric dog owners and brachycephalic breed specialists drive specification.
- Standard:Simple raised ridges or compartmentalized channels without variable difficulty. Entry-level positioning captures first-time slow feeder purchasers.
Puzzle configurations generate the highest margins; interactive designs are expanding most quickly as technology integration accelerates.
End User:
Procurement authority and volume scale separate consumer-driven replacement purchases from institutional specification decisions with multi-year contract horizons.
- Dog Owners:Large-breed gastric dilatation-volvulus risk awareness drives premium substrate adoption; golden retriever and German shepherd owner communities show highest enrichment-grade conversion rates.
- Cat Owners:Feline obesity intervention and whisker fatigue mitigation concentrate demand in puzzle and shallow-wide configurations; single-cat households outspend multi-cat environments per capita.
- Pet Shelters:High-volume, high-durability requirements favor stainless steel with minimal crevices for sanitation efficiency; procurement runs through municipal and nonprofit funding cycles with formal RFP processes.
- Veterinarians:Post-diagnosis recommendation moments for bloat prevention and weight management create trusted endorsement channels; FDA Center for Veterinary Medicine material safety compliance is non-negotiable for clinic retail.
Dog owners hold the largest share; veterinarians are gaining share fastest through professional credibility transfer.
Distribution Channel:
Discovery mechanics and tactile assessment requirements shape channel economics, with first-time purchasers favoring physical evaluation and repeat buyers shifting toward algorithmic convenience.
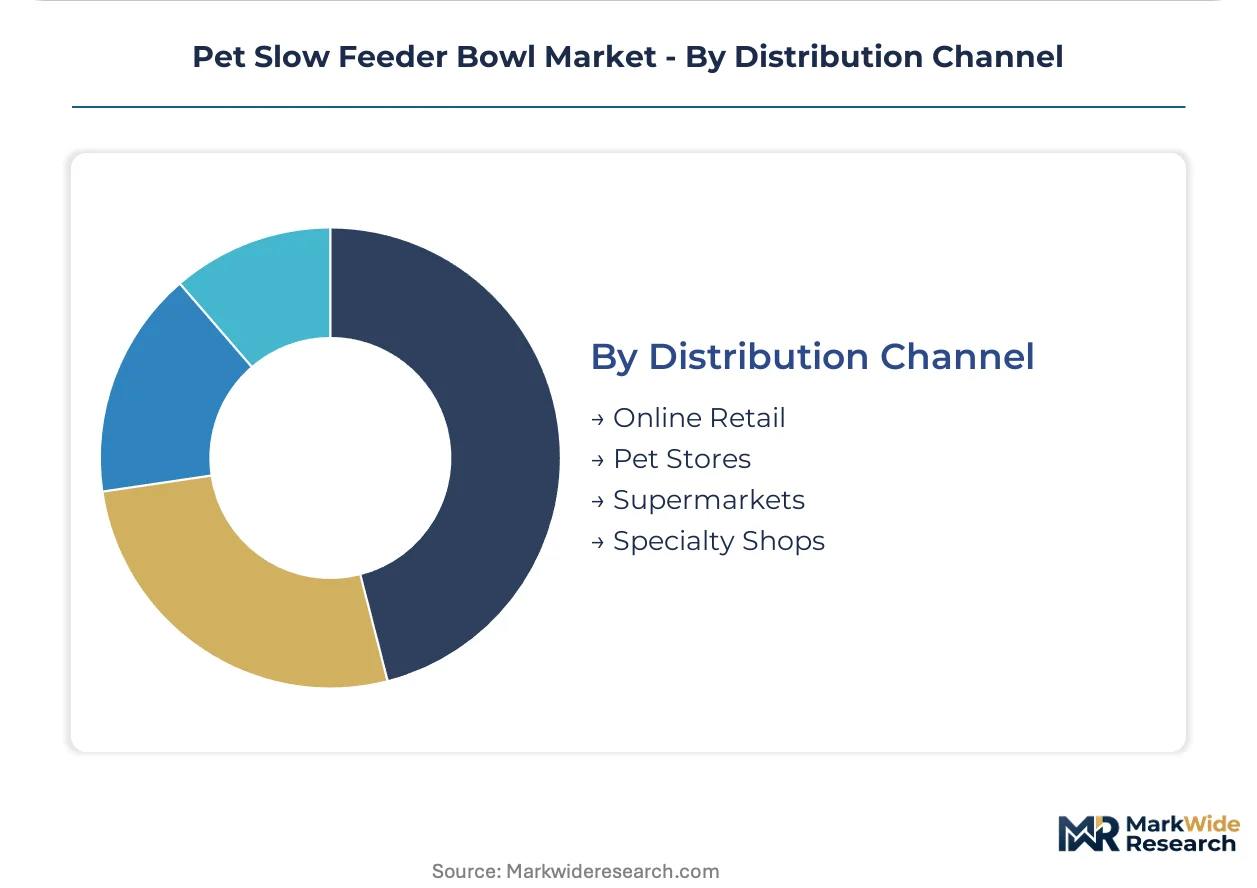
- Online Retail:Amazon marketplace visibility and subscription-box curation displace single-item search behavior among millennial and Gen-Z owners; algorithm-dependent ranking forces continuous advertising expenditure to maintain discoverability.
- Pet Stores:Tactile product assessment and staff consultation retain advantage for first-time purchasers; specialty retailers in the United States and United Kingdom are consolidating shelf positioning around certified brands with REACH compliance documentation.
- Supermarkets:Mass-market plastic variants with impulse-purchase pricing capture routine shopping trip conversion; limited SKU depth constrains premium substrate representation.
- Specialty Shops:Boutique pet lifestyle retailers curate design-forward ceramic and silicone configurations for urban affluent demographics; personalized service justifies price premiums.
Online retail holds the largest share; specialty shops are climbing the fastest as pet humanization deepens experience-oriented purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine guidelines on food-contact material safety anchor demand formation in the United States, while EU REACH compliance and China's injection-molding capacity expansion reshape supply-side geography across the analysis window.
United States
Premium pet care spending concentrates in coastal metropolitan markets where pet humanization indices drive enrichment-grade silicone adoption. California Proposition 65 warning-label requirements for trace chemical content create liability friction that favors established importers with dedicated regulatory affairs capacity. FDA certification timelines compress effective selling seasons for new entrants.
China
Guangdong and Zhejiang provinces dominate injection-molding and silicone-forming capacity for maze-pattern and puzzle-element designs. GB standards on food-contact plastics and SAMR market supervision protocols constrain export-oriented manufacturers serving Western markets. Pearl River Delta tooling clusters collapse production lead times for complex geometries.
Germany
Veterinary obesity management protocols increasingly specify puzzle-configuration slow feeders for post-diagnosis dietary intervention. EU REACH Annex XVII restrictions on phthalates and heavy metals force substrate transitions among export manufacturers. KBA and federal consumer protection frameworks extend testing burdens to pet accessory imports.
United Kingdom
Specialty retailers consolidate shelf positioning around certified brands with REACH compliance documentation. Feline obesity intervention drives demand for shallow-wide ceramic configurations in urban affluent demographics. London and Southeast England concentrate boutique pet lifestyle retail with personalized service premiums.
Japan
METI industrial standards and PMDA material safety protocols elevate certification requirements for imported pet accessories. Kansai and Tokyo metropolitan areas concentrate design-conscious owners seeking aesthetic integration with home décor. Single-cat household density outpaces multi-pet environments in per-capita enrichment spending.
Pet Slow Feeder Bowl Market Competitive Landscape
Capability concentration sits with veterinary-endorsed premium brands; scale advantage sits with algorithm-optimized marketplace operators. The vendor base organizes around three strategic archetypes: direct-to-consumer specialists leveraging margin control, veterinary-channel anchors building professional credibility, and Amazon-native competitors optimizing search visibility. Dominant competitive moves include regulatory certification investments that lock out low-cost rivals and subscription-box bundling that displaces single-item discovery.
Within the veterinary-endorsement tier, PetSafe occupies a position exemplifying professional credibility transfer through animal hospital channels. Outward Hound and JASGOOD represent contrasting scale strategies: the former anchors direct-to-consumer positioning across North America, while the latter exemplifies algorithm-dependent marketplace visibility optimization. LickiMat and Company of Animals sit within the enrichment-specialist archetype, their geographic origins suggesting differentiated regional supply relationships.
| Leading Market Players |
|---|
| Outward Hound |
| LickiMat |
| PetSafe |
| Company of Animals |
| JASGOOD |
| Neater Pet Brands |
| JW Pet Company |
| Petmate |
| UPSKY |
| Others |
Value Network & Pricing Analysis
Guangdong injection-molding clusters in China's Pearl River Delta compress production lead times for maze-pattern and puzzle-element designs, translating tooling efficiency into downstream margin capture for brands with FDA-certified supply chains. REACH compliance investments and California Proposition 65 litigation exposure stratify pricing power between certified incumbents and low-cost importers facing exit pressures.
Pricing Analysis
Coastal United States metropolitan markets command 40-60% premiums over mass-market channels for medical-grade silicone configurations, while plastic variants in supermarket impulse displays anchor the economy tier. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-endorsed stainless steel from Amazon-optimized private-label imports. Cost compression in polymer substrates is intensifying because healthcare sectors compete for medical-grade silicone allocation. First-time purchasers through pet specialty stores show lowest price sensitivity; multi-pet households in mass-market channels exhibit highest elasticity.
Supply Chain Analysis
Pearl River Delta contract manufacturers in Guangdong and Zhejiang provinces hold dominant injection-molding and silicone-forming capacity for export-oriented brands serving Western markets. Raw material flows draw from Saudi petrochemical feedstocks for polypropylene, German silicone precursors for medical-grade LSR, and Australian nickel for 304 stainless steel alloys. Single-source vulnerability concentrates in FDA-certified silicone compounders with limited alternative qualification pathways. Distribution runs through Amazon marketplace fulfillment centers for repeat purchasers, while veterinary clinic direct distribution captures post-diagnosis recommendation moments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-box bundling and smart-bowl sensor integration are shifting discovery economics from search-based retail to curated ecosystem platforms, creating interoperability dependencies that favor vertically integrated hardware-software players.
For Market Incumbents: Harden regulatory certification moats by accelerating FDA Center for Veterinary Medicine pre-submissions ahead of material safety guideline revisions. Deepen backward integration into medical-grade silicone compounding to secure allocation priority against healthcare sector competition. Lock veterinary clinic channel exclusivity through post-diagnosis recommendation protocols that transfer professional credibility. For New Entrants and Emerging Players: Pursue biodegradable substrate white-space ahead of California and EU packaging waste compliance deadlines, where PLA and hemp-composite developers face limited incumbent competition. Target feline obesity intervention segments in Japan and Germany, where single-cat household density and veterinary protocol adoption outpace supply. Anchor go-to-market through BarkBox-style subscription curation rather than algorithm-dependent Amazon visibility. For Investors and Strategic Acquirers: Long-term, this sits as a pet humanization infrastructure play because enrichment-grade substrate conversion and veterinary-channel credibility transfer compound defensibility across replacement cycles. Acquisition candidates cluster around REACH-certified manufacturers with dedicated regulatory affairs capacity and existing laboratory relationships. Watch FDA certification timeline compression as inflection signal—accelerated approval cycles would unlock working capital efficiency for scaled players.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Endorsement Program Expansion | PetSafe's animal hospital channel builds professional credibility transfer for bloat prevention recommendations. |
| Direct-to-Consumer Platform Launch | Outward Hound's margin control across North America bypasses retailer margin stacking and price transparency. |
| Smart Bowl Sensor Integration | Pressure sensor and mobile-app connectivity opens subscription-service revenue models in coastal metropolitan markets. |
| Biodegradable Substrate Development | PLA and hemp-composite innovation captures first-mover advantage ahead of California packaging waste mandates. |
| REACH Compliance Certification Investment | EU Annex XVII testing documentation locks out low-cost competitors and consolidates specialty retail shelf positioning. |
Research Methodology
Operator-level perspectives from pet product brand managers, veterinary clinic procurement officers, Amazon marketplace sellers, injection-molding plant engineers, and regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, EU REACH Annex XVII restriction lists, CPSC lead-content enforcement actions, and customs trade data on pet accessory imports. Bottom-up demand modeling triangulated against top-down category spending estimates across the analysis window.
Scenario-bracketing framed volume and value outputs across material type, design feature complexity, end-user procurement authority, and distribution channel format dimensions. CAGRs derived from segment-level growth rate reconciliation with aggregate category expansion patterns. Veterinary endorsement penetration rates and subscription-box bundling velocity served as industry-specific forecast inputs throughout the projection horizon.
Sensitivities concentrate around FDA certification timeline volatility, medical-grade silicone supply competition from healthcare sectors, and algorithm-dependent Amazon ranking stability. Forecasts reflect documented assumptions on pet humanization index trajectory and regulatory compliance cost absorption capacity. Quarterly review of veterinary protocol adoption rates, state-level packaging waste legislation progression, and injection-molding capacity utilization in Guangdong is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Pet Pens Market
Pet Care Products
Pet Apparel Market
Pet Care Products
Pet Calming Products Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Omega-3 Pet Supplement Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Pet Toys Market
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Germany Pet Training Services Market