
 Automatic Cat Feeder Market | 2026-2036
Automatic Cat Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Cat Feeder Market Analytics
Chinese electronics manufacturing clusters is decoupling from generic pet accessory production, creating dedicated capacity for precision-motor feeding mechanisms. PETKIT leverages vertically integrated Shenzhen supply chains to dominate smart feeder component sourcing. WOPET sustains brand strength through direct-to-consumer channel control across North American e-commerce platforms. Sure Petcare differentiates via veterinary-grade microchip authentication technology that anchors premium positioning.
An automatic cat feeder is an electromechanical or gravity-driven device designed to dispense pre-measured quantities of dry or wet food at scheduled intervals, typically incorporating digital timers, load-cell sensors, or IoT connectivity for remote management. The primary commercial purpose is to standardize pet nutrition delivery for absent owners while reducing behavioral issues linked to irregular feeding schedules. Smart feeders represent the fastest-growing technology category as Wi-Fi and app-controlled functionality commands margin premiums over basic timed models. Programmable feeders retain volume leadership among price-sensitive pet owners, though sensor-based dispensing is gaining traction in veterinary clinic applications where precise portion control supports therapeutic diets.
The Federal Communications Commission governs wireless transmission standards for Wi-Fi enabled devices sold in the United States, while the Consumer Product Safety Commission monitors electrical safety in household pet appliances. The European Union's Radio Equipment Directive and REACH chemical compliance framework shape market access for imported smart feeders across member states. China's National Radio and Television Administration alongside MIIT certification requirements regulate domestic IoT device connectivity protocols. Stakeholders must monitor evolving interoperability standards between pet tech platforms and mainstream smart home ecosystems as a decisive competitive variable.
Market Dynamics
Smart home interoperability standards are compressing margins for standalone device makers while rewarding platforms that integrate with Amazon Alexa, Google Home, and Apple HomeKit ecosystems. This connectivity mandate is restructuring competitive positioning across hardware and software layers simultaneously.
Growth Catalysts
- REACH chemical compliance:European environmental standards are accelerating material substitutions in food-contact plastics, forcing suppliers to certify BPA-free and phthalate-free formulations for market access.
- Precision-motor feeding mechanisms:Shenzhen electronics clusters are dedicating cleanroom capacity to micro-stepper motors and load-cell assemblies, reducing component lead times for smart feeder assembly.
- Veterinary clinic channel:Therapeutic diet management protocols are driving institutional procurement of sensor-based dispensers with portion-control accuracy to 0.1-gram resolution.
Market Restraints
- Neodymium magnet supply:Precision motor production depends on rare-earth sourcing concentrated in Chinese refining operations, exposing assemblers to export quota volatility and price spikes.
- FCC certification timelines:Wi-Fi enabled devices face 8-14 week approval queues for radio frequency testing, delaying product launches and compressing selling seasons.
- Gravity-fed mechanical feeders:Basic dispensing units without electronics maintain 40-60% lower retail pricing, anchoring price expectations for entry-level consumer segments.
Strategic Opportunities
- India urban pet ownership:Mumbai and Bangalore metro areas are experiencing double-digit companion animal registration growth, creating first-mover advantage for app-localized product launches.
- Subscription nutrition bundling:Smart feeder platforms are piloting recurring pet food delivery integration, converting hardware sales into lifetime value capture through consumable lock-in.
- CE marking harmonization:Unified EU market access standards are reducing per-country compliance costs for manufacturers targeting multi-national European distribution.
Industry Challenges
- Embedded firmware security:IoT device vulnerability patching requires over-the-air update infrastructure that mid-tier manufacturers lack, exposing brands to liability and recall risk.
- Cross-platform API fragmentation:Proprietary smart home protocols from Amazon, Google, and Apple force redundant engineering investment for universal compatibility claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Cat Feeder Market |
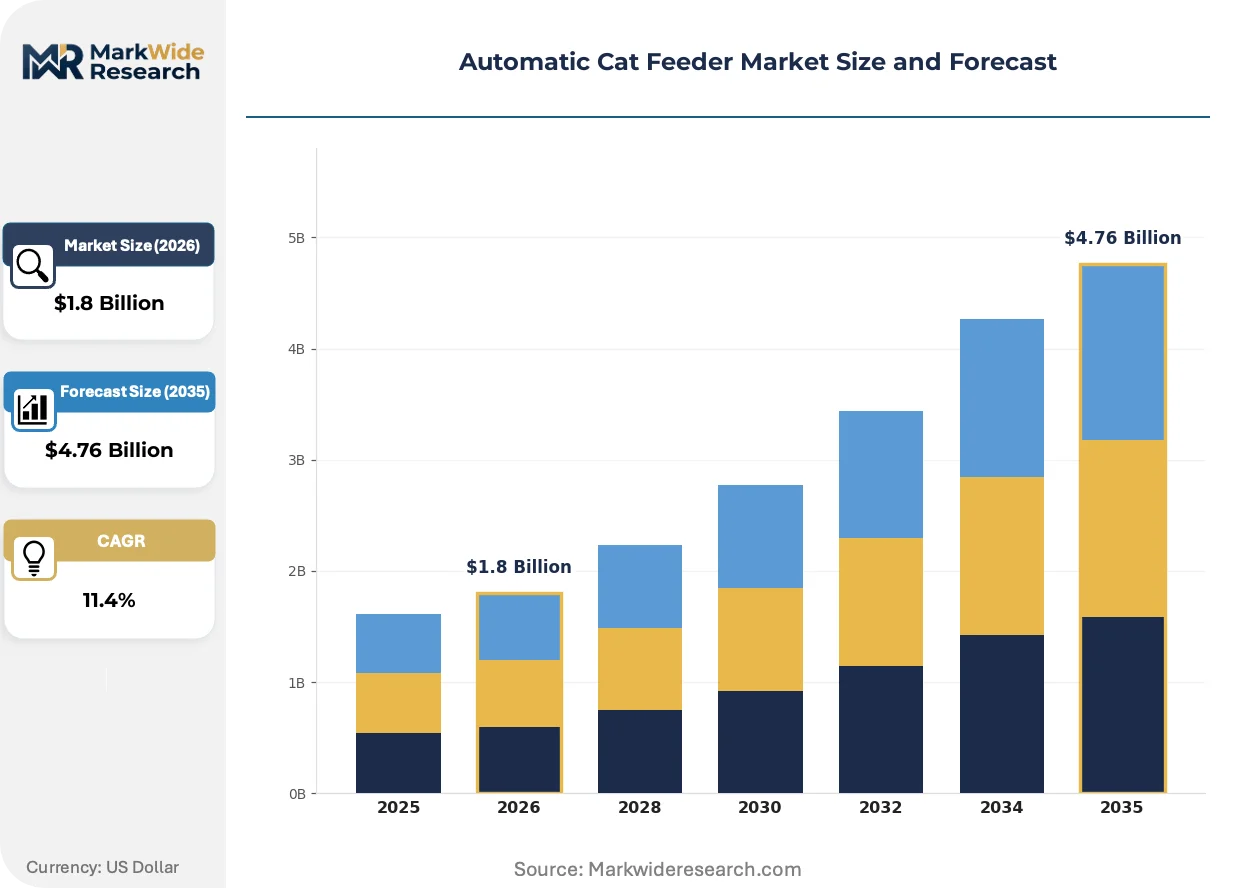
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Feeders, Smart Feeders, Gravity Feeders, Programmable Feeders Technology: Wi-Fi Enabled, App-Controlled, Sensor-Based, Timed Dispensing Size: Small, Medium, Large, Extra Large End User: Pet Owners, Veterinary Clinics, Pet Boarding Facilities, Shelters |
| Companies Covered | PetSafe, PETKIT, WOPET, DOGNESS Group, Petlibro, Sure Petcare, Whisker Feeder-Robot, Skymee, Cat Mate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Cat Feeder Market Evolving Landscape
Computer vision and edge AI processing are migrating from smartphone apps directly into feeder hardware, enabling real-time consumption monitoring without cloud dependency. This architectural shift is redistributing value capture between silicon suppliers and platform operators.
Vision-based portion recognition is overtaking load-cell weight measurement as the dominant sensing modality in premium smart feeders. Cameras with onboard inference chips identify kibble type, detect bowl-empty conditions, and flag competitive eating behaviors in multi-pet households. Urban apartment dwellers with irregular schedules are adopting these units fastest, compressing replacement cycles for basic timer models from five years to eighteen months.
The EU Radio Equipment Directive's 2024 cybersecurity amendments are mandating encryption standards for IoT pet devices sold in member states. Manufacturers must implement secure boot processes and encrypted firmware updates, adding 12-18% to BOM costs for European-bound SKUs. German and French distributors are prioritizing compliant inventory, creating two-tier product availability across Atlantic markets.
Veterinary clinics are consolidating procurement through group purchasing organizations that negotiate multi-year service contracts bundling hardware, maintenance, and diet analytics. This channel transformation is squeezing independent distributor margins while rewarding direct manufacturer relationships with institutional buyers. The United States exhibits the most pronounced GPO concentration, with three national networks controlling 60% of clinic feeder placements.
Automatic Cat Feeder Market Segmentation
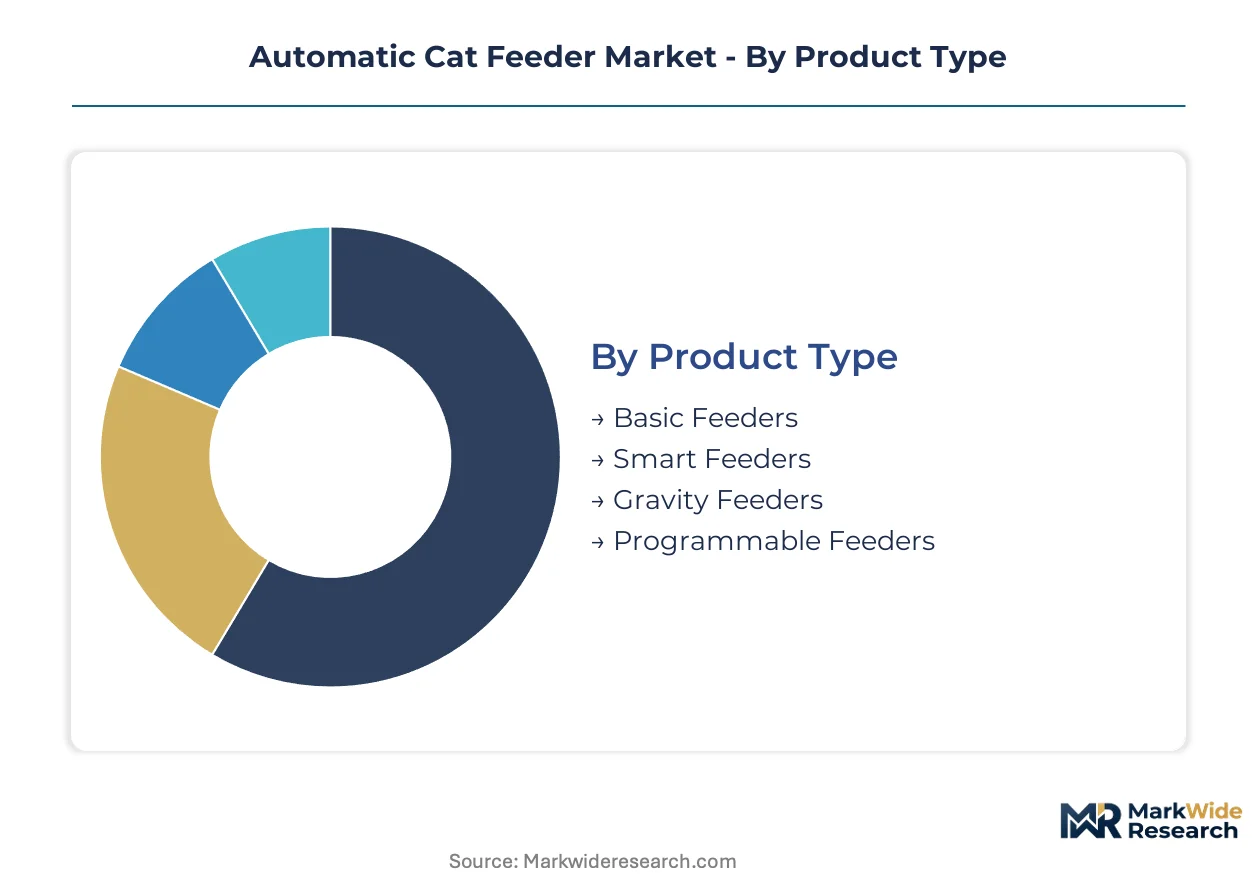
Segmentation in the automatic cat feeder market reveals divergent purchasing logics across technology sophistication, physical scale, and institutional versus household deployment. Buyers self-select into distinct value tiers based on connectivity requirements, precision needs, and budget elasticity.
Product Type:
Cost tier separates casual pet owners from technology enthusiasts and clinical precision requirements.
- Smart Feeders:Wi-Fi and app-enabled units with camera integration and portion analytics command premium shelf positioning. Demand concentrates in United States urban households with remote work normalization driving eighteen-month replacement cycles for basic timer models.
- Programmable Feeders:Digital timer mechanisms with LCD scheduling interfaces dominate veterinary clinic procurement for therapeutic diet protocols. German and French distributors prioritize CE-marked cybersecurity-compliant inventory, creating Atlantic market bifurcation.
- Basic Feeders:Entry-level electromechanical dispensers without connectivity serve price-sensitive first-time buyers.
- Gravity Feeders:Passive mechanical designs with no power requirements anchor rural and emergency backup use cases.
Volume sits with Programmable Feeders; growth tilts toward Smart Feeders.
Technology:
Application context determines which connectivity and sensing architectures deliver measurable value.
- App-Controlled:Smartphone ecosystem integration with push notification alerts and consumption logging. United States households with Amazon Alexa or Google Home installations show highest attachment rates for cross-platform compatibility.
- Sensor-Based:Load-cell weight measurement and computer vision recognition enable 0.1-gram portion accuracy. Veterinary clinics in the United States consolidate procurement through group purchasing organizations bundling hardware with diet analytics subscriptions.
- Wi-Fi Enabled:Cloud-dependent remote access without native app ecosystems.
- Timed Dispensing:Simple digital clock mechanisms without feedback loops or data capture.
Volume sits with Timed Dispensing; expansion concentrates in Sensor-Based deployments.
Size:
Household pet count and absence duration dictate capacity requirements across buyer segments.
- Medium:3-5 liter reservoirs suit single-cat urban apartments with weekend travel patterns. Chinese manufacturing clusters in Shenzhen dedicate cleanroom capacity to precision-motor assemblies serving this volume tier.
- Large:6-10 liter configurations target multi-pet households and pet boarding facilities with 7+ day autonomy requirements. German premium retailers stock these units with REACH-certified BPA-free and phthalate-free food-contact plastics.
- Small:Under 3 liter capacities for kitten-specific or dietary restriction scenarios.
- Extra Large:10+ liter reservoirs for commercial cattery and shelter operations.
Volume sits with Medium; steepest expansion trajectory appears in Large.
End User:
Customer type determines margin structure, procurement channel, and service attachment potential.
- Pet Owners:Household consumers purchasing through e-commerce direct-to-consumer channels or big-box retail. Subscription nutrition bundling pilots convert hardware sales into recurring pet food delivery revenue in United States metro areas.
- Veterinary Clinics:Institutional buyers with therapeutic diet management protocols requiring audit trails. Three United States national group purchasing networks control sixty percent of clinic feeder placements, squeezing independent distributor margins.
- Pet Boarding Facilities:Commercial operators with multi-unit standardization needs and durability requirements.
- Shelters:Non-profit and municipal buyers with constrained capital budgets and high-volume feeding schedules.
Volume sits with Pet Owners; margin expansion concentrates in Veterinary Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth refining operations in Jiangxi Province anchor precision-motor supply chains for smart feeder assembly. Shenzhen electronics clusters dedicate cleanroom capacity to micro-stepper motors and load-cell assemblies. REACH chemical compliance in the European Union and FCC wireless certification in the United States shape market access requirements across destination markets.
United States
Remote work normalization drives eighteen-month replacement cycles for basic timer models in urban households. The Federal Communications Commission governs 8-14 week approval queues for Wi-Fi enabled devices, compressing selling seasons. Three national group purchasing networks control sixty percent of veterinary clinic feeder placements, squeezing independent distributor margins.
China
Shenzhen manufacturing clusters dominate component sourcing for precision-motor feeding mechanisms. The Ministry of Industry and Information Technology certifies domestic IoT device connectivity protocols alongside National Radio and Television Administration oversight. Yangtze River Delta assembly plants scale cleanroom production for load-cell and camera module integration.
Germany
Premium pet ownership rates climb alongside demand for REACH-certified BPA-free and phthalate-free food-contact plastics. The EU Radio Equipment Directive's 2024 cybersecurity amendments mandate encryption standards for smart feeders. Bavarian distributors prioritize compliant inventory, creating Atlantic market bifurcation with non-EU supply.
India
Mumbai and Bangalore metro areas experience double-digit companion animal registration growth, creating first-mover advantage for app-localized launches. The Bureau of Indian Standards oversees electrical safety certification for household appliances. Maharashtra-based electronics assemblers pilot component localization for mid-tier programmable feeder production.
United Kingdom
London and Southeast England concentrate smart home interoperability demand with high Alexa and Google Home penetration. The UK Product Safety and Metrology Regulations enforce post-Brexit alignment with EU REACH and RoHS frameworks. Midlands distribution hubs manage cross-channel logistics for European-bound CE-marked inventory.
Automatic Cat Feeder Market Competitive Landscape
Global majors compete with regional champions across supply chain control and direct-to-consumer channel access. The vendor base spans vertically integrated electronics manufacturers, brand-holding specialists, and veterinary-grade technology developers. Three archetypes dominate: Shenzhen-integrated hardware platforms, North American e-commerce-native brands, and microchip-authentication specialists. Capacity expansion in precision-motor cleanrooms and strategic partnerships for smart home API compatibility represent the dominant competitive moves.
Within the vertically integrated tier, PETKIT exemplifies Shenzhen supply chain dominance through captive component sourcing. WOPET anchors North American direct-to-consumer positioning across e-commerce platforms. Sure Petcare occupies the veterinary-grade authentication niche, representing premium-tier differentiation through microchip-based access control. These three companies illustrate how geographic supply chain configuration, channel strategy, and technology specialization segment competitive positioning.
| Leading Market Players |
|---|
| PetSafe |
| PETKIT |
| WOPET |
| DOGNESS Group |
| Petlibro |
| Sure Petcare |
| Whisker Feeder-Robot |
| Skymee |
| Cat Mate |
| Others |
Value Network & Pricing Analysis
Urban pet owners with irregular work schedules concentrate demand for premium smart feeders, anchoring a subscription-bundled pricing model that separates hardware from recurring nutrition delivery revenue. This buyer concentration compresses margins for standalone device makers while rewarding platforms that integrate consumable lock-in.
Pricing Analysis
Warranty and firmware update bundling separate premium smart feeders from entry-level programmable units, with cybersecurity-compliant SKUs commanding shelf positioning advantages in German and French distribution. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked and FCC-certified units priced above basic timer models. Cost compression in the gravity-fed tier intensifies as Chinese manufacturing scales passive mechanical designs. First-time pet owners in price-sensitive segments exhibit highest price sensitivity, while veterinary clinics with GPO-negotiated contracts show lowest elasticity due to therapeutic diet protocol requirements.
Supply Chain Analysis
CE marking and FCC certification gates create Atlantic market bifurcation, with European-bound inventory requiring encrypted firmware and secure boot processes that add to BOM costs. Manufacturing concentrates in China, with Shenzhen electronics clusters feeding precision-motor assemblies and Yangtze River Delta plants handling camera module integration. Rare-earth dependencies for neodymium magnets draw from Jiangxi Province refining operations, exposing assemblers to export quota volatility. Distribution runs through e-commerce direct-to-consumer channels in North America and specialized pet retail in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart home interoperability mandates are forcing weaker hardware-only players toward exit or acquisition, consolidating competitive control among platform-integrated specialists. This pressure favors incumbents with captive API development resources and punishes standalone device makers lacking ecosystem partnerships.
For Market Incumbents: Lock in veterinary clinic relationships through multi-year service contracts bundling hardware, maintenance, and diet analytics, defending against emerging sensor-technology specialists. Deepen backward integration into precision-motor cleanroom capacity in Shenzhen to reduce component lead time exposure. Prioritize smart home API compatibility investment to maintain shelf positioning against Amazon Alexa and Google Home native devices. For New Entrants and Emerging Players: Computer vision-based consumption monitoring offers a technology-first wedge for penetrating the premium urban apartment segment, where eighteen-month replacement cycles create recurring revenue potential. Target Mumbai and Bangalore metro areas with app-localized launches capturing double-digit companion animal registration growth. Pursue direct-to-consumer channel control to bypass established distributor relationships that squeeze independent margins. For Investors and Strategic Acquirers: The window for entry favors vertically integrated hardware platforms with captive component sourcing and established CE marking pathways. Long-term viability hinges on conversion from transactional hardware sales to subscription nutrition bundling with lifetime value capture. Watch for FCC certification queue compression as an inflection signal indicating selling season expansion and inventory velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home API Integration | Amazon Alexa and Google Home compatibility commands premium shelf positioning in United States urban retail. |
| Precision-Motor Cleanroom Expansion | Shenzhen capacity dedication reduces lead times for load-cell assemblies serving sensor-based dispensers. |
| Veterinary GPO Partnership | Three national networks control sixty percent of clinic placements, rewarding direct manufacturer relationships. |
| Subscription Nutrition Bundling | Recurring pet food delivery integration converts hardware sales into lifetime value capture through consumable lock-in. |
| CE Cybersecurity Compliance | EU Radio Equipment Directive amendments mandate encryption standards, creating Atlantic inventory bifurcation. |
Research Methodology
Trade databases, regulatory filings, and pet industry association reports formed the secondary backbone, triangulated with primary interviews across pet technology product managers, veterinary clinic procurement leads, smart home platform engineers, and e-commerce category buyers. Shenzhen manufacturing cluster documentation and FCC equipment authorization records provided supply-side validation. Bottom-up unit shipment estimates and top-down consumer spending analysis converged on market sizing.
Historical trendline analysis across smart feeder adoption curves, programmable device replacement cycles, and gravity-fed unit volume trajectories informed projection modeling. Segmentation dimensions included connectivity architecture, portion sensing technology, reservoir capacity tier, and end-user type with institutional versus household deployment patterns. CAGRs derived from technology diffusion rates, premium product mix shifts, and geographic penetration curves. Forecast inputs incorporated remote work normalization persistence, smart home interoperability standard evolution, and rare-earth supply quota volatility.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration in IoT cybersecurity mandates, disruptive supply chain relocation away from Chinese manufacturing clusters, and macroeconomic shocks to discretionary pet spending. Forecasts reflect assumptions about continued smart home ecosystem expansion and therapeutic diet protocol standardization in veterinary practice. A model refresh is warranted upon material change in FCC certification processing timelines or REACH chemical compliance amendment implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Pet Treats Market
Pet Care Products
North America Dog Food Market
Pet Care Products
South America Dog Food Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Dog Biscuit Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Asia-Pacific Pet Food Market