
 UK Pet Grooming Market | 2026-2036
UK Pet Grooming Market Size, Share, and Industry Trends Forecast 2026-2036
UK Pet Grooming Market Analytics
Affluent urban households with small-breed dogs is reorganizing demand patterns across the UK pet grooming sector. Spectrum Brands leverages its multi-channel distribution to sustain shelf presence in major retail chains. Beaphar BV anchors the professional-grade product segment through veterinary-aligned formulations. Company of Animals Ltd. differentiates via behavioral training-integrated grooming tools that address anxiety-prone pets.
UK pet grooming encompasses hygiene maintenance, coat management, and cosmetic styling performed on companion animals using species-specific tools, pH-balanced formulations, and mechanical or hand-operated equipment designed for safe animal handling. Shampoos and conditioners formulated for dermatological sensitivity dominate product value pools, while clippers and precision blades command premium pricing in professional channels. Mobile services represent the fastest-growing distribution channel, capitalizing on convenience-seeking owners in dense suburban catchments where fixed salon capacity remains constrained.
DEFRA enforces animal welfare licensing under the Animal Welfare (Licensing of Activities Involving Animals) Regulations, mandating staff qualifications and facility inspections that elevate compliance costs for new entrants. The British Dog Groomers' Association maintains voluntary certification standards that increasingly function as de facto market access requirements for commercial operators. Veterinary clinics expanding into ancillary grooming must navigate dual oversight from the Royal College of Veterinary Surgeons and local authority environmental health departments. Stakeholders should monitor whether DEFRA proposes mandatory qualification tiers that would reshape workforce economics and consolidation incentives across fragmented regional markets.
Market Dynamics
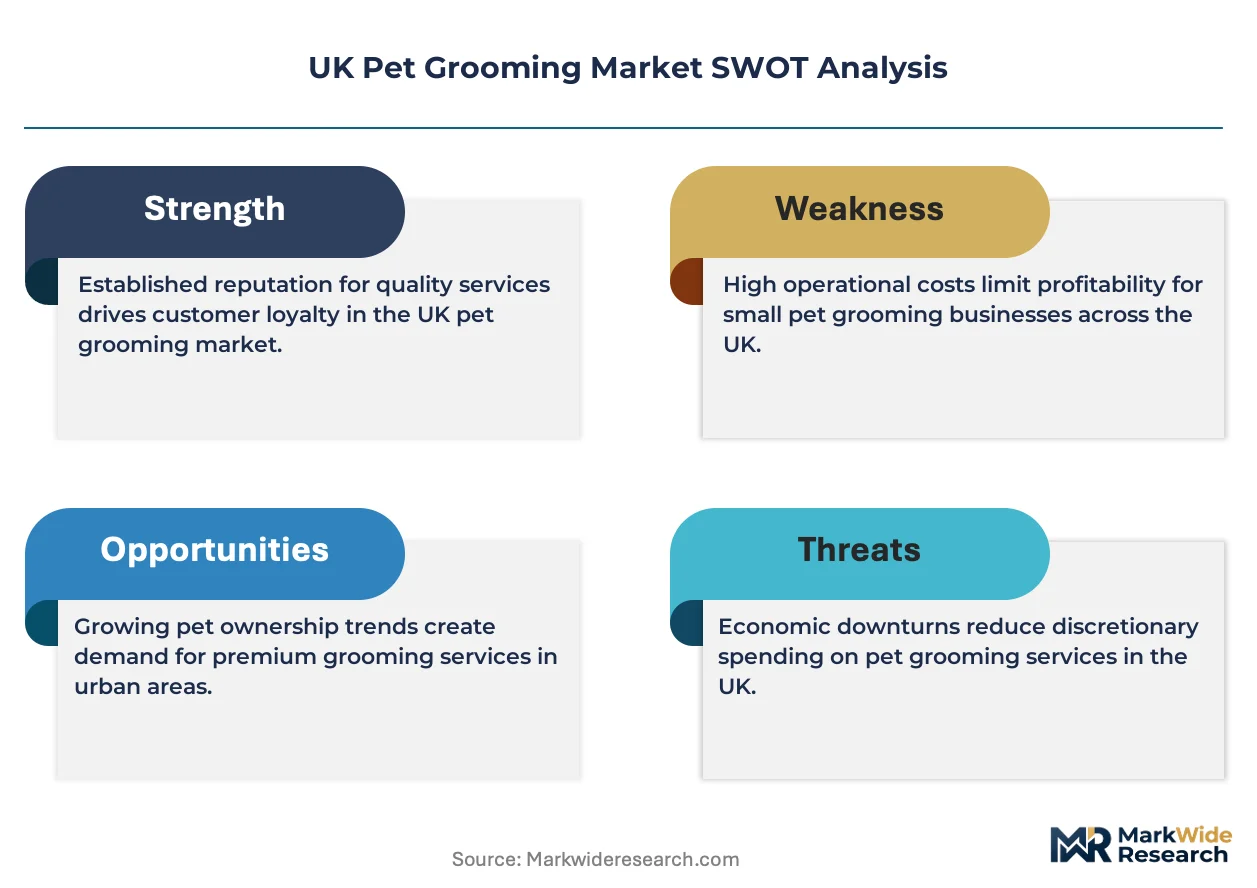
DEFRA animal welfare licensing mandates are compressing market entry timelines while simultaneously elevating operational standards across commercial grooming operations. This regulatory tightening is forcing capital reallocation toward staff qualification and facility compliance.
Growth Catalysts
- Urban millennial pet ownership:Dense metropolitan clusters in Greater London and the South East concentrate disposable income toward recurring small-breed grooming expenditures.
- DEFRA licensing framework:Mandatory facility inspections and staff qualifications create competitive moats for incumbent operators with established compliance infrastructure.
- Mobile service technology:GPS-enabled route optimization and van-mounted hydrobath systems enable scalable doorstep service delivery in capacity-constrained suburban catchments.
Market Restraints
- Veterinary-grade input costs:pH-balanced dermatological formulations and hypoallergenic coat treatments carry premium procurement burdens that compress margin structures for independent salons.
- Greater London capacity saturation:Fixed salon density in affluent postal codes limits new entrant addressable market without mobile or franchise expansion.
- Dual oversight complexity:Veterinary clinics offering ancillary grooming face overlapping inspection regimes from the Royal College of Veterinary Surgeons and local environmental health departments.
Strategic Opportunities
- Scottish and Northern English expansion:Underpenetrated metropolitan zones in Manchester, Leeds, and Glasgow present first-mover advantages for branded mobile networks.
- Behavioral-integrated tool convergence:Anxiety-reduction grooming implements combining pheromone diffusion with mechanical desensitization address the underserved nervous-pet segment.
- British Dog Groomers' Association certification:Voluntary standards increasingly function as de facto market access requirements, creating differentiation leverage for early certifiers.
Industry Challenges
- Qualified groomer pipeline:DEFRA-mandated staff competencies face training bottlenecks at accredited vocational providers, extending recruitment cycles.
- Legacy booking system integration:Independent salons struggle to synchronize appointment platforms with emerging tele-veterinary referral networks and subscription management tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Pet Grooming Market |
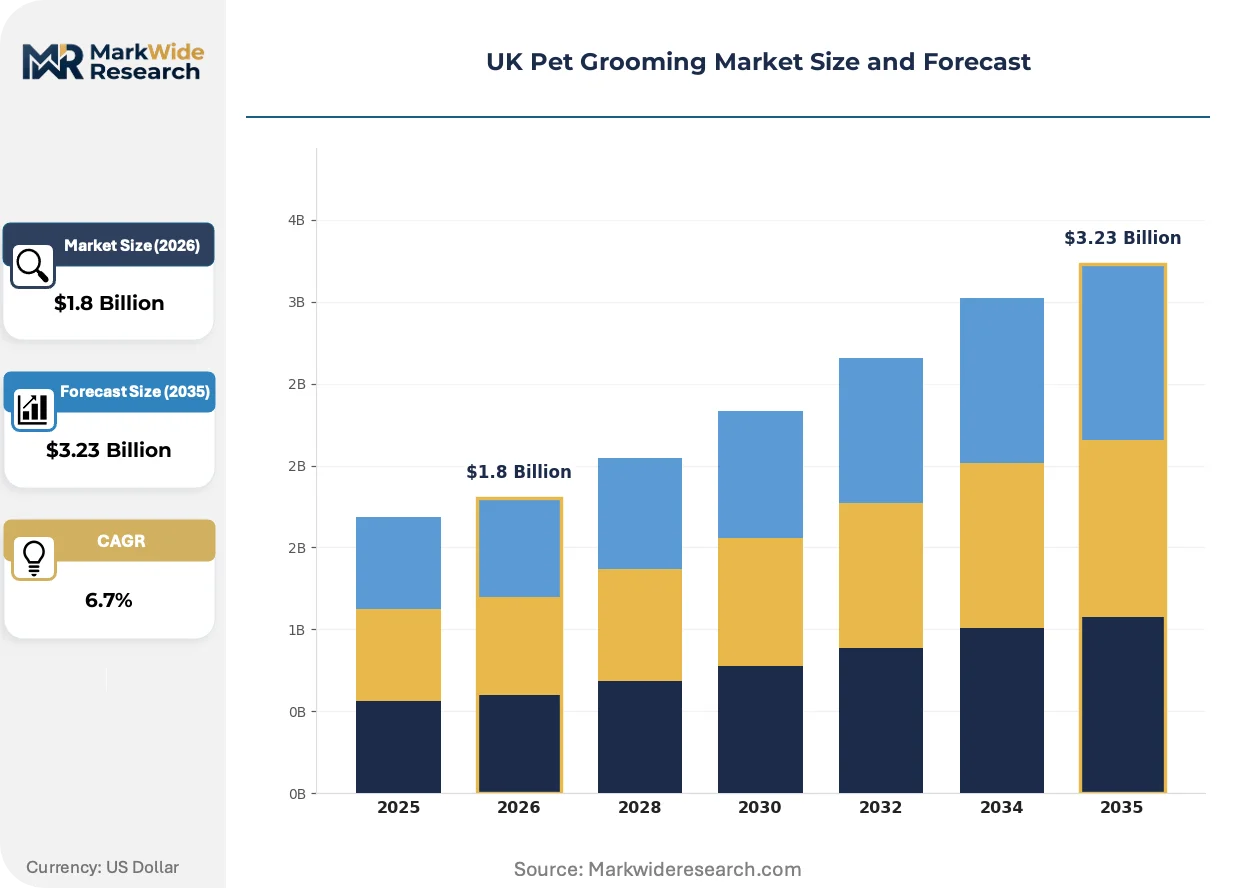
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bathing, Clipping, Nail Trimming, Ear Cleaning Animal Type: Dogs, Cats, Rabbits, Guinea Pigs Grooming Product: Shampoos, Conditioners, Brushes, Clippers Distribution Channel: Online Retail, Pet Stores, Veterinary Clinics, Mobile Services |
| Companies Covered | Petco Animal Supplies, Inc., Spectrum Brands, Beaphar BV, 4-Legger, The Hartz Mountain Corporation, Ferplast S.p.A., Company of Animals Ltd., Groomer's Choice, SynergyLabs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Pet Grooming Market Evolving Landscape
Silent clipper motor technology and IoT-enabled coat monitoring devices are compressing the traditional service-model boundary between professional grooming and at-home maintenance. These innovations are redistributing value capture across the channel stack.
Low-decibel rotary motor clippers with ceramic blade assemblies are supplanting traditional electromagnetic models in anxiety-sensitive grooming protocols. Premium salon operators in Greater London are adopting these units at accelerated replacement cycles. The shift is compressing aftermarket blade revenue while elevating initial equipment price points and service differentiation.
DEFRA's Animal Welfare (Licensing of Activities Involving Animals) Regulations are mandating documented staff qualification tiers and facility audit trails. Commercial operators must now maintain continuous compliance records accessible to local authority inspectors. Mobile service providers face particular adaptation pressure as van-based operations fall under the same facility-inspection regime as fixed salons.
Subscription-based grooming packages with embedded wellness checks are displacing transactional appointment booking in affluent suburban households. Tiered membership structures bundle coat maintenance, dental inspection, and behavioral assessment into recurring revenue relationships. This model concentrates most rapidly in the South East where household pet expenditure budgets support annual commitment frameworks.
UK Pet Grooming Market Segmentation
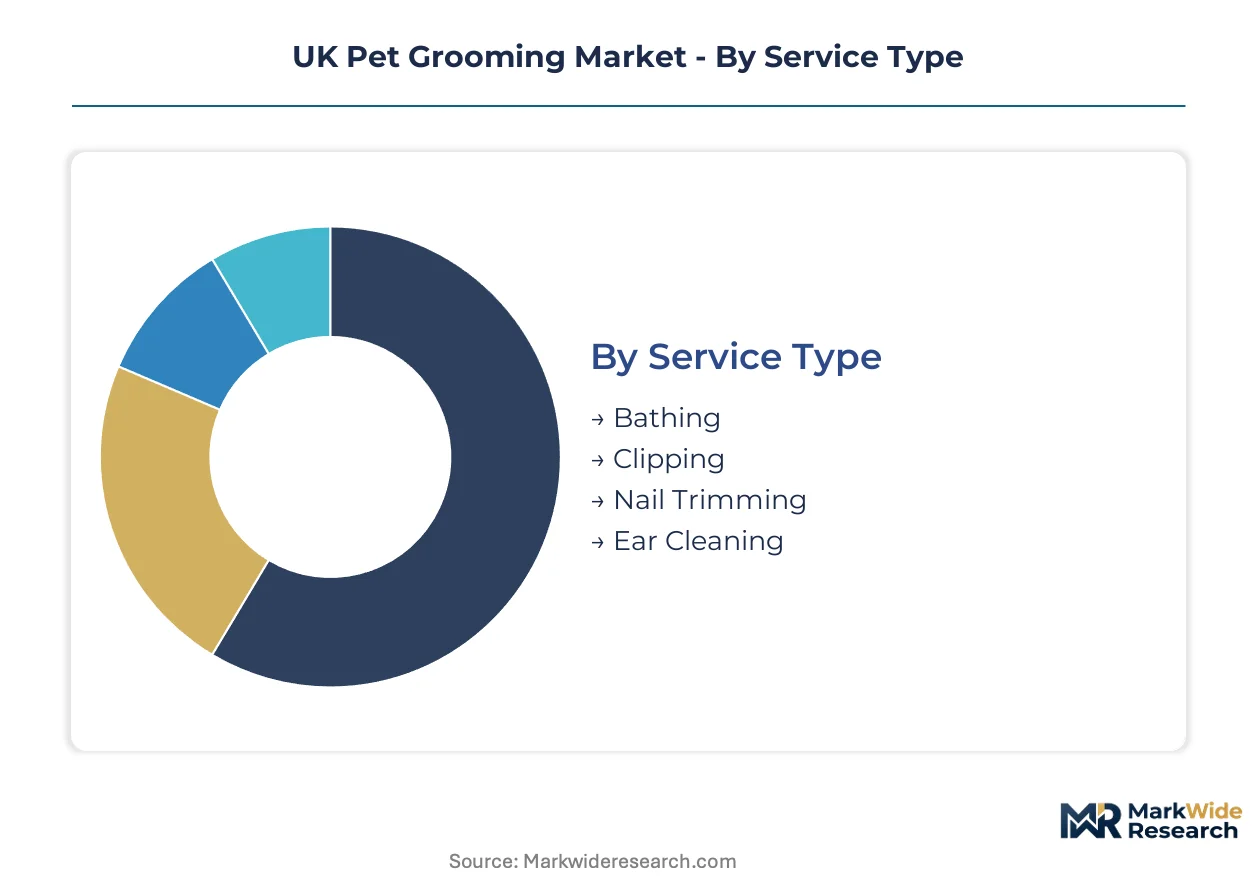
Segmentation in the UK pet grooming market reveals how service delivery, animal physiology, and procurement channels create distinct margin profiles. Understanding these divisions exposes where capital concentrates and where mobile technology is redrawing competitive boundaries.
Service Type:
Mobile service operators route different service intensities through distinct van configurations and appointment clustering algorithms.
- Bathing:Hydrobath systems with temperature-controlled recirculation dominate mobile unit specifications. Demand clusters in Greater London suburban corridors where fixed salon capacity constraints force convenience-seeking owners toward doorstep delivery. DEFRA facility inspection requirements now extend to van-mounted equipment, elevating capital barriers for new mobile entrants.
- Clipping:Precision blade work on small-breed dogs commands premium pricing in urban millennial households. Silent rotary motor technology is displacing electromagnetic models in anxiety-sensitive protocols across South East premium salons. Equipment replacement cycles compress as ceramic blade assemblies become standard.
- Nail Trimming:Quick-service add-on bundled into membership packages. Grinders with variable-speed dremel heads reduce quick-injury liability for independent operators.
- Ear Cleaning:Veterinary-referral dependent service requiring otoscope examination protocols. Revenue concentrates in clinic-integrated grooming operations with dual oversight from the Royal College of Veterinary Surgeons.
By volume, bathing leads. By growth pace, clipping is ahead.
Animal Type:
Cost-to-serve varies dramatically across species due to handling protocols, behavioral pharmacology requirements, and dermatological sensitivity profiles.
- Dogs:Small-breed canines generate disproportionate revenue per groom through styling-intensive coat maintenance. Urban millennial ownership in Greater London and the South East sustains recurring expenditure patterns. DEFRA licensing mandates elevate staff qualification requirements for commercial operators handling high-volume dog traffic.
- Cats:Feline grooming demands specialized restraint techniques and low-stress handling certification. Demand concentrates in veterinary-aligned channels where sedation protocols address aggressive behavioral presentations.
- Rabbits:Fragile dermal structure requires species-specific tool sets with reduced blade contact pressure. Limited groomer competency compresses addressable market to specialist operators.
- Guinea Pigs:Minimal serviceable revenue per animal restricts commercial viability to veterinary clinic add-ons or dedicated exotic pet salons in university towns.
By revenue contribution, dogs dominate. By unmet need, cats show the steepest expansion trajectory.
Grooming Product:
Professional-grade formulations and precision equipment command divergent margin structures across retail and service channels.
- Shampoos:pH-balanced dermatological formulations with colloidal oatmeal and medicated selenium sulfide variants anchor professional product value pools. Veterinary-aligned distribution through practice-exclusive SKUs captures premium pricing unavailable to mass retail.
- Conditioners:Leave-in detangling agents with silicone-free formulations address long-coat small-breed maintenance. South East households with elevated pet expenditure budgets drive subscription replenishment models.
- Brushes:Slicker and pin brush configurations segment by coat type density. Slicker brushes with self-cleaning retraction mechanisms command price premiums in direct-to-consumer channels.
- Clippers:Cordless lithium-ion units with adjustable blade systems displace corded electromagnetic models. Silent motor technology is gaining share fastest in anxiety-sensitive grooming protocols.
By unit volume, brushes lead. By value concentration, clippers are expanding most quickly.
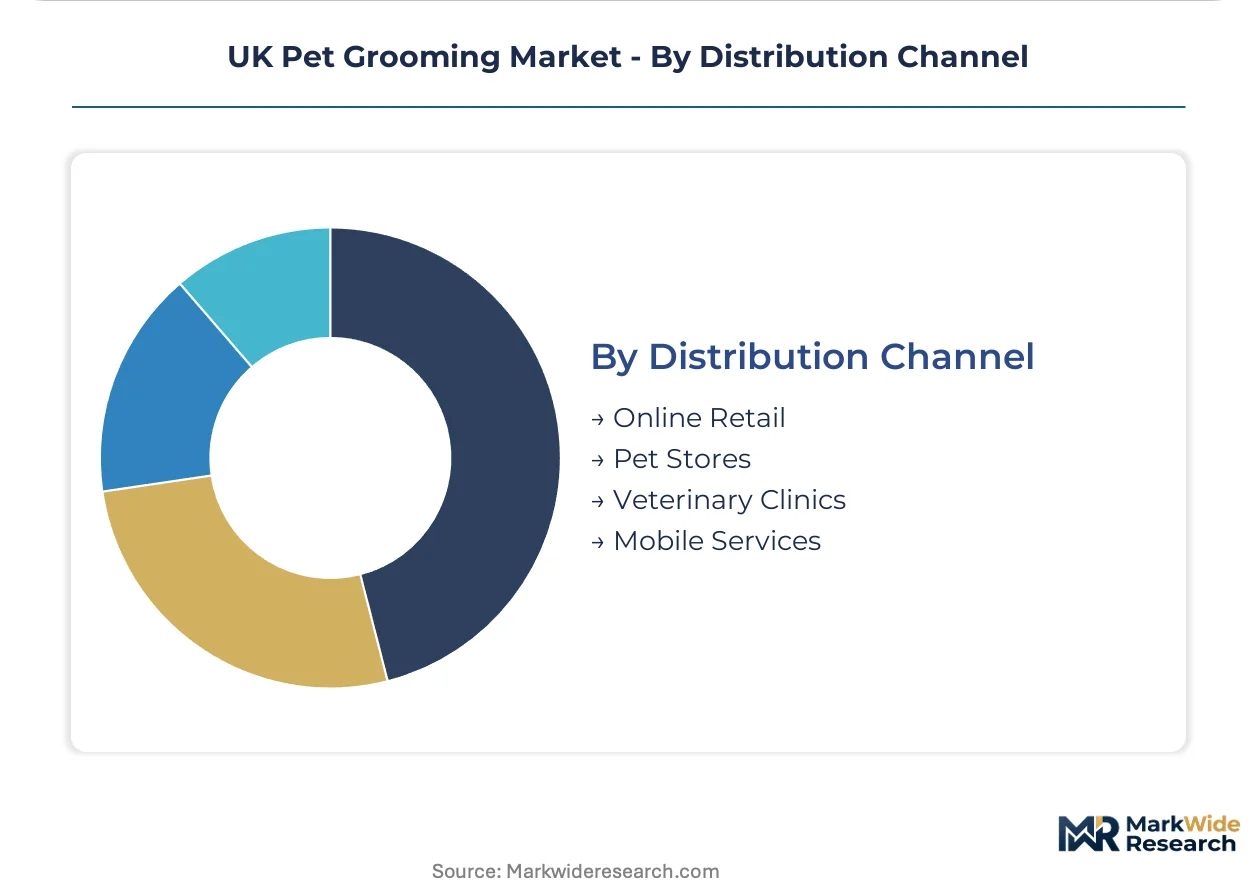
Distribution Channel:
Customer acquisition economics and service fulfillment costs create divergent scaling profiles across physical and digital touchpoints.
- Online Retail:Subscription replenishment models for consumables capture recurring revenue with minimal marginal fulfillment cost. Chewy and Amazon Pet dominate search visibility for shampoo and conditioner replenishment. Direct-to-consumer brush and clipper brands leverage Instagram veterinary influencer endorsement.
- Pet Stores:Grooming salons co-located within Pets at Home superstores benefit from foot traffic conversion. In-store hydrobath stations in Greater London flagships demonstrate equipment efficacy to drive product attachment.
- Veterinary Clinics:Dual oversight from the Royal College of Veterinary Surgeons and local environmental health departments elevates compliance burden. Ancillary grooming services capture margin from captive clinical appointment traffic.
- Mobile Services:GPS-enabled route optimization and van-mounted hydrobath systems enable scalable doorstep delivery. Scottish and Northern English metropolitan zones present first-mover expansion opportunities for branded networks.
By current revenue share, pet stores lead. By expansion velocity, mobile services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M6 motorway corridor and its feeder networks enable mobile grooming van deployment across England's midsection, while Scotland's A9 spine links Highland catchments to Lowland service hubs. These transport arteries determine where subscription-based doorstep delivery achieves viable route density.
Greater London
Urban millennial households with small-breed dogs concentrate disposable income in postal codes W1-KN. DEFRA's Animal Welfare (Licensing of Activities Involving Animals) Regulations mandate documented staff qualifications and facility audit trails accessible to local authority inspectors. Fixed salon capacity saturation in affluent boroughs accelerates mobile service adoption, with GPS-enabled route optimization penetrating suburban corridors beyond the North Circular.
South East England
Household pet expenditure budgets in Surrey, Kent, and Sussex support annual subscription commitment frameworks for bundled grooming and wellness services. The British Dog Groomers' Association voluntary certification standards function as de facto market access requirements for commercial operators. Premium salon clusters in Guildford and Brighton deploy silent rotary motor clippers at accelerated replacement cycles, compressing aftermarket blade revenue.
Scotland
Underpenetrated metropolitan zones in Glasgow and Edinburgh present first-mover advantages for branded mobile networks with van-mounted hydrobath systems. The Scottish Government's animal welfare licensing regime operates under devolved authority, maintaining alignment with DEFRA standards while allowing local authority discretion in inspection scheduling. Edinburgh's New Town and Glasgow's West End concentrate small-breed ownership among young professional households.
North West England
Manchester and Leeds metropolitan areas exhibit growing demand for professional-grade grooming as veterinary clinic expansion into ancillary services intensifies. Dual oversight from the Royal College of Veterinary Surgeons and local environmental health departments elevates compliance burden for clinic-integrated operators. The M62 corridor enables mobile service radius extension across the Pennine catchment.
Midlands
Birmingham and Nottingham urban clusters demonstrate emerging subscription model viability as household pet expenditure patterns migrate northward from the South East. DEFRA-mandated staff competencies face training bottlenecks at accredited vocational providers across the East and West Midlands, extending recruitment cycles for independent salons. The M1 corridor supports mobile van logistics between metropolitan nodes.
UK Pet Grooming Market Competitive Landscape
Concentration sits with multi-channel consumer goods conglomerates and veterinary-aligned specialists. The UK pet grooming sector exhibits tiered structure with distinct scaling profiles across mass retail, professional-grade distribution, and mobile service networks. Three strategic archetypes dominate: diversified consumer products groups leveraging shelf presence in major retail chains; veterinary-formulation specialists capturing premium pricing through practice-exclusive distribution; and behavioral-integrated tool developers addressing anxiety-prone pet segments. Competitive moves center on certification leverage and mobile infrastructure deployment rather than horizontal consolidation.
Among diversified consumer products groups, Spectrum Brands anchors mass-market penetration through multi-channel distribution sustaining shelf presence in major retail chains. Beaphar BV occupies a position within the veterinary-aligned tier, representing professional-grade formulation specialists that capture premium pricing through practice-exclusive SKUs. Company of Animals Ltd. exemplifies the behavioral-integrated archetype, differentiating through grooming tools that address anxiety-prone pets. These three entities collectively illustrate how competitive positioning fragments across distinct value capture mechanisms rather than converging on scale-driven consolidation.
| Leading Market Players |
|---|
| Petco Animal Supplies, Inc. |
| Spectrum Brands |
| Beaphar BV |
| 4-Legger |
| The Hartz Mountain Corporation |
| Ferplast S.p.A. |
| Company of Animals Ltd. |
| Groomer's Choice |
| SynergyLabs |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts between mobile grooming fleet operators and hydrobath equipment manufacturers lock in supply access while anchoring price visibility across the analysis window. These arrangements insulate branded networks from spot-market volatility in van-mounted grooming systems while compressing margin flexibility for independent salon operators lacking procurement scale.
Pricing Analysis
Volume-discount tiering structures separate enterprise mobile fleets from independent salon operators and at-home groomers across equipment procurement. Three-tier pricing stratifies by certification grade, with British Dog Groomers' Association-accredited operators commanding preferential terms on silent rotary motor clippers. Pricing pressure stems from veterinary-grade pH-balanced formulation costs that compress margin structures for non-aligned independents. At-home groomers exhibit highest price sensitivity, while South East subscription-model households demonstrate lowest elasticity.
Supply Chain Analysis
Inventory lead times for lithium-ion clipper batteries and ceramic blade assemblies extend procurement cycles for UK-based grooming equipment distributors. Manufacturing concentrates in China, Germany, and Japan, with precision motor components drawing from Taiwanese electronics suppliers. Single-source vulnerability sits with specialized hydrobath pump systems where German engineering dominates. Distribution runs through veterinary-aligned wholesale channels for professional-grade formulations, while mass retail captures consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward subscription-model households as Greater London and South East consolidation concentrates recurring revenue relationships with fewer, larger grooming networks. This fragmentation among independent salons weakens collective bargaining position against product suppliers and equipment vendors.
For Market Incumbents: Fortify compliance infrastructure as DEFRA licensing mandates deepen competitive moats. Invest in British Dog Groomers' Association certification pipelines to anchor workforce quality against mobile service entrants. Capture backward integration into silent clipper motor technology to defend equipment margin erosion from ceramic blade commoditization. For New Entrants and Emerging Players: Lead with GPS-enabled mobile deployment in Scottish metropolitan zones where route density remains underdeveloped. Target Manchester and Leeds veterinary clinic partnerships as the most penetrable channel for ancillary grooming integration. Deploy behavioral-integrated tool differentiation addressing anxiety-prone pet segments underserved by legacy electromagnetic clipper protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mobile grooming networks with embedded subscription wellness packages. Long-term viability over the projection horizon favors operators with van-mounted infrastructure scalable across Northern English expansion corridors. Acquisition focus should center on branded mobile networks with established DEFRA compliance records. Watch for DEFRA mandatory qualification tier proposals as the inflection signal reshaping workforce economics.| Strategic Initiative | Industry Significance |
|---|---|
| Silent Motor Technology Adoption | Ceramic blade assemblies in low-decibel clippers capture anxiety-sensitive grooming protocols across Greater London premium salons. |
| Mobile Fleet Expansion | GPS-optimized van networks penetrate Scottish and Northern English metropolitan zones with constrained fixed salon capacity. |
| Certification Infrastructure Investment | British Dog Groomers' Association qualification pipelines address DEFRA-mandated staff competency bottlenecks at vocational providers. |
| Subscription Model Conversion | Tiered membership structures bundle coat maintenance with dental inspection to lock in South East household recurring expenditure. |
| Veterinary Channel Partnership | Dual oversight navigation with Royal College of Veterinary Surgeons captures captive clinical appointment traffic for ancillary grooming. |
Research Methodology
Cross-validation between primary interviews with commercial grooming operators and secondary validation through DEFRA licensing registers anchors the qualitative findings. Conversations with mobile fleet managers, independent salon proprietors, veterinary clinic service directors, and British Dog Groomers' Association certification officers combined with trade customs data, Pets at Home annual filings, and Royal College of Veterinary Surgeons oversight documentation. Bottom-up service volume estimates triangulate against top-down household pet expenditure surveys.
Sensitivity analysis across the modeling period tests demand elasticity for subscription versus transactional booking models. Segmentation dimensions include service delivery mode, animal physiology category, product formulation grade, and distribution channel type. CAGRs derive from trend extrapolation of mobile service penetration rates and silent motor equipment replacement cycles calibrated against Greater London and South East household disposable income trajectories.
Forecasts assume regulatory continuity in DEFRA animal welfare licensing and Scottish Government devolved welfare regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Pet Stairs Market
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
Japan Pet Food Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Mink Oil Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Pet Toys Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Cat Litter Market