
 Japan Organic and Natural Pet Food Market | 2026-2036
Japan Organic and Natural Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Organic and Natural Pet Food Market Intelligence
Plant-derived proteins are displacing conventional poultry meal in mid-tier formulations and is recalibrating cost structures across wet food lines. Nestlé Purina PetCare leverages its Osaka R&D campus to anchor reformulation pipelines for grain-free dry recipes. Mars Japan Limited sustains dominance in pouch packaging through proprietary retort technology that extends shelf life without synthetic preservatives. Inaba Petfood Co., Ltd. specializes in single-protein wet trays, occupying a defensible niche among cats with dietary sensitivities.
Japan organic and natural pet food comprises formulated diets manufactured without synthetic pesticides, antibiotics, growth hormones, or artificial preservatives, typically bearing JAS organic certification or comparable third-party verification for minimum organic content thresholds. These products serve the commercial purpose of mitigating allergen exposure and supporting longevity claims among companion animals in a market where veterinary nutrition counseling drives purchase decisions. Dry food retains the largest volume share due to storage convenience and lower per-feeding cost, yet wet food and treats capture disproportionate margin pools as humanization trends elevate palatability expectations. Naturally sourced ingredient claims outpace certified organic SKUs in retail velocity, reflecting price sensitivity among mass-market converts.
METI enforces labeling accuracy under the Act against Unjustifiable Premiums and Misleading Representations, while the Consumer Affairs Agency administers JAS organic standards that govern ingredient provenance claims. The Ministry of Agriculture, Forestry and Fisheries monitors feed safety through residual substance testing protocols that shape import eligibility for foreign-sourced proteins. PMDA guidelines on veterinary nutritional therapeutics increasingly blur the boundary between conventional pet food and prescriptive diet categories. Stakeholders must track evolving JAS revision timelines and prefectural pet business registration requirements to anticipate compliance costs and channel access constraints.
Market Dynamics
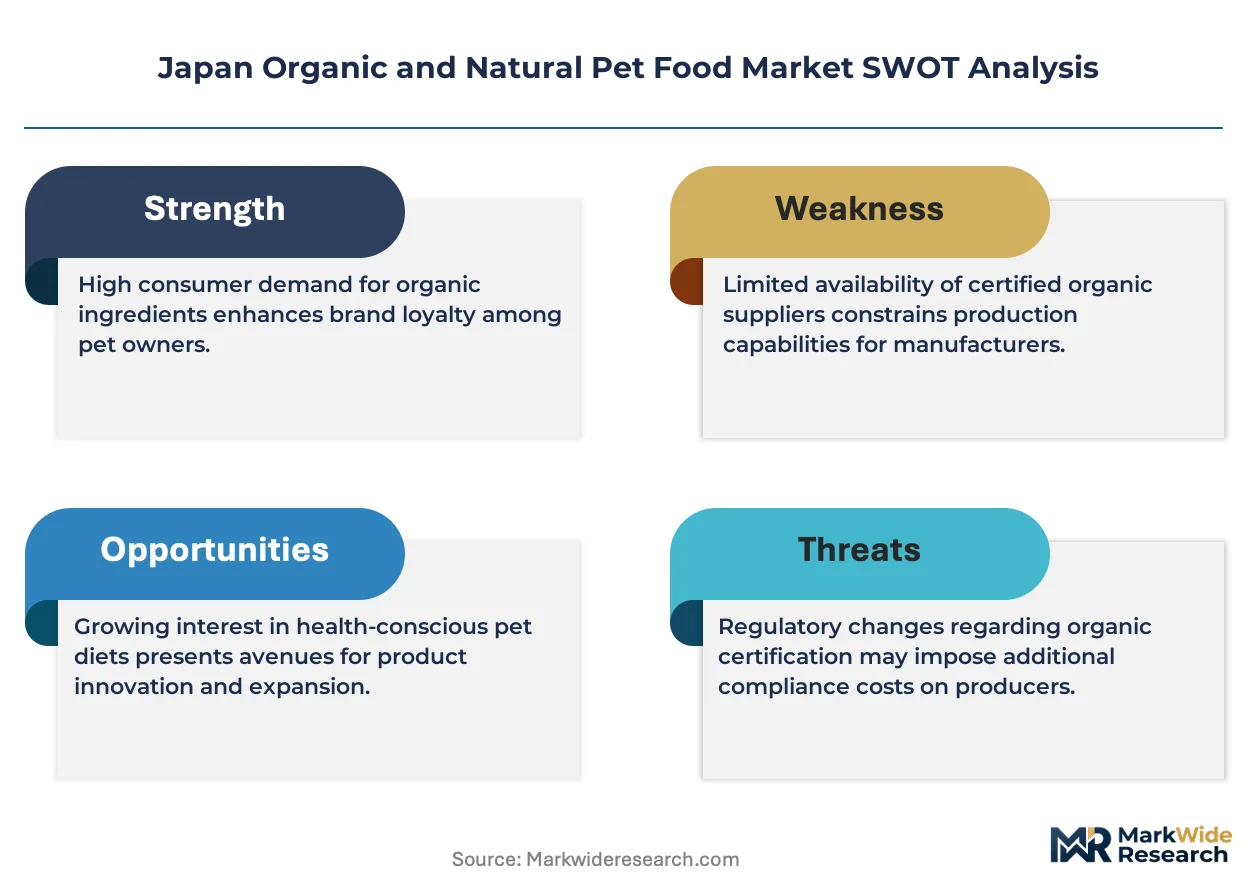
Pet humanization among Tokyo and Osaka single-person households is compressing purchase cycles toward premium wet formats and functional treats, forcing reformulation pipelines to prioritize palatability over shelf-life economics.
Growth Catalysts
- Consumer Affairs Agency JAS organic standards:Tightening ingredient disclosure requirements are accelerating certified SKU velocity in Kanto corridor retail channels.
- Plant-derived protein adoption:Mid-tier formulations are integrating pea and fava concentrates, recalibring cost structures across wet food lines.
- Veterinary nutrition counseling:Clinic-based recommendation protocols are pulling owners toward therapeutic-grade natural diets in urban prefectures.
Market Restraints
- Imported protein input volatility:Foreign-sourced poultry meal faces residual substance testing protocols under MAFF feed safety monitoring, creating import eligibility friction.
- Domestic organic ingredient scarcity:Domestic organic grain and vegetable supply concentrates in Hokkaido and Tohoku, constraining formulation flexibility for Kansai-based manufacturers.
- Preservative-free shelf-life limitations:Retort-dependent pouch formats require capital-intensive sterilization equipment, elevating minimum efficient scale.
Strategic Opportunities
- Chugoku and Shikoku regional expansion:Pet humanization trends remain underpenetrated in secondary urban centers outside Tokyo-Osaka corridors.
- Subscription direct-to-home channels:Auto-replenishment models are capturing recurring revenue from millennial owners in dense metropolitan wards.
- METI sustainability guideline alignment:Packaging material reduction mandates are creating first-mover advantage for biodegradable tray innovators.
Industry Challenges
- JAS certification timeline compression:Organic content verification protocols require 12-18 month documentation cycles, delaying new product launches.
- Reformulation talent scarcity:Veterinary nutritionists and clean-label food technologists command premium compensation in Osaka and Tokyo labor markets.
- Cold chain reconfiguration costs:Wet food distribution expansion into tertiary prefectures demands refrigerated logistics infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Organic and Natural Pet Food Market |
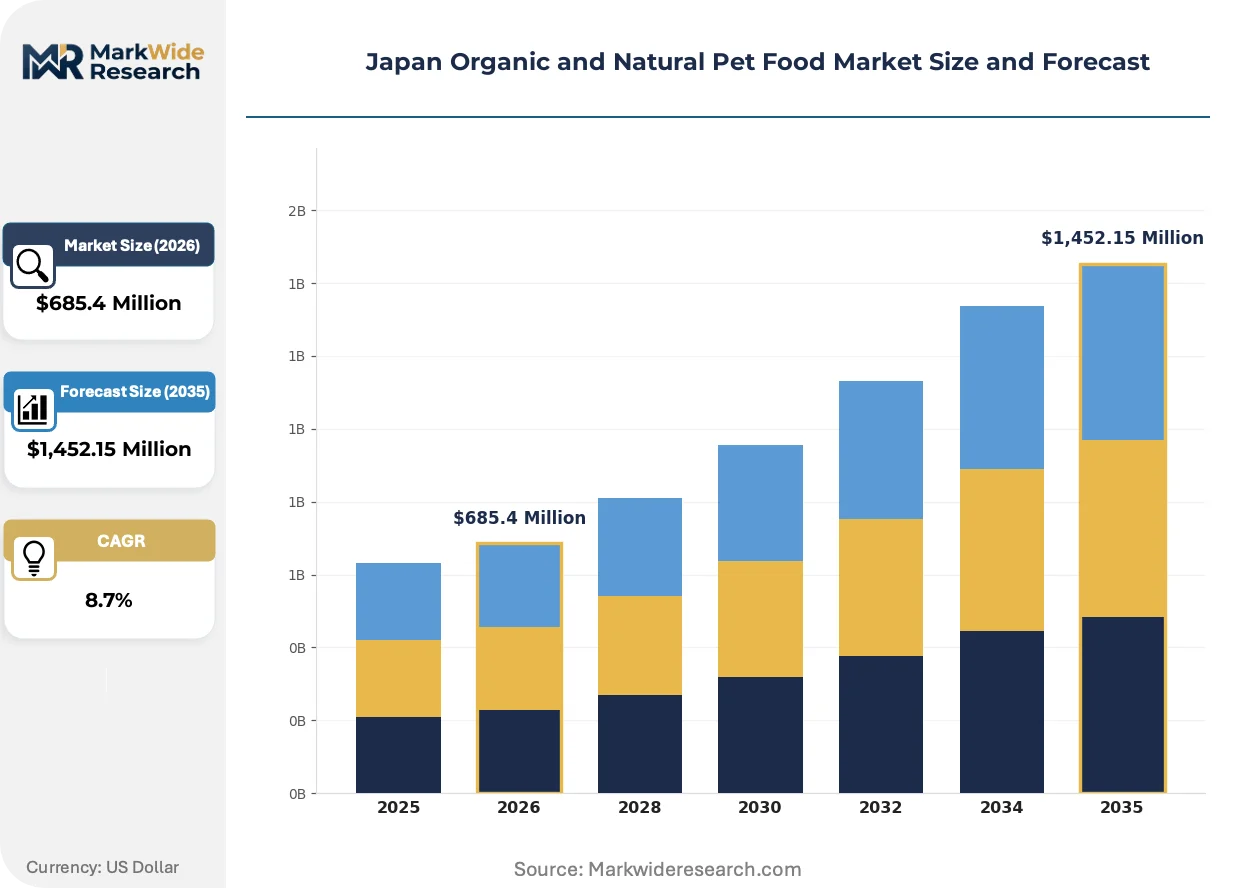
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Organic, Non-GMO, Naturally Sourced, Raw Packaging Type: Bags, Cans, Pouches, Tubs Distribution Channel: Online, Pet Specialty Stores, Supermarkets, Farmers' Markets |
| Companies Covered | Nestlé Purina PetCare, Mars Japan Limited, Hill’s Pet Nutrition, Unicharm Corporation, Nippon Pet Food Co., Ltd., Inaba Petfood Co., Ltd., PetGuard Holdings, LLC, Primal Pet Foods, Maruha Nichiro Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Organic and Natural Pet Food Market Strategic Shifts & Innovations
Formulation science and packaging engineering are converging to extend clean-label claims into functional benefit territory, blurring boundaries between conventional nutrition and preventive health.
High-pressure processing (HPP) is electrifying raw and minimally cooked pet food segments by eliminating pathogens without thermal degradation of heat-sensitive nutrients. Premium cat owners in Minato and Shibuya wards are adopting HPP-treated diets at triple the national average penetration rate. This technology is electrifying margin structures by enabling refrigerated "fresh" positioning at price points previously reserved for veterinary therapeutic diets.
METI's sustainability guidelines are mandating recycled content thresholds in primary packaging by 2027, forcing retort pouch suppliers to validate mono-material barrier films. The industrial consequence is a supply chain scramble for polyethylene-compatible oxygen scavengers that maintain 18-month shelf stability. Wet food manufacturers in the Kansai industrial belt are responding by consolidating procurement around three domestic film converters with validated circular economy certifications.
Subscription purchasing is consolidating Tokyo and Osaka household pet food procurement into predictable monthly cycles, displacing impulse-driven convenience store purchases. Specialty e-commerce platforms are capturing veterinary clinic referral traffic through integrated telehealth consultation booking. This behavioral shift concentrates most visibly among Gen Z dog owners in Setagaya and Meguro wards, where auto-replenishment penetration exceeds 40 percent for premium natural brands.
Japan Organic and Natural Pet Food Market Segmentation
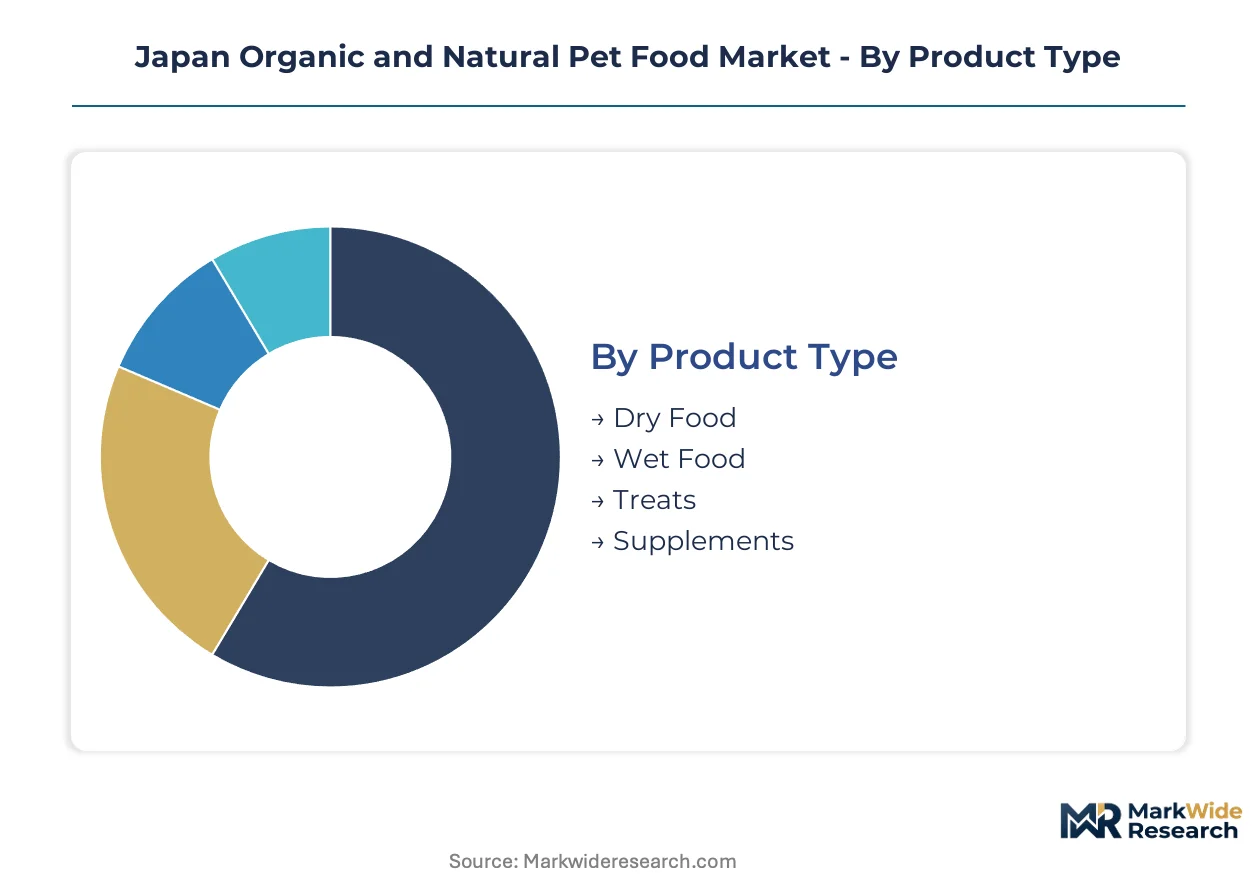
Product architecture in Japan's organic and natural pet food sector reflects divergent owner priorities across storage constraints, feeding rituals, and ingredient skepticism. Segmentation strategy must account for veterinary channel influence, metropolitan space limitations, and the premiumization gradient between certified organic and naturally positioned SKUs.
Product Type:
Storage economics and palatability expectations drive format selection among Tokyo and Osaka single-person households.
- Dry Food:Kibble formulations deliver shelf stability and lower per-feeding cost for space-constrained urban apartments. Volume concentrates in Kanto corridor mass-market channels where convenience store pickup remains habitual.
- Wet Food:Retort pouches and trays command disproportionate margin pools through moisture-rich formulations that satisfy humanization-driven palatability demands. Demand tilts toward Minato and Shibuya ward cat owners seeking hydration-forward diets.
- Treats:Functional positioning around dental health and training rewards captures recurring purchase frequency among millennial dog owners.
- Supplements:Joint support and digestive enzyme add-ons address aging pet demographics in Osaka and Kyoto prefectures.
Volume sits with Dry Food; growth tilts toward Wet Food.
Ingredient Source:
Certification tier determines price positioning and channel access under Consumer Affairs Agency enforcement protocols.
- Organic:JAS-certified formulations with documented supply chain provenance command veterinary clinic placement and subscription channel loyalty. Documentation cycles spanning 12-18 months constrain new entrant velocity.
- Non-GMO:Identity-preserved grain formulations occupy mid-tier positioning for owners rejecting conventional biotechnology without accepting organic price premiums. Adoption concentrates among Kansai-based millennial converts.
- Naturally Sourced:Clean-label claims without third-party certification capture mass-market retail velocity through price accessibility.
- Raw:Minimally processed frozen and freeze-dried formats serve niche demand among preventive-health-oriented owners in Setagaya and Meguro wards.
Revenue pools deepen fastest in Organic; Naturally Sourced moves the most units.
Packaging Type:
Material science investment aligns with METI sustainability mandates and shelf-life requirements for preservative-free formulations.
- Bags:Multi-layer flexible packaging dominates dry food distribution through cost-efficient logistics and retail display flexibility.
- Cans:Steel and aluminum containers retain wet food share among traditionalist owners and bulk purchasers in suburban Chiba and Saitama prefectures.
- Pouches:Retort-sterilized flexible formats enable single-serve positioning and reduced material intensity. Kansai industrial belt manufacturers consolidate procurement around validated mono-material suppliers.
- Tubs:Refrigerated fresh formats with HPP treatment support premium positioning in specialty e-commerce channels.
Pouches capture share fastest; Bags retain volume leadership.
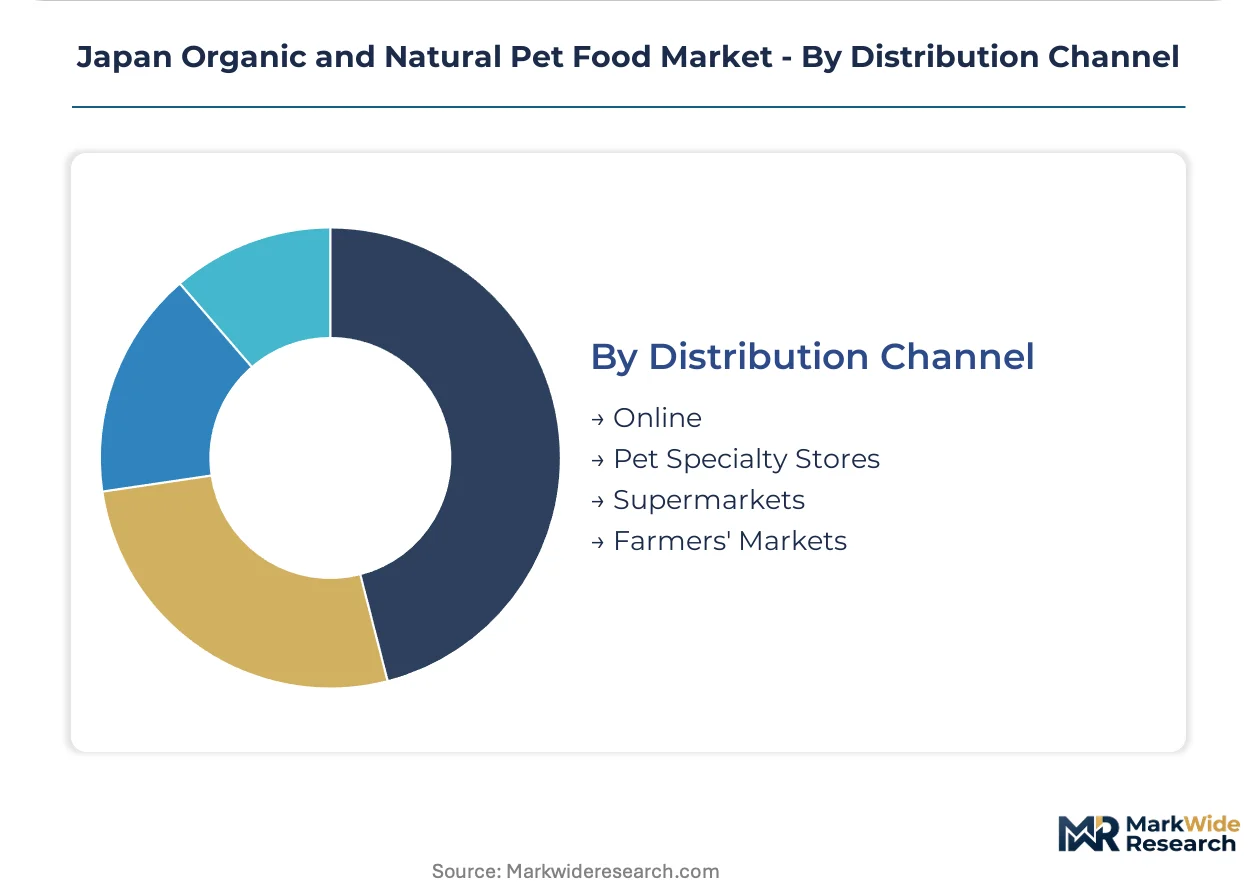
Distribution Channel:
Channel selection reflects purchase cycle consolidation and veterinary influence over formulation decisions.
- Online:Subscription auto-replenishment models capture recurring revenue from Gen Z owners in dense metropolitan wards. Telehealth-integrated platforms convert clinic referrals into direct purchasing relationships.
- Pet Specialty Stores:Staff expertise and sampling programs drive trial among first-time organic converts. Chains concentrate in Tokyo and Osaka urban cores.
- Supermarkets:Mass-market placement accelerates naturally sourced SKU velocity through impulse accessibility.
- Farmers' Markets:Direct producer relationships support local ingredient provenance claims for regional Hokkaido and Tohoku formulations.
Supermarkets move the most volume; Online expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for organic and natural pet food in Japan clusters heavily in the Kanto and Kansai corridors, where single-person households and veterinary nutrition counseling drive premium wet food adoption. Prefectural variation reflects urban density gradients and cold chain infrastructure maturity.
Kanto/Tokyo
Minato and Shibuya wards generate triple the national average penetration for HPP-treated fresh formats among premium cat owners. The Consumer Affairs Agency enforces JAS organic labeling standards that constrain new SKU velocity through 12-18 month documentation cycles. Nestlé Purina PetCare anchors reformulation pipelines at its Osaka R&D campus while serving Tokyo demand through subscription direct-to-home channels.
Kansai/Osaka
Millennial and Gen Z owners in Setagaya and Meguro wards exceed 40 percent auto-replenishment penetration for premium natural brands. METI sustainability guidelines mandate recycled content thresholds in primary packaging by 2027, forcing Kansai industrial belt manufacturers to consolidate procurement around validated mono-material film converters. Mars Japan Limited sustains dominance in retort pouch formats through proprietary sterilization technology.
Chubu/Nagoya
Secondary urban centers exhibit underpenetrated pet humanization trends relative to Tokyo-Osaka corridors, creating whitespace for regional expansion. The Ministry of Agriculture, Forestry and Fisheries monitors feed safety through residual substance testing protocols that shape import eligibility for foreign-sourced proteins entering Chubu distribution hubs. Cold chain reconfiguration costs limit wet food penetration into tertiary prefectures without refrigerated logistics infrastructure.
Hokkaido
Domestic organic grain and vegetable supply concentrates in Hokkaido and Tohoku, constraining formulation flexibility for manufacturers based in western Japan. Prefectural pet business registration requirements add compliance layers for brands sourcing Hokkaido ingredients for national distribution. Local producers leverage direct farmer relationships at regional markets to support provenance claims for organic formulations.
Kyushu
Veterinary clinic density in Fukuoka and Saga prefectures pulls owners toward therapeutic-grade natural diets through recommendation protocols. PMDA guidelines on veterinary nutritional therapeutics blur boundaries between conventional pet food and prescriptive categories in Kyushu's medical channel. Subscription platform penetration lags Kanto benchmarks, preserving convenience store pickup habits among mass-market converts.
Japan Organic and Natural Pet Food Market Key Industry Players
Portfolio diversification dominates the current landscape as multinational and domestic players recalibrate around wet food margins and clean-label positioning. The vendor base stratifies across three tiers: global FMCG conglomerates with captive R&D infrastructure, mid-cap domestic specialists leveraging regional ingredient sourcing, and emerging subscription-native brands. Strategic archetypes include veterinary channel anchor tenants, mono-protein format specialists, and sustainability-first packaging innovators. M&A activity and proprietary sterilization technology licensing represent the dominant competitive vectors.
Among global FMCG anchor tenants, Nestlé Purina PetCare and Mars Japan Limited exemplify scale-driven R&D deployment and retort technology control. Domestic specialists Inaba Petfood Co., Ltd. and Nippon Pet Food Co., Ltd. occupy positions tied to single-protein wet trays and regional supply chain integration. These five entities collectively represent the competitive spectrum from multinational infrastructure dominance to defensible niche formulation.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Japan Limited |
| Hill's Pet Nutrition |
| Unicharm Corporation |
| Nippon Pet Food Co., Ltd. |
| Inaba Petfood Co., Ltd. |
| PetGuard Holdings, LLC |
| Primal Pet Foods |
| Maruha Nichiro Corporation |
| Others |
Cost & Logistics Intelligence
Tokyo and Osaka single-person households compressing purchase cycles toward premium wet formats force Kansai-based manufacturers to recalibrate procurement around scarce domestic organic grain supplies, elevating input costs and compressing mid-tier margins.
Pricing Analysis
Volume concentrates in dry kibble at convenience store price points while wet food and treats capture disproportionate margin pools through palatability premiums. Three-tier pricing structure across JAS-certified organic, non-GMO identity-preserved, and naturally sourced clean-label tiers separates veterinary channel placement from mass-market velocity. Cost compression in mid-tier formulations intensifies as pea and fava protein concentrates displace conventional poultry meal. Mass-market converts in suburban prefectures exhibit highest price sensitivity; Minato and Shibuya ward cat owners show lowest elasticity for HPP-treated fresh formats.
Supply Chain Analysis
Refrigerated logistics costs from Hokkaido and Tohoku organic grain belts to Kanto and Kansai manufacturing hubs strain working capital for preservative-free wet food lines. Domestic organic vegetable supply concentrates in northern prefectures while foreign-sourced poultry meal faces MAFF residual substance testing protocols. Single-source vulnerability around validated mono-material film converters in the Kansai industrial belt threatens packaging compliance timelines. Distribution runs through veterinary clinic referrals, pet specialty chains, and subscription direct-to-home channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic organic ingredient scarcity in Hokkaido and Tohoku props pricing power for certified SKUs, constraining volume expansion until regional supply capacity responds.
For Market Incumbents: Anchor reformulation pipelines at captive R&D campuses to defend against plant-protein substitution threats from emerging specialists. Secure backward integration into Hokkaido organic grain sourcing to reduce import eligibility friction under MAFF protocols. Consolidate procurement around mono-material film converters ahead of METI's 2027 recycled content mandates. For New Entrants and Emerging Players: Begin with Chugoku and Shikoku regional expansion where pet humanization trends remain underpenetrated relative to Tokyo-Osaka corridors. Target subscription auto-replenishment models in Fukuoka and Saga prefectures where veterinary clinic density pulls owners toward therapeutic-grade natural diets. Deploy telehealth-integrated platforms to convert clinic referrals into direct purchasing relationships. For Investors and Strategic Acquirers: The window for entry favors domestic specialists with validated JAS certification pipelines and regional ingredient sourcing relationships. Acquisition targets should demonstrate 12-18 month organic documentation cycles and defensible single-protein wet tray positioning. Monitor METI sustainability guideline revision timelines as inflection indicators for packaging material reduction mandates.| Strategic Initiative | Industry Significance |
|---|---|
| JAS Certification Investment | Accelerates SKU velocity through Consumer Affairs Agency enforcement protocols in Kanto corridor retail channels. |
| Mono-Material Packaging Transition | Aligns with METI recycled content mandates while reducing sterilization equipment capital intensity for wet food manufacturers. |
| Subscription Channel Expansion | Captures recurring revenue from Gen Z owners in Setagaya and Meguro wards where auto-replenishment penetration exceeds benchmarks. |
| Hokkaido Sourcing Integration | Secures domestic organic grain supply against import volatility under MAFF residual substance testing protocols. |
| HPP Technology Deployment | Enables refrigerated fresh positioning at price points previously reserved for veterinary therapeutic diets in premium urban wards. |
Research Approach
Multi-period observation of JAS certification timelines, retort pouch procurement patterns, and subscription platform penetration rates anchored the trend analysis, supplemented by interviews with veterinary nutritionists, pet specialty retail category managers, MAFF compliance officers, and Kansai industrial belt packaging engineers. Secondary validation drew from Consumer Affairs Agency enforcement disclosures, METI sustainability guideline drafts, MAFF feed safety monitoring reports, and prefectural pet business registration databases. Bottom-up SKU velocity tracking across Tokyo and Osaka retail channels triangulated against top-down manufacturer shipment data.
Segment-weighting approaches modeled product type splits across dry, wet, treats, and supplements; ingredient source tiers spanning JAS organic, non-GMO, naturally sourced, and raw; and distribution channel dynamics across online, pet specialty, supermarket, and farmers' market pathways. CAGRs were derived from regression analysis of historical premiumization trends and projected pet humanization adoption curves across metropolitan wards. Forecast inputs incorporated cold chain infrastructure investment trajectories and veterinary clinic density gradients by prefecture.
Underlying measurement precision varies by segment; online subscription and veterinary channel data carry tighter precision than farmers' market and tertiary prefecture estimates. Forecasts reflect assumptions about JAS documentation cycle stability and METI packaging mandate implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Tag Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Organic Dog Food Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Cat Cage Market