
 United States Pet Care and Services Market | 2026-2036
United States Pet Care and Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pet Care and Services Market Analytics
The Pet Sustainability Coalition's packaging accountability framework is expanding pressure on manufacturers to reduce plastic waste across treat and food packaging. Mars, Incorporated leverages its diversified nutrition science portfolio to sustain premium positioning across therapeutic and wellness formulations. PetSmart LLC anchors its competitive stance through geographic dominance in big-box retail combined with in-store veterinary clinic partnerships.
Pet care and services encompass the commercial ecosystem of nutrition, health management, grooming, training, boarding, and ancillary products formulated for companion animal maintenance and wellbeing. Pet food manufacturing employs extrusion processing with precise protein-fat-carbohydrate ratios calibrated to species-specific metabolic requirements, while veterinary diagnostics integrate immunoassay and molecular testing platforms for disease surveillance. The product category dimension shows food commanding the largest revenue pool due to repeat purchase frequency, though health products generate superior per-unit margins driven by prescription and preventive care trends. Service type segmentation reveals grooming and boarding as mature revenue bases, while training services capture outsized growth from behavioral health awareness among first-time dog owners.
The FDA Center for Veterinary Medicine enforces feed safety standards under the Federal Food, Drug, and Cosmetic Act, while state veterinary medical boards regulate the scope of telehealth and paraprofessional services permitted within clinic settings. The USDA Animal and Plant Health Inspection Service oversees interstate health certificate requirements that shape pet transport and boarding operational compliance. Stakeholders must monitor evolving state legislation on veterinary technician scope of practice and telemedicine reimbursement parity as these frameworks will determine competitive access across service delivery models.
Market Dynamics
Telemedicine reimbursement parity debates across state veterinary medical boards are fragmenting service delivery models, forcing operators to navigate patchwork compliance while scaling digital health platforms.
Growth Catalysts
- Humanization of pet nutrition:Owners now apply human-grade dietary standards to companion animals, expanding demand for fresh-cooked and raw formulations that command premium shelf positioning.
- FDA Center for Veterinary Medicine feed safety modernization:Enhanced hazard analysis requirements are professionalizing manufacturing practices and elevating barriers for subscale producers.
- Urban pet density in California, Texas, and Florida:Metropolitan concentration supports specialized service economics, enabling boarding facilities to offer enrichment programming and behavioral consulting.
Market Restraints
- Veterinary labor supply constraints:Accredited DVM program output limits create persistent staffing bottlenecks for clinic expansion, particularly in rural and exurban markets.
- Protein input cost volatility:Beef, poultry, and fish meal prices fluctuate with commodity cycles, compressing margins for mid-tier pet food manufacturers lacking forward contracting capabilities.
- State-level telehealth scope restrictions:Veterinary practice acts in jurisdictions like Texas and Tennessee impose VCPR requirements that block asynchronous consultation models.
Strategic Opportunities
- Behavioral health service gaps:Separation anxiety and reactivity training command out-of-pocket spend from Millennial first-time owners, creating white space beyond traditional obedience instruction.
- Senior pet therapeutic nutrition:Kidney, joint, and cognitive support formulations for aging companion animals represent underdeveloped SKU depth relative to human senior nutrition analogues.
- USDA APHIS health certificate digitization:Streamlined interstate transport documentation reduces boarding and relocation friction, enabling platform-based pet mobility services.
Industry Challenges
- Certified veterinary technician recruitment:CVT licensure requirements vary by state, complicating multi-jurisdiction staffing and credential recognition for telehealth paraprofessional deployment.
- Legacy practice management system integration:Cloud-native diagnostic and scheduling platforms face resistance from clinic owners with sunk costs in on-premise server infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pet Care and Services Market |
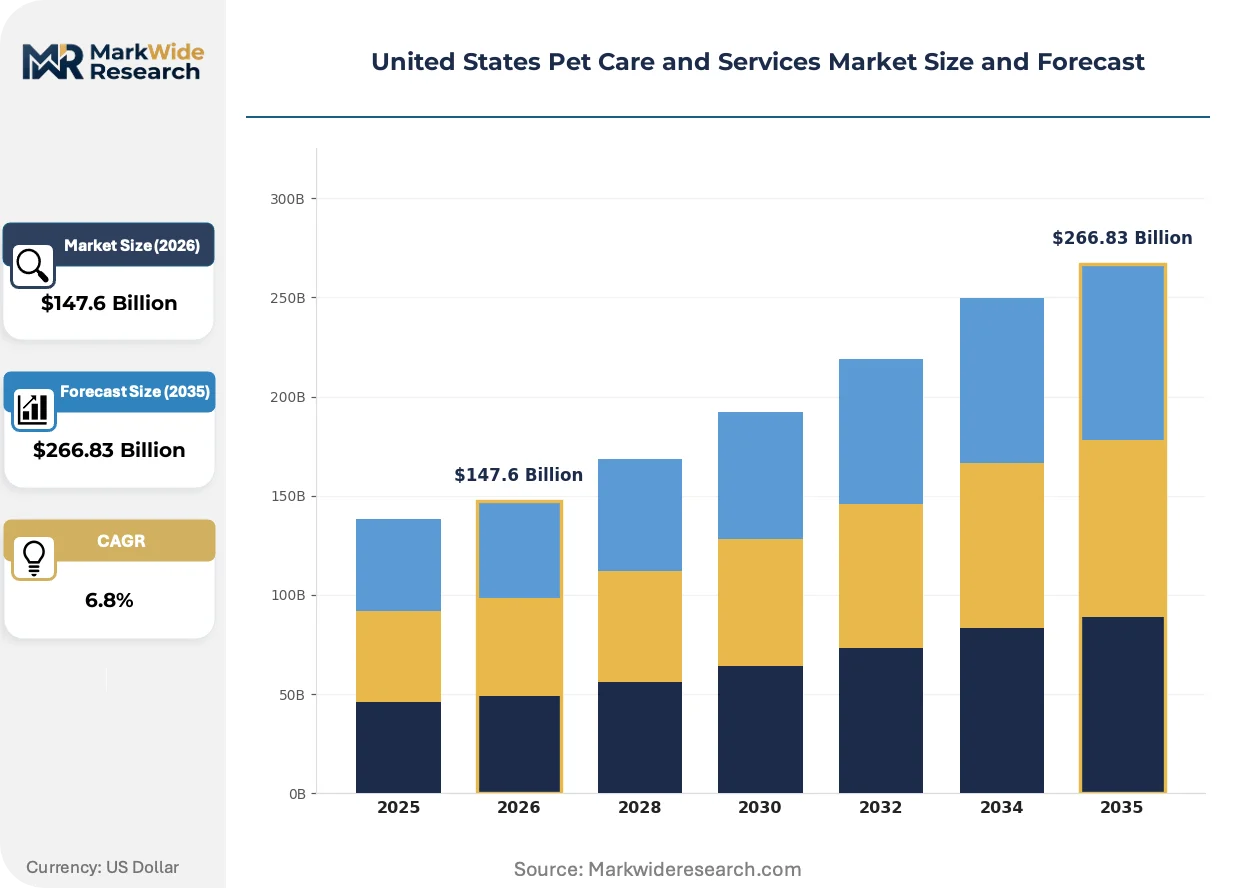
| Market Size in 2026 | $147.6 Billion |
| Market Size in 2035 | $266.83 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Grooming, Training, Walking, Boarding Pet Type: Dogs, Cats, Birds, Reptiles Product Category: Food, Accessories, Health Products, Toys Distribution Channel: Online Retail, Pet Stores, Supermarkets, Veterinary Clinics |
| Companies Covered | PetSmart LLC, Mars, Incorporated, Petco Health & Wellness Company, Inc., Chewy, Inc., Nestlé Purina PetCare, Hill's Pet Nutrition, Inc., IDEXX Laboratories, Inc., Trupanion, Inc., Zoetis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pet Care and Services Market Evolving Landscape
Direct-to-consumer subscription models and at-home diagnostic hardware are compressing the traditional clinic visit cycle, shifting preventive care touchpoints from physical facilities to owner-managed environments.
Telehealth platforms with asynchronous symptom triage and AI-assisted image recognition are decentralizing first-contact veterinary consultations. Millennial and Gen Z pet owners in metropolitan markets adopt these tools at rates exceeding telemedicine penetration in human primary care. This shift compresses emergency room utilization for non-urgent presentations while creating channel conflict with established brick-and-mortar practices.
The FDA Center for Veterinary Medicine's enforcement discretion framework for compounded animal drugs is tightening quality documentation requirements. Manufacturers must now demonstrate batch testing and stability data for office-use preparations. This policy elevates compliance costs for independent pharmacies while favoring 503B outsourcing facilities with validated quality systems.
Subscription-based fresh food delivery is displacing mass-market kibble purchasing among urban households with single-pet or small-multiple-pet configurations. Direct distribution bypasses retail slotting fees and enables precise portion customization by weight, age, and activity level. California and New York metropolitan areas exhibit the highest subscription penetration, with spillover into secondary markets via social media referral loops.
United States Pet Care and Services Market Segmentation
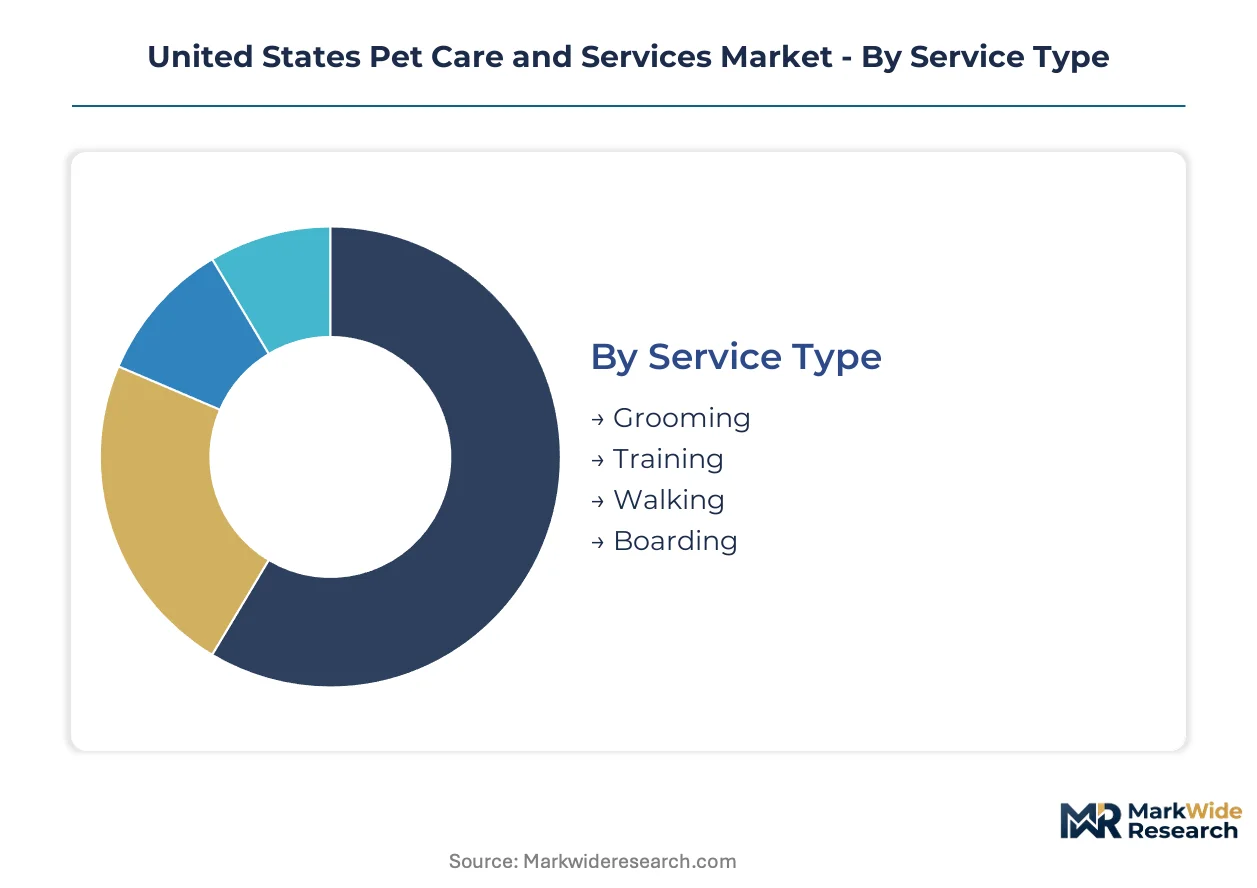
Segmentation in the United States pet care and services market exposes divergent margin profiles and channel economics across service delivery models. Distinct buyer archetypes—from urban Millennials seeking subscription convenience to rural owners prioritizing veterinary proximity—drive category-specific investment priorities.
Service Type:
Buyer willingness to pay varies sharply by perceived skill specialization and frequency of need.
- Grooming:Coat-specific services (hydrotherapy, breed-standard cuts) command premium pricing in metropolitan California and Texas markets. Demand concentrates among small-breed dog owners in urban zip codes where apartment living limits at-home maintenance.
- Training:Behavioral modification for separation anxiety and leash reactivity captures out-of-pocket spend from first-time Millennial dog owners. Demand clusters in Florida metropolitan areas where rescue dog adoption rates exceed national averages.
- Walking:Midday exercise services scale through gig-economy platforms with GPS-tracked visit verification.
- Boarding:Enrichment programming and webcam access differentiate premium operators from commodity kennel capacity.
Grooming leads volumes today; training is gaining share fastest.
Pet Type:
Species-specific metabolic and behavioral requirements dictate entirely different supply chain and service configurations.
- Dogs:Canine nutrition demands precise protein-fat ratios calibrated to activity level and life stage. Veterinary diagnostic spending concentrates in senior dog populations across suburban Texas and Florida markets.
- Cats:Feline preventive care historically underperforms canine benchmarks, though chronic kidney disease screening is expanding diagnostic capture rates. Urban California households drive demand for specialized feline-only veterinary practices.
- Birds:Avian veterinary services require specialized equipment and anesthesia protocols available only in major metropolitan corridors.
- Reptiles:Habitat temperature and UVB lighting specifications create durable accessories demand with limited service attach opportunities.
Dogs dominate revenue contribution; cats are climbing the fastest among companion animal categories.
Product Category:
Repeat purchase frequency and margin structure diverge dramatically across physical goods versus health interventions.
- Food:Extruded kibble, fresh-cooked subscription meals, and raw formulations span mass to ultra-premium price tiers. Subscription penetration concentrates in California and New York metropolitan areas where direct-to-consumer brands bypass retail slotting fees.
- Health Products:Prescription therapeutics and preventive parasiticides generate superior per-unit margins driven by FDA Center for Veterinary Medicine compliance requirements. Demand clusters in states with high veterinary clinic density.
- Accessories:Collars, leashes, and bedding function as impulse and gift purchases with seasonal concentration.
- Toys:Durability and safety certification (ASTM F963 alignment) differentiate mass-market from premium positioning.
Food anchors purchase frequency; health products deliver the steepest margin expansion trajectory.
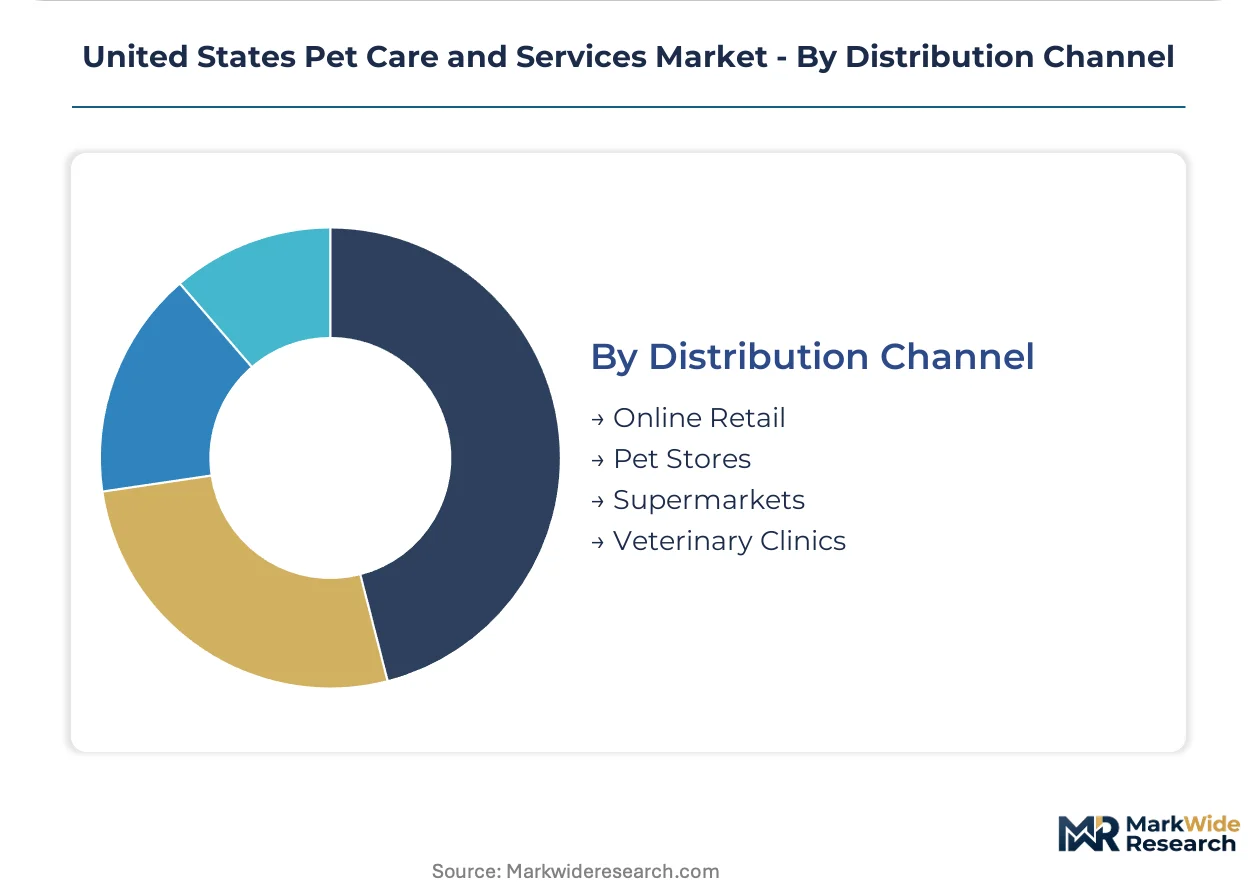
Distribution Channel:
Channel selection reflects owner convenience thresholds and the complexity of purchase decision support required.
- Online Retail:Subscription auto-ship and same-day delivery platforms capture urban households seeking replenishment automation. California and New York metro areas exhibit highest penetration, with spillover into secondary markets via social referral.
- Pet Stores:Big-box format with in-store veterinary clinic partnerships anchors competitive positioning through service bundling and loyalty program density.
- Supermarkets:Mass-market kibble and treat placement competes on price transparency and promotional velocity.
- Veterinary Clinics:Prescription diet and therapeutic product distribution tied to VCPR requirements creates channel exclusivity for clinically indicated nutrition.
Pet stores lead transaction volumes today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pet care industry traces its modern scale to post-war suburban expansion, when rising household pet ownership created distributed demand for veterinary services and manufactured nutrition. Regional concentration now follows metropolitan pet density, state regulatory frameworks, and specialized service infrastructure.
California
Los Angeles and San Francisco metropolitan areas sustain the nation's highest subscription penetration for direct-to-consumer fresh pet food. The California Veterinary Medical Board enforces strict telemedicine VCPR requirements that shape digital health platform deployment. San Diego anchors specialized feline-only veterinary practice expansion, with urban households driving demand for species-specific clinical environments.
Texas
Dallas-Fort Worth and Houston metropolitan corridors concentrate boarding facility investment with enrichment programming and behavioral consulting services. The Texas State Board of Veterinary Medical Examiners maintains VCPR requirements that restrict asynchronous consultation models. Austin's rescue dog adoption rates exceed national benchmarks, generating outsized demand for separation anxiety and reactivity training services.
Florida
Miami and Tampa metropolitan areas support premium grooming economics through small-breed dog ownership in apartment-dense zip codes. The Florida Department of Business and Professional Regulation oversees veterinary practice acts that influence clinic expansion timelines. Orlando's tourism infrastructure enables pet-friendly hospitality service bundling, integrating boarding with travel-oriented wellness packages.
New York
New York City metropolitan pet density sustains gig-economy dog walking platforms with GPS-tracked visit verification. The New York State Education Department regulates veterinary technician scope of practice across multi-jurisdiction staffing deployments. Buffalo and Rochester secondary markets exhibit subscription service spillover via social media referral loops from primary metro adopters.
Illinois
Chicago metropolitan veterinary diagnostic spending concentrates in senior dog populations across suburban collar counties. The Illinois Department of Financial and Professional Regulation shapes telehealth reimbursement parity debates affecting service delivery model selection. Peoria and Springfield markets face veterinary labor supply constraints from accredited DVM program output limitations, creating persistent rural staffing bottlenecks.
United States Pet Care and Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and service bundling depth. The market structure fragments across three tiers: diversified nutrition science conglomerates, specialized veterinary service platforms, and direct-to-consumer subscription operators. Strategic archetypes include vertically integrated manufacturers with captive ingredient sourcing, big-box retailers with in-store clinic partnerships, and cloud-native diagnostic platforms. Dominant competitive moves encompass M&A for therapeutic nutrition portfolios and geographic expansion of subscription fulfillment infrastructure.
Among diversified nutrition conglomerates, Mars, Incorporated and Nestlé Purina PetCare occupy positions exemplifying premium therapeutic and mass-market wellness formulation breadth. Within veterinary diagnostics, IDEXX Laboratories, Inc. anchors the reference laboratory and in-clinic testing platform segment. These three entities represent distinct strategic archetypes: Mars and Nestlé Purina exemplify CPG-derived pet nutrition scale, while IDEXX occupies the clinical diagnostics infrastructure tier.
| Leading Market Players |
|---|
| PetSmart LLC |
| Mars, Incorporated |
| Petco Health & Wellness Company, Inc. |
| Chewy, Inc. |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition, Inc. |
| IDEXX Laboratories, Inc. |
| Trupanion, Inc. |
| Zoetis |
| Others |
Value Network & Pricing Analysis
Beef and poultry meal commodity indices cascade through pet food manufacturing into three distinct pricing tiers, with protein input volatility compressing margins for mid-tier producers lacking forward contracting capabilities while premium subscription operators maintain pricing power through direct-to-consumer relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation driven by ingredient quality grade and veterinary prescription status. Price differentiation intensifies as FDA Center for Veterinary Medicine compliance costs elevate therapeutic nutrition positioning. Pricing pressure stems from protein commodity volatility, particularly affecting standard-tier manufacturers. Rural and exurban veterinary service buyers exhibit highest price sensitivity, while urban Millennial subscribers to fresh-cooked meal plans demonstrate lowest elasticity.
Supply Chain Analysis
Product return flows and packaging waste recovery programs are emerging as cost centers for subscription pet food operators managing temperature-controlled logistics. Manufacturing concentrates in the United States, with ingredient sourcing drawing from domestic meat processing byproducts and imported fish meal from Peru and Southeast Asia. Supply chain risk centers on single-source vulnerability for specialized veterinary pharmaceuticals. Distribution runs through direct-to-consumer fulfillment centers, big-box retail consolidation points, and veterinary clinic dispensing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary telehealth reimbursement parity gaps between California and Texas create geographic-arbitrage opportunities for platform operators able to navigate divergent state Veterinary Practice Act requirements.
For Market Incumbents: Anticipate asynchronous consultation platform entrants by securing multi-state veterinary medical board licenses ahead of regulatory harmonization. Defensive consolidation through captive supply of therapeutic nutrition ingredients offsets protein commodity volatility. Channel control via in-store clinic partnerships at PetSmart and Petco locations protects against direct-to-consumer subscription erosion.
For New Entrants and Emerging Players: The mid-market pricing gap between premium fresh subscription services and economy kibble offers entry opportunity for regional fresh-cooked operators with localized fulfillment. White-space targets include senior pet therapeutic nutrition formulations and behavioral health training services in Florida metropolitan rescue-dense markets. Go-to-market leverage through veterinary clinic referral partnerships accelerates trust acquisition.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native diagnostic platforms integrating AI-assisted image recognition for asynchronous triage. Long-term viability across the analysis window favors operators with validated quality systems under FDA Center for Veterinary Medicine enforcement discretion frameworks. Acquisition targets include 503B outsourcing facilities with batch testing capabilities. Monitor state veterinary technician scope-of-practice expansion as inflection signal for telehealth paraprofessional deployment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees and enables precise portion customization by pet weight and life stage. |
| In-Store Veterinary Clinic Partnership | Creates service bundling density that anchors big-box competitive positioning against online entrants. |
| Therapeutic Nutrition Portfolio Expansion | Captures FDA-compliant prescription diet margins unavailable to mass-market wellness formulations. |
| Telehealth Platform Integration | Compresses emergency room utilization while navigating state-level VCPR requirement fragmentation. |
| Packaging Sustainability Repositioning | Addresses Pet Sustainability Coalition accountability framework pressure before regulatory mandate. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary practice owners, pet food manufacturing procurement leads, retail category buyers, and telehealth platform operators with secondary validation against FDA Center for Veterinary Medicine enforcement discretion filings, state veterinary medical board regulatory updates, and Nielsen retail audit data. Bottom-up service provider revenue aggregation and top-down household pet expenditure estimates were triangulated for consistency.
Historical reference periods anchored the forecast window through retrospective analysis of subscription penetration trajectories and veterinary diagnostic spending patterns across metropolitan statistical areas. Segmentation modeling incorporated service type, pet species, product category, and distribution channel dimensions with regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation adjusted for protein commodity cycle positioning and telehealth reimbursement parity legislative momentum.
Caveats apply where state veterinary practice act revisions or FDA feed safety modernization enforcement intensity could materially shift the outlook for asynchronous consultation models and compounded drug quality documentation requirements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
India Pet Clothing Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Dog Safety Leash Market
Pet Care Products
Pet Beds Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Pet Tag Market
Pet Care Products
Cat Mat Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Dog Pad Market
Pet Care Products
Netherlands Pet Food Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market