
 UK Dog Food Market | 2026-2036
UK Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
UK Dog Food Market Insights
Subscription-based replenishment services is consolidating around recurring delivery models that lock in lifetime value beyond single-transaction kibble sales. Mars Incorporated leverages its vertically integrated supply chain to control ingredient sourcing from farm to bowl. Nestlé Purina anchors its position through science-backed veterinary formulations that command shelf space in professional channels. Butcher's Pet Care specializes in British-sourced wet food recipes that resonate with locally minded consumers.
UK dog food comprises nutritionally formulated feed products manufactured through extrusion, canning, or cold-pressed processes to meet AAFCO-equivalent nutrient profiles for canine maintenance, growth, or therapeutic conditions. Dry kibble dominates volume due to shelf stability and lower logistics costs, while raw and grain-free segments capture disproportionate margin pools as ingredient-quality premiums widen. Wet food retains loyal followings among small-breed owners prioritizing palatability and moisture content. Online distribution channels are displacing supermarket dominance as direct-to-consumer platforms capture recurring purchase data.
DEFRA enforces pet food labeling and traceability rules under the Animal Feed Regulations, while the FSA monitors manufacturing hygiene through retained EU hygiene regulations post-Brexit. The Advertising Standards Authority polices health claims on packaging, constraining how brands communicate nutritional benefits to consumers. Stakeholders must monitor evolving novel protein approval pathways and shifting retailer sustainability requirements to maintain formulation relevance and shelf access.
Market Dynamics
Subscription-based replenishment models are restructuring UK dog food economics by converting sporadic supermarket purchases into predictable recurring revenue streams that lock in lifetime customer value.
Growth Catalysts
- DEFRA Traceability Mandates:The Animal Feed Regulations enforce ingredient provenance disclosure, compelling manufacturers to upgrade sourcing transparency and premiumize formulations.
- Urban Household Concentration:Greater London's dense pet-owning population accelerates same-day and scheduled delivery adoption for heavy kibble replenishment.
- Cold-Pressed Processing:Lower-temperature manufacturing preserves heat-sensitive nutrients, enabling brands to command ingredient-quality premiums in the raw-adjacent segment.
Market Restraints
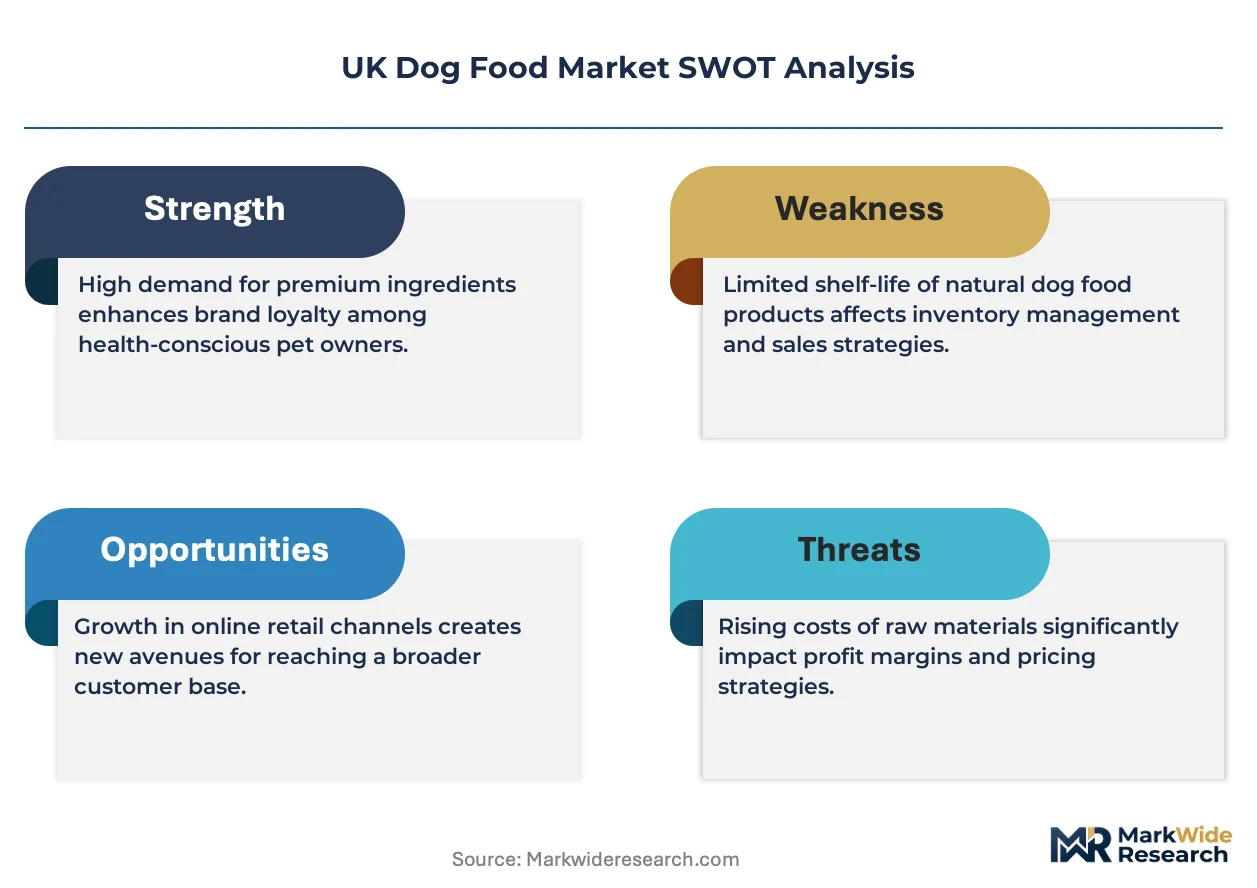
- Protein Input Volatility:British poultry and red meat prices fluctuate with agricultural commodity cycles, compressing margin stability for wet food specialists.
- Retailer Consolidation Risk:Tesco, Sainsbury's, and Morrisons control dominant shelf space, extracting listing fees that disadvantage emerging challenger brands.
- Novel Protein Approval Friction:Insect-based and cultivated protein sources face extended European Food Safety Authority novel food authorization timelines.
Strategic Opportunities
- Veterinary Channel Underpenetration:Practice-exclusive therapeutic formulations remain underdeveloped relative to US market depth, offering white space for science-backed entrants.
- FSA Hygiene Regulation Alignment:Post-Brexit retained EU hygiene standards create compliance clarity that British manufacturers can leverage for export certification.
- Direct-to-Consumer Platform Convergence:Subscription APIs integrating with smart feeder hardware enable automated replenishment triggered by consumption sensors.
Industry Challenges
- Formulation Talent Scarcity:Veterinary nutritionists and regulatory affairs specialists command premium salaries amid competition from pharmaceutical and human food sectors.
- Legacy System Integration:Established manufacturers struggle to retrofit ERP systems for real-time subscription inventory management and predictive demand forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Dog Food Market |
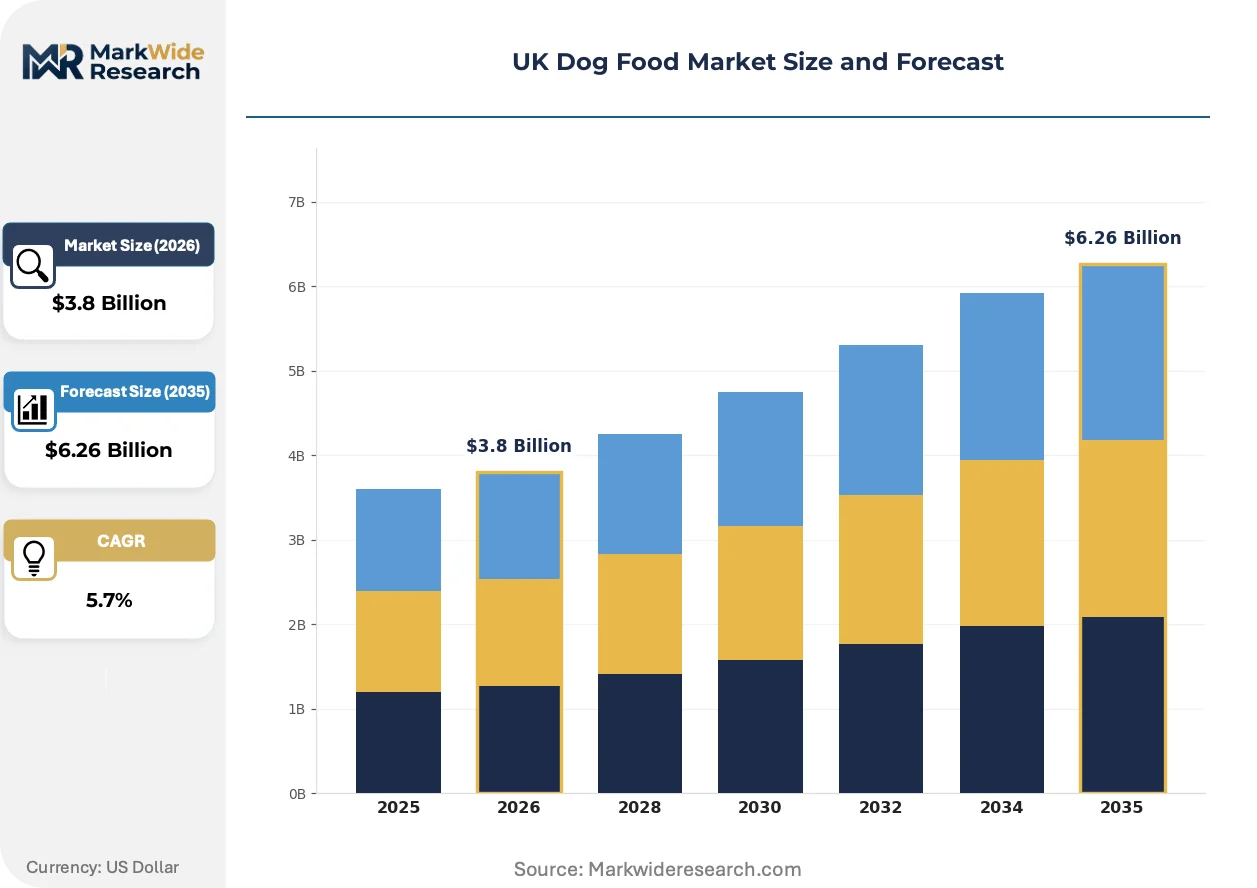
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry, Wet, Treats, Raw Ingredient Quality: Natural, Organic, Grain-Free, Premium Distribution Channel: Online, Supermarkets, Pet Specialty Stores, Warehouse Clubs Dog Size: Small Breed, Medium Breed, Large Breed, All Sizes |
| Companies Covered | Mars Incorporated, Nestlé Purina, Hill's Pet Nutrition, The J.M. Smucker Company, GA Pet Food Partners, Butcher's Pet Care, Pets Choice, Burns Pet Nutrition, Lily's Kitchen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Dog Food Market Trends and Innovations
Digital infrastructure and shifting consumption rituals are compressing traditional retail intermediaries while elevating transparency and personalization as competitive differentiators across British pet nutrition.
Smart feeder technology is decentralizing replenishment decision-making from owner memory to automated consumption monitoring. Affluent households in the South East deploy WiFi-connected dispensers that track intake patterns and trigger algorithmic reordering. This infrastructure shift is decentralizing inventory risk from retailers to manufacturers while generating proprietary consumption datasets.
DEFRA's evolving animal feed labeling requirements under retained EU frameworks tighten permissible health claim language on packaging. The Advertising Standards Authority actively polices nutritional benefit assertions, constraining how brands communicate functional ingredients. Wet food and treat categories face the steepest compliance recalibration as palatability marketing intersects with therapeutic positioning scrutiny.
Subscription bundling is compressing the traditional supermarket replenishment cycle into consolidated monthly deliveries with personalized portioning. Urban professionals in Manchester and Bristol increasingly favor curated boxes combining kibble, toppers, and dental chews over aisle browsing. This behavioral pivot concentrates purchase data with direct-to-consumer platforms that disaggregate traditional retail analytics.
UK Dog Food Market Segmentation
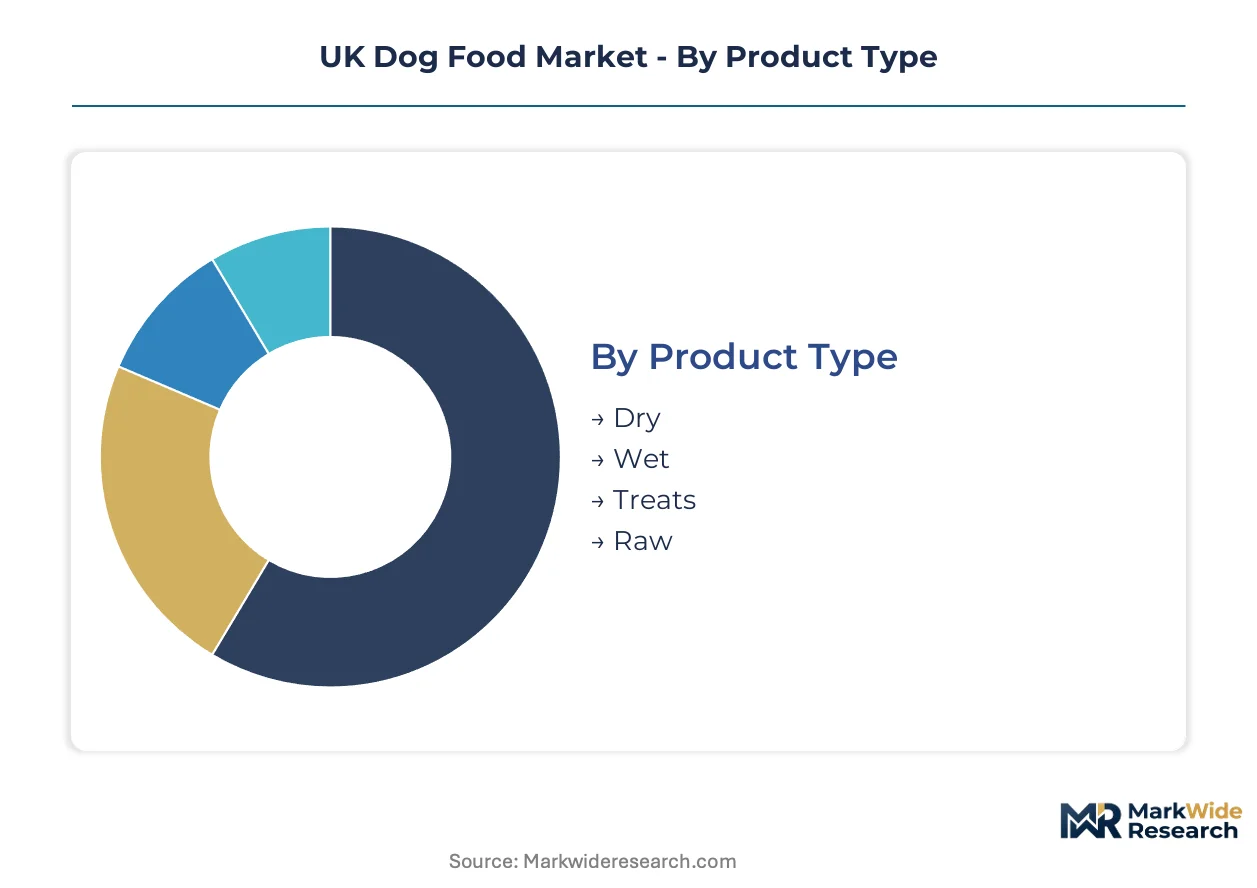
UK dog food segmentation reveals divergent margin structures across format and channel choices. Purchase decisions cluster around convenience thresholds, ingredient transparency demands, and breed-specific nutritional requirements that reshape manufacturer prioritization.
Product Type:
Cost tier differentiation separates mass-market replenishment from premium fresh formats in this category.
- Dry:Extruded kibble delivers shelf-stable nutrition at the lowest per-kilogram logistics cost. Greater London households favor bulk dry formats for scheduled delivery integration, though cold-pressed variants command ingredient premiums in the South East.
- Wet:Canned and tray formats prioritize palatability and moisture content for small-breed owners. Butcher's Pet Care anchors this segment through British-sourced meat recipes that resonate with locally minded purchasers in urban centers.
- Treats:Functional and dental chew formats capture impulse purchase behavior across channels.
- Raw:Frozen and freeze-dried formulations target raw-adjacent nutrition seekers with minimal processing claims.
Dry leads volumes today; raw is gaining share fastest.
Ingredient Quality:
Application context determines whether owners prioritize certification badges or clean-label simplicity.
- Natural:Minimally processed ingredient positioning without synthetic additives dominates mainstream premium shelves. Manchester and Bristol subscription services bundle natural kibble with toppers to justify recurring price points.
- Organic:Soil Association certification commands listing fees at Waitrose and Ocado that challenger brands struggle to absorb. DEFRA traceability mandates compound compliance costs for organic supply chains.
- Grain-Free:Potato and legume-based formulations target digestive sensitivity positioning.
- Premium:Veterinary endorsement and breed-specific tailoring support price architecture.
Natural leads volumes today; organic is climbing the fastest.
Distribution Channel:
Customer type separates subscription-committed urban professionals from price-sensitive bulk purchasers.
- Online:Direct-to-consumer platforms capture proprietary consumption data through subscription APIs. Smart feeder hardware integration enables automated replenishment triggered by sensor readings in affluent South East households.
- Supermarkets:Tesco, Sainsbury's, and Morrisons extract listing fees that disadvantage emerging brands. Promotional cadence drives stock-up behavior among price-sensitive owners in the Midlands.
- Pet Specialty Stores:Pets at Home and independent retailers provide formulation consultation and loyalty program lock-in.
- Warehouse Clubs:Costco and similar operators move bulk dry formats for multi-dog households.
Supermarkets lead volumes today; online is expanding most quickly.
Dog Size:
Volume scale and feeding frequency reshape packaging economics and replenishment rhythm.
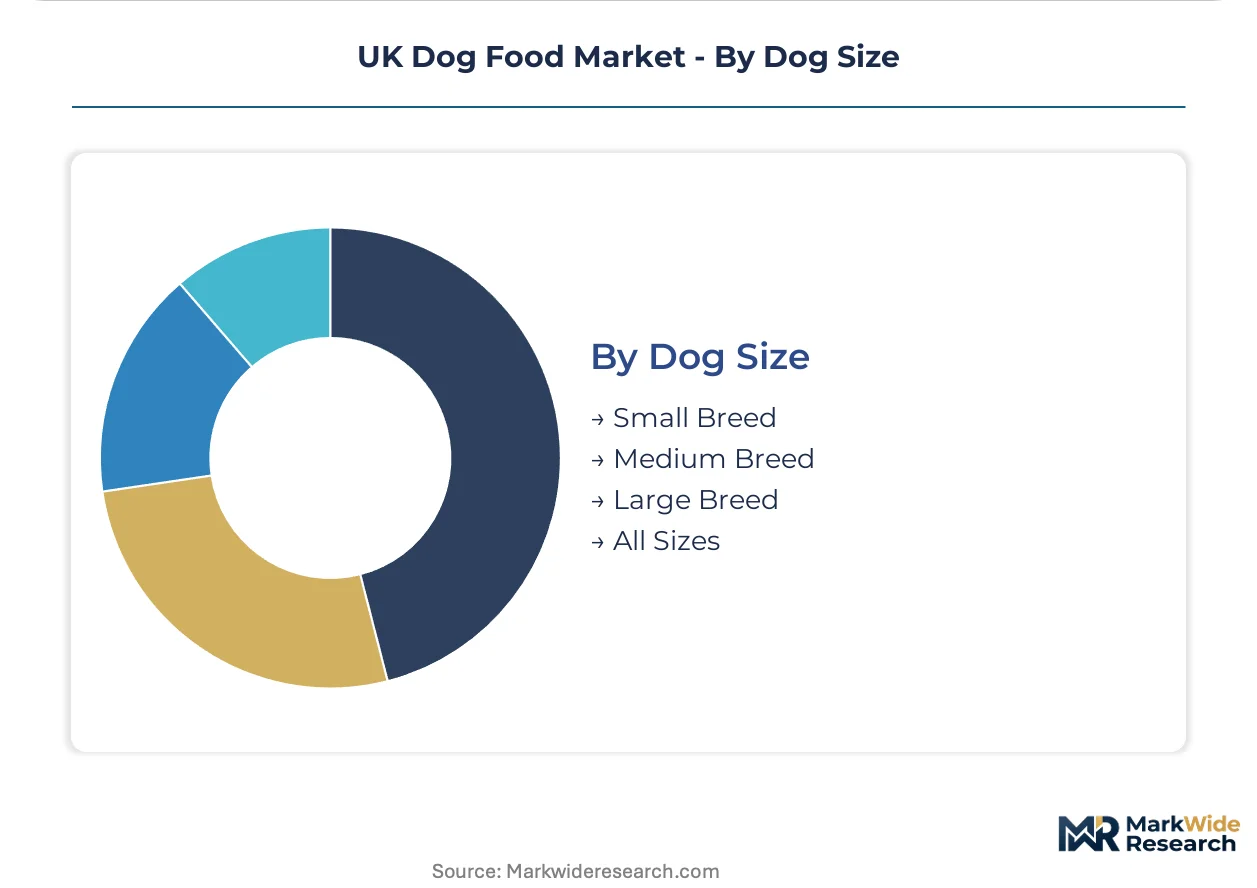
- Small Breed:Higher per-kilogram willingness-to-pay for palatability and portion control. Urban flats in Greater London concentrate small-breed ownership where wet food and toppers dominate.
- Medium Breed:Balanced dry-wet consumption patterns with moderate bag sizes.
- Large Breed:Bulk dry consumption with joint health and weight management formulation requirements.
- All Sizes:Life-stage formulations spanning puppy through senior without breed specificity.
All sizes leads volumes today; small breed shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cold-pressed manufacturing infrastructure outpaces British capacity, while France's agricultural cooperatives supply novel protein inputs that UK formulators increasingly source. Regulatory divergence post-Brexit is fragmenting supply chain coordination across these neighboring markets.
Greater London and South East
Affluent households in Kensington, Chelsea, and Surrey drive premiumization through subscription services and smart feeder adoption. DEFRA's Animal Feed Regulations enforce traceability standards that manufacturers must integrate into labeling systems. The M25 corridor concentrates direct-to-consumer fulfillment centers serving same-day delivery zones.
Midlands
Price-sensitive bulk purchasing patterns dominate Birmingham and Leicester pet-owning demographics. The Food Standards Agency monitors manufacturing hygiene at co-packing facilities across Staffordshire and Derbyshire. Coventry hosts cold-pressed processing specialists supplying natural-positioned brands.
North England
Manchester and Leeds subscription adoption accelerates among young professional households seeking convenience. Local authority environmental health teams enforce retained EU hygiene regulations at wet food canneries. Yorkshire's agricultural base supplies poultry and red meat inputs to regional formulators.
Scotland
Edinburgh and Glasgow concentrate small-breed ownership in urban flats favoring wet food palatability. Food Standards Scotland aligns with FSA frameworks while maintaining distinct enforcement protocols. Aberdeen's proximity to North Sea fishing fleets supports fish-based protein sourcing for premium formulations.
Wales
Rural multi-dog households in Powys and Gwynedd favor bulk dry formats through warehouse club channels. Welsh Government rural development programs support local meat sourcing for artisan pet food producers. Wrexham's manufacturing corridor hosts extrusion facilities serving private label contracts.
UK Dog Food Market Competitive Landscape
Top-tier vendors anchor mass-market shelf presence, while mid-tier specialists and challenger brands compete through subscription channels and ingredient differentiation. Mars Incorporated and Nestlé Purina control dominant retail listings through veterinary endorsement and marketing scale. Strategic archetypes include multinational CPG conglomerates, British-sourced wet food specialists, and direct-to-consumer subscription platforms. Competitive moves center on backward integration into protein sourcing and API development for automated replenishment systems.
Among multinational conglomerates, Mars Incorporated and Nestlé Purina exemplify scale-driven positioning through vertically controlled supply chains and science-backed formulation claims. Butcher's Pet Care represents the British-sourced archetype, anchoring wet food segments through locally minded positioning. These three entities occupy distinct competitive vectors—mass-market penetration, veterinary channel depth, and regional authenticity—without overlapping strategic territory.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina |
| Hill's Pet Nutrition |
| The J.M. Smucker Company |
| GA Pet Food Partners |
| Butcher's Pet Care |
| Pets Choice |
| Burns Pet Nutrition |
| Lily's Kitchen |
| Others |
Pricing and Supply Chain Analysis
Urban subscription households in Greater London and the South East concentrate purchasing power, locking in recurring revenue models that trade per-transaction margin for lifetime value capture across wet and dry formats.
Pricing Analysis
Capacity additions in cold-pressed processing across the Midlands are reshaping price floors for natural-positioned brands. Three-tier pricing structure across premium, standard, and economy levels separates Soil Association-certified organic recipes from mass-market extruded kibble and private-label economy bags. Pricing pressure stems from protein input volatility in British poultry and red meat markets, compressing wet food specialist margins. Price-sensitive bulk purchasers in the Midlands and Wales drive stock-up behavior through warehouse clubs, while affluent South East households show lowest sensitivity to subscription premiums.
Supply Chain Analysis
Reverse logistics for frozen raw formats and temperature-controlled wet food returns flow through regional cold-chain hubs in Staffordshire and Derbyshire. Primary protein sourcing draws from British poultry farms in Yorkshire and North Sea fishing fleets near Aberdeen, with secondary dependence on EU agricultural cooperatives for novel protein inputs. Single-source vulnerability concentrates in cold-pressed equipment manufacturing, where German engineering suppliers dominate British capacity expansion. Distribution runs through direct-to-consumer fulfillment centers along the M25 corridor, displacing traditional supermarket replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK dog food operates as a geographic-arbitrage play between DEFRA's retained EU traceability frameworks and emerging markets with weaker ingredient disclosure mandates, where British compliance investments convert to export certification premiums.
For Market Incumbents: Hedge margin exposure by securing captive poultry supply contracts in Yorkshire and accelerating backward integration into rendering facilities. Channel control through veterinary practice exclusivity defends against subscription-platform disintermediation. Certification investment in Soil Association organic tiers locks out challenger brands from Waitrose and Ocado shelf space.
For New Entrants and Emerging Players: Direct-to-consumer APIs offer the most penetrable route for algorithmic replenishment tied to smart feeder hardware consumption data. White space concentrates in veterinary-exclusive therapeutic formulations, where science-backed entrants undercut Hill's Pet Nutrition and Nestlé Purina professional channel depth. Go-to-market angle: partner with Manchester and Bristol urban professional clusters for curated subscription bundling.
For Investors and Strategic Acquirers: Multinational CPG conglomerates are the most active acquirer in this space, seeking British-sourced authenticity positioning. Long-term viability favors mid-tier specialists with backward-integrated protein sourcing and subscription platform technology. Acquisition target archetype: cold-pressed processing specialists with FSA hygiene certification and export-ready capacity. Signal to watch: DEFRA novel protein approval timelines for insect-based formulations as margin structure inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Rendering | Captive poultry supply from Yorkshire farms stabilizes input costs against commodity volatility. |
| Smart Feeder API Development | Algorithmic reordering triggered by consumption sensors locks in recurring revenue across South East households. |
| Veterinary Channel Exclusivity | Practice-exclusive therapeutic formulations command premium shelf space in professional channels. |
| Cold-Pressed Capacity Expansion | Lower-temperature manufacturing preserves heat-sensitive nutrients for raw-adjacent premium positioning. |
| Soil Association Certification Investment | Organic tier compliance opens Waitrose and Ocado listings that challenger brands struggle to absorb. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with veterinary nutritionists, FSA manufacturing inspectors, subscription platform CTOs, and Pets at Home category buyers combined with secondary validation through DEFRA Animal Feed Regulations filings, Nielsen retail audit data, and British Poultry Council supply reports. Bottom-up demand modeling from breed-size consumption patterns and top-down market sizing from customs trade flows were triangulated for consistency.
Segment-weighting approaches applied differential growth assumptions across product type, ingredient quality tier, distribution channel, and dog size dimensions. CAGRs were derived from fitted trend analysis incorporating urban household concentration, cold-pressed processing adoption curves, and subscription penetration rates. Forecast inputs included DEFRA traceability mandate implementation timelines and smart feeder hardware shipment data across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for insect-based protein approval would alter the outlook. Forecasts reflect assumptions about retained EU hygiene regulation stability and protein input price normalization. Practitioners should monitor EFSA novel food authorization timelines and retailer sustainability requirement shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Dog Brush Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Cat Backpacks Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Pet Care Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
South Africa Pet Food Market
Pet Care Products
China Pet Food Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Pet Smart Tracker Market