
 Gcc Pet Food Market | 2026-2036
Gcc Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Gcc Pet Food Market Intelligence
Buyer concentration among dog owners is hardening across the GCC as pet humanization accelerates in Saudi Arabia and the UAE. Nestlé Purina leverages its global formulation expertise to dominate premium dry food shelves in Riyadh and Dubai. Mars Incorporated sustains shelf presence through deep distribution partnerships with Carrefour and Lulu hypermarkets. Hill's Pet Nutrition Inc. differentiates via prescription diet positioning aligned with veterinary clinic networks.
GCC pet food encompasses nutritionally complete and complementary feeds manufactured through extrusion, canning, or cold-pressing processes, with formulations meeting AAFCO or FEDIAF nutrient profiles adapted to regional climate and breed needs. Dry food occupies the largest volume share due to storage convenience and lower per-gram cost in high-temperature environments. Wet food registers faster value growth as cat ownership expands among apartment dwellers in Doha and Manama. Grain-free ingredient positioning commands margin premiums, though regulatory scrutiny on carbohydrate substitution is intensifying.
Saudi Food and Drug Authority import permits and UAE Ministry of Climate Change and Environment halal certification requirements shape product registration timelines and formulation constraints across Gulf markets. SFDA labeling mandates on protein source disclosure are forcing reformulation of economy-tier imports. Stakeholders must monitor evolving Gulf Standardization Organization harmonization talks, as unified pet food standards would reshape competitive access across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and the UAE.
Market Dynamics
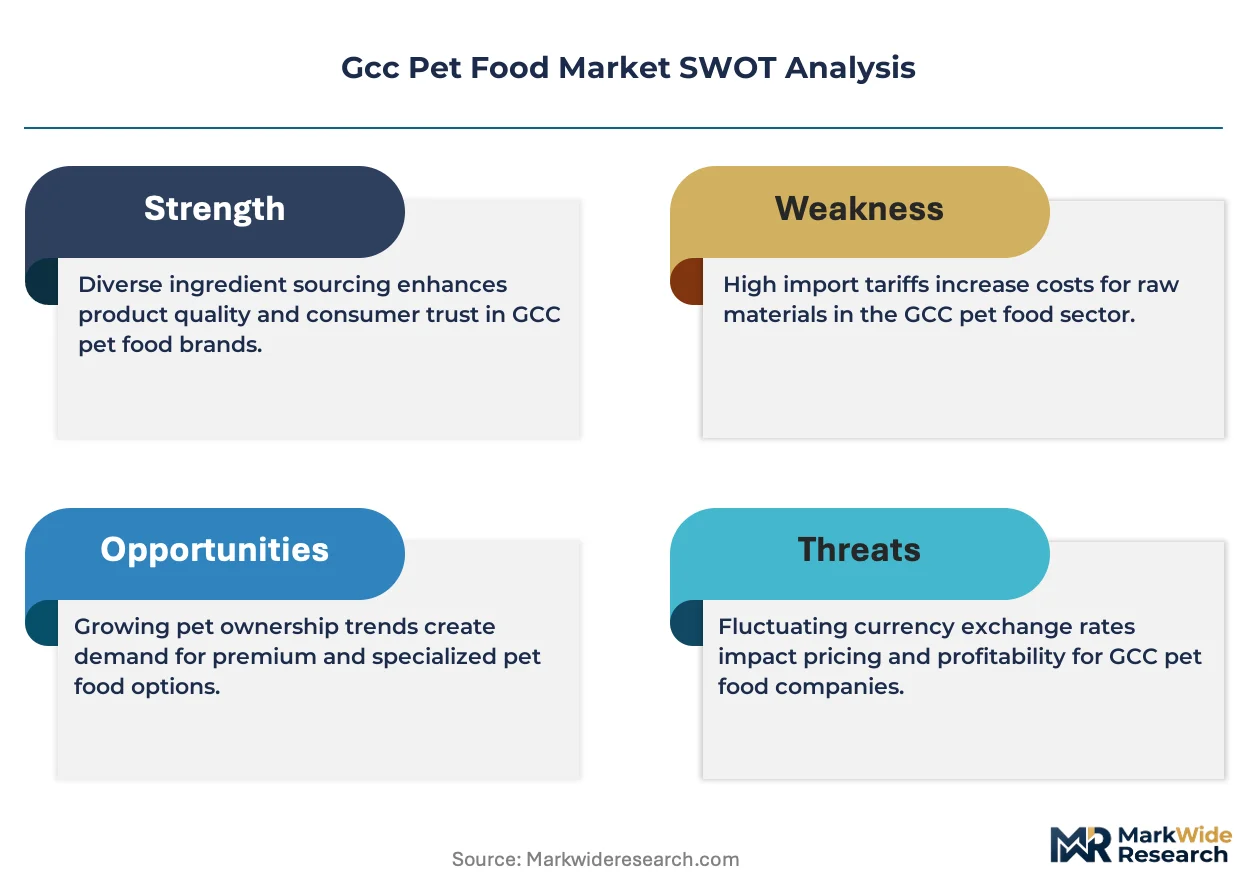
Pet humanization among Saudi and Emirati households is compressing purchase cycles and hardening ingredient preferences, forcing manufacturers to reformulate around grain-free positioning while navigating divergent halal certification requirements across Gulf states.
Growth Catalysts
- SFDA Protein Disclosure Mandates:Saudi Food and Drug Authority labeling rules on protein source transparency are accelerating premium tier adoption as economy imports face reformulation costs.
- Apartment-Dwelling Cat Ownership:Rising cat adoption in Doha and Manama high-rises is expanding wet food consumption, outpacing dry food value growth in Qatar and Bahrain.
- Veterinary Clinic Network Density:Prescription diet distribution through Saudi and UAE veterinary channels is creating captive demand for therapeutic formulations.
Market Restraints
- Import Permit Volatility:SFDA and UAE Ministry of Climate Change and Environment registration timelines create six-to-twelve month product launch delays.
- Climate-Driven Storage Costs:High-temperature warehousing requirements in Jeddah and Dubai inflate working capital needs for wet food inventory.
- Ingredient Substitution Scrutiny:Carbohydrate replacement in grain-free formulations faces intensifying Gulf Standardization Organization review.
Strategic Opportunities
- Oman and Kuwait Underpenetration:Pet ownership rates in Muscat and Kuwait City lag Riyadh and Dubai by forty percent, creating first-mover expansion corridors.
- Cold-Pressed Nutrition Positioning:Low-temperature processing technology offers differentiation against extruded commodity products in premium shelves.
- E-Commerce Subscription Models:Direct-to-consumer auto-replenishment bypasses hypermarket slotting fees and captures recurring revenue.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Formulation expertise for breed-specific and therapeutic diets concentrates in Western markets, complicating local R&D.
- Halal Supply Chain Segregation:Dedicated production lines for GCC-compliant products raise capital intensity versus shared global facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gcc Pet Food Market |
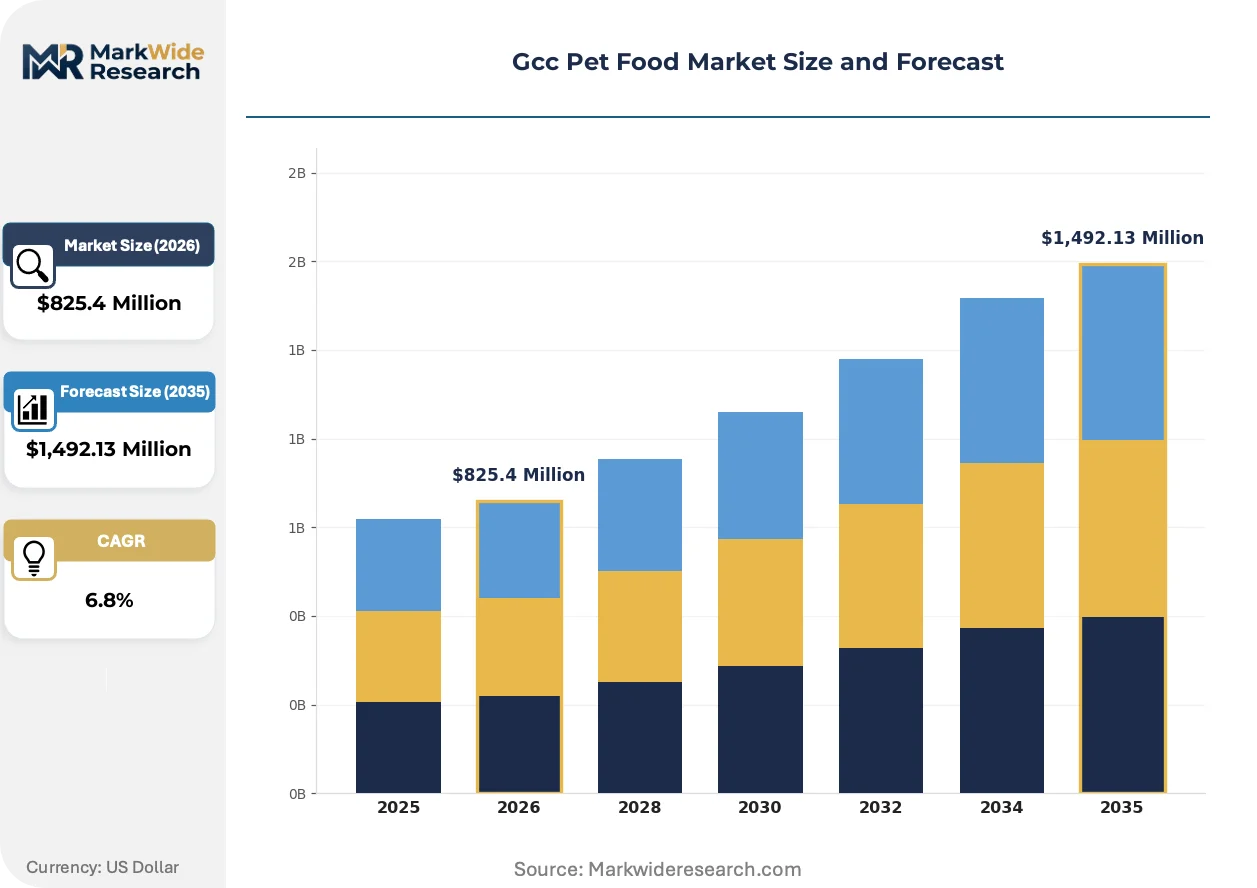
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Distribution Channel: Online Retail, Supermarkets, Pet Shops, Specialty Stores End User: Dog Owners, Cat Owners, Small Animal Owners, Bird Owners Ingredient Type: Grain-Free, Organic, High-Protein, Prescription Diets |
| Companies Covered | Nestlé Purina, Mars Incorporated, Hill’s Pet Nutrition Inc., General Mills Inc., WellPet LLC, The J.M. Smucker Company, Schell & Kampeter Inc., Heristo AG, Diamond Pet Foods, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gcc Pet Food Market Strategic Shifts & Innovations
Extrusion technology refinements and cold-pressed processing advances are reshaping formulation capabilities, while regulatory harmonization talks and channel fragmentation are redrawing competitive access patterns across the Gulf.
Smart packaging with humidity indicators and oxygen scavengers is automating shelf-life management in Saudi and UAE retail environments. Premium brands in Riyadh and Dubai are adopting these sensors to reduce spoilage claims in high-temperature supply chains. The technology is automating quality assurance workflows that previously required manual inventory rotation.
UAE Ministry of Climate Change and Environment halal certification requirements are tightening ingredient traceability obligations for imported pet food. Manufacturers must now document slaughterhouse compliance for animal-derived components across their entire supply base. Wet food importers face the steepest compliance burden due to higher meat inclusion rates.
Subscription-based auto-replenishment is displacing traditional hypermarket bulk purchasing among affluent Saudi and Emirati pet owners. Younger households in Jeddah and Abu Dhabi prioritize convenience over per-unit cost savings. This channel shift concentrates customer data with direct-to-consumer platforms, eroding retailer leverage over shelf placement negotiations.
Gcc Pet Food Market Segmentation
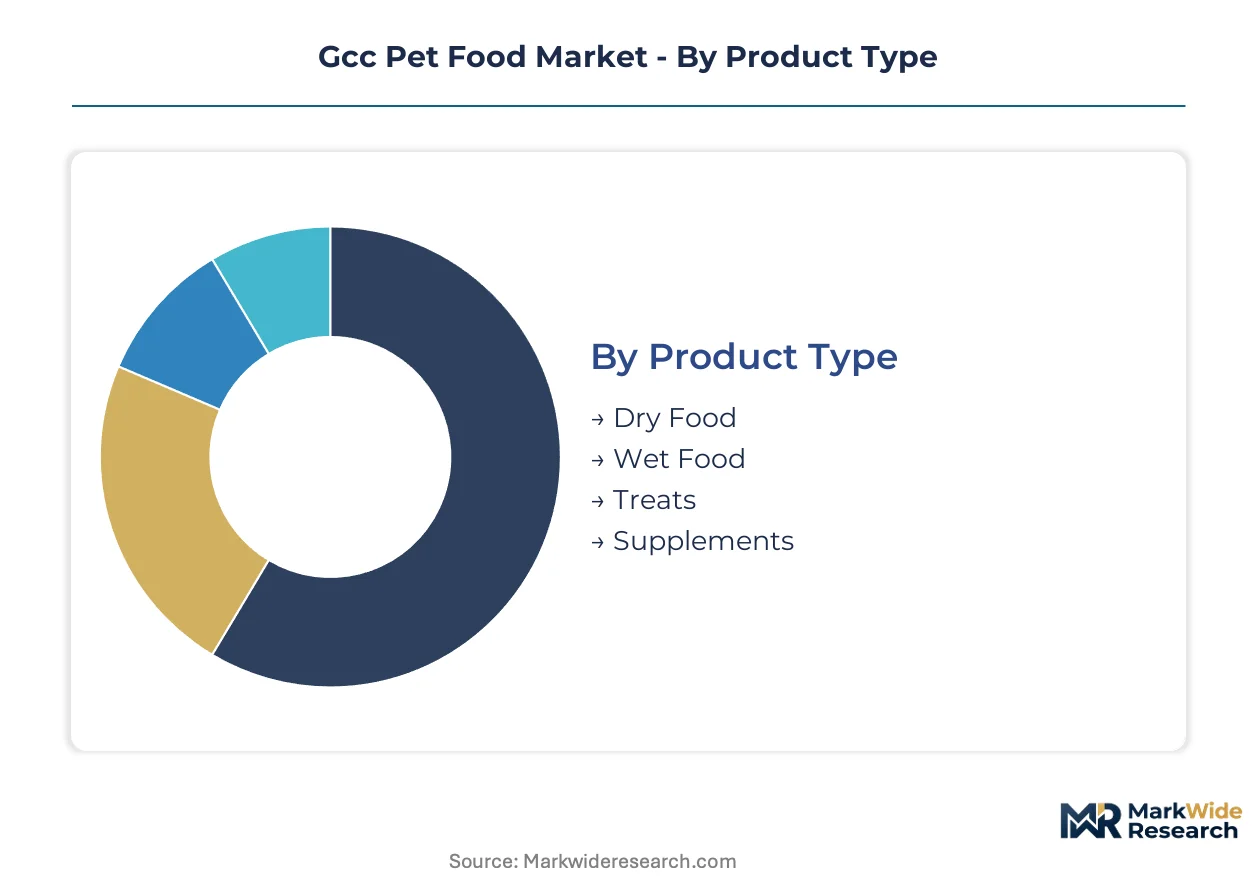
Segmentation in the GCC pet food market reveals how climate constraints, regulatory fragmentation, and channel evolution create distinct competitive arenas. Manufacturers must align formulation investments with distribution economics and end-user preferences that vary sharply across Saudi Arabia, the UAE, and smaller Gulf states.
Product Type:
Standalone dry formulations dominate warehouse economics, while wet and functional categories embed deeper into veterinary and subscription channels.
- Dry Food:Extruded kibble formulations with moisture content below 10 percent suit Jeddah and Dubai storage conditions where refrigeration costs erode wet food margins. Saudi hypermarket chains move bulk volumes through Carrefour and Lulu shelf placements, though grain-free positioning commands slotting fee premiums.
- Wet Food:Canned and pouch formats with 75-85 percent moisture content align with feline hydration needs in Doha and Manama apartment dwellings. Cat ownership concentration in Qatar and Bahrain drives value expansion faster than volume, despite climate-driven cold chain costs.
- Treats:Functional and reward formulations occupy impulse purchase zones in UAE pet shop checkout lanes.
- Supplements:Joint, coat, and digestive additives distribute primarily through veterinary clinic recommendation in Riyadh and Dubai.
Dry food leads volumes today; wet food is gaining share fastest.
Distribution Channel:
Channel selection determines margin capture, with direct-to-consumer models bypassing traditional retail levy structures.
- Online Retail:Auto-replenishment platforms capture recurring revenue from Jeddah and Abu Dhabi millennials who prioritize convenience over per-unit savings. Subscription data concentration erodes retailer negotiating leverage over shelf placement.
- Supermarkets:Carrefour and Lulu hypermarkets in Saudi Arabia and the UAE maintain dry food volume dominance through bulk pack promotions and loyalty program integration.
- Pet Shops:Independent and chain pet retailers in Dubai and Doha provide species-specific consultation that drives premium tier conversion.
- Specialty Stores:Veterinary-exclusive and premium nutrition boutiques in Riyadh and Manama focus on prescription diet fulfillment and breed-specific formulations.
Supermarkets anchor volume throughput; online retail is expanding most quickly.
End User:
Species-specific nutritional requirements fragment manufacturing runs and formulation R&D priorities.
- Dog Owners:Large-breed and working dog formulations dominate Saudi demand, with premiumization trends hardening around grain-free and high-protein positioning. SFDA protein disclosure mandates accelerate economy-tier displacement.
- Cat Owners:Apartment-dwelling feline populations in Doha, Manama, and Abu Dhabi drive wet food and litter-adjacent purchasing patterns, with urinary health formulations gaining veterinary endorsement.
- Small Animal Owners:Rabbit, guinea pig, and hamster keepers in Kuwait and Oman represent emerging demand pockets with limited local formulation availability.
- Bird Owners:Avian nutrition concentrates in UAE specialty retail, with import dependency for species-specific seed and pellet blends.
Dog owners command revenue concentration; cat owners are climbing the fastest.
Ingredient Type:
Ingredient positioning separates margin tiers, with certification requirements and substitution scrutiny reshaping competitive access.
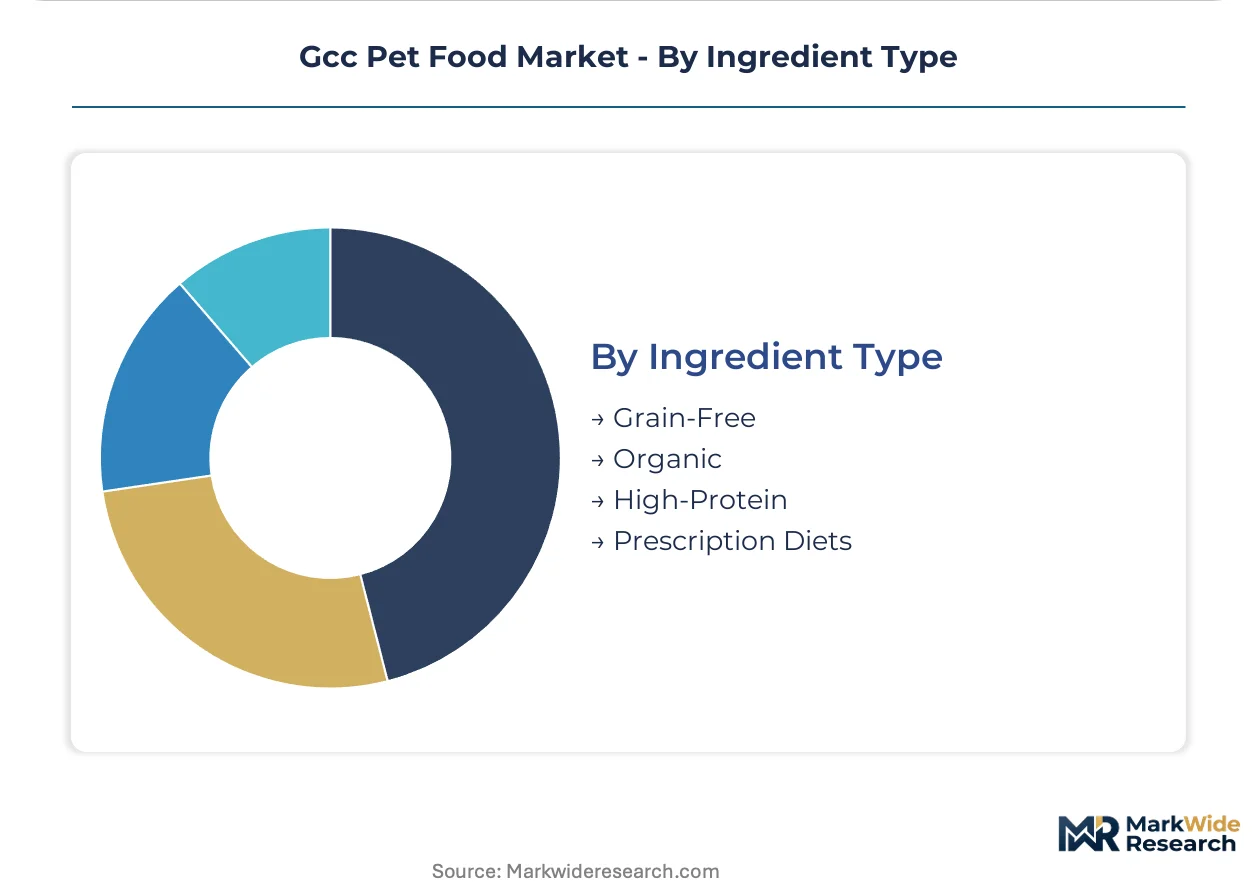
- Grain-Free:Carbohydrate replacement with legumes, tubers, and novel proteins commands 20-40 percent price premiums in Riyadh and Dubai premium shelves. Gulf Standardization Organization scrutiny on substitution safety is intensifying reformulation costs.
- Organic:Certified organic supply chains face halal segregation requirements that raise production line capital intensity for GCC-dedicated facilities.
- High-Protein:Elevated meat inclusion formulations align with raw feeding trends among Saudi and Emirati enthusiasts, though cold chain requirements constrain wet format economics.
- Prescription Diets:Therapeutic formulations for renal, diabetic, and gastrointestinal conditions distribute through captive veterinary channels in Saudi Arabia and the UAE, creating switching cost barriers.
Grain-free leads volume positioning; prescription diets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands larger pet food volumes than the UAE, yet Emirati consumers adopt premium formulations at faster rates. The Gulf Cooperation Council's regulatory fragmentation creates divergent entry timelines across member states.
Saudi Arabia
Large-breed dog ownership and working animal traditions sustain dry food demand across Riyadh and Jeddah. SFDA protein disclosure mandates are accelerating economy-tier displacement as importers absorb reformulation costs. The Eastern Province's logistics corridors host temperature-controlled warehousing clusters serving domestic distribution.
United Arab Emirates
Apartment-dwelling cat populations in Dubai and Abu Dhabi expand wet food consumption faster than dry alternatives. UAE Ministry of Climate Change and Environment halal certification requirements tighten slaughterhouse documentation for animal-derived ingredients. Sharjah's free trade zones concentrate re-export operations targeting smaller Gulf markets.
Qatar
High-rise residential patterns in Doha compress living spaces and favor feline companionship over large dogs. The country's national food safety authority aligns import permit timelines with Gulf Standardization Organization harmonization talks. Lusail's emerging retail corridors attract premium brand flagship placements.
Bahrain
Manama's dense urban core mirrors Doha's cat ownership concentration and wet food preference patterns. Central Bank liquidity regulations indirectly affect distributor working capital for cold chain inventory. Muharraq's veterinary clinic density exceeds national averages and supports prescription diet penetration.
Oman
Pet ownership rates in Muscat lag Riyadh and Dubai by substantial margins, creating expansion headroom for first movers. The Ministry of Agriculture and Fisheries maintains less stringent registration timelines than Saudi or Emirati counterparts. Salalah's port infrastructure offers alternative import routes bypassing Strait of Hormuz congestion.
Gcc Pet Food Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The market exhibits moderate concentration, with multinational food groups leveraging global R&D scale against regional distributors with veterinary channel relationships. Three archetypes dominate: global nutrition conglomerates with Gulf-dedicated production lines, prescription diet specialists anchored in clinic networks, and private-label contractors serving hypermarket chains. Capacity expansion and strategic partnerships constitute the primary competitive moves, as slotting fee negotiations and cold chain investments reshape access economics.
Within the global conglomerate tier, Nestlé Purina and Mars Incorporated exemplify scale-driven positioning through shelf dominance in Saudi and Emirati retail corridors. Hill's Pet Nutrition Inc. occupies the prescription-focused archetype, with its clinic-centric distribution model creating switching cost barriers. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Nestlé Purina |
| Mars Incorporated |
| Hill's Pet Nutrition Inc. |
| General Mills Inc. |
| WellPet LLC |
| The J.M. Smucker Company |
| Schell & Kampeter Inc. |
| Heristo AG |
| Diamond Pet Foods |
| Others |
Cost & Logistics Intelligence
Cold-pressed processing technology adoption in UAE and Saudi manufacturing facilities is compressing production costs for premium formulations while concentrating supply leverage among operators with dedicated halal-certified lines. This dual effect reshapes margin structures across grain-free and therapeutic tiers as smaller importers face reformulation cost barriers.
Pricing Analysis
Capacity additions in Saudi Arabia are reshaping price floors for dry food segments as local extrusion investments reduce import dependency. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and protein disclosure compliance. Cost compression in economy tiers is intensifying because SFDA labeling mandates force reformulation of legacy imports. Hypermarket bulk purchasers in Riyadh show highest price sensitivity; veterinary channel buyers in Dubai demonstrate lowest sensitivity due to therapeutic necessity.
Supply Chain Analysis
Return flows of expired or recalled wet food products from Dubai and Jeddah retail channels are driving reverse-logistics infrastructure investments among distributors with cold-chain capabilities. Manufacturing concentrates in Thailand, France, and the United States for premium formulations; regional toll production in Saudi Arabia serves mass-market dry segments. Raw material dependencies center on poultry meal, fish oil, and novel protein sources from certified halal slaughterhouses. Single-source vulnerability runs through UAE Ministry of Climate Change and Environment import permit bottlenecks. Distribution runs through Carrefour and Lulu hypermarket networks for volume, with veterinary clinics and subscription platforms capturing premium tier fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC pet food market functions as a stable compounder anchored by irreversible pet humanization trends among Saudi and Emirati households. Regulatory tightening on protein disclosure and halal certification creates persistent barriers that protect invested incumbents.
For Market Incumbents: Hedge against prescription diet margin erosion by deepening veterinary clinic network exclusivity in Riyadh and Dubai before generic therapeutic entrants gain formulary access. Accelerate backward integration into cold-pressed production capabilities to capture grain-free premiumization without third-party tolling dependencies. SFDA registration timeline volatility threatens working capital efficiency for importers lacking local manufacturing. For New Entrants and Emerging Players: UAE Ministry of Climate Change and Environment halal certification requirements in the Emirates open a window for specialists with pre-certified supply chains to bypass incumbent reformulation delays. Target underpenetrated Muscat and Kuwait City markets where pet ownership rates lag Riyadh and Dubai by substantial margins. Lead with e-commerce subscription models to bypass hypermarket slotting fee structures and capture recurring revenue from convenience-prioritizing millennials. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with veterinary channel relationships but without captive manufacturing. The five-to-ten year viability thesis rests on persistent premiumization and regulatory moat deepening. Monitor Gulf Standardization Organization harmonization progress as the inflection signal; unified standards would reshape competitive access economics across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and the UAE.| Strategic Initiative | Industry Significance |
|---|---|
| Halal-Certified Production Line Investment | SFDA and UAE Ministry compliance accelerates product registration timelines versus import-dependent competitors. |
| Veterinary Clinic Network Expansion | Prescription diet distribution through Riyadh and Dubai clinics creates captive demand with high switching costs. |
| Cold-Pressed Processing Adoption | Low-temperature technology differentiates premium positioning against commodity extruded products in UAE retail. |
| E-Commerce Subscription Platform Launch | Auto-replenishment captures recurring revenue from Jeddah millennials while bypassing Lulu slotting fees. |
| Oman and Kuwait Market Entry | First-mover expansion into Muscat and Kuwait City exploits forty percent penetration gaps versus Saudi Arabia. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and regulatory interpretation nuances. Primary discussions with pet food brand managers, veterinary clinic procurement heads, SFDA regulatory affairs specialists, and Carrefour category buyers informed formulation and channel dynamics. Secondary validation drew from SFDA import permit databases, UAE Ministry of Climate Change and Environment certification registries, Gulf Standardization Organization harmonization documentation, and Nielsen retail audit data for Saudi and Emirati hypermarkets. Bottom-up SKU-level demand modeling and top-down macroeconomic anchoring were cross-checked for consistency.
Segment-weighted forecasting applied distinct growth assumptions across dry, wet, treats, and supplements by species and distribution channel throughout the projection horizon. Product type, ingredient positioning, end-user species, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from trend extrapolation moderated by regulatory event probability and channel shift elasticity. Breed-specific formulation R&D intensity and cold chain infrastructure development served as industry-specific forecast inputs.
Revisions become necessary when Gulf Standardization Organization harmonization talks conclude, SFDA protein disclosure mandates expand to complementary feeds, or wet food cold chain disruptions persist beyond seasonal patterns. Practitioners should monitor veterinary clinic network density in secondary cities and subscription platform customer acquisition costs for early signals of channel power shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Mobile Pet Care Market
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Toy Dog Market