
 High Protein Dog Food Market | 2026-2036
High Protein Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
High Protein Dog Food Market Foresight
Extrusion technology is narrowing the gap between mass-market kibble and raw-nutrient retention, enabling brands to hit protein thresholds previously reserved for freeze-dried formats. Mars Petcare Inc. leverages global manufacturing scale to standardize high-protein formulations across multiple price tiers. Nestlé Purina PetCare anchors its portfolio in veterinary science credibility, while Orijen specializes in whole-prey ingredient ratios that command shelf-space premiums in specialty retail.
High protein dog food denotes formulations where protein constitutes the dominant macronutrient, typically exceeding crude protein thresholds through concentrated meat meals, hydrolyzed proteins, or novel animal ingredients processed via low-temperature drying or cold-press methods to preserve amino acid bioavailability. Dry food dominates volume due to logistics efficiency and extended shelf stability, though raw food segments capture disproportionate margin pools through subscription direct-to-consumer channels. Plant-based ingredient sources face formulation complexity around digestible amino acid completeness, while functionality positioning around muscle gain and weight management attracts performance-oriented buyers willing to pay certification premiums.
The FDA Center for Veterinary Medicine oversees pet food safety under the Federal Food, Drug, and Cosmetic Act, while AAFCO establishes model regulations for nutritional adequacy claims that most US states adopt. The USDA Agricultural Marketing Service shapes organic and grass-fed certification pathways that protein-source marketing increasingly invokes. Stakeholders must monitor evolving state-level raw-food sale restrictions and potential federal scrutiny of "human-grade" labeling claims that currently operate in regulatory gray zones.
Market Dynamics
Extrusion technology is compressing the cost-performance gap between mass-market kibble and premium raw formats, forcing incumbents to defend shelf space through accelerated protein threshold claims rather than traditional brand equity.
Growth Catalysts
- AAFCO Model Bill Adoption:State-level harmonization of nutritional adequacy claims reduces interstate formulation friction for multi-brand portfolios.
- Cold-Press Processing Scale-Up:Equipment manufacturers in Germany and Italy are commercializing lower-temperature extrusion lines that preserve lysine bioavailability in meat meals.
- Urban Pet Ownership Density:Metropolitan households in the United States and United Kingdom concentrate demand for subscription-formatted fresh and raw protein delivery.
Market Restraints
- Animal Protein Input Volatility:Chicken meal and fish meal prices swing with livestock feed grain costs and aquaculture harvest cycles.
- Freeze-Dried Capacity Concentration:Contract manufacturing for low-temperature drying clusters in Pacific Northwest processing corridors, creating single-point supply risk.
- Raw Food State Restrictions:FDA guidance documents and state agriculture department rules in several jurisdictions limit retail sale of unpasteurized formats.
Strategic Opportunities
- Insect Protein Regulatory Pathways:EFSA novel food approvals and FDA GRAS self-affirmation channels are opening black soldier fly and cricket meal for complete-and-balanced formulations.
- Veterinary Channel Integration:Prescription high-protein therapeutic diets for renal and weight management cases bypass price competition in mass retail.
- Direct-to-Consumer Cold Chain:Refrigerated subscription logistics now reach secondary cities in Texas, Florida, and Ohio with sub-48-hour freshness guarantees.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Pet food companies compete with human food and pharmaceutical sectors for protein chemists and companion animal nutritionists.
- Human-Grade Labeling Compliance:USDA FSIS edible-grade facility requirements for pet food plants demand capital outlays that mid-tier brands struggle to fund.
- Legacy ERP Integration:Lot traceability systems for raw ingredient provenance must interface with decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Protein Dog Food Market |
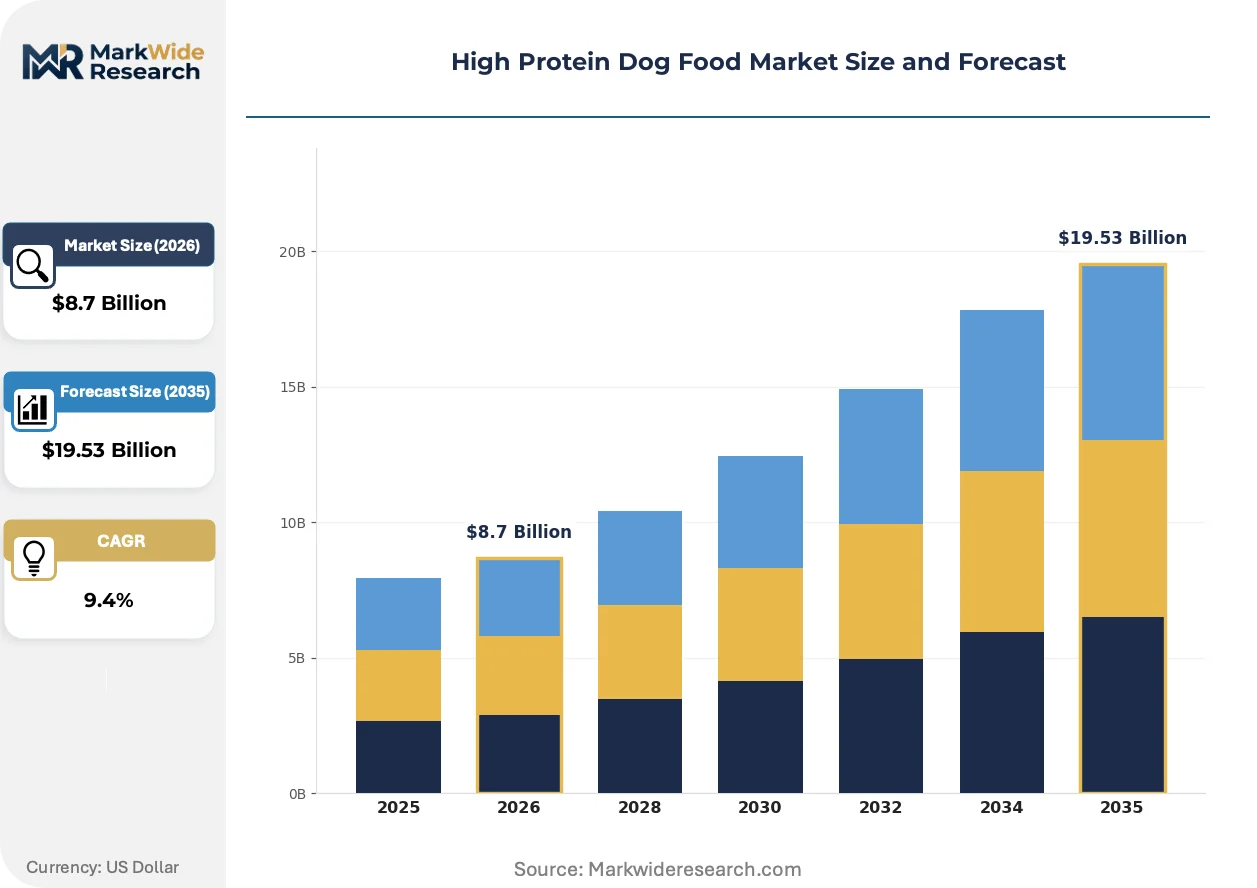
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Source: Meat, Fish, Plant-Based, Mixed Functionality: Weight Management, Muscle Gain, Energy Boost, Overall Health Packaging Type: Bags, Cans, Pouches, Bulk |
| Companies Covered | Mars Petcare Inc., Nestlé Purina PetCare, Hill's Pet Nutrition, The J.M. Smucker Company, General Mills Inc., Diamond Pet Foods, Orijen, Stella & Chewy's, Wellness Pet LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Protein Dog Food Market Shifts & Advancements
Protein sourcing and processing methods are diverging sharply between commodity cost optimization and bioavailability-maximizing premium positioning, with technology investment determining which tier brands can credibly occupy.
Cold-press extrusion is hybridizing the operational efficiency of conventional kibble manufacturing with the nutrient retention profiles previously exclusive to freeze-dried formats. Specialty retailers and veterinary clinics are the primary adoption channels for these intermediate-price-point products. This convergence is compressing margin structures for legacy freeze-dried specialists while enabling mass-market brands to claim protein density parity.
EFSA's expanding novel food catalog for insect proteins is creating regulatory precedent that the FDA Center for Veterinary Medicine is monitoring for potential GRAS pathway alignment. European formulation labs are advancing black soldier fly meal inclusion rates above 25% in complete diets. North American brands are responding with limited-ingredient trials pending domestic regulatory clarity.
Subscription-based fresh protein delivery is displacing periodic retail replenishment among urban households with single-pet ownership. Direct-to-consumer channels capture these buyers through veterinary nutritionist consultations bundled with auto-ship programs. This shift concentrates in coastal metropolitan corridors where cold-chain logistics density supports weekly delivery cadences.
High Protein Dog Food Market Segmentation
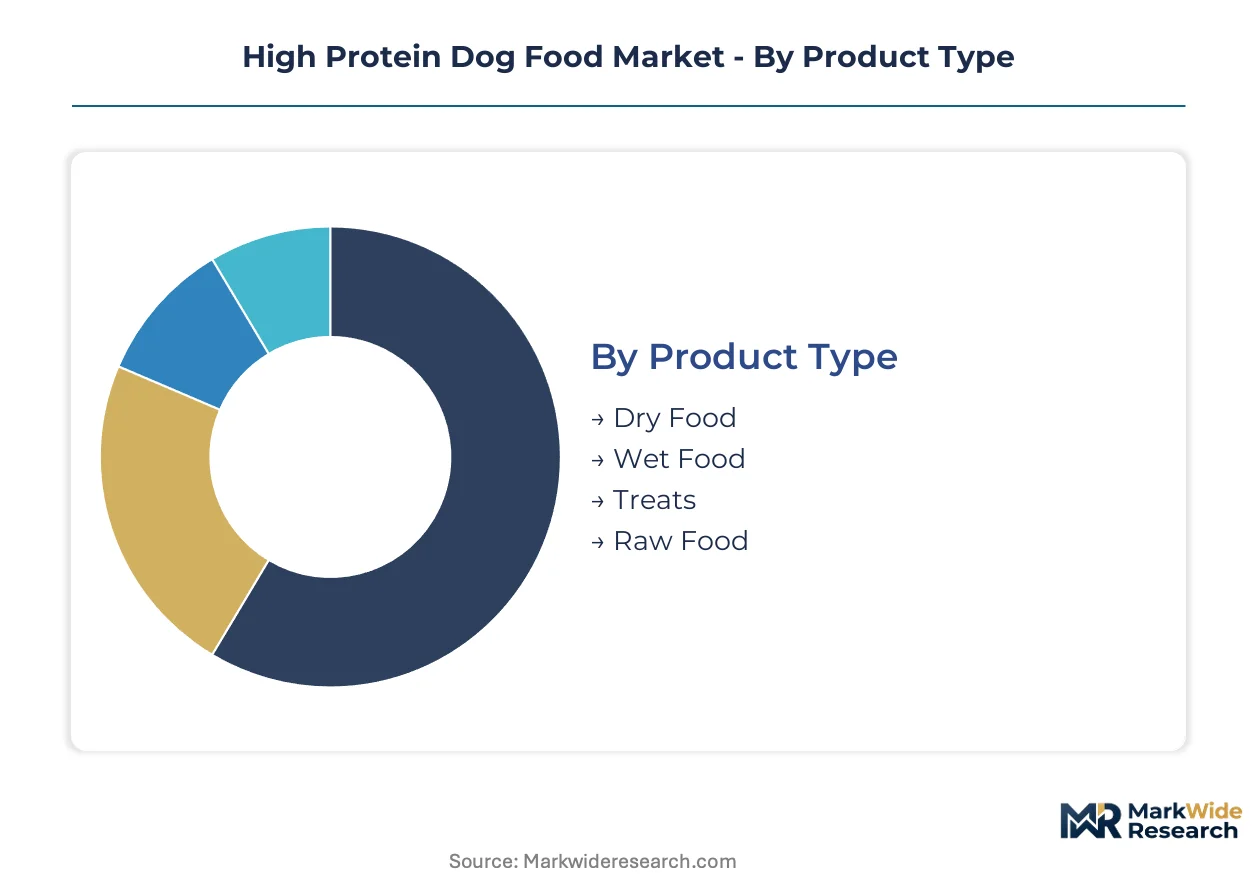
High protein dog food segmentation reveals how protein concentration, processing method, and delivery format intersect to create distinct margin pools and channel strategies. Manufacturers must align formulation investments with the specific performance claims and convenience expectations each segment commands.
Product Type:
Mature formats dominate volume while emerging processing technologies reshape competitive boundaries between shelf-stable and fresh alternatives.
- Dry Food:Extruded kibble formulations achieve protein density through concentrated meat meals and hydrolyzed proteins, with cold-press advances narrowing the nutrient-retention gap with freeze-dried alternatives. United States mass retail channels concentrate demand for 28-32% crude protein variants targeting working breeds and performance dogs.
- Raw Food:Unpasteurized or HPP-treated whole-prey formulations deliver bioavailable amino acid profiles through minimal thermal processing, though state-level retail restrictions in California, New Jersey, and Maryland constrain distribution expansion. Subscription direct-to-consumer channels in metropolitan corridors capture premium buyers seeking ancestral diet positioning.
- Wet Food:Retort-processed cans and trays utilize protein-rich gravies and chunked muscle meat to achieve palatability thresholds for senior dogs and finicky eaters.
- Treats:High-protein training rewards and dental chews incorporate dehydrated organ meats and single-ingredient freeze-dried proteins for intermittent supplementation.
Dry food retains volume leadership; raw food holds the steepest expansion curve.
Ingredient Source:
Cost tier differentiation separates commodity protein inputs from novel and certified sourcing premiums that command shelf-space positioning.
- Meat:Chicken meal, beef meal, and pork meal provide concentrated protein density at scale, with USDA Agricultural Marketing Service organic and grass-fed certifications enabling price premiums in specialty retail. Formulation chemists balance rendered protein bioavailability against palatability thresholds for high-inclusion diets.
- Plant-Based:Pea protein, potato protein, and yeast concentrates face digestibility challenges around methionine and taurine completeness, though EFSA novel food approvals for fermented protein sources are expanding formulation options in European markets.
- Fish:Salmon meal, whitefish meal, and krill deliver omega-3 fatty acid co-benefits alongside protein density, with Marine Stewardship Council certification increasingly invoked in coastal United States markets.
- Mixed:Blended animal-plant formulations optimize cost-performance ratios for mid-tier positioning while managing amino acid complementarity.
Meat-sourced formulations dominate current revenue; plant-based alternatives are climbing the fastest as regulatory clarity emerges.
Functionality:
Application-specific positioning determines whether brands compete on veterinary credibility, performance metrics, or general wellness claims.
- Weight Management:High-protein, low-carbohydrate formulations leverage satiety signaling and lean mass preservation, with veterinary channel distribution in the United States bypassing price competition in mass retail.
- Muscle Gain:Elevated branched-chain amino acid profiles target working dogs, athletic breeds, and post-surgical recovery cases through specialty retailer and breeder network channels.
- Energy Boost:Moderate protein elevation with fat optimization serves high-activity companion dogs in single-pet urban households.
- Overall Health:General wellness positioning without specific performance claims captures price-sensitive buyers through mass-market retail placement.
Weight management retains volume leadership; muscle gain commands the steepest price premiums per kilogram.
Packaging Type:
Volume and margin dynamics diverge sharply between logistics-optimized formats and convenience-positioned single-serve alternatives.
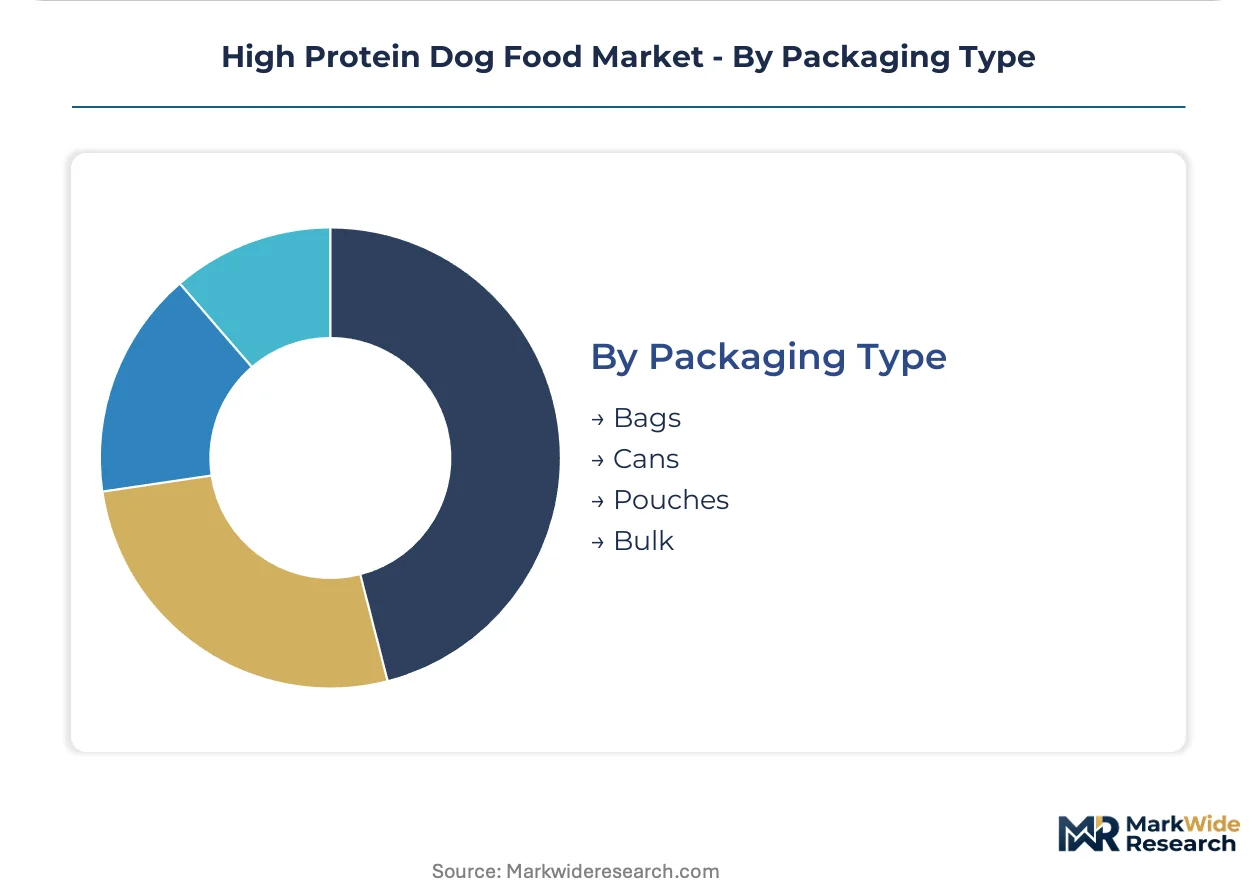
- Bags:Multi-layer laminate and paper-based flexible packaging dominate dry food distribution, with extended shelf stability enabling warehouse club and e-commerce bulk purchasing in the United States.
- Pouches:Retort and aseptic fill technologies enable single-serve wet food portions that displace can formats in urban households prioritizing refrigerator space and portion control.
- Cans:Traditional steel and aluminum containers retain wet food volume through veterinary and mass retail channels despite material cost volatility.
- Bulk:Refill and unpackaged formats concentrate in commercial kennel and breeder supply channels with minimal retail penetration.
Bags retain volume leadership; pouches are gaining share fastest through subscription channel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States high-protein dog food exports flow primarily to Canadian and Mexican markets under USMCA tariff provisions, with European Union member states representing the fastest-growing destination corridor for premium freeze-dried formats.
United States
Metropolitan households in Austin, Seattle, and Denver drive subscription-format fresh protein adoption through direct-to-consumer cold-chain logistics. FDA Center for Veterinary Medicine labeling enforcement under the Federal Food, Drug, and Cosmetic Act tightens nutrient adequacy claim standards. Pacific Northwest processing corridors in Oregon and Washington concentrate freeze-dried contract manufacturing capacity.
Germany
Urban pet owners in Berlin, Munich, and Hamburg accelerate spending on cold-press extruded kibble with elevated meat meal inclusion. EFSA novel food approvals for insect protein sources create regulatory precedent that domestic formulation labs exploit. Bavarian equipment manufacturers commercialize lower-temperature extrusion lines preserving lysine bioavailability.
United Kingdom
London and Greater Manchester households concentrate demand for veterinary-channel therapeutic high-protein diets targeting weight management cases. FSA guidance on raw pet food sale restrictions shapes retail distribution strategies. Southeast England logistics clusters enable sub-48-hour refrigerated subscription delivery to secondary cities.
France
Île-de-France and Auvergne-Rhône-Alpes regions exhibit strong demand for Marine Stewardship Council-certified fish protein formulations. ANSM oversight of veterinary feed supplements intersects with EU pet food labeling regulations. Lyon-based specialty retailers command shelf-space premiums for whole-prey ingredient ratio positioning.
Japan
Tokyo and Osaka metropolitan areas concentrate ownership of small-breed dogs requiring palatability-optimized high-protein wet food. METI standards for pet food quality labeling create compliance thresholds for imported formulations. Kansai region distribution networks facilitate cold-chain freshness guarantees for premium raw formats.
High Protein Dog Food Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational consumer packaged goods conglomerates with veterinary science credibility, mid-scale specialists in whole-prey and freeze-dried formats, and emerging insect-protein formulation labs awaiting regulatory clarity. Strategic archetypes include scale-driven portfolio standardizers, bioavailability-maximizing premium positioning specialists, and direct-to-consumer subscription operators. Dominant competitive moves encompass cold-press processing technology licensing and backward integration into rendered protein supply.
Within the multinational tier, Mars Petcare Inc. and Nestlé Purina PetCare exemplify scale-driven portfolio diversification across mass-market and veterinary channels. Orijen occupies a position within the premium specialist archetype, anchoring whole-prey ingredient ratio positioning in specialty retail. These three entities represent the dominant competitive anchors shaping formulation investment patterns and shelf-space negotiation dynamics across North American and European markets.
| Leading Market Players |
|---|
| Mars Petcare Inc. |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| The J.M. Smucker Company |
| General Mills Inc. |
| Diamond Pet Foods |
| Orijen |
| Stella & Chewy's |
| Wellness Pet LLC |
| Others |
Supply & Pricing Matrix
Undercapacity in Pacific Northwest freeze-dried processing corridors tightens protein meal spot markets, pushing contract manufacturers toward premium pricing while mass-market brands exploit cold-press scale economics to compress mid-tier price bands.
Pricing Analysis
Cold-press extrusion equipment generation gaps separate pricing tiers: prior-generation thermal processing anchors economy kibble, current-generation lower-temperature lines command mid-tier positioning, and next-generation nutrient-retention systems target premium parity with freeze-dried formats. Three-tier pricing structure across premium, standard, and economy levels reflects protein density thresholds and certification grades. Cost compression in standard-tier extruded kibble is intensifying because European equipment manufacturers commercialized lysine-preserving lines. Price-sensitive mass-market retail buyers in warehouse club channels contrast with least-sensitive subscription-format fresh protein subscribers in metropolitan corridors.
Supply Chain Analysis
USDA FSIS edible-grade facility requirements function as de facto export controls limiting cross-border flows of human-grade labeled products. Protein meal supply concentrates in United States rendering corridors, German equipment manufacturing clusters, and Thai fish meal processing hubs. Raw material dependencies include chicken meal, fish meal, and emerging black soldier fly larvae. Single-source vulnerability clusters in Pacific Northwest freeze-dried contract manufacturing. Distribution runs through mass retail, veterinary clinics, and direct-to-consumer cold-chain subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high protein dog food market represents a service-attach opportunity as veterinary nutritionist consultations bundled with auto-ship subscriptions expand faster than standalone product sales.
For Market Incumbents: Harden cold-chain logistics density in secondary metropolitan corridors to defend against subscription-format entrants. Secure backward integration into rendered protein supply to buffer against chicken meal price volatility. Invest in AAFCO nutritional adequacy certification to maintain shelf-space negotiation leverage against emerging insect-protein specialists. For New Entrants and Emerging Players: Pursue white-space positioning in state jurisdictions with permissive raw-food retail frameworks, particularly Texas and Florida metropolitan expansion zones. Target underpenetrated veterinary channel therapeutic diets for renal and weight management cases. Deploy direct-to-consumer cold-chain freshness guarantees as primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cold-press extrusion equipment manufacturing as German and Italian producers scale commercial lines. Long-term viability favors brands with captive supply agreements and subscription retention infrastructure. Acquisition target archetype: mid-scale specialists with whole-prey ingredient credibility and veterinary channel relationships. Signal to watch: FDA GRAS determinations for black soldier fly meal inclusion rates above 25%.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Processing Scale-Up | Equipment commercialization in Germany and Italy narrows nutrient-retention gaps with freeze-dried alternatives. |
| Veterinary Channel Integration | Prescription therapeutic diets bypass price competition through AAFCO nutritional adequacy claims. |
| Insect Protein Regulatory Pathway | EFSA novel food approvals and FDA GRAS channels open black soldier fly meal for complete formulations. |
| Direct-to-Consumer Cold Chain | Refrigerated subscription logistics reach Texas and Florida secondary cities with sub-48-hour guarantees. |
| Backward Integration into Rendered Supply | Captive protein meal sourcing buffers against livestock feed grain cost volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine guidance documents, AAFCO model regulations, USDA Agricultural Marketing Service certification pathways, and trade customs data. Interviews conducted with pet food formulation chemists, veterinary nutritionists, specialty retail category buyers, contract manufacturing procurement leads, and cold-chain logistics operators. Secondary validation sources include SEC filings of publicly traded pet food conglomerates, state agriculture department raw-food sale regulations, and equipment manufacturer technical disclosures. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Forecast inputs span protein concentration tiers, processing technology generations, ingredient source categories, functionality positioning, and packaging format adoption curves across the projection horizon. Segmentation dimensions modeled include product type, ingredient source, functionality application, and packaging format through regional regulatory clusters. CAGRs derive from trend extrapolation of protein threshold claims and technology adoption S-curves. Industry-specific inputs incorporate AAFCO model bill adoption timelines and cold-chain logistics density expansion.
Sensitivities concentrate around FDA enforcement actions on human-grade labeling claims, state-level raw-food retail restriction expansions, and animal protein input price volatility. Forecasts reflect documented assumptions regarding regulatory pathway timelines and equipment commercialization schedules. Material shifts in insect protein GRAS determinations or freeze-dried capacity concentration events would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
South America Dog Food Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Pet Calming Products Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Dog Collars Market
Pet Care Products
Pet Gadgets Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
Asia-Pacific Pet Clothing Market