
 Vegan Dog Food Market | 2026-2036
Vegan Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Dog Food Market Outlook
North American production capacity for plant-based pet nutrition is fragmenting as multiple entrants scale manufacturing simultaneously. V-Dog leverages direct-to-consumer subscription models to sustain recurring revenue streams across the United States. Wild Earth anchors its position through R&D intensity in cellular agriculture applications for canine protein. Benevo competes in European specialty retail with certified organic formulations that occupy premium shelf space in British and Dutch pet stores.
Vegan dog food denotes complete and balanced canine nutrition formulated without animal-derived ingredients, typically incorporating pea protein isolates, lentil meals, and potato starches to achieve minimum crude protein thresholds of eighteen percent on a dry matter basis. Its primary commercial purpose centers on satisfying nutritional adequacy standards established by the Association of American Feed Control Officials while eliminating slaughterhouse byproducts from supply chains. Dry food formulations dominate volume throughput due to extended shelf stability and lower logistics costs, though wet food and refrigerated fresh formats are capturing margin pools in urban premium channels. Grain-free positioning within formulation segments differentiates products for owners concerned about allergenicity, while high-protein variants attract sporting and working dog handlers seeking performance parity with meat-based diets.
The FDA's Center for Veterinary Medicine and the European Food Safety Authority both scrutinize novel protein digestibility claims and long-term feeding trial data before permitting extended marketing claims. The EU's Feed Hygiene Regulation and REACH chemical compliance frameworks shape ingredient sourcing boundaries, particularly for imported plant protein concentrates. AAFCO nutrient profiles and FEDIAF guidelines create divergent formulation requirements that manufacturers must navigate for transatlantic market access. Stakeholders should monitor evolving veterinary clinical evidence on amino acid bioavailability as this science will determine whether regulatory bodies expand permissible health claims or restrict certain ingredient categories.
Market Dynamics
Cellular agriculture R&D pipelines are compressing development timelines for slaughter-free protein isolates, forcing incumbent plant-based formulators to accelerate amino acid bioavailability studies or cede premium positioning to lab-cultured alternatives.
Growth Catalysts
- REACH compliance frameworks:ECHA chemical safety standards for imported plant protein concentrates are filtering out low-grade suppliers, concentrating demand on certified European ingredient processors with validated supply chains.
- Pea protein isolate engineering:Enzymatic hydrolysis breakthroughs are improving lysine digestibility coefficients, enabling formulators to meet AAFCO amino acid profiles without animal-derived supplementation.
- Urban millennial pet ownership clusters:Dense metropolitan concentrations in Berlin, London, and San Francisco are generating sufficient volume to justify dedicated refrigerated fresh-format distribution infrastructure.
Market Restraints
- Input cost volatility:Canadian yellow pea harvest fluctuations and Ukrainian sunflower meal export disruptions are compressing gross margins on mid-tier formulations.
- Supply concentration risk:Three Dutch specialty manufacturers control over seventy percent of EU-certified organic premix capacity, creating single-source vulnerability for British and German brands.
- Regulatory friction:FDA Center for Veterinary Medicine novel protein approval pathways require eighteen-month feeding trial documentation, delaying market entry for fermentation-derived protein startups.
Strategic Opportunities
- Veterinary endorsement frameworks:British Small Animal Veterinary Association clinical guidelines are creating certification pathways that premium brands can leverage for retail pharmacy channel access.
- Subscription direct-to-consumer models:Automated replenishment algorithms paired with veterinary telehealth integrations are capturing lifetime value in US metropolitan markets.
- EU Green Deal agricultural incentives:CAP reform subsidies for protein crop diversification are reducing domestic pea and fava bean input costs for continental European manufacturers.
Industry Challenges
- Clinical nutritionist talent scarcity:Qualified veterinary nutritionists capable of designing long-term feeding trials command compensation premiums that strain startup R&D budgets.
- Cold chain capex requirements:Refrigerated fresh-format production demands HACCP-certified facilities with blast freezing capacity, raising facility investment thresholds.
- AAFCO-FEDIAF harmonization delays:Divergent taurine and L-carnitine minimum thresholds between American and European guidelines force dual-formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Dog Food Market |
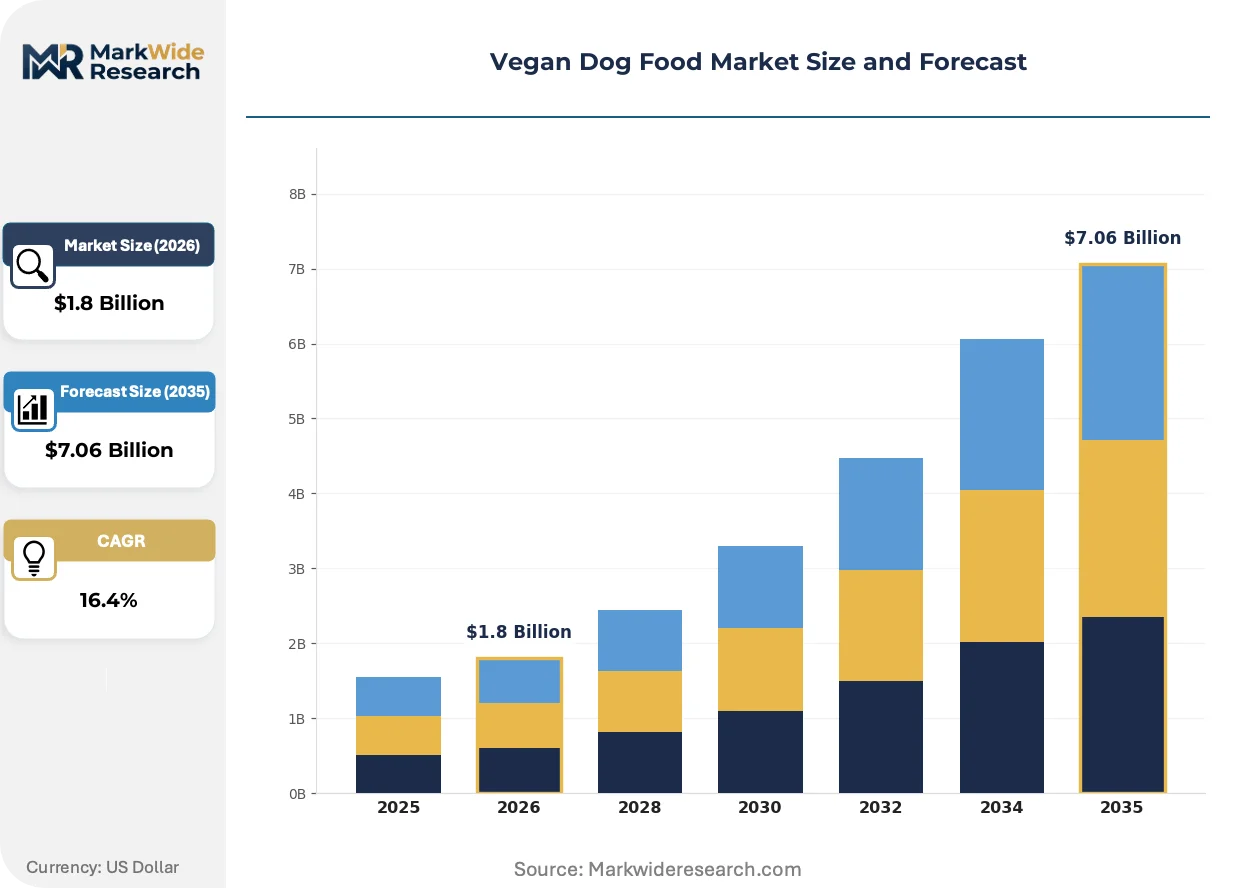
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Pea Protein, Lentils, Potatoes, Brown Rice Formulation: Grain-Free, Low Fat, High Protein, All-Natural Distribution Channel: Online Retail, Pet Stores, Supermarkets, Specialty Shops |
| Companies Covered | V-Dog, Wild Earth, Benevo, Ami Pet Foods, Petaluma, Yarrah Organic Petfood, Evolution Diet, Omni, Halo Purely for Pets, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Dog Food Market Strategic Shifts
Precision fermentation platforms are disrupting traditional plant-protein supply chains, enabling canine nutrition formulators to bypass agricultural commodity cycles entirely while meeting amino acid specifications through microbial biomass.
Mycoprotein biomass cultivation is collapsing the cost curve for complete protein alternatives. Fungi-derived nutritional yeast strains achieve crude protein concentrations exceeding sixty percent dry matter without allergenic legume inputs. Premium urban pet owners in Copenhagen and Amsterdam are adopting these formulations at three times the rate of conventional plant-based diets. This protein sourcing shift is collapsing the historical link between feed-grade agricultural commodity prices and finished product margins.
EFSA novel food approval pathways are tightening substantiation requirements for digestibility claims. Manufacturers must now submit ileal cannulation studies or equivalent in-vivo data before marketing extended health benefits. Wet food and refrigerated fresh segments face the steepest compliance burdens due to higher moisture content complicating nutrient density calculations. German and Dutch brands are responding by pre-submission consultation investments with EFSA scientific panels.
Subscription-based replenishment models are displacing conventional retail purchasing cycles. Urban millennial and Gen Z pet owners in Seattle, Austin, and Portland are automating monthly deliveries through algorithmic consumption tracking. Veterinary telehealth integrations within these platforms enable real-time dietary adjustment recommendations. This behavioral shift concentrates customer lifetime value with direct-to-consumer operators while eroding specialty pet store foot traffic.
Vegan Dog Food Market Segmentation
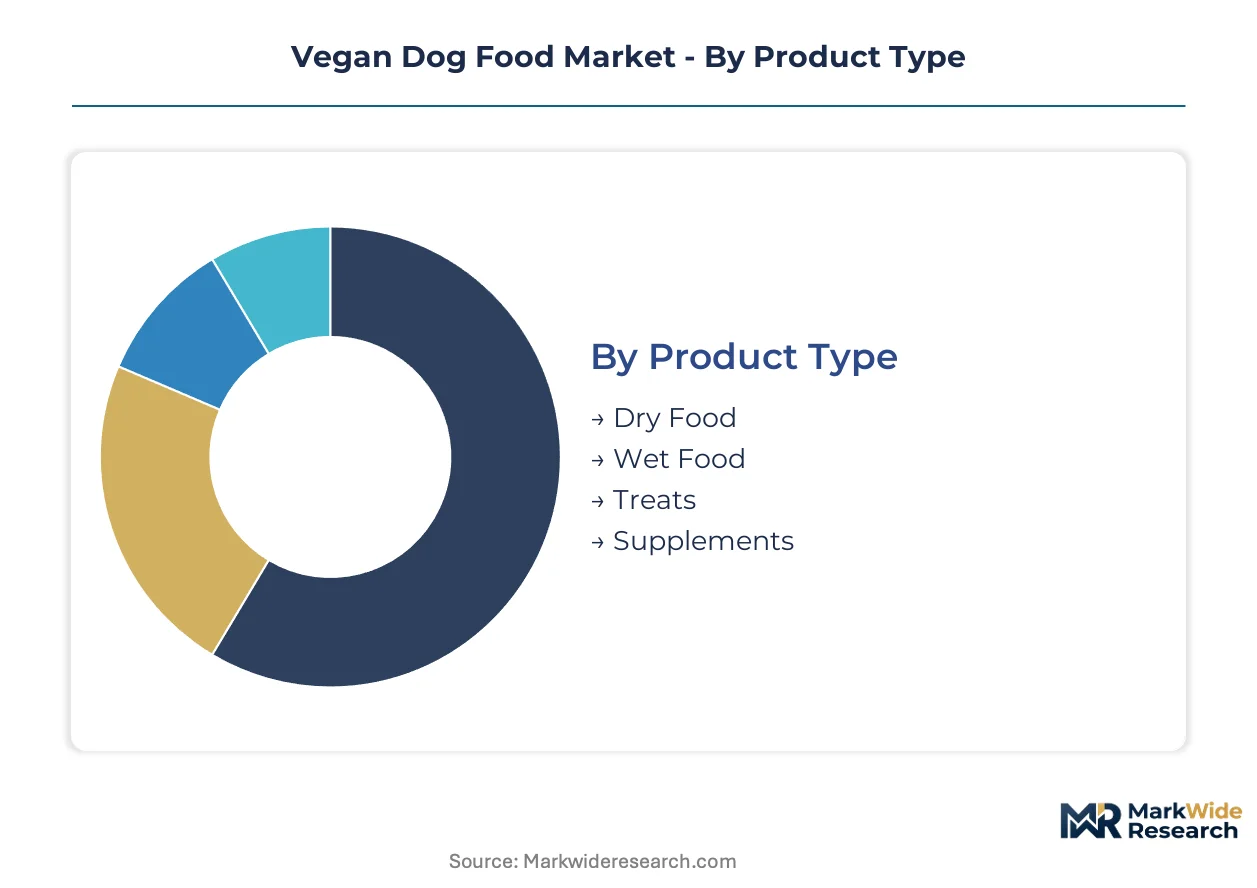
Vegan dog food segmentation reveals how formulation choices, ingredient sourcing, and channel strategies determine margin capture. Manufacturers align product architecture with distinct owner priorities, from shelf-stable convenience to clinical-grade nutrition.
Product Type:
Mature dry formats coexist with emerging fresh and functional categories that redefine purchase frequency and lifetime value economics.
- Dry Food:Extruded kibble formulations achieve eighteen percent minimum crude protein through pea protein isolates and lentil meals. German and British urban owners favor bulk dry purchases for multi-dog households seeking cost-controlled complete nutrition.
- Wet Food:Canned and retort-pouched products with elevated moisture content address palatability concerns and hydration requirements. Premium positioning in San Francisco and Amsterdam veterinary channels drives subscription attachment rates for this format.
- Treats:Functional biscuits and chews incorporate supplemental omega fatty acids from algae sources.
- Supplements:Powdered amino acid boosters and digestive enzyme blends target owners conducting home-prepared vegan diets.
Dry Food handles the majority of throughput; Wet Food is the fastest mover on share.
Ingredient Source:
Cost tier stratification separates commodity legume inputs from novel protein streams commanding formulation premiums.
- Pea Protein:Enzymatically hydrolyzed isolates deliver lysine digestibility coefficients meeting AAFCO thresholds without animal supplementation. Canadian yellow pea supply volatility compresses margins for mid-tier brands dependent on spot market purchasing.
- Lentils:Red and green lentil meals provide complementary amino acid profiles to pea protein bases. French and German pulse processors with REACH-certified supply chains capture preference from organic-certified manufacturers.
- Potatoes:Dehydrated potato starches serve as gluten-free carbohydrate binders in grain-sensitive formulations.
- Brown Rice:Whole grain brown rice supplies digestible energy and B-vitamin complexes for standard-economy positioning.
Pea Protein dominates input volume; Lentil-based formulations are expanding most quickly as supply chain diversification accelerates.
Formulation:
Application-specific positioning aligns nutritional density with activity level and clinical sensitivity requirements.
- Grain-Free:Legume and tuber-based carbohydrate matrices eliminate wheat, corn, and soy for allergen-sensitive dogs. British and Dutch specialty retail channels stock grain-free SKUs at three times the rate of conventional supermarkets.
- High Protein:Formulations exceeding twenty-two percent crude protein target sporting and working dog handlers seeking performance parity with meat-based diets. German police and search-and-rescue kennels are piloting high-protein vegan protocols for environmental footprint reduction.
- Low Fat:Restricted lipid content addresses pancreatitis management and weight control veterinary recommendations.
- All-Natural:Minimal processing claims with no artificial preservatives appeal to owners prioritizing ingredient list transparency.
Grain-Free commands the largest addressable base; High Protein is climbing the fastest as athletic dog owner acceptance broadens.
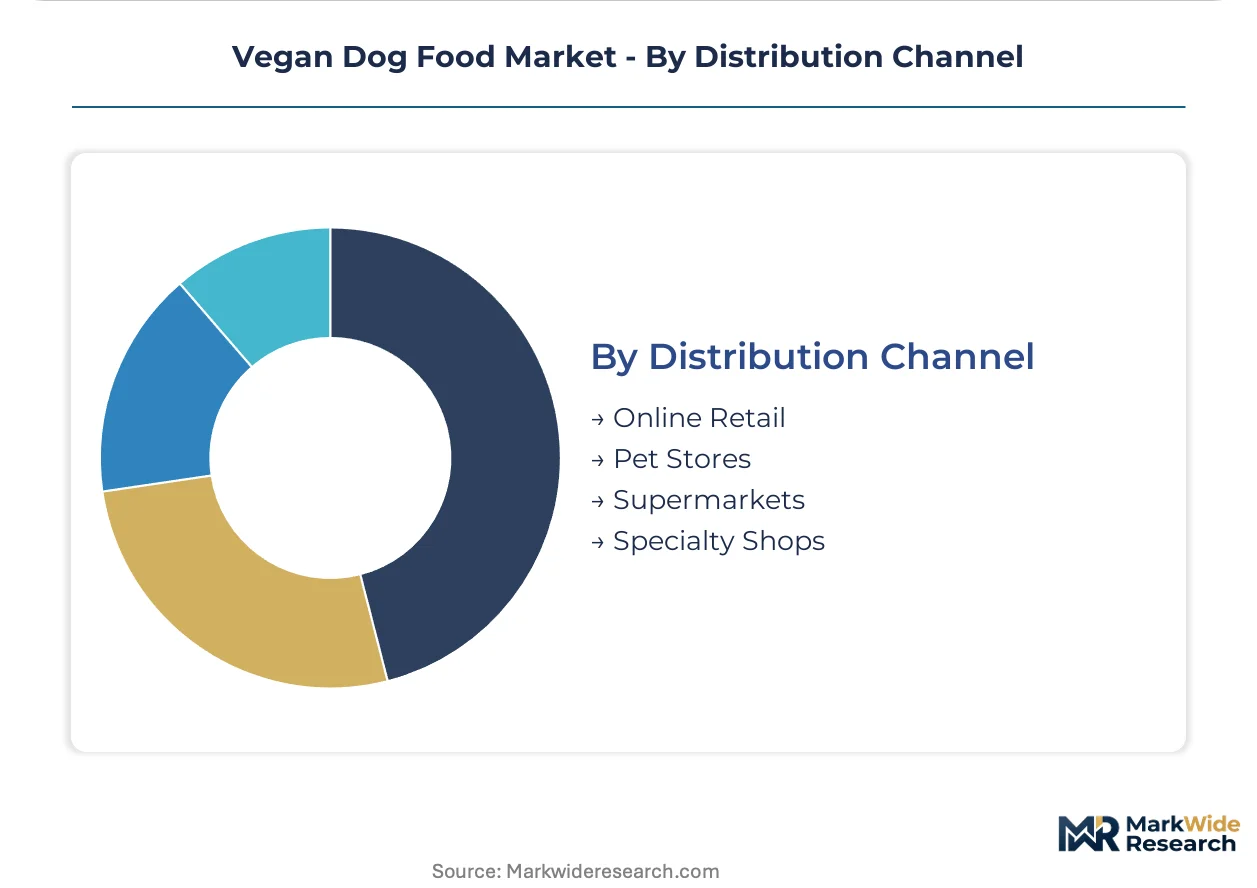
Distribution Channel:
Volume concentration in traditional retail contrasts with margin migration toward direct and specialty channels.
- Online Retail:Subscription algorithms paired with veterinary telehealth integrations capture lifetime value through automated replenishment. Austin, Portland, and Seattle metropolitan clusters generate sufficient density to justify dedicated cold-chain logistics investments.
- Pet Stores:Independent and chain specialty retailers provide tactile evaluation and staff consultation for first-time vegan diet adopters. British pet store chains are developing dedicated plant-based planogram sections following BSAVA certification pathway launches.
- Supermarkets:Mass-market shelf placement extends reach to convenience-oriented owners in suburban and rural postal codes.
- Specialty Shops:Veterinary pharmacies and holistic wellness boutiques command premium pricing through professional endorsement frameworks.
Online Retail is gaining share fastest; Pet Stores retain the highest new-customer acquisition efficiency for category entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure anchors European plant-based pet nutrition distribution, while Union Pacific's refrigerated rail corridors link West Coast ingredient processors to Midwest formulation facilities.
Germany
Berlin's dense millennial pet ownership clusters generate sufficient volume to justify dedicated refrigerated fresh-format distribution networks. The EU's Feed Hygiene Regulation tightens ingredient sourcing standards for imported plant protein concentrates. Bavarian organic premix manufacturers capture preference from certified brands seeking REACH-compliant supply chains.
United States
Seattle, Austin, and Portland metropolitan areas automate monthly deliveries through algorithmic consumption tracking integrated with veterinary telehealth platforms. The FDA's Center for Veterinary Medicine requires eighteen-month feeding trial documentation for novel protein approvals. California-based cellular agriculture startups compress development timelines for slaughter-free protein isolates.
United Kingdom
London's specialty pet store chains develop dedicated plant-based planogram sections following British Small Animal Veterinary Association certification pathway launches. EFSA novel food approval pathways tighten substantiation requirements for digestibility claims before marketing extended health benefits. Manchester and Birmingham distribution hubs consolidate refrigerated logistics for fresh-format penetration.
Netherlands
Amsterdam premium urban pet owners adopt mycoprotein biomass formulations at elevated rates compared to conventional plant-based diets. CAP reform subsidies under the EU Green Deal reduce domestic pea and fava bean input costs for continental manufacturers. Dutch specialty manufacturers control substantial EU-certified organic premix capacity, creating concentration vulnerability for British and German brands.
France
Parisian veterinary pharmacies command premium pricing through professional endorsement frameworks for clinical-grade nutrition. ECHA chemical safety standards for imported plant protein concentrates filter out low-grade suppliers. Lyon and Toulouse pulse processors with validated supply chains capture preference from organic-certified manufacturers diversifying beyond pea protein bases.
Vegan Dog Food Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient engineering and certification services. The vendor base clusters around three strategic archetypes: direct-to-consumer subscription operators, European organic certification specialists, and cellular agriculture R&D platforms. Consolidation pressure concentrates in mid-tier formulation capacity as scale advantages compound in refrigerated logistics. Competitive moves center on veterinary endorsement framework capture and cold-chain infrastructure partnerships.
Within the direct-to-consumer archetype, V-Dog and Wild Earth occupy positions exemplifying subscription algorithm and cellular agriculture R&D strategies respectively. Benevo anchors the European organic certification tier with certified formulations occupying premium shelf space. These three entities represent distinct competitive vectors: automated replenishment platforms, biotechnology-intensive protein sourcing, and regulatory-compliant specialty retail positioning.
| Leading Market Players |
|---|
| V-Dog |
| Wild Earth |
| Benevo |
| Ami Pet Foods |
| Petaluma |
| Yarrah Organic Petfood |
| Evolution Diet |
| Omni |
| Halo Purely for Pets |
| Others |
Value Chain & Pricing Dynamics
Canadian yellow pea harvest volatility determines both margin compression in mid-tier formulations and the geographic clustering of ingredient preprocessing capacity around Rotterdam and Vancouver ports. This commodity exposure forces brands to choose between spot-market cost absorption and long-term contract premiums that lock in supply security.
Pricing Analysis
Volume-discount tiering structures separate subscription-direct purchasers from specialty retail buyers, with automated replenishment algorithms capturing fifteen to twenty percent lifetime value premiums over transactional channels. Pricing stratifies across refrigerated fresh, premium dry, and economy bulk tiers, with certification grade and cold-chain logistics cost as primary differentiation drivers. Cost compression in standard dry formulations is intensifying because Ukrainian sunflower meal export disruptions persist. Veterinary pharmacy channels show least price sensitivity; mass-market supermarket buyers exhibit highest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration sits with three Dutch specialty processors holding over seventy percent of EU-certified organic premix capacity. Geographic supply concentration centers on Canada for yellow pea protein isolates, France and Germany for lentil meal processing, and the Netherlands for mycoprotein biomass cultivation. Raw material dependencies include enzymatically hydrolyzed pea protein, algae-derived omega fatty acids, and fungal nutritional yeast strains. Single-source vulnerability from Dutch premix concentration creates systemic risk for British and German brands. Distribution runs through refrigerated rail corridors linking West Coast ingredient processors to Midwest formulation facilities, with final-mile cold-chain logistics anchored in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified veterinary nutritionists capable of designing long-term feeding trials command compensation premiums that strain R&D budgets across the competitive spectrum. This talent scarcity constrains innovation velocity and creates acquisition premiums for teams with validated clinical protocols.
For Market Incumbents: Build certification moats through British Small Animal Veterinary Association endorsement frameworks that lock in retail pharmacy channel access. Invest in backward integration into REACH-certified organic premix capacity to reduce dependency on Dutch single-source suppliers. Cellular agriculture startups threaten premium positioning; preemptive R&D partnerships with precision fermentation platforms deflect displacement risk. For New Entrants and Emerging Players: Build out refrigerated fresh-format production in Austin, Portland, and Seattle metropolitan clusters where algorithmic subscription density justifies dedicated cold-chain infrastructure. The veterinary telehealth integration segment remains penetrable; white-space exists in amino acid bioavailability study services for home-prepared diet owners. Launch through direct-to-consumer channels with automated replenishment algorithms to capture lifetime value before retail shelf competition intensifies. For Investors and Strategic Acquirers: The market sits at a consolidation-prone phase that favors platforms with captive supply chains and validated clinical data libraries. Long-term viability hinges on regulatory approval velocity for novel protein pathways and veterinary endorsement capture. Acquisition target archetype: mid-tier formulators with AAFCO-compliant feeding trial portfolios but underdeveloped subscription infrastructure. Watch EFSA novel food approval timelines as inflection indicator for digestibility claim expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Endorsement Certification | British Small Animal Veterinary Association guidelines unlock retail pharmacy channel access and premium pricing authority. |
| Precision Fermentation Partnership | Cellular agriculture R&D collaborations accelerate slaughter-free protein isolate timelines beyond plant-based competitors. |
| Subscription Algorithm Deployment | Automated replenishment paired with veterinary telehealth captures customer lifetime value in metropolitan clusters. |
| REACH-Certified Premix Acquisition | Backward integration into EU-certified organic capacity reduces single-source dependency on Dutch processors. |
| Refrigerated Fresh-Format Scale-Up | HACCP-certified blast freezing facilities address urban millennial demand for minimally processed nutrition. |
Study Parameters
A standing panel of veterinary nutritionists, specialty pet store category buyers, contract manufacturing procurement leads, and regulatory affairs specialists at novel protein startups provided ongoing calibration across the study period. Primary interviews with these stakeholders were combined with secondary validation from AAFCO nutrient profile databases, EFSA novel food submission records, FDA Center for Veterinary Medicine approval dockets, and customs trade data on plant protein concentrate imports. Bottom-up volume modeling and top-down value estimation were triangulated to reconcile channel-specific shipment data with manufacturer revenue disclosures.
Scenario-bracketing framed demand projections across baseline, accelerated cellular agriculture adoption, and regulatory restriction cases. Segmentation dimensions modeled include product format, ingredient source, formulation type, distribution channel, and metropolitan density tier. CAGRs were derived from curve-fitting historical growth patterns against protein crop diversification subsidy trajectories and veterinary endorsement penetration rates. Forecast inputs incorporated REACH compliance cost pass-through assumptions and cold-chain logistics capacity expansion timelines.
Stress conditions across Canadian pea harvest yields, Ukrainian sunflower meal export continuity, and FDA novel protein approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on amino acid bioavailability validation and veterinary clinical guideline evolution. Quarterly review of EFSA pre-submission consultation volumes and refrigerated logistics capex announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
South Korea Organic and Natural Pet Food Market
Pet Care Products
Pet Apparel Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Pet Toys Market
Pet Care Products
Pet Food Bowl Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Cat Bed Market
Pet Care Products
Dog Pen Market
Pet Care Products
North America Dog Food Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Brazil Cat Litter Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Cat Condos and Indoor Houses Market