
 Vegan Cat Food Market | 2026-2036
Vegan Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Cat Food Market Outlook
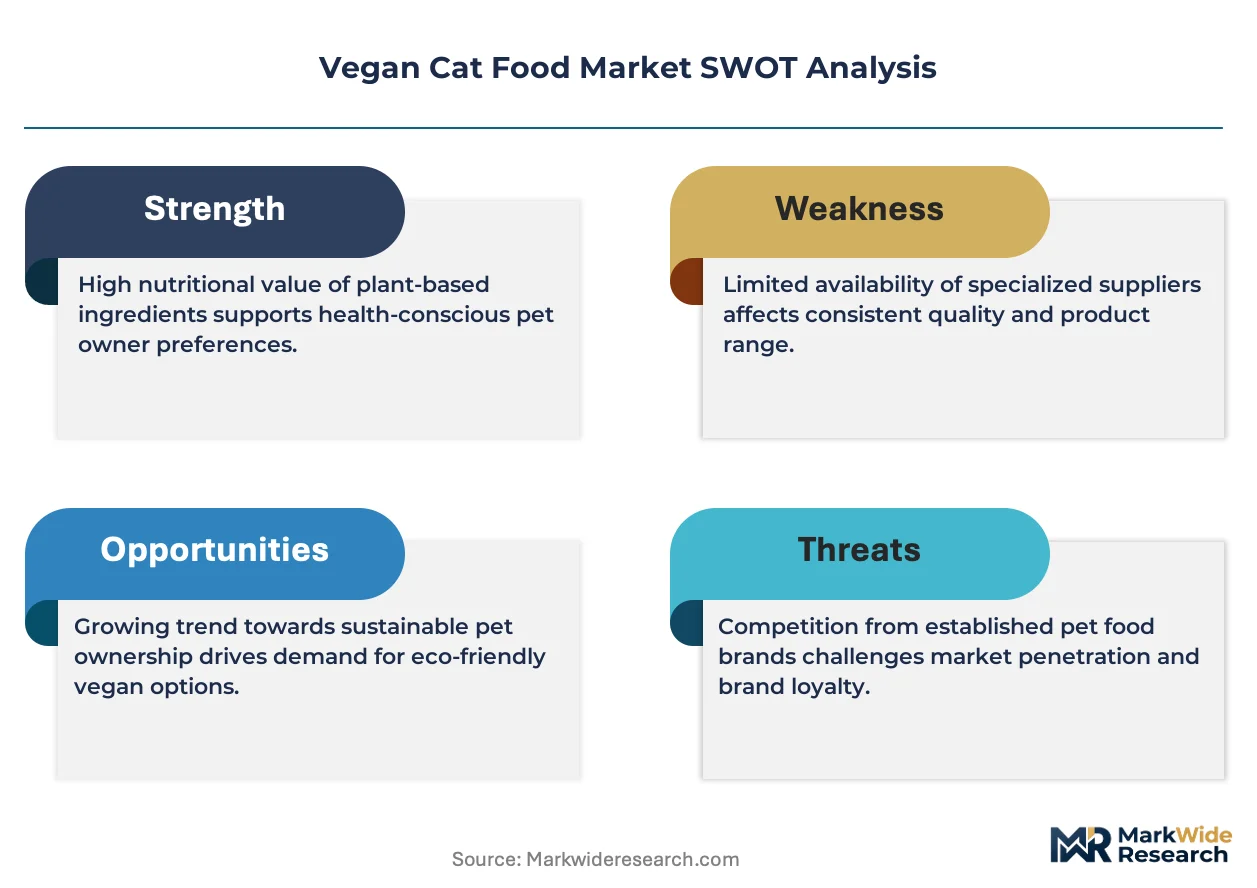
Capital-intensity divergence between in-house extrusion capabilities and outsourced co-manufacturing is rotating competitive advantage toward vertically integrated producers. Benevo leverages its British manufacturing base to control formulation quality from raw ingredient to finished kibble. Wild Earth sustains a technology-forward profile through precision fermentation research for alternative proteins. Amì Planet Srl anchors European distribution with Italian production and direct-to-consumer channels across the continent.
Vegan cat food refers to nutritionally complete feline diets formulated without animal-derived ingredients, typically achieving protein targets through pea, soy, or fungal protein concentrates balanced with synthetic taurine and arachidonic acid to meet obligate carnivore metabolic requirements. Dry food dominates volume due to shelf stability and lower logistics costs, though wet food commands premium pricing from owners seeking higher moisture content for urinary tract health. The grain-free ingredient segment differentiates through allergen positioning, while online retail channels capture the fastest growth by enabling subscription models and direct consumer education on plant-based nutrition adequacy.
The FDA's Center for Veterinary Medicine enforces nutritional adequacy claims under AAFCO standards, while the EU's FEDIAF guidelines mandate specific amino acid profiles that vegan formulations must demonstrate through feeding trials. REACH compliance affects ingredient sourcing for European manufacturers, and the EU Green Deal's agricultural emissions targets indirectly incentivize plant-based feed innovation. Stakeholders must monitor evolving veterinary consensus on long-term feline health outcomes from plant-exclusive diets, as regulatory frameworks and consumer trust hinge on emerging clinical evidence rather than formulation claims alone.
Market Dynamics
AAFCO nutritional adequacy standards and EU FEDIAF amino acid mandates are compressing formulation freedom while precision fermentation research unlocks novel protein sourcing pathways for plant-based feline nutrition.
Growth Catalysts
- Urban Millennial Pet Ownership:Concentrated demand in United States, Germany, and United Kingdom metropolitan clusters accelerates specialty retail channel development for alternative protein diets.
- EU Green Deal Agricultural Targets:Emissions reduction mandates for livestock farming indirectly incentivize plant-based feed innovation and research funding allocation.
- Precision Fermentation Scale-Up:Fungal protein production technologies achieve cost parity with conventional animal protein concentrates in pilot manufacturing facilities.
Market Restraints
- Synthetic Amino Acid Cost Volatility:Taurine and arachidonic acid supply chains remain tethered to petrochemical feedstock pricing and pharmaceutical-grade purification capacity constraints.
- Veterinary Consensus Uncertainty:Long-term clinical evidence gaps on obligate carnivore metabolic adaptation to plant-exclusive diets create consumer trust friction and regulatory scrutiny intensity.
- Co-Manufacturing Concentration Risk:Limited extrusion facilities capable of allergen-segregated vegan production runs create single-source dependencies for mid-tier brands.
Strategic Opportunities
- Subscription Direct-to-Consumer Channels:United States and United Kingdom urban markets enable recurring revenue models with embedded nutritional education content delivery.
- Wet Food Premium Positioning:Higher moisture formulations targeting urinary tract health concerns command price multiples over dry kibble in specialty veterinary channels.
- REACH-Compliant European Sourcing:Ingredient traceability standards create competitive moats for manufacturers with certified supply chain documentation systems.
Industry Challenges
- Feline Clinical Nutrition Expertise Scarcity:Veterinary specialists with plant-based diet research experience remain concentrated in academic institutions rather than commercial R&D functions.
- Feeding Trial Certification Timelines:AAFCO and FEDIAF protocol compliance requires 26-week minimum study durations that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Cat Food Market |
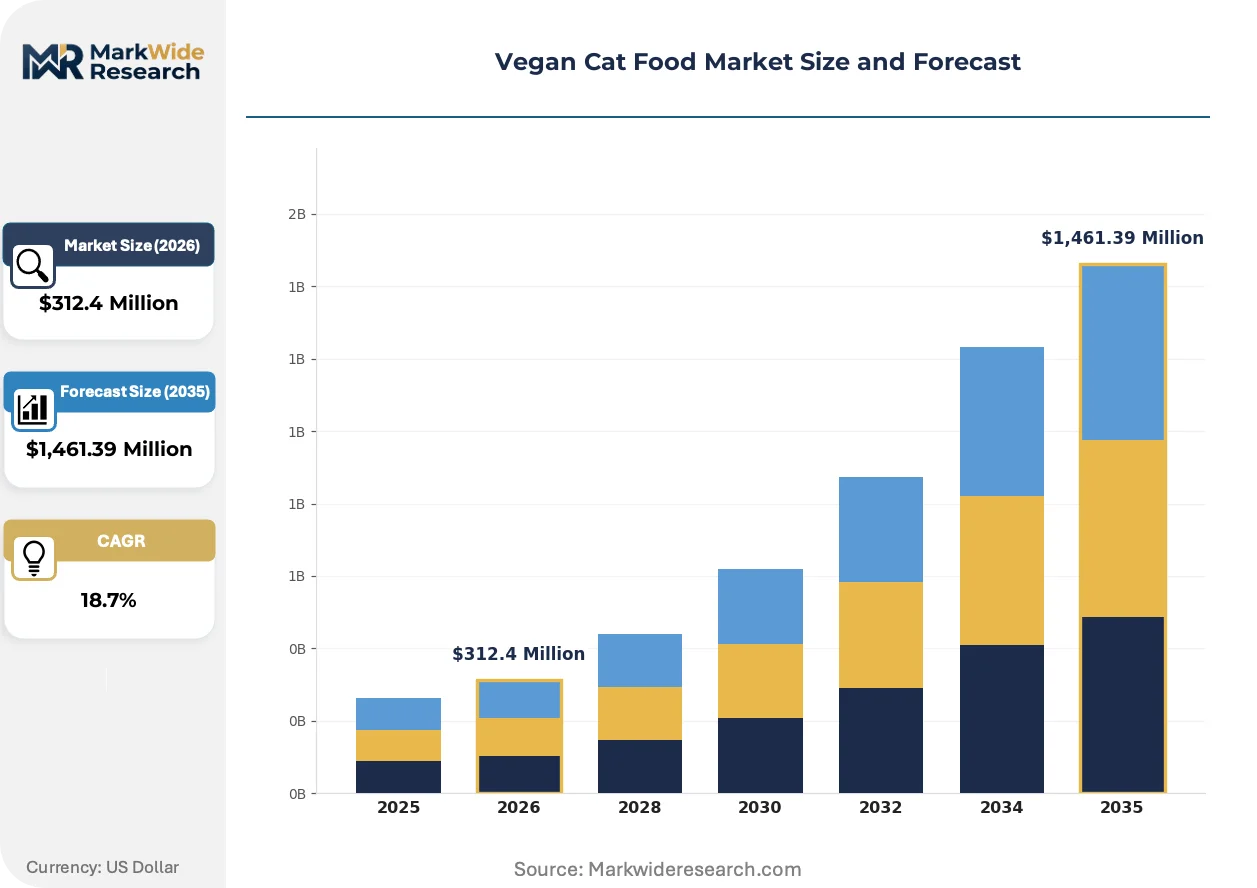
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Plant-Based, Grain-Free, Protein-Rich, Organic Packaging Type: Bags, Cans, Pouches, Bulk Distribution Channel: Online Retail, Pet Stores, Specialty Shops, Supermarkets |
| Companies Covered | Amì Planet Srl, Veggieanimals, VGRRR Pet Food Inc., Nature's HUG Pet Food Inc., Benevo, Wild Earth, Compassion Circle, Inc., Wysong, Vitaveg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Cat Food Market Strategic Shifts
Formulation science and distribution infrastructure are diverging toward divergent quality tiers while regulatory frameworks harden around nutritional substantiation requirements.
Fungal protein concentrate technology is bifurcating product positioning strategies. Precision fermentation-derived biomass achieves complete amino acid profiles without agricultural land use. Premium-positioned brands adopt these inputs for sustainability narrative differentiation. Cost-engineered formulations remain anchored to pea and soy isolates, compressing mid-market margin structures.
REACH chemical registration requirements are tightening ingredient sourcing transparency. European manufacturers must demonstrate full supply chain substance documentation for novel protein inputs. Wet food producers face heightened scrutiny on preservative systems and can-lining compatibility. German and United Kingdom importers are accelerating third-party audit investments to preempt enforcement actions.
Veterinary channel endorsement patterns are shifting toward evidence-demanding positioning. Specialty clinics in United States metropolitan markets now require peer-reviewed feeding study citations before shelf placement. Online subscription models bypass this gatekeeping through direct consumer education investments. United Kingdom and Germany digital-native brands capture this bypass opportunity with veterinary nutritionist content partnerships.
Vegan Cat Food Market Segmentation
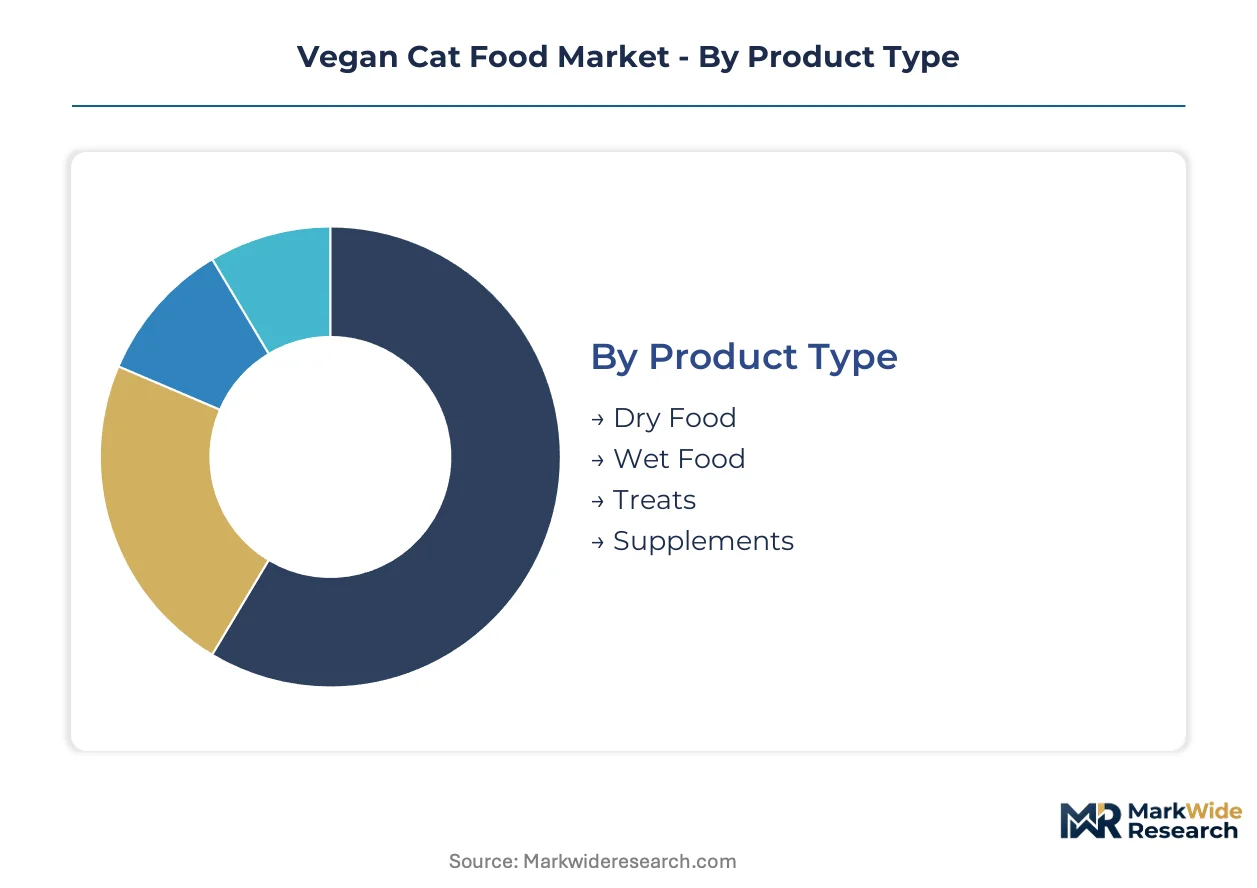
Segmentation in vegan cat food reveals how formulation choices, packaging economics, and channel access determine which consumer cohorts brands can profitably serve. Understanding these splits exposes where margin pools concentrate and where competitive positioning must adapt.
Product Type:
Higher moisture formulations command premium multiples due to veterinary endorsement and perceived urinary tract benefits, while dry formats dominate volume through logistics efficiency.
- Dry Food:Extruded kibble formulations achieve shelf stability through low moisture content and oxygen-barrier packaging. Demand concentrates in United States urban subscription channels where millennial owners prioritize convenience and automated replenishment.
- Wet Food:Canned or pouched formulations with 75-85% moisture content target feline hydration requirements through meat analog texture and palatability engineering. United Kingdom and Germany specialty veterinary clinics drive premium positioning through clinical endorsement requirements.
- Treats:Bite-sized functional rewards with limited caloric contribution, typically employing pea protein isolates and yeast extracts for umami flavor profiles.
- Supplements:Synthetic taurine, arachidonic acid, and vitamin premixes addressing nutritional gaps in homemade plant-based feeding regimens.
The dominant share belongs to Dry Food, while Wet Food is closing the gap fastest through veterinary channel penetration.
Ingredient Source:
Cost structures diverge sharply between commodity legume isolates and certified organic supply chains, with regulatory compliance adding documentation overhead across all tiers.
- Plant-Based:Pea, soy, lentil, and fava bean protein concentrates form the nutritional backbone, balanced with synthetic amino acids to meet obligate carnivore requirements. German manufacturers leveraging REACH-compliant supply chains capture margin premiums through traceability certification.
- Grain-Free:Formulations excluding wheat, corn, and rice target allergen-sensitive feline populations and owner perception of ancestral dietary alignment. United States specialty retailers position these SKUs adjacent to limited-ingredient veterinary diets.
- Protein-Rich:Elevated crude protein percentages exceeding 40% on a dry matter basis, achieved through protein concentrate fortification rather than fresh ingredient inclusion.
- Organic:Certified organic ingredient sourcing with prohibited synthetic pesticide residues and GMO exclusion, commanding 25-40% price premiums in United Kingdom and German urban markets.
Plant-Based formulations anchor volume, though Organic is expanding most quickly through sustainability-motivated purchasing in metropolitan clusters.
Packaging Type:
Unit economics and shelf-life requirements push brands toward formats that minimize per-gram distribution cost while preserving nutritional integrity.
- Bags:Multi-layer polymer or paper-based flexible packaging for dry kibble, enabling pallet-efficient logistics and retail display flexibility. United States co-manufacturing facilities favor this format for production line throughput.
- Cans:Metal containers with epoxy phenolic linings for wet food, requiring compatibility testing with acidic plant-based formulations to prevent corrosion and off-flavor migration.
- Pouches:Retortable flexible packaging gaining share in wet food for portion control and reduced material weight versus cans.
- Bulk:Large-format packaging for multi-cat households and commercial catteries, bypassing retail markup through direct distribution.
Bags retain the installed base, yet Pouches are gaining share fastest through sustainability messaging and material reduction claims.
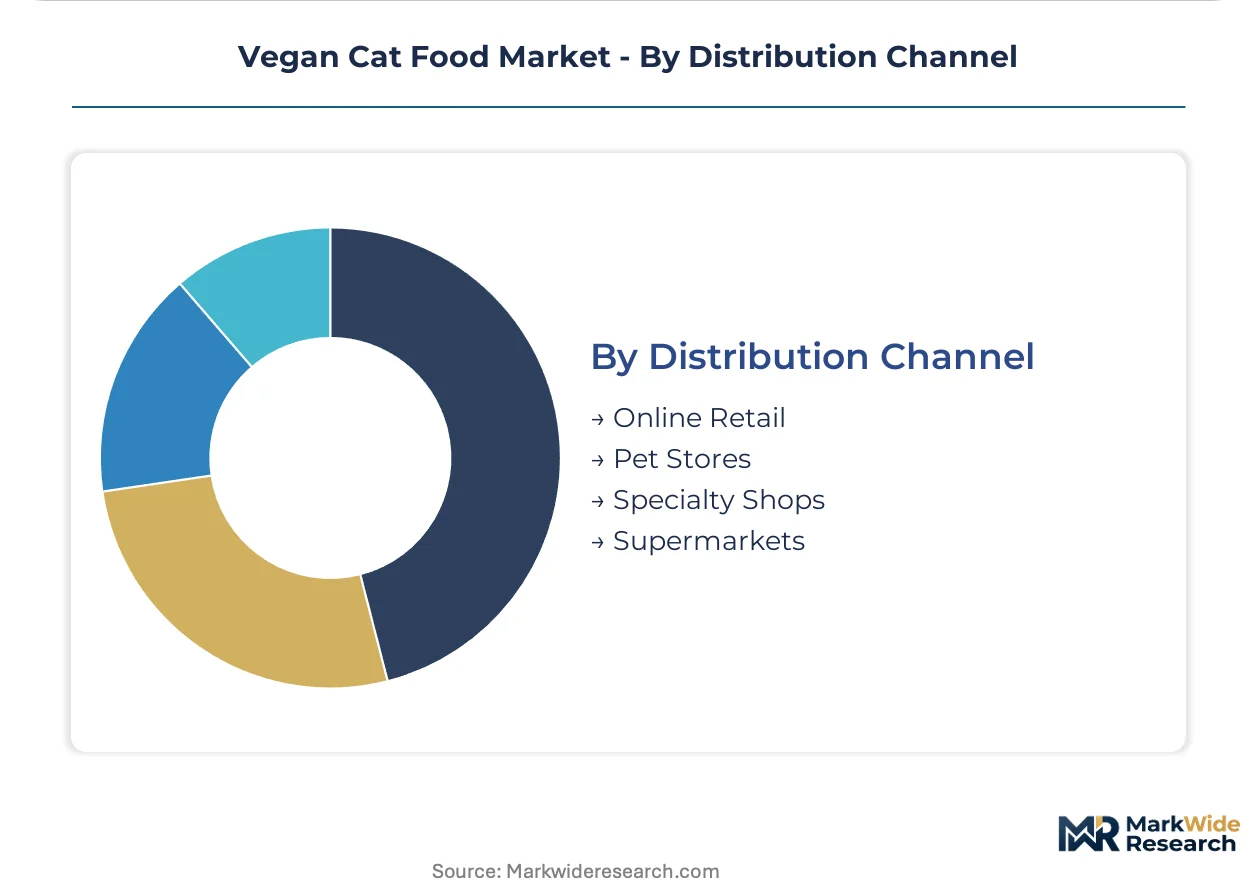
Distribution Channel:
Channel selection determines customer acquisition cost and educational burden, with digital-native brands bypassing traditional gatekeepers through content investment.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription models and nutritional education at scale. United States and United Kingdom urban markets show highest penetration among millennial and Gen Z cohorts.
- Pet Stores:Specialty retail chains with trained staff capable of explaining plant-based nutritional adequacy to skeptical owners. Germany's Fressnapf and United States Petco anchor this channel with dedicated alternative diet sections.
- Specialty Shops:Independent retailers focusing on natural and holistic pet nutrition, often requiring brand storytelling and local community engagement.
- Supermarkets:Mass retail placement demanding price competitiveness and packaging formats suited to high-velocity shelf turnover, with limited staff expertise for consumer education.
Online Retail commands the steepest expansion trajectory, while Pet Stores defend the highest-margin positioning through service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets where vegan cat food serves ethical lifestyle alignment versus those prioritizing clinical nutritional outcomes. Urban millennial density and specialty retail infrastructure determine adoption velocity more than absolute pet population.
United States
Subscription direct-to-consumer channels capture millennial and Gen Z owners in metropolitan clusters. The FDA's Center for Veterinary Medicine enforces AAFCO nutritional adequacy standards that compress formulation freedom. Los Angeles and New York anchor specialty retail development with dedicated alternative diet sections in Petco and independent natural pet stores.
Germany
Fressnapf's national retail network accelerates plant-based SKU placement alongside conventional veterinary diets. REACH compliance requirements tighten ingredient sourcing documentation for novel protein inputs. Berlin and Hamburg concentrate demand among sustainability-motivated urban professionals seeking certified organic formulations.
United Kingdom
Veterinary clinic endorsement requirements drive premium wet food positioning through peer-reviewed feeding study demands. The EU Green Deal's agricultural emissions targets indirectly channel research funding toward plant-based feed innovation. London's specialty veterinary channels and Manchester's digital-native brand headquarters concentrate competitive activity.
Italy
Amì Planet Srl's domestic production base anchors European distribution with direct-to-consumer penetration across the continent. FEDIAF amino acid mandates require specific nutritional substantiation that favors established formulation expertise. Milan and Bologna host manufacturing facilities serving Mediterranean and Central European markets.
Canada
Cross-border e-commerce from United States brands supplements limited domestic specialty retail infrastructure. Health Canada and the PMRA regulate veterinary health products including nutritional adequacy claims for alternative diets. Toronto and Vancouver metropolitan areas concentrate demand among urban professionals with ethical consumption preferences.
Vegan Cat Food Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence between in-house extrusion capabilities and outsourced co-manufacturing rotating advantage toward vertically integrated producers. The market structure fragments across three strategic archetypes: European manufacturers leveraging REACH-compliant supply chains for traceability premiums, United States technology-forward brands investing in precision fermentation research, and direct-to-consumer specialists capturing subscription revenue through nutritional education content. Dominant competitive moves include backward integration into captive ingredient sourcing and geographic expansion through continental distribution partnerships.
Within the integrated manufacturing tier, Benevo exemplifies British-based vertical control from raw ingredient through finished kibble, while Wild Earth occupies a position among technology-forward developers exploring precision fermentation pathways. Amì Planet Srl anchors the European specialist archetype with Italian production serving continental direct-to-consumer channels.
| Leading Market Players |
|---|
| Amì Planet Srl |
| Veggieanimals |
| VGRRR Pet Food Inc. |
| Nature's HUG Pet Food Inc. |
| Benevo |
| Wild Earth |
| Compassion Circle, Inc. |
| Wysong |
| Vitaveg |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day synthetic amino acid lead times compress formulation flexibility and rotate pricing power toward manufacturers with captive taurine supply agreements. Inventory velocity at extrusion facilities in the United States and Germany determines contract tier access for mid-tier brands seeking allergen-segregated production slots.
Pricing Analysis
Long-term offtake contracts for fungal protein concentrates anchor premium-tier pricing, while spot-market pea and soy isolate purchases dominate standard formulations. Price differentiation rests on AAFCO feeding trial certification status and REACH-compliant supply chain documentation. Cost compression in economy-tier kibble is intensifying because co-manufacturing capacity constraints force bidding wars for limited extrusion windows. Subscription-direct buyers in United States urban markets show lowest price sensitivity, while supermarket channel purchasers in Germany exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate wet food canning operations, whereas strategic stockpiling of synthetic taurine and arachidonic acid buffers pharmaceutical-grade supply volatility. Raw material sourcing draws from United States fungal fermentation facilities, Chinese pea protein isolate processors, and Indian pharmaceutical-grade amino acid refiners. Single-source vulnerability concentrates in European extrusion facilities capable of allergen-segregated vegan production runs. Distribution runs through specialty pet retail chains in Germany and the United Kingdom, direct-to-consumer subscription platforms in the United States, and veterinary clinic networks in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in wet food premium tiers where veterinary endorsement requirements create formulation expertise moats. Urban millennial pet ownership patterns in United States, German, and United Kingdom metropolitan clusters generate niche demand for subscription-direct channels with embedded nutritional education.
For Market Incumbents: Shield market position by securing captive supply agreements for precision fermentation-derived proteins before cost parity erodes differentiation. Backward integration into synthetic amino acid sourcing mitigates pharmaceutical-grade supply volatility threatening margin stability. Invest in AAFCO and FEDIAF feeding trial certification infrastructure to preempt regulatory compliance barriers for emerging entrants. For New Entrants and Emerging Players: Veterinary nutritionist content partnerships represent a service-layer gap where established brands under-invest in direct consumer education. Target wet food premium positioning in United Kingdom specialty veterinary channels where peer-reviewed feeding study requirements deter fast-follower competition. Capture United States urban millennial demand through subscription models with automated replenishment and nutritional adequacy content delivery. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-transition play because EU Green Deal agricultural emissions targets channel research funding toward plant-based feed innovation. Acquisition candidates with REACH-compliant supply chain documentation and Italian or British manufacturing footprints command defensive positioning. Monitor veterinary consensus publication velocity in peer-reviewed journals as the critical inflection signal for regulatory and consumer trust trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Fungal protein cost parity with animal concentrates unlocks premium-tier sustainability positioning for United States technology-forward brands. |
| AAFCO Feeding Trial Certification | Twenty-six-week nutritional substantiation studies preempt FDA Center for Veterinary Medicine enforcement actions on adequacy claims. |
| REACH-Compliant Supply Chain Documentation | Full substance traceability for novel protein inputs creates competitive moats for German manufacturers serving EU Green Deal-aligned demand. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models with embedded education content bypass specialty veterinary gatekeeping in United States metropolitan markets. |
| Wet Food Premium Tier Introduction | Seventy-five to eighty-five percent moisture formulations command price multiples through urinary tract health positioning in United Kingdom clinics. |
Study Parameters
The analysis maps dry food extrusion, wet food canning, fungal protein fermentation, and synthetic amino acid refinement sub-sectors, each validated through formulation scientists, veterinary nutritionists, specialty retail buyers, and regulatory affairs specialists. Primary interviews with supply chain managers at United States co-manufacturing facilities and procurement leads at German retailers combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, EFSA feeding study databases, FEDIAF nutritional guidelines, and REACH substance registration records. Bottom-up capacity modeling and top-down demand estimation triangulate volume and value outputs.
Consistency checks against external benchmarks validated projection outputs against specialty pet retail audit data and customs trade flows for pea protein isolate and fungal biomass shipments. Segmentation dimensions modeled include product moisture content, ingredient certification tier, packaging format, and distribution channel complexity across the analysis window. CAGRs derive from cohort-specific adoption curves for millennial and Gen Z pet owner segments, with veterinary endorsement velocity and regulatory compliance timelines as industry-specific forecast inputs.
Underlying assumptions cover sustained urban pet ownership growth, stable synthetic amino acid supply chains, and gradual veterinary consensus formation, with deviation risk concentrated in long-term feline health outcome studies and EU feed hygiene regulation amendments. Revision becomes warranted when peer-reviewed clinical evidence on obligate carnivore metabolic adaptation crosses thresholds sufficient to trigger regulatory framework restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Toy Dog Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Global Pet Supplies Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Hair Dryer for Pets Market
Pet Care Products
South America Cat Food Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Brazil Pet Food Market
Pet Care Products
UK Pet Diet Market
Pet Care Products
UK Pet Grooming Market
Pet Care Products
North America Pet Diet Market