
 High Fiber Dog Food Market | 2026-2036
High Fiber Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
High Fiber Dog Food Market Analytics
North American specialty grain mills and pulse processors is consolidating around contract supply for premium pet nutrition brands. Mars Petcare Inc. leverages its integrated ingredient sourcing network to secure consistent sweet potato and pea fiber volumes. Nestlé Purina PetCare anchors its position through veterinary channel partnerships that drive clinical endorsement of therapeutic fiber blends. Blue Buffalo differentiates via grain-free positioning that redirects fiber demand toward legume and vegetable sources.
High fiber dog food denotes formulations containing elevated crude fiber content, typically derived from beet pulp, cellulose, psyllium husk, or fermentable oligosaccharides, designed to modulate canine glycemic response, stool quality, and satiety signaling. Dry food dominates volume throughput due to shelf stability and cost-efficient fiber incorporation during extrusion, though wet food commands premium positioning for therapeutic applications targeting digestive disorders. Ingredient source segmentation reveals vegetable-derived fibers gaining traction as grain-free formulations expand, while legume-based options attract protein-fiber dual positioning. Customer type dynamics show veterinarians emerging as gatekeepers for prescription fiber diets, filtering owner purchasing decisions through clinical authority.
The FDA's Center for Veterinary Medicine enforces ingredient safety standards under the Federal Food, Drug, and Cosmetic Act, while AAFCO model regulations govern nutritional adequacy claims and fiber content labeling across state jurisdictions. State feed control officials in California, Texas, and New York conduct random sampling that enforces compliance and shapes regional market access thresholds. Stakeholders must monitor evolving FDA guidance on novel fiber ingredients and anticipate state-level enforcement divergence that could fragment distribution strategies.
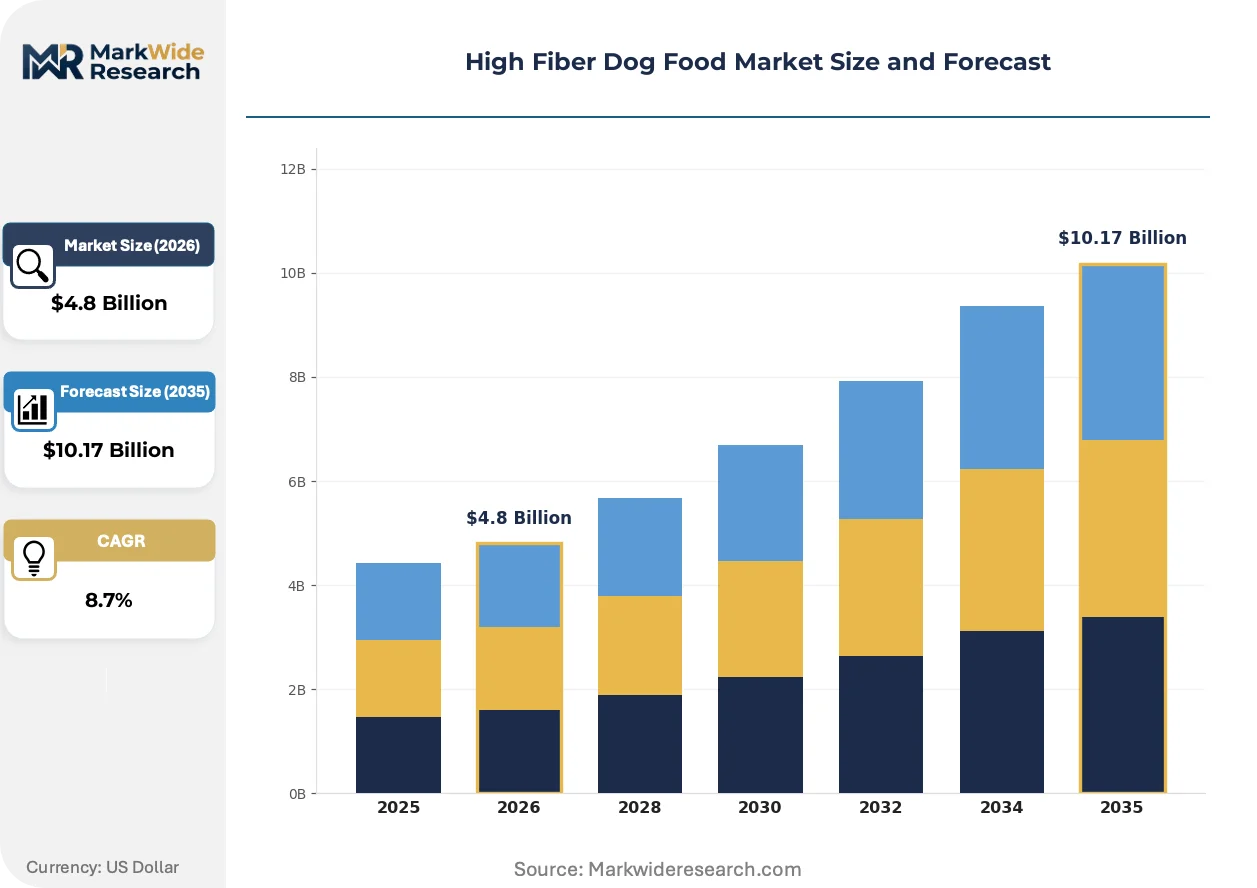
Market Dynamics
Veterinary channel consolidation and pet humanization are restructuring how therapeutic fiber formulations reach end consumers, with clinical endorsement now filtering owner purchasing decisions through prescription pathways that privilege science-backed positioning over mass-market branding.
Growth Catalysts
- AAFCO Nutritional Adequacy Framework:Model regulations governing fiber content labeling create compliance clarity that enables premium positioning and justifies price architecture across state jurisdictions.
- Diabetic Canine Population:Veterinary recommendations for glycemic-modulating diets drive prescription volume through specialty clinics and emergency animal hospitals.
- Pulse Processing Infrastructure:North American specialty grain mills are consolidating contract supply relationships that secure consistent pea fiber and lentil derivative volumes for premium pet nutrition brands.
Market Restraints
- Sweet Potato Supply Concentration:Ingredient sourcing networks face geographic concentration risk in southeastern US growing regions where climate volatility affects harvest consistency.
- Grain-Free Formulation Technical Limitations:Legume-based fiber sources introduce protein-fiber interaction complexities that challenge extrusion stability and shelf-life performance in dry food matrices.
- State Feed Control Sampling Variance:California, Texas, and New York enforcement divergence creates compliance fragmentation that elevates distribution strategy costs for multi-state operators.
Strategic Opportunities
- Wet Food Therapeutic Positioning:Digestive disorder applications command premium pricing through veterinary channels where moisture content enhances palatability for compromised animals.
- Fermentable Oligosaccharide Convergence:Prebiotic fiber technology is converging with microbiome science to create next-generation formulations targeting gut-brain axis modulation.
- Direct-to-Consumer Subscription Models:Bypassing traditional retail through personalized nutrition platforms captures owner data and builds recurring revenue streams.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Formulation science expertise gaps slow clinical trial design and regulatory submission timelines for novel fiber ingredients.
- Legacy Extrusion Equipment Retrofit Costs:High-fiber inclusion rates demand capital-intensive processing modifications that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Fiber Dog Food Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Grains, Vegetables, Fruits, Legumes Packaging Type: Bag, Can, Pouch, Box Customer Type: Dog Owners, Pet Stores, Veterinarians, Online Retailers |
| Companies Covered | Mars Petcare Inc., Nestlé Purina PetCare, Colgate-Palmolive Company, General Mills Inc., The J.M. Smucker Company, Royal Canin, Blue Buffalo, Nutro, Diamond Pet Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Fiber Dog Food Market Evolving Landscape
Active reshaping in this market centers on ingredient source rotation, clinical validation requirements, and channel architecture transformation that privileges veterinary gatekeeping over traditional retail discovery.
Psyllium husk extraction technology is converging with precision drying systems to preserve mucilaginous properties through processing. Specialty therapeutic brands are adopting these systems at accelerated pace to differentiate stool-quality claims. The structural consequence is compression of commodity fiber margins as functional efficacy becomes the primary purchase determinant.
FDA Center for Veterinary Medicine guidance on novel fiber ingredients is tightening safety substantiation requirements for fermentable substrates. This elevates clinical trial burden and extends time-to-market for ingredient innovators. Small-scale domestic manufacturers face disproportionate impact and are responding through cooperative research arrangements with university veterinary schools.
Subscription-based replenishment models are displacing periodic retail purchasing among urban companion animal owners. Veterinary clinics and direct platforms are capturing volume previously routed through mass-market pet specialty retailers. This behavioral shift is most visible in coastal metropolitan markets where convenience prioritization overrides price sensitivity.
High Fiber Dog Food Market Segmentation
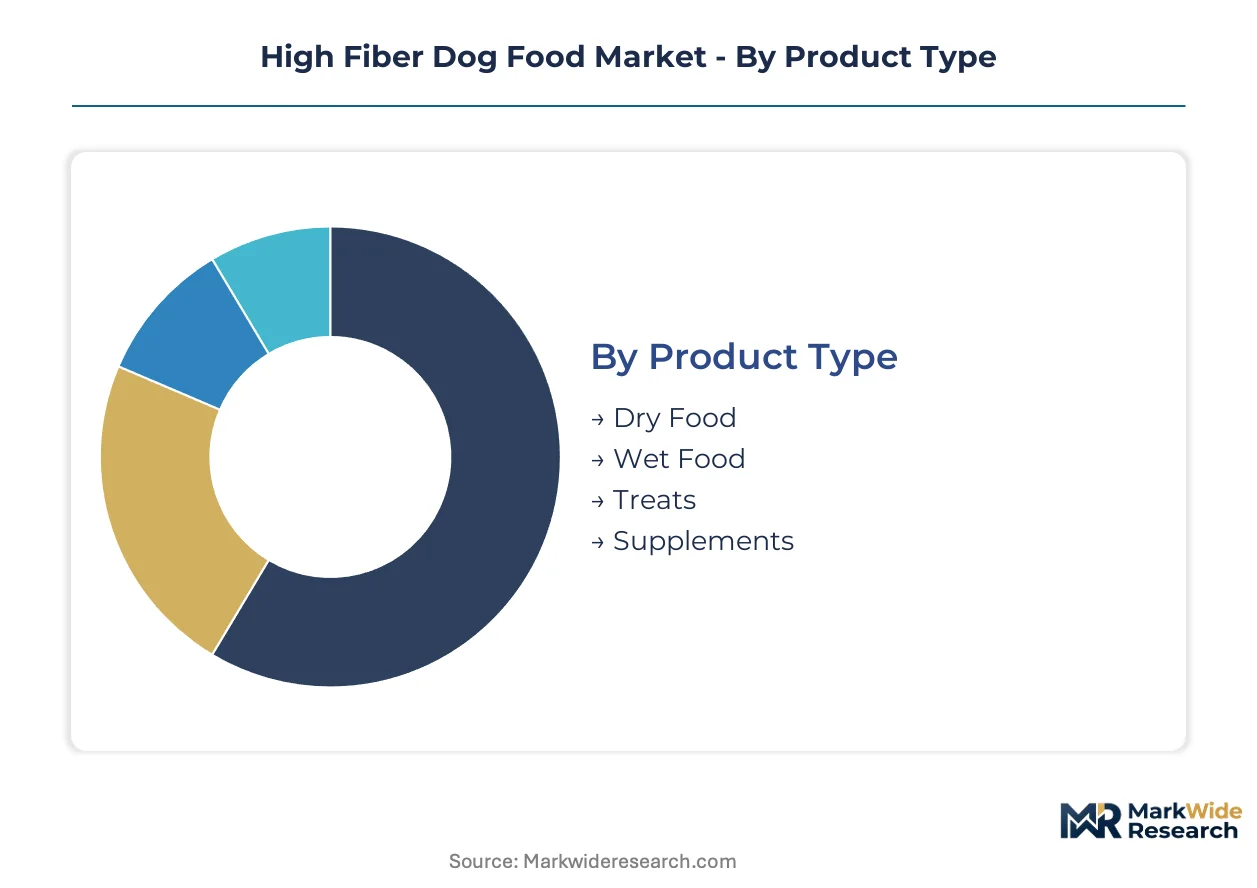
Segmentation in high fiber dog food reveals how purchasing authority has fragmented across clinical, retail, and digital channels. Manufacturers must align formulation specifications, packaging formats, and fiber sourcing strategies to the distinct technical and commercial requirements of each buyer category.
Product Type:
Price sensitivity and feeding convenience determine format selection among companion animal owners, with therapeutic applications commanding fundamentally different technical specifications than routine nutrition.
- Dry Food:Extruded kibble matrices accommodate crude fiber inclusion rates of 8-15% through beet pulp, cellulose, and pea fiber integration during high-pressure thermal processing. Shelf stability and cost-efficient bulk production concentrate demand in multi-dog households across suburban United States markets where storage capacity and feeding frequency favor dry formats.
- Wet Food:Canned and tray formulations leverage moisture content to enhance palatability for diabetic, geriatric, or digestive-compromised animals requiring glycemic modulation or stool quality management. Veterinary prescription pathways in specialty and emergency clinics drive premium positioning where clinical endorsement overrides mass-market price comparison.
- Treats:Functional snack formats deliver targeted fiber supplementation through limited-ingredient biscuits and dental chews positioned for intermittent reward rather than complete nutrition.
- Supplements:Powder and chewable add-on products enable fiber customization atop existing diets, appealing to owners seeking incremental dietary modification without complete formula switching.
Dry food leads on scale through retail volume and household penetration; wet food leads on momentum through veterinary channel expansion and therapeutic premiumization.
Ingredient Source:
Supply chain resilience and protein-fiber interaction complexity are reshaping sourcing decisions as grain-free positioning redirects formulation toward alternative carbohydrate bases.
- Vegetables:Sweet potato, pumpkin, and cellulose derivatives provide fermentable and non-fermentable fiber fractions with established glycemic response modulation. Southeastern United States growing regions supply concentrated volumes to Mars Petcare and Nestlé Purina, though climate volatility elevates contract security premiums.
- Legumes:Pea fiber, lentil derivatives, and chickpea fractions deliver protein-fiber dual positioning that supports grain-free claims while contributing amino acid profiles. Blue Buffalo and specialty brands anchor positioning here, though extrusion stability challenges and protein-carbohydrate interaction complexities constrain inclusion rates in dry matrices.
- Grains:Oat fiber, barley, and brown rice fractions retain cost advantage and processing familiarity in conventional formulations, particularly in price-sensitive retail tiers.
- Fruits:Apple fiber, blueberry pomace, and cranberry extracts contribute antioxidant positioning alongside soluble fiber content, concentrated in premium and super-premium product lines.
Vegetable sourcing leads on scale through established agricultural infrastructure; legume integration leads on momentum through grain-free category expansion.
Packaging Type:
Shelf-life requirements and channel-specific merchandising constraints dictate format selection, with veterinary and digital channels demanding fundamentally different protection and portability specifications than mass retail.
- Bag:Multi-wall paper and plastic laminate structures dominate dry food distribution, offering moisture barrier protection and efficient palletization for warehouse club and pet specialty retail.
- Can:Steel and aluminum containers preserve wet food sterility and palatability, essential for therapeutic applications where product integrity supports clinical efficacy claims.
- Pouch:Flexible retort and spouted formats enable portion control and resealability, gaining traction in urban markets where convenience and premium positioning align.
- Box:Carton-based secondary packaging supports subscription and direct-to-consumer fulfillment, optimizing for shipping dimensional efficiency and unboxing experience.
Bags lead on scale through dry food volume concentration; pouches lead on momentum through convenience-oriented urban purchasing and subscription model compatibility.
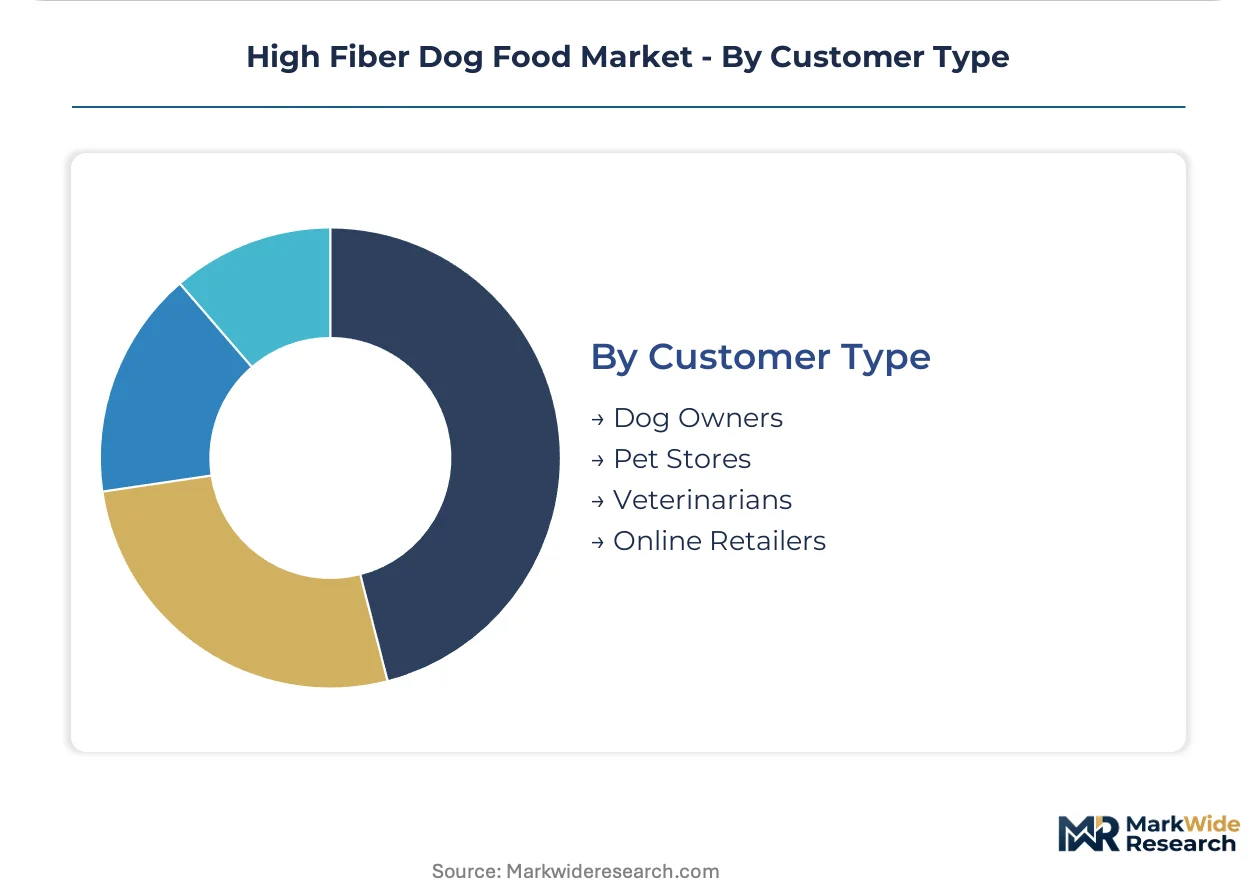
Customer Type:
Purchasing authority has concentrated in clinical gatekeepers and digital platforms, fragmenting traditional retail influence and demanding segmented commercial strategies.
- Veterinarians:Clinical endorsement of prescription fiber diets for diabetic and overweight canines filters owner decisions through authority-based recommendation, privileging science-backed positioning and therapeutic claims. FDA Center for Veterinary Medicine oversight of veterinary feed directive compliance elevates documentation and substantiation burdens.
- Dog Owners:Direct purchasing through mass retail and digital channels reflects pet humanization trends and ingredient transparency demands, with subscription models capturing recurring revenue in coastal metropolitan United States markets.
- Pet Stores:Specialty retail retains curation role for premium and super-premium discovery, though volume share faces pressure from veterinary prescription and direct-to-consumer channels.
- Online Retailers:Platform algorithms and review aggregation accelerate brand switching and enable personalized nutrition matching, concentrating data capture and customer relationship ownership.
Veterinary channels lead on momentum through clinical authority consolidation; dog owner direct purchasing leads on scale through household penetration and retail accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined pet food safety frameworks and lower cost-of-compliance thresholds. The United States maintains the highest absolute compliance burden through FDA Center for Veterinary Medicine oversight, while emerging production hubs exploit regulatory harmonization gaps to capture contract manufacturing volume.
United States
Veterinary prescription pathways and pet humanization trends concentrate demand in California, Texas, and New York metropolitan markets. FDA enforcement of veterinary feed directive compliance elevates documentation burdens that privilege established manufacturers with dedicated regulatory affairs infrastructure. The Southeast growing belt—spanning North Carolina, Georgia, and Florida—anchors sweet potato and pea fiber sourcing networks that supply extrusion facilities in the Midwest.
Germany
EFSA novel food ingredient assessments and strict GMO labeling requirements shape formulation choices for premium export-oriented producers. The country's national pharmaceutical regulator enforces veterinary medicinal product boundaries that constrain therapeutic claim positioning. Bavaria's ingredient processing corridor around Munich hosts specialty grain mills supplying contract fiber volumes to private-label pet nutrition brands.
China
SAMR national food safety standards and GB pet feed specifications govern import substitution strategies targeting domestic premiumization. The country's national agricultural regulator monitors mycotoxin thresholds in grain-based fiber sources with sampling intensity that exceeds regional peers. Yangtze River Delta manufacturing clusters around Shanghai are consolidating extrusion capacity to serve Asia-Pacific brand owners seeking cost-advantaged production.
Brazil
ANVISA veterinary product registration pathways and MERCOSUR technical regulations create dual compliance obligations for multinational entrants. The country's national agricultural supply company supports domestic soybean fiber derivative production through procurement guarantees. São Paulo state's pet food manufacturing belt is absorbing technology transfer from European equipment suppliers to upgrade high-fiber extrusion capabilities.
United Kingdom
Post-Brexit divergence from EU feed additive approvals is fragmenting regulatory coherence and elevating dual-registration costs for cross-channel operators. The Food Standards Agency enforces retained EU law with enforcement discretion that creates uncertainty for novel fiber ingredient innovators. The Midlands manufacturing corridor retains concentration of extrusion assets originally established to serve European Union distribution networks.
High Fiber Dog Food Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue veterinary channel specialization and direct-to-consumer subscription models to bypass retail gatekeepers. Market structure exhibits consolidated leadership at the mass-premium intersection, with fragmentation persisting in therapeutic and grain-free niches where clinical validation requirements filter participation. Three archetypes dominate: multinational consumer goods conglomerates with integrated ingredient sourcing, veterinary-focused specialists leveraging prescription pathways, and digitally native challengers capturing subscription recurring revenue. Capacity expansion and strategic partnerships represent the dominant competitive moves, with extrusion equipment retrofit partnerships and university veterinary school research arrangements accelerating clinical substantiation timelines.
Among diversified consumer goods conglomerates, Mars Petcare Inc. and Nestlé Purina PetCare exemplify scale-driven archetypes with captive supply networks spanning sweet potato procurement through retail distribution. Blue Buffalo occupies a position within the grain-free specialist tier, representing formulation approaches that redirect fiber demand toward legume and vegetable sources. These three companies anchor the competitive landscape through divergent channel strategies—veterinary endorsement, mass retail penetration, and premium ingredient positioning—that collectively define the market's strategic frontier.
| Leading Market Players |
|---|
| Mars Petcare Inc. |
| Nestlé Purina PetCare |
| Colgate-Palmolive Company |
| General Mills Inc. |
| The J.M. Smucker Company |
| Royal Canin |
| Blue Buffalo |
| Nutro |
| Diamond Pet Foods |
| Others |
Value Network & Pricing Analysis
Captive sourcing of sweet potato and pea fiber through long-term contracts with southeastern United States growers anchors both supply security and pricing power for premium manufacturers. This backward integration insulates Mars Petcare and Nestlé Purina from spot-market volatility while supporting the premium positioning necessary for veterinary-channel markup capture.
Pricing Analysis
Veterinary channel margins command the highest premium tier, where clinical endorsement justifies substantial markup over mass-market retail. Three-tier pricing structure across premium, standard, and economy levels separates prescription therapeutic formulations from grain-free specialty lines and conventional retail offerings. Price differentiation rests on certification grade—FDA Center for Veterinary Medicine compliance for prescription diets versus AAFCO nutritional adequacy for retail tiers. Pricing pressure stems from state feed control sampling variance, which elevates compliance costs for multi-state operators. Mass-market retail buyers exhibit highest price sensitivity, while veterinary clinic procurement committees prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled prescription diets require specialized handling through veterinary clinic return programs, creating dedicated collection infrastructure that commodity retail channels lack. Geographic supply concentrates in the United States for sweet potato fiber, Canada for pea protein derivatives, and Brazil for soybean hull fractions. Raw material dependencies include southeastern US agricultural harvests, North American pulse processing mill output, and international legume protein concentrate imports. Single-source vulnerability in southeastern growing regions—where climate volatility affects harvest consistency—represents the dominant structural risk. Distribution runs through veterinary clinic direct delivery, pet specialty retail warehousing, and subscription platform fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing footprint arbitrage between FDA-regulated US production and emerging contract manufacturing hubs exploits compliance cost differentials. Brazil's ANVISA pathways and lower regulatory documentation burdens attract volume seeking margin preservation.
For Market Incumbents: Deepen captive supply relationships with southeastern US sweet potato cooperatives to secure harvest priority rights ahead of climate-stressed growing seasons. Expand extrusion capacity in Midwest processing corridors to capture economies of scale as high-fiber inclusion rates strain legacy equipment. Vertical integration into pea fiber milling through partnership with North American specialty grain processors defends margin position against commodity price spikes. Reinforce veterinary channel control through exclusive distribution agreements with specialty and emergency clinic networks. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription models targeting coastal metropolitan markets where convenience prioritization overrides price sensitivity. Target the wet food therapeutic segment, where moisture-enhanced palatability commands premium pricing and veterinary endorsement filters owner decisions. Exploit white space in fermentable oligosaccharide formulations by partnering with university veterinary schools for clinical substantiation. Deploy personalized nutrition platforms that capture owner data and build recurring revenue streams outside traditional retail gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier therapeutic specialists because veterinary channel consolidation concentrates purchasing authority around clinically validated brands. The five-to-ten year viability window favors acquisition of extrusion-capable manufacturers with FDA veterinary feed directive compliance infrastructure already in place. Target firms with established university research partnerships that accelerate novel fiber ingredient substantiation timelines. Monitor FDA Center for Veterinary Medicine guidance evolution as the critical inflection signal—tightening safety requirements will filter marginal participants and concentrate value in substantiated portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership Expansion | Clinical endorsement through specialty clinics filters owner purchasing decisions toward prescription fiber formulations. |
| Backward Integration into Pea Fiber Milling | Captive supply from North American pulse processors secures consistent input volumes for grain-free positioning. |
| Direct-to-Consumer Subscription Launch | Urban coastal markets prioritize convenience over price sensitivity, enabling recurring revenue capture outside retail. |
| University Research Collaboration | Partnerships with veterinary schools accelerate clinical trial design for novel fermentable fiber substantiation. |
| Extrusion Equipment Retrofit Investment | High-fiber inclusion rates demand capital-intensive processing modifications that strain mid-tier manufacturer balance sheets. |
Research Methodology
Multiple input streams—structured interviews with veterinary nutritionists and pet food formulation scientists, regulatory affairs specialists at FDA Center for Veterinary Medicine, procurement managers at specialty clinic networks, and category buyers at pet specialty retailers—were reconciled against secondary validation from AAFCO model regulations, FDA veterinary feed directive compliance databases, state feed control official sampling records, and SEC filings from publicly traded pet nutrition conglomerates. Bottom-up volume estimates from ingredient sourcing networks and top-down demand projections from veterinary prescription pathway analysis were triangulated to constrain forecast variance.
Data-stream reconciliation across the projection horizon employed segmentation modeling by product type, ingredient source, packaging format, and customer channel, with cross-validation against regional regulatory clusters. CAGRs were derived from fitted growth curves anchored to veterinary diabetic canine population projections and pet humanization trend indices. Industry-specific forecast inputs included sweet potato harvest yield variance models and extrusion capacity utilization rates at Midwest processing facilities.
Inputs from veterinary clinic procurement systems and state feed control sampling databases were available through the study window; gaps in real-time prescription volume tracking introduce uncertainty bands around therapeutic segment projections. Forecasts reflect assumptions regarding AAFCO regulatory stability and FDA enforcement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
United States Pet Market
Pet Care Products
Cat Collar Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Tofu Cat Litter Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Dog Vest Market
Pet Care Products
United Kingdom Cat Litter Market
Pet Care Products
Pet Fitness Care Market