
 Agricultural Tractor Robots Market | 2026-2036
Agricultural Tractor Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Tractor Robots Market Analysis
ISO 12100 safety compliance for autonomous machinery is reorganizing competitive entry in agricultural tractor robotics. Deere & Company leverages its precision agriculture ecosystem to anchor North American deployment. AGCO Corporation differentiates through open-architecture platforms that integrate third-party autonomy modules. CNH Industrial N.V. competes via manufacturing scale across European and North American production facilities.
Agricultural tractor robots combine sensor fusion arrays, electro-hydraulic actuation, and real-time kinematic GPS guidance to execute soil preparation, seeding, and crop management cycles without continuous human operation. These systems typically operate at sub-inch positioning accuracy while managing implement forces through programmable hydraulic valves. Autonomous tractors currently dominate capital deployment, while computer vision technology is expanding fastest as perception stacks mature for obstacle detection in unstructured field environments. Electric tractors represent an emerging segment where battery energy density limitations constrain duty-cycle economics.
The EU Machinery Directive, EPA emissions certification for non-road engines, and FCC Part 15 rules for unlicensed radio telemetry collectively shape product development timelines and geographic launch sequencing. Farm operators in jurisdictions with stringent autonomous vehicle liability frameworks face extended validation requirements before field deployment. Stakeholders must monitor evolving liability allocation between equipment manufacturers and farm operators as insurance frameworks adapt to unmanned machinery operations.
Market Dynamics
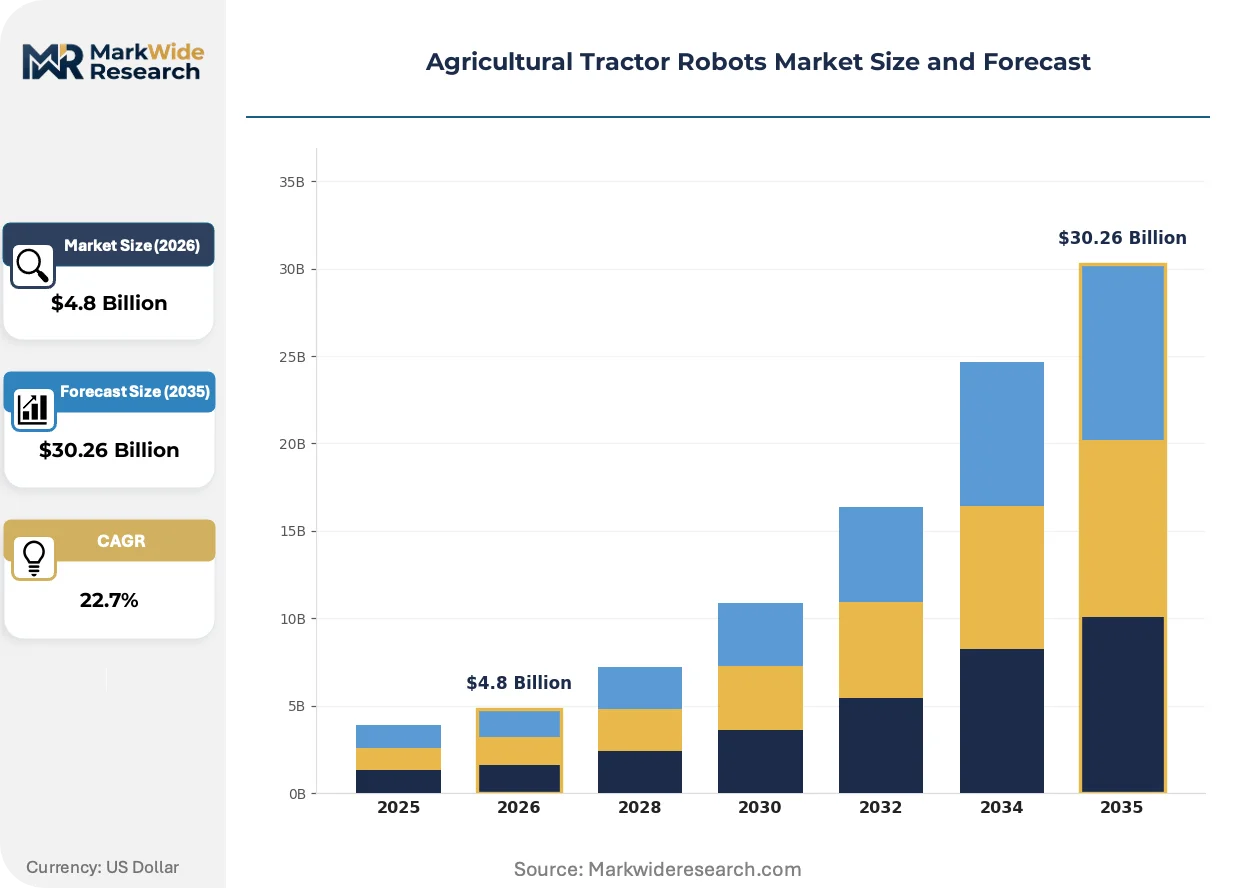
Farm consolidation across the United States is concentrating capital deployment toward autonomous tillage systems, while ISO 12100 safety compliance is reorganizing which manufacturers can certify equipment for unmanned field operation.
Growth Catalysts
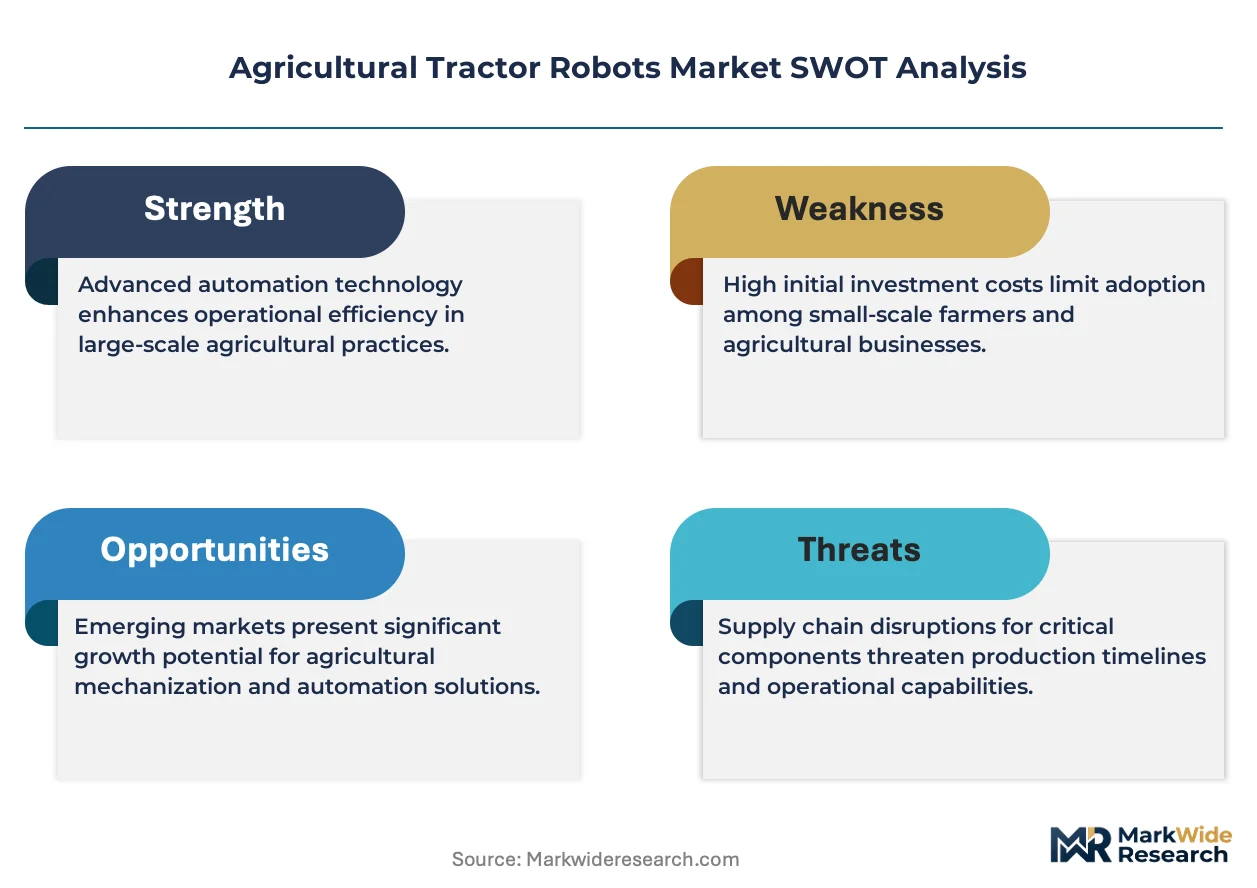
- EU Machinery Directive:Mandatory CE marking for autonomous agricultural equipment is creating a standardized certification pathway that reduces regional fragmentation for compliant manufacturers.
- Sensor fusion arrays:Integration of LiDAR, radar, and computer vision modules is enabling sub-inch positioning accuracy without continuous human oversight in row-crop environments.
- Midwestern US farm consolidation:Large-scale operators managing ten-thousand-plus acre holdings are deploying capital toward autonomous seeding and soil preparation cycles.
Market Restraints
- Lithium-ion battery energy density:Current cell chemistry limitations constrain duty-cycle economics for electric tractor variants, compressing operational windows during peak planting seasons.
- Specialized hydraulic component suppliers:Concentration of electro-hydraulic valve manufacturing in German and Japanese supply bases creates vulnerability to regional production disruptions.
- FCC Part 15 unlicensed radio telemetry:Spectrum congestion in rural deployment zones limits real-time data transmission bandwidth for fleet coordination algorithms.
Strategic Opportunities
- Brazilian soybean belt expansion:Underpenetrated autonomous tillage adoption in Mato Grosso and Goiás states offers first-mover positioning for RTK-GPS-guided systems.
- US Inflation Reduction Act:Clean energy tax credits for agricultural electrification are narrowing total cost of ownership gaps between diesel and battery-electric tractor platforms.
- Telematics-platform convergence:Integration of autonomous navigation stacks with predictive maintenance algorithms is opening subscription revenue streams beyond equipment sales.
Industry Challenges
- Autonomous systems engineering talent:Scarcity of robotics software developers with agricultural domain expertise is extending product development timelines for perception stack optimization.
- ISO 12100 validation protocols:Extended field-testing requirements for safety-critical obstacle detection are delaying commercial launch schedules by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Tractor Robots Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Tractors, Semi-Autonomous Tractors, Hybrid Tractors, Electric Tractors Technology: Machine Learning, GPS Navigation, IoT Connectivity, Computer Vision End User: Farm Owners, Agricultural Cooperatives, Contract Farmers, Research Institutions Application: Tillage, Planting, Harvesting, Irrigation |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Autonomous Solutions, Inc., CLAAS KGaA mbH, Kubota Corporation, Yanmar Holdings Co., Ltd., Lely, Trimble, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Tractor Robots Market Emerging Trajectories
Autonomous tractor technology is separating into distinct performance tiers as perception capabilities mature, while regulatory frameworks in multiple jurisdictions are hardening certification requirements for unmanned agricultural machinery.
Computer vision perception stacks are bifurcating the autonomous tractor market into premium systems with full obstacle-avoidance autonomy and standard-tier platforms requiring supervised operation. Large-scale row-crop operators in Iowa and Illinois are adopting premium configurations for overnight tillage cycles. This technology stratification is compressing pricing power for mid-tier manufacturers lacking proprietary vision algorithms.
EPA emissions certification for non-road engines is tightening nitrogen oxide limits for diesel-powered autonomous tractors, forcing manufacturers to integrate selective catalytic reduction systems. The industrial consequence is elevated bill-of-materials costs and extended type-approval timelines. European manufacturers with established aftertreatment supply chains are responding faster than North American competitors, shifting competitive positioning in cross-border procurement.
Service contract unbundling is displacing traditional bundled maintenance agreements for autonomous tractor fleets. Dealer networks in the US Corn Belt are losing exclusivity on predictive maintenance revenue as OEMs deploy direct-to-operator telematics platforms. This channel disruption is most visible in Kansas and Nebraska, where farm operators now procure software updates and component replacement services through separate vendor relationships.
Agricultural Tractor Robots Market Segmentation
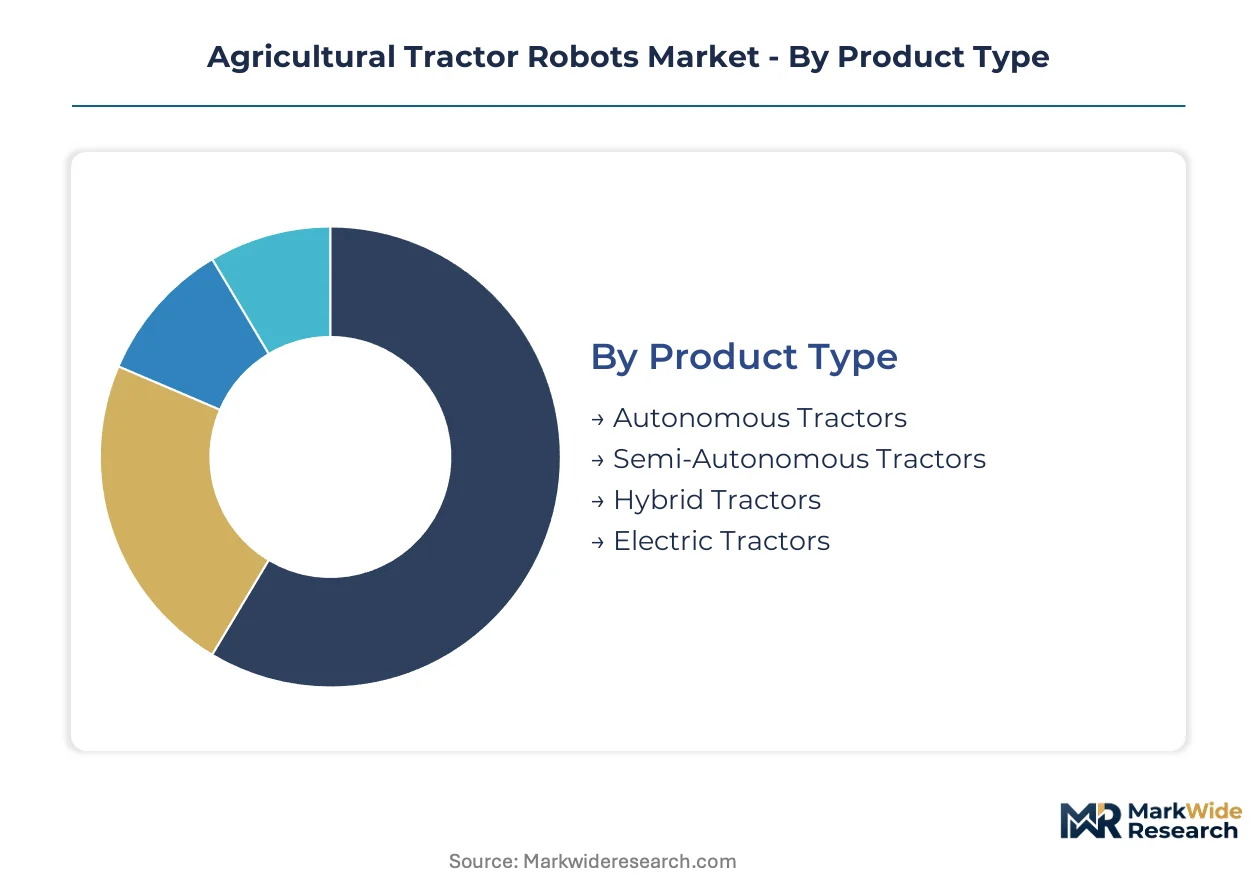
Segmentation in agricultural tractor robotics reveals how capital deployment concentrates across automation tiers and control architectures. Manufacturers calibrate sensor payloads and hydraulic systems to match distinct operational intensity requirements across end-use profiles.
Product Type:
Margins pool heaviest in configurations enabling unmanned operation cycles, where software licensing and predictive maintenance subscriptions compound equipment revenue.
- Autonomous Tractors:Full-stack systems integrate LiDAR arrays, RTK-GPS guidance, and electro-hydraulic implement control for continuous unmanned field operation. Demand concentrates in Iowa and Illinois row-crop operations managing ten-thousand-plus acre holdings, driven by overnight tillage economics and labor scarcity during compressed planting windows.
- Semi-Autonomous Tractors:Operator-supervised platforms retain manual override capability while automating steering and implement depth control through programmable hydraulic valves. Brazilian Mato Grosso soybean operations favor these configurations for capital-constrained expansion, balancing automation gains against lower upfront acquisition costs.
- Hybrid Tractors:Diesel-electric powertrains pair internal combustion engines with electric auxiliary drives for implement operation.
- Electric Tractors:Battery-electric platforms face duty-cycle constraints from lithium-ion energy density limits during peak seasonal demand.
Autonomous tractors hold installed capacity. Electric tractors are rotating up the share rankings.
Technology:
Technology selection tracks the progression from positioning accuracy toward environmental perception and fleet coordination capabilities.
- Computer Vision:Perception stacks process stereo camera arrays and neural network inference for obstacle detection in unstructured field environments. Large-scale US operators deploy these systems for premium overnight autonomy, with EPA emissions certification timelines accelerating hardware integration schedules.
- Machine Learning:Edge-deployed models optimize implement settings based on real-time soil sensor feedback and yield map historical data. EU Machinery Directive CE marking requirements are concentrating demand among European manufacturers with validated safety-critical algorithm documentation.
- GPS Navigation:RTK-corrected positioning achieves sub-inch accuracy for repetitive field patterns.
- IoT Connectivity:Telemetry modules enable fleet coordination and predictive maintenance algorithm deployment.
Computer Vision commands premium pricing tiers. Machine Learning is climbing the fastest among perception technologies.
End User:
End-user segmentation reflects capital access gradients and operational scale thresholds for automation economics.
- Farm Owners:Individual proprietors and family operations deploy autonomous systems to replace retiring equipment operators and compress seasonal labor requirements. Kansas and Nebraska grain operations lead US adoption, leveraging USDA conservation program incentives for precision agriculture infrastructure.
- Agricultural Cooperatives:Member-owned aggregations pool capital for shared autonomous fleet deployment across multiple production units. Illinois and Iowa cooperatives are consolidating procurement power to negotiate telematics-platform convergence and subscription service unbundling.
- Contract Farmers:Service providers face utilization-rate thresholds for autonomous equipment amortization.
- Research Institutions:University extension programs and USDA research stations validate perception algorithms under controlled field conditions.
Farm Owners anchor current deployment volumes. Agricultural Cooperatives are gaining share fastest through pooled procurement models.
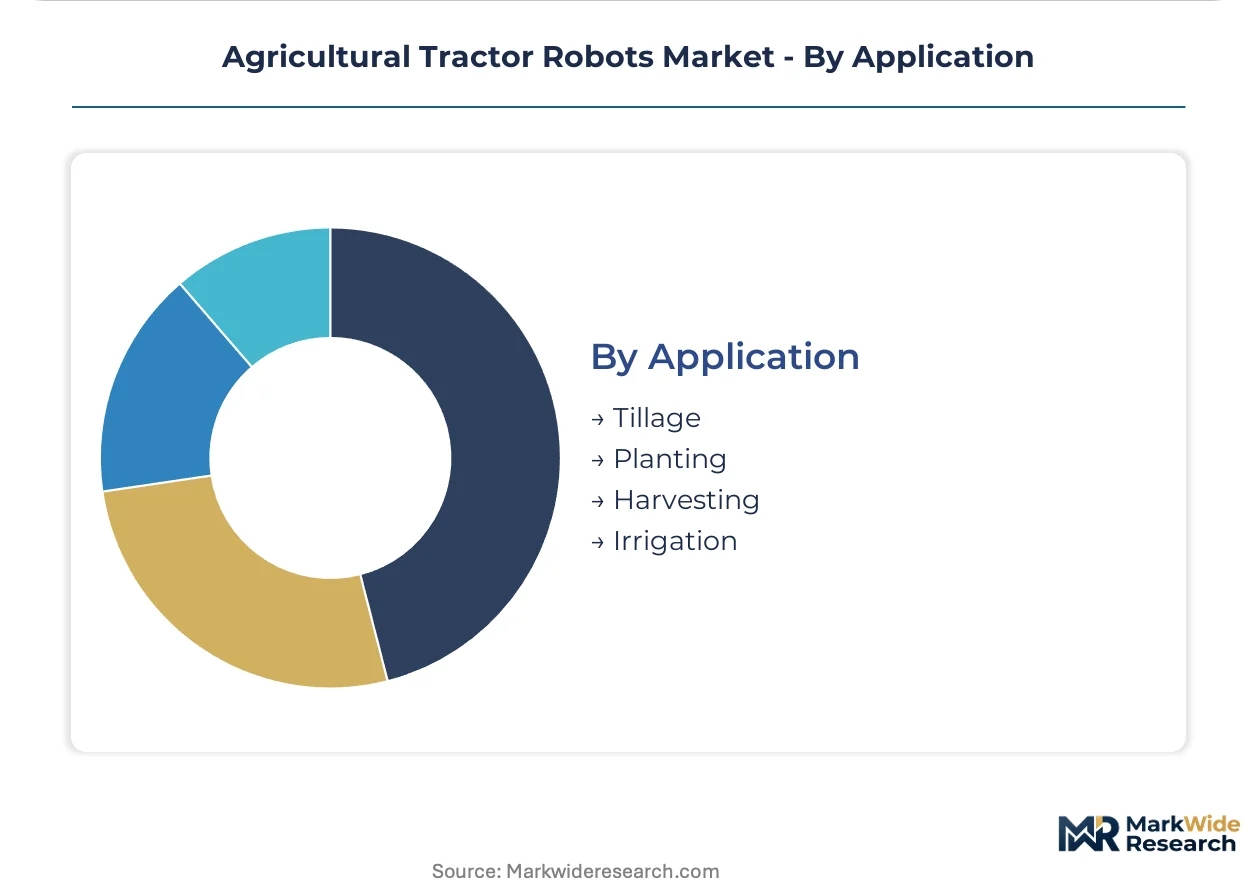
Application:
Application segmentation separates soil preparation and planting cycles with deterministic field patterns from harvesting operations requiring adaptive obstacle response.
- Tillage:Soil preparation cycles follow repetitive geometric patterns with minimal dynamic obstacle exposure, making tillage the primary entry point for full autonomy deployment. US Corn Belt operators prioritize autonomous tillage for 24-hour operational windows during weather-constrained spring preparation periods.
- Planting:Seeding operations demand sub-inch positioning accuracy for row spacing and seed depth consistency, with implement force management through programmable hydraulic valves. Brazilian Goiás state expansion is concentrating demand for RTK-GPS-guided planting systems as soybean belt acreage extends into previously marginal lands.
- Harvesting:Crop removal operations face variable moisture conditions and dynamic yield mapping requirements.
- Irrigation:Autonomous pivot and linear move systems integrate with tractor robotics for water application scheduling.
Tillage holds installed capacity. Planting is rotating up the share rankings as perception stacks mature for seedbed preparation complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River inland waterway system underwrites US agricultural robotics deployment by connecting Midwestern grain terminals to export markets. European rail freight corridors and the Rhine-Danube waterway network similarly enable component logistics for autonomous machinery manufacturers.
United States
Midwestern farm consolidation into ten-thousand-plus acre holdings concentrates capital for autonomous tillage deployment. The EPA enforces Tier 4 Final emissions standards for non-road engines, forcing selective catalytic retrofits on diesel tractor platforms. Iowa and Illinois operators lead overnight autonomy adoption for compressed spring planting windows.
Germany
Precision agriculture component manufacturing clusters in Baden-Württemberg supply electro-hydraulic valve systems to global tractor assemblers. The EU Machinery Directive mandates CE marking for autonomous equipment, creating standardized certification pathways. Stuttgart-area engineering firms validate ISO 12100 safety protocols for obstacle-detection perception stacks.
Brazil
Mato Grosso and Goiás soybean belt expansion generates demand for RTK-GPS-guided seeding systems on previously marginal acreage. ANVISA regulates agricultural chemical application rates that autonomous sprayers must integrate. Campo Grande machinery dealers are retrofitting semi-autonomous platforms for capital-constrained operators.
Japan
Small-field rice cultivation drives compact autonomous tractor development for terraced terrain. METI subsidizes precision agriculture technology adoption under Smart Agriculture initiatives. Osaka-based hydraulic component suppliers serve Asian tractor assembly networks.
China
Yangtze River Delta manufacturing clusters produce sensor fusion arrays for cost-sensitive automation tiers. MIIT standards govern agricultural machinery safety certification timelines. Jiangsu province testbeds validate computer vision algorithms for unstructured field obstacle detection.
Agricultural Tractor Robots Market Vendor Landscape
Listed leaders compete with private specialists across capital access and R&D scale. The vendor base separates into three tiers: diversified agricultural equipment conglomerates with precision agriculture ecosystems, regional machinery manufacturers integrating third-party autonomy modules, and pure-play robotics software developers. Strategic moves concentrate on telematics-platform convergence and predictive maintenance subscription unbundling.
Within the diversified equipment tier, Deere & Company and AGCO Corporation exemplify manufacturers leveraging installed precision agriculture infrastructure to anchor autonomous deployment. CNH Industrial N.V. occupies a position among European-headquartered conglomerates with manufacturing scale across multiple continents. These three entities represent distinct strategic postures: ecosystem integration, open-architecture platform development, and transcontinental production footprint optimization.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Autonomous Solutions, Inc. |
| CLAAS KGaA mbH |
| Kubota Corporation |
| Yanmar Holdings Co., Ltd. |
| Lely |
| Trimble, Inc. |
| Others |
Supply Flow & Price Mechanics
Ten-thousand-plus acre farm consolidation in Iowa and Illinois concentrates procurement volumes that reshape supplier pricing power and compress mid-tier manufacturer margins. Scale economies at this operational tier enable volume-discount negotiations that cascade through electro-hydraulic component sourcing and telematics subscription bundling.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between large-scale operators and OEMs, with three-tier pricing stratification across premium autonomy configurations, standard supervised platforms, and economy retrofit kits. Price differentiation hinges on ISO 12100 safety certification grade and after-sales service bundling depth. Cost compression in standard-tier platforms is intensifying because Brazilian and Chinese manufacturers are flooding cost-sensitive segments with unbundled hardware. Agricultural cooperatives in Illinois and Iowa exhibit highest price sensitivity due to pooled procurement leverage, while individual farm owners managing premium acreage show lowest sensitivity to upfront capital outlays.
Supply Chain Analysis
Germany and Japan anchor electro-hydraulic valve manufacturing for precision implement control, with Baden-Württemberg engineering clusters and Osaka-based suppliers feeding global tractor assembly networks. Lithium-ion cell production draws from South Korean and Chinese cathode material streams, while sensor fusion arrays source CMOS image sensors from Taiwanese foundries. Single-source vulnerability concentrates in German hydraulic component suppliers subject to Rhine-Danube waterway logistics disruptions. Distribution runs through authorized dealer networks in the US Corn Belt and Campo Grande machinery corridors in Brazil, with direct-to-operator telematics platforms displacing traditional channel exclusivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of robotics software developers with agricultural domain expertise constrains product development velocity and extends commercialization timelines for perception stack optimization. This capability gap creates asymmetric returns for stakeholders who secure talent pipelines or acquire validated algorithm portfolios.
For Market Incumbents: Consolidate control over electro-hydraulic valve supply chains through backward integration into German and Japanese component manufacturing. Defensive positioning requires accelerating ISO 12100 validation protocols to maintain certification lead times against emerging Chinese competitors. Channel control investments in direct-to-operator telematics platforms will offset dealer network revenue erosion.
For New Entrants and Emerging Players: CE marking fast-tracks for autonomous agricultural equipment create regulatory arbitrage opportunities against North American competitors facing extended EPA emissions certification timelines. Brazilian Mato Grosso soybean belt expansion offers the most penetrable geography for RTK-GPS-guided seeding systems. Go-to-market positioning through retrofit autonomy modules for existing tractor fleets bypasses capital-intensive full-stack development.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with telematics-platform convergence and predictive maintenance subscription unbundling. Long-term viability across the projection horizon favors acquisition targets with validated perception algorithms and established CE marking documentation. Watch for inflection signals in lithium-ion battery energy density breakthroughs that would unlock electric tractor duty-cycle economics.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 12100 Safety Certification Investment | CE marking validation accelerates European market entry against EPA-constrained competitors. |
| Telematics-Platform Convergence | Predictive maintenance subscriptions displace dealer-exclusive service revenue in Kansas and Nebraska. |
| Retrofit Autonomy Module Development | Capital-constrained Brazilian operators adopt supervised platforms for Mato Grosso expansion. |
| Electro-Hydraulic Supply Chain Integration | Backward control over German valve manufacturing insulates against Rhine logistics disruptions. |
| Computer Vision Perception Stack Acquisition | Validated obstacle-detection algorithms compress twelve-to-eighteen-month development timelines. |
Methodological Framework
Desk research of SEC 10-K filings, EU Machinery Directive implementation guidance, and EPA non-road engine certification databases preceded structured interviews with precision agriculture product managers, electro-hydraulic component procurement leads, and farm cooperative equipment directors. Primary fieldwork across Iowa, Illinois, and Mato Grosso validated autonomous tillage deployment patterns against secondary trade data from agricultural machinery customs records. Bottom-up equipment shipment analysis triangulated with top-down farm consolidation census data.
Variance decomposition across automation tier, control architecture, and geographic adoption pattern informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, perception technology maturity, end-user capital access tier, and application intensity. CAGRs were derived from equipment replacement cycle analysis and fleet penetration rate trajectories. Forecast inputs incorporated lithium-ion battery energy density improvement curves and ISO 12100 validation protocol evolution.
Decision-makers should treat outputs as directional under assumptions of continued farm consolidation and stable regulatory certification timelines; material deviation in battery chemistry breakthroughs or liability framework shifts would warrant model refresh. Recalibration cycles align with material shifts in EPA emissions standards and EU Machinery Directive enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Vietnam Combine Harvester Market