
 India Agricultural Machinery Market | 2026-2036
India Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
India Agricultural Machinery Market Outlook
The PLI scheme for farm machinery is expanding the cost-of-entry calculus for domestic manufacturers and foreign entrants alike. Mahindra & Mahindra Limited leverages its vertically integrated foundry-to-dealer network to dominate tractor sales across the Indo-Gangetic plain. Escorts Kubota Limited anchors its position through specialized harvester production for rice and wheat belts. TAFE Motors and Tractors Limited competes aggressively on price in the sub-40 HP segment where smallholder penetration remains deepest.
India agricultural machinery encompasses tractors, harvesters, tillage implements, and irrigation equipment rated by engine displacement, draft force, and field efficiency metrics, serving to replace manual and animal traction in crop production cycles. Tractors command the largest installed base and aftermarket parts revenue pool, while precision agriculture technologies represent the fastest-growing margin segment as IoT-enabled variable-rate application spreads. Harvesters retain structural importance in Punjab and Haryana where labor shortages during peak windows force mechanization timelines.
BIS certification mandates and the CEA's agricultural pump efficiency regulations shape product design and import eligibility for equipment sold in Indian territory. The PLI scheme's domestic value-add thresholds and DGFT's phased import restrictions on fully built tractors are redirecting capital toward local assembly and component sourcing. Stakeholders must monitor how state-level farm mechanization subsidies interact with central procurement targets to anticipate demand inflections across India's heterogeneous agro-climatic zones.
Market Dynamics
The PLI scheme's domestic value-add thresholds are redirecting capital toward local assembly and component sourcing, compressing import-dependent supply structures while accelerating indigenization timelines across tractor and harvester manufacturing.
Growth Catalysts
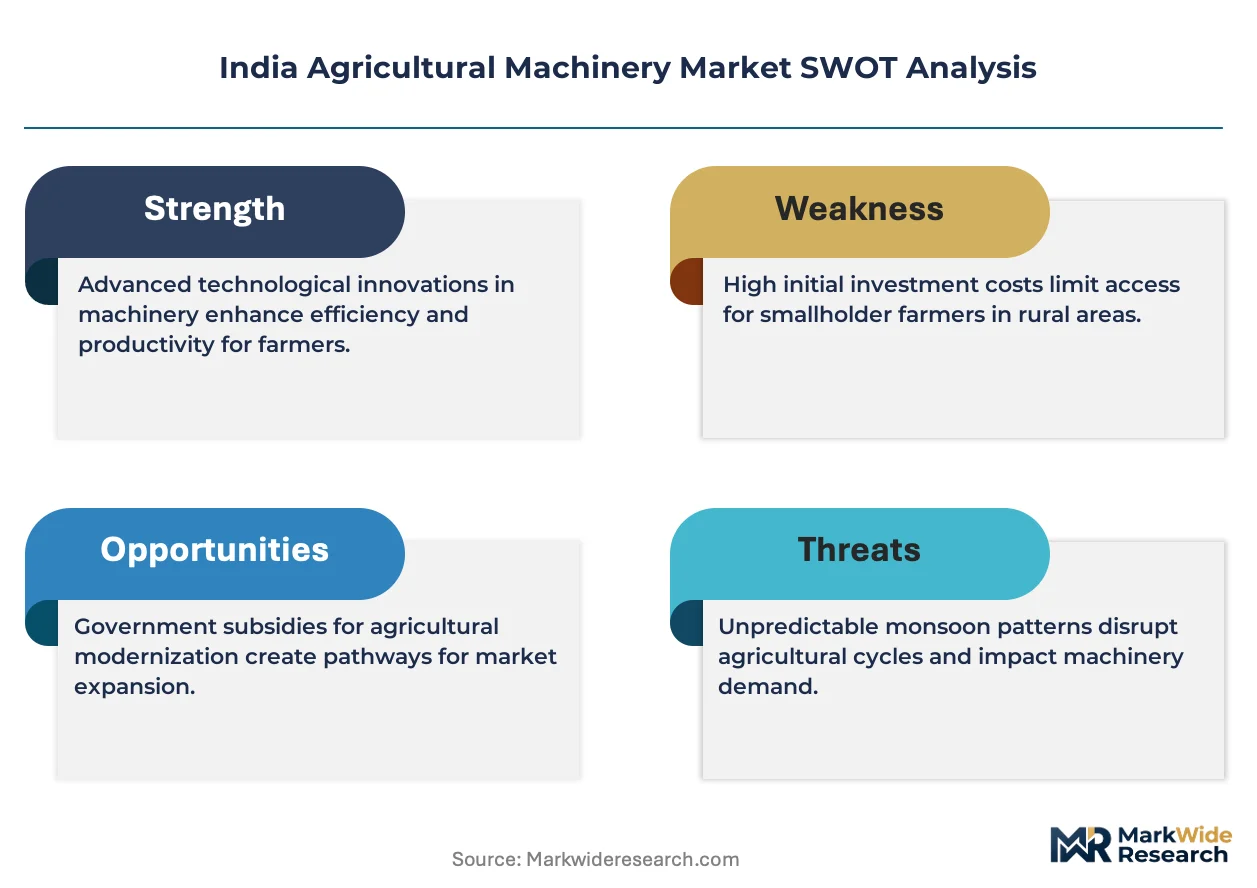
- Precision agriculture adoption:GPS-guided tractors and drone-based crop monitoring are penetrating Punjab's rice-wheat belt and Karnataka's commercial horticulture zones, displacing manual scouting methods.
- State-level mechanization subsidies:Maharashtra and Gujarat smallholders are upgrading to mechanized tillage equipment under combined central and state fiscal support programs.
- Labor shortage pressures:Peak-season agricultural labor scarcity in Punjab and Haryana is compressing mechanization timelines for harvester deployment.
Market Restraints
- Steel and alloy input volatility:Foundry-grade metal price fluctuations compress margin buffers for domestic tractor manufacturers dependent on commodity-linked component costs.
- BIS certification timelines:Bureau of Indian Standards testing protocols create extended product approval cycles that delay new equipment launches by 8-14 months.
- Animal traction persistence:Draft cattle and manual labor retain cost advantages in scattered landholding zones below two hectares, limiting addressable market expansion.
Strategic Opportunities
- Sub-40 HP segment depth:Smallholder penetration in eastern Uttar Pradesh and Bihar remains underdeveloped relative to western states, creating whitespace for price-optimized equipment lines.
- CEA pump efficiency mandates:Agricultural pump replacement cycles under central efficiency regulations are opening retrofit and upgrade revenue streams for irrigation equipment suppliers.
- IoT-enabled variable-rate application:Convergence of soil sensor networks with automated spreader controls is creating premium service attach rates in commercial farming zones.
Industry Challenges
- Certification compliance bandwidth:Simultaneous BIS, CEA, and state-level roadworthiness approvals strain regulatory affairs teams at equipment manufacturers.
- Dealer technician skill gaps:Diagnostic and repair capabilities for GPS-guided and telematics-integrated machinery lag behind hardware deployment rates in rural service networks.
- Spare parts inventory complexity:PLI-driven component localization is forcing reconfiguration of aftermarket supply chains originally optimized for imported part numbers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Agricultural Machinery Market |
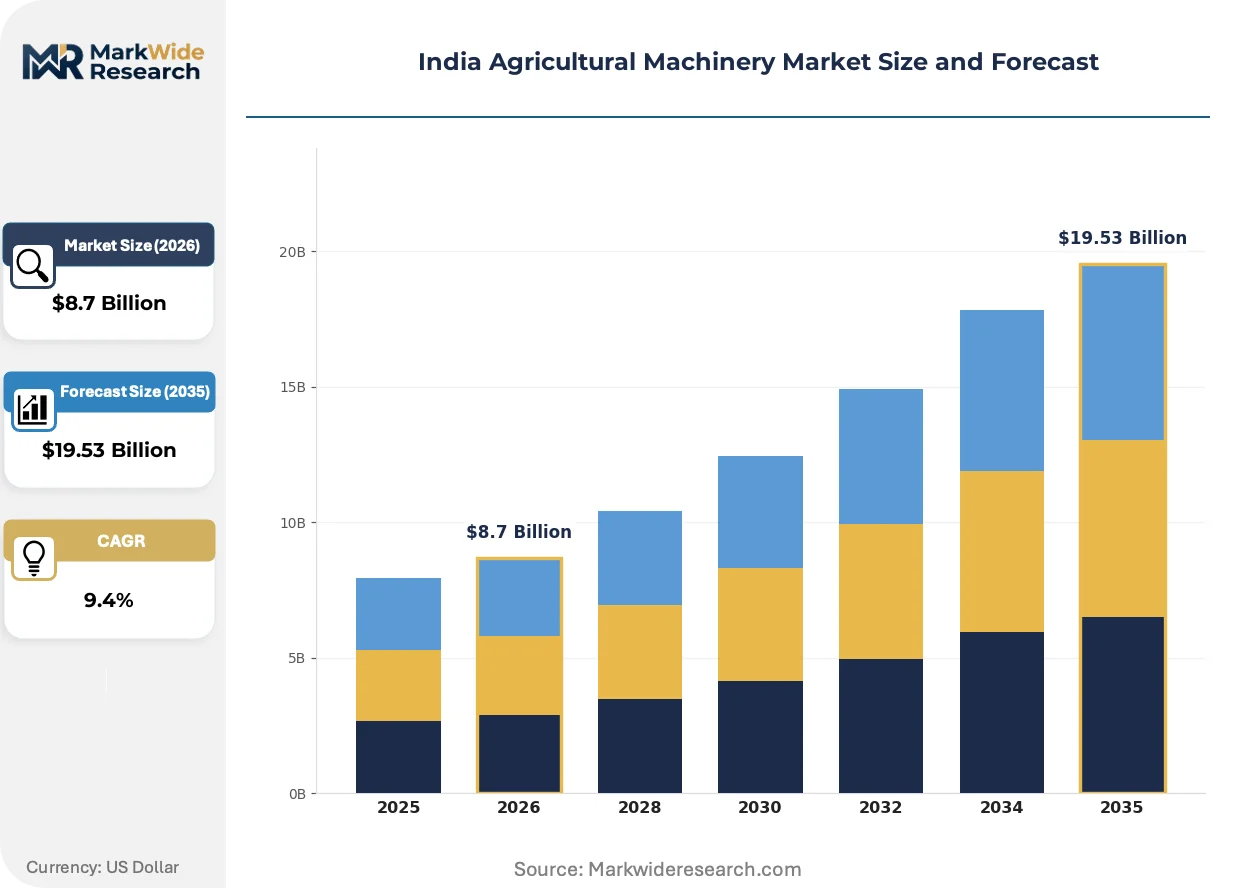
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plows, Seeders Technology: Automation, Precision Agriculture, IoT, Traditional End User: Farmers, Agricultural Cooperatives, Contractors, Government Application: Crop Cultivation, Soil Preparation, Irrigation, Harvesting |
| Companies Covered | Mahindra & Mahindra Limited, Escorts Kubota Limited, TAFE Motors and Tractors Limited, International Tractors Limited, CNH Industrial (India) Private Limited, VST Tillers Tractors Ltd., Deere & Company, AGCO Corporation, CLAAS KGaA mbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Agricultural Machinery Market Strategic Shifts
Mechanization intensity is bifurcating across India's agro-climatic zones, with precision technologies concentrating in commercial belts while basic equipment penetrates fragmented smallholdings.
Telematics-enabled fleet management is absorbing diagnostic and maintenance functions previously handled through dealer site visits. Large farming cooperatives in Punjab and Haryana are adopting subscription-based equipment monitoring at the fastest clip. This compression of service touchpoints is reshaping dealer economics and aftermarket revenue pools.
DGFT's phased import restrictions on fully built tractors are forcing foreign manufacturers to establish local assembly operations. The policy is accelerating technology transfer agreements and joint venture formations. Sub-40 HP and 40-75 HP segments are experiencing the most rapid localization of engine and transmission sourcing.
Smallholder equipment procurement is fragmenting across digital marketplaces, manufacturer direct channels, and traditional dealer networks. Younger farmers in Gujarat and Maharashtra are bypassing established dealers for online configuration and financing. This channel disintermediation is most pronounced in tractor purchases below 35 horsepower where specification complexity remains limited.
India Agricultural Machinery Market Segmentation
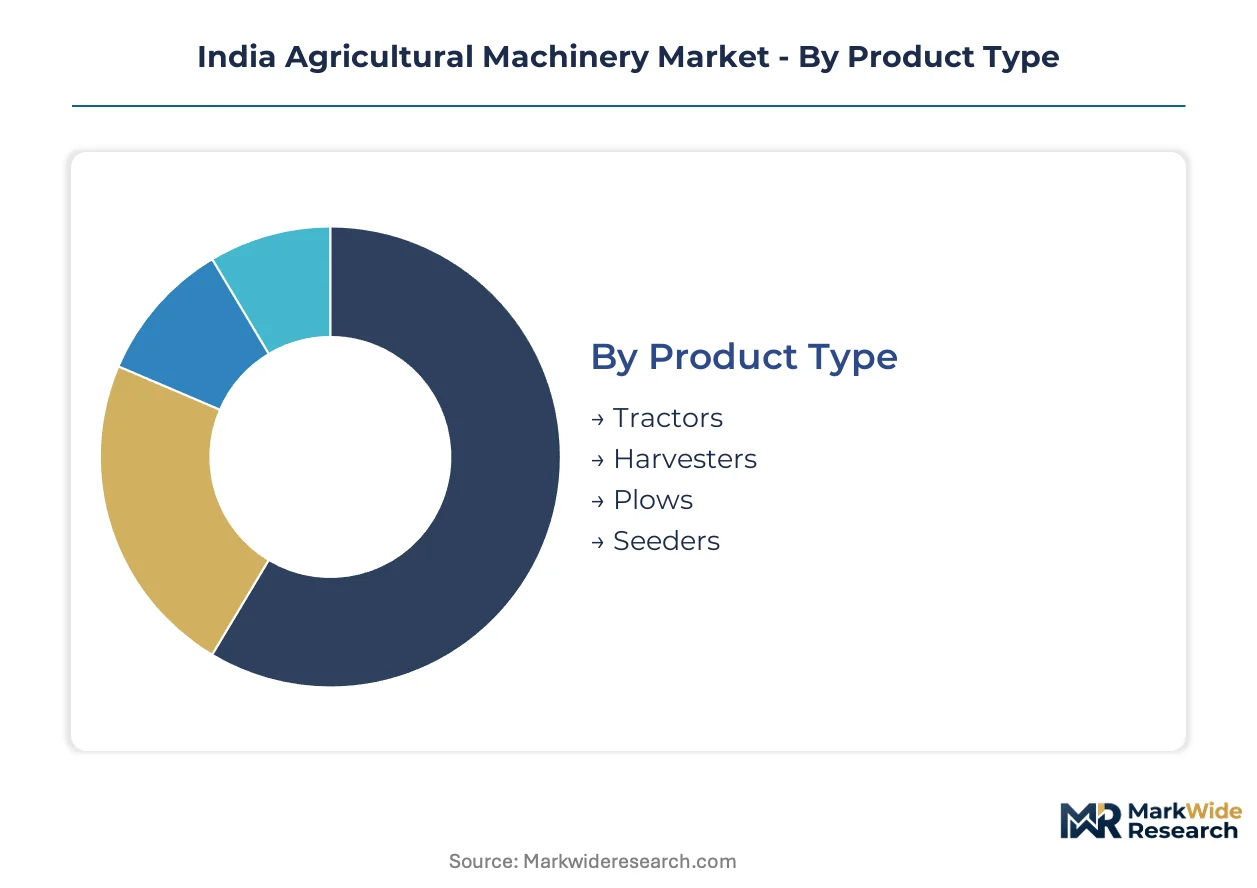
Equipment segmentation in India's agricultural machinery market reveals how capital deployment, labor substitution pressures, and subsidy eligibility criteria fragment procurement patterns across the country's heterogeneous farming systems. Understanding these divides allows suppliers to align product specifications with the operational constraints of distinct user archetypes.
Product Type:
Domestic manufacturing capacity concentrates disproportionately in power-mechanical equipment where foundry-to-assembly integration yields cost advantages, while implement production remains more geographically dispersed.
- Tractors:Engine-displacement categories from sub-20 HP to above 75 HP define specification tiers, with power take-off ratings and hydraulic lift capacity determining implement compatibility. Demand clusters in Punjab's rice-wheat belt and Maharashtra's sugarcane zones where consolidated landholdings justify ownership over rental.
- Harvesters:Self-propelled combines and tractor-mounted variants rated by grain tank capacity and cutting width address peak-season labor shortages. Procurement concentrates in Haryana and western Uttar Pradesh where wheat procurement windows compress mechanical timelines.
- Plows:Moldboard and disc configurations matched to soil type dominate tillage implement sales.
- Seeders:Zero-till and raised-bed planters penetrate conservation agriculture adoption zones.
Tractors absorb the bulk of installed capacity; harvesters are expanding most quickly.
Technology:
Technology tiering reflects a cost-maturity gradient where premium automation commands margin premiums in commercial belts while basic mechanization penetrates price-sensitive smallholder markets.
- Automation:Autosteer systems and implement control architectures reduce operator fatigue while improving field efficiency metrics. Deployment concentrates in Karnataka's commercial horticulture and Punjab's large cooperative farms where labor costs justify capital intensity.
- Precision Agriculture:Variable-rate application systems integrating soil sensors with spreader controls enable input optimization. Adoption clusters in Gujarat's cotton belt and Tamil Nadu's precision-irrigated vegetable production where input costs dominate margin calculations.
- IoT:Telematics-enabled fleet management and predictive maintenance protocols reshape dealer service economics.
- Traditional:Conventional mechanical systems without electronic integration retain dominance in sub-40 HP tractor segments and eastern state's fragmented landholdings.
Traditional equipment retains the deepest installed base; precision agriculture is climbing the fastest.
End User:
User-type segmentation tracks capital access gradients, with institutional procurement operating on multi-year replacement cycles distinct from individual farmer financing constraints.
- Farmers:Individual owner-operators ranging from marginal smallholders to commercial enterprises drive volume demand, with credit access and subsidy eligibility shaping specification choices. Maharashtra and Gujarat smallholders exhibit strongest upgrade momentum under combined central and state mechanization programs.
- Agricultural Cooperatives:Pooled procurement entities in Punjab and Haryana achieve scale economies in fleet purchases and maintenance contracts. These bodies prioritize interchangeability and parts commonality across equipment pools.
- Contractors:Service providers renting equipment by acre or hour operate on utilization-maximization models.
- Government:State agriculture departments and research stations procure demonstration fleets and extension equipment on budget-cycle timelines.
Farmers absorb the bulk of installed capacity; agricultural cooperatives are gaining share fastest.
Application:
Application segmentation aligns with crop calendar criticality, where harvesting window constraints command premium pricing power relative to less time-sensitive soil preparation operations.
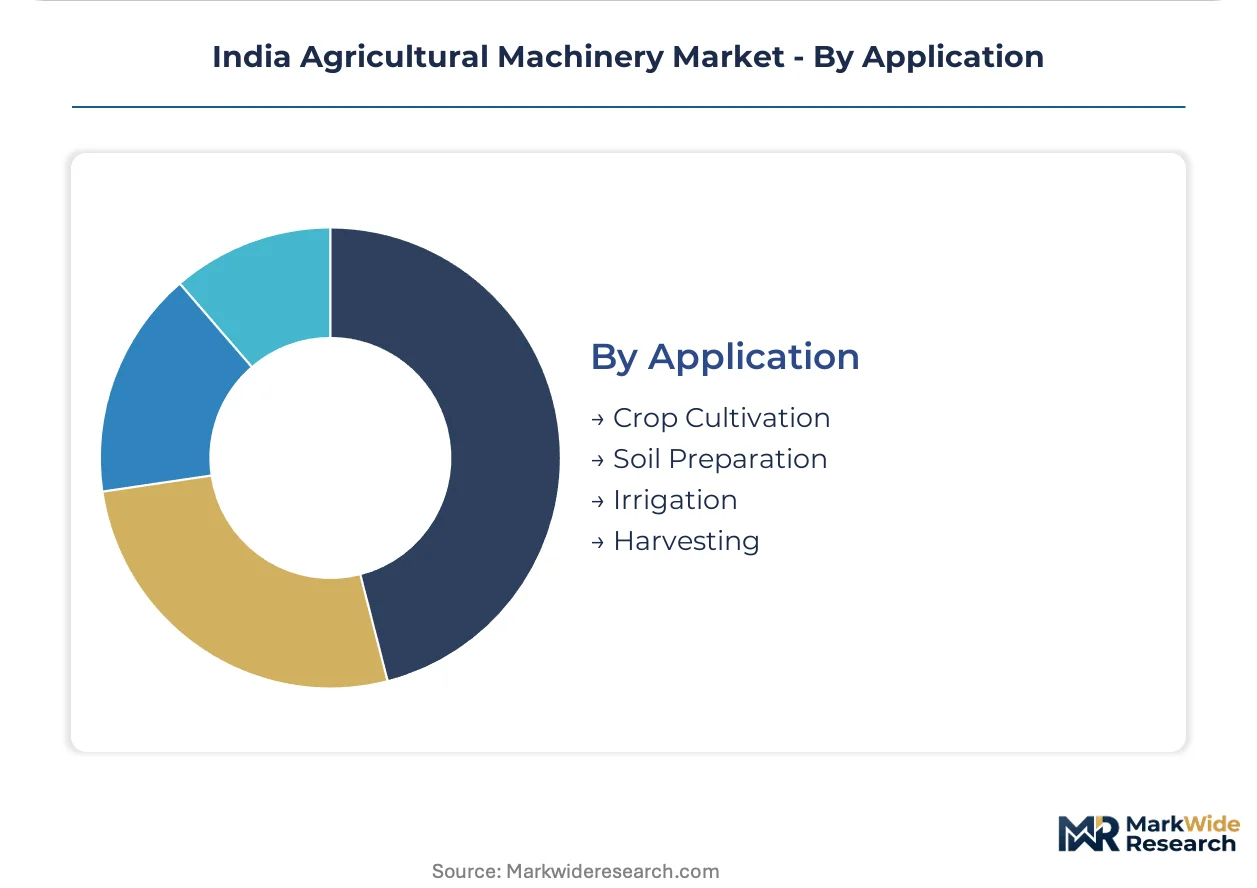
- Crop Cultivation:Planting and crop care equipment including transplanters, sprayers, and interculture tools address labor substitution during vegetative growth stages. Demand intensifies in rice-intensive eastern states where manual transplanting costs escalate.
- Soil Preparation:Tillage, leveling, and residue management implements establish seedbed conditions across diverse soil textures. Penetration remains deepest in western India's mechanized belts with eastern adoption accelerating under eastern Uttar Pradesh and Bihar subsidy programs.
- Irrigation:Pump sets, sprinklers, and drip system components respond to CEA efficiency mandates and groundwater depletion pressures.
- Harvesting:Grain, forage, and specialty crop collection equipment addresses peak-season labor scarcity.
Soil preparation absorbs the bulk of installed capacity; irrigation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level agricultural machinery subsidies and the PLI scheme's domestic value-add thresholds are concentrating capital deployment across India's heterogeneous agro-climatic zones, with western and northern states exhibiting deepest mechanization penetration.
Maharashtra
Sugarcane mechanization and horticulture expansion drive harvester and tractor demand in western Maharashtra's cooperative belt. The state's farm mechanization subsidy program layers atop central PLI incentives to reduce equipment acquisition costs for smallholders. Pune and Nashik districts host expanding dealer networks and component fabrication clusters serving the Deccan plateau.
Punjab
Peak-season labor shortages during wheat and rice procurement windows compress mechanization timelines for combine harvesters. State agricultural department procurement targets and central food grain procurement policies align to sustain fleet replacement cycles. Ludhiana and Jalandhar anchor northern India's densest tractor and harvester manufacturing corridor.
Gujarat
Cotton precision agriculture and groundnut mechanization propel GPS-guided tractor adoption in the Saurashtra peninsula. The state's integration with central PLI scheme disbursements accelerates smallholder upgrades to mechanized tillage equipment. Rajkot and Ahmedabad concentrate implement fabrication and precision technology assembly operations.
Karnataka
Commercial horticulture zones around Bengaluru and Mysuru drive demand for drip irrigation systems and precision spraying equipment. State-level micro-irrigation subsidies intersect with CEA pump efficiency mandates to accelerate equipment replacement cycles. The state's technology corridor attracts IoT-enabled variable-rate application system deployments.
Haryana
Wheat procurement logistics and labor migration patterns force rapid harvester deployment across the rice-wheat belt. State mechanization subsidies and central minimum support price operations sustain equipment utilization rates above national averages. Hisar and Karnal function as distribution hubs for Indo-Gangetic plain farming cooperatives.
India Agricultural Machinery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across India's agricultural machinery sector, creating a tiered structure where scale advantages in foundry-to-assembly integration clash with segment-specific technology depth. The market exhibits moderate consolidation at the tractor core, with fragmentation increasing in implements and precision agriculture peripherals. Three archetypes dominate: vertically integrated domestic champions with captive component supply, multinational assemblers navigating DGFT localization mandates, and regional specialists exploiting sub-40 HP price sensitivity. Competitive intensity centers on backward integration into engine and transmission sourcing, alongside dealer network density expansion in eastern underpenetrated districts.
Among domestic integrated manufacturers, Mahindra & Mahindra Limited and Escorts Kubota Limited exemplify contrasting scale-specialization strategies, while TAFE Motors and Tractors Limited occupies a position emphasizing sub-40 HP price competitiveness. These entities represent the indigenization thrust shaped by PLI domestic value-add thresholds and DGFT phased import restrictions on fully built tractors. Foreign multinationals including Deere & Company and CNH Industrial (India) Private Limited anchor the premium technology tier through local assembly operations and technology transfer agreements.
| Leading Market Players |
|---|
| Mahindra & Mahindra Limited |
| Escorts Kubota Limited |
| TAFE Motors and Tractors Limited |
| International Tractors Limited |
| CNH Industrial (India) Private Limited |
| VST Tillers Tractors Ltd. |
| Deere & Company |
| AGCO Corporation |
| CLAAS KGaA mbH |
| Others |
Value Chain & Pricing Dynamics
Family-owned foundry-to-assembly operations across Punjab and Maharashtra exercise pricing discipline through captive component sourcing, while PLI scheme disbursement timelines compress working capital cycles and force inventory-heavy financing structures on smaller tier-two fabricators.
Pricing Analysis
Short lead-time premiums attach to GPS-guided tractors and precision implements where BIS certification backlogs stretch delivery windows. Three-tier pricing structure separates premium autosteer-equipped models from standard mechanical configurations and economy sub-40 HP units. Cost compression in the economy tier is intensifying because foundry-grade steel input volatility erodes margin buffers for price-competitive assemblers. Agricultural cooperatives in Haryana and Punjab exhibit lowest price sensitivity due to pooled procurement scale, while marginal smallholders in eastern Uttar Pradesh and Bihar drive hardest bargain negotiations.
Supply Chain Analysis
BIS certification mandates and CEA pump efficiency regulations gate component eligibility, forcing foundry suppliers to maintain dual-qualified inventory streams. Manufacturing concentration centers on India, with engine and transmission sourcing increasingly localized under DGFT phased import restrictions. Supply chains draw from domestic steel foundries, hydraulic component fabricators, and electronics assembly clusters in Pune, Ludhiana, and Rajkot. Single-source vulnerability concentrates in high-precision GPS modules and telematics chipsets where import dependency persists. Distribution runs through manufacturer-direct channels, traditional dealer networks, and emerging digital marketplaces serving younger farmers in Gujarat and Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS certification timelines and PLI domestic value-add thresholds erect compliance moats that favor capitalized incumbents with dedicated regulatory affairs bandwidth over under-resourced regional assemblers.
For Market Incumbents: Anchor market position through backward integration into foundry operations and transmission casting facilities, eliminating margin leakage to commodity-linked component suppliers. Escalate certification investment to compress BIS approval cycles below competitor timelines. Defend against digital marketplace disintermediation by embedding financing and service contracts within direct channel offerings. For New Entrants and Emerging Players: Capture whitespace in eastern Uttar Pradesh and Bihar sub-40 HP segments where dealer network density remains thinnest and state subsidy penetration lags western benchmarks. Prioritize price-optimized equipment lines with simplified mechanical architectures that bypass telematics integration costs. Pursue cooperative procurement channel partnerships to achieve fleet-scale entry without individual farmer credit underwriting burdens. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier implement fabricators in Maharashtra and Gujarat facing working capital strain from PLI disbursement delays. Long-term viability hinges on localization depth and state subsidy relationship access. Monitor DGFT notification timing on tractor import restrictions as inflection signal for assembly capacity valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive steel casting capacity insulates margin buffers from commodity price swings affecting competitors. |
| CEA Pump Efficiency Certification | Regulatory compliance unlocks retrofit revenue streams under central irrigation equipment replacement mandates. |
| Telematics Platform Development | Fleet monitoring subscriptions reshape dealer economics in Punjab and Haryana cooperative segments. |
| Eastern State Dealer Network Expansion | First-mover density in Bihar and eastern Uttar Pradesh captures subsidy-accelerated smallholder upgrades. |
| Digital Marketplace Channel Launch | Direct online configuration and financing targets younger farmers bypassing traditional dealer relationships. |
Study Parameters
Document review covered BIS certification records, CEA efficiency compliance databases, and state agriculture department procurement circulars, complemented by interviews with tractor platform engineers, cooperative fleet managers, foundry operations directors, and aftermarket service heads. Secondary validation drew from DGFT trade notifications, PLI scheme disbursement reports, and customs import data on fully built tractors and precision agriculture components. Bottom-up equipment shipment tracking and top-down state subsidy allocation analysis were triangulated to establish market sizing.
Cross-referencing historical replacement cycle patterns against panel input from dealer network heads and agricultural cooperative procurement committees anchored the projection framework. Segmentation modeling spanned product type, technology tier, end-user archetype, and application across the analysis window. CAGRs were derived from fitted trend lines on mechanization intensity ratios and subsidy penetration curves. Forecast inputs incorporated labor migration patterns in Punjab and Haryana, groundwater depletion trajectories affecting pump replacement demand, and PLI localization threshold compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to state-level subsidy continuity and DGFT import restriction phase-in schedules. Forecasts reflect documented assumptions on subsidy disbursement velocity and certification backlog resolution. A model refresh is warranted upon material change in PLI scheme eligibility criteria or BIS testing protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Rotary Tiller Market
Agricultural Machinery
Mini Tractors Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
South America Agricultural Machinery Market