
 Industrial Shelling Machines Market | 2026-2036
Industrial Shelling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Shelling Machines Market Insights
A shortage of certified mechanical technicians is redrawing competitive boundaries across the industrial shelling machines sector. Buhler AG leverages its Swiss engineering heritage to sustain premium positioning in rotary sheller systems. Satake Corporation anchors Asian supply chains through deep rice and grain processing expertise. PETKUS Technologie GmbH competes on precision agriculture integration, while F. H. SCHULE Mühlenbau GmbH specializes in custom oilseed processing configurations.
Industrial shelling machines mechanically remove husks, pods, or outer layers from nuts, grains, and seeds using rotating drums, impact bars, or pneumatic pressure differentials, typically operating at throughput rates from 500 kg to 50 tons per hour depending on crop density and moisture content. These systems serve commercial agriculture and food manufacturing by delivering clean, intact kernels for downstream milling, pressing, or packaging operations. Continuous shellers dominate volume installations due to uninterrupted processing economics, while pneumatic technology segments capture expanding margin pools in delicate nut applications where kernel integrity commands premium pricing. Batch shellers retain relevance in specialty seed coating operations requiring precise lot control and traceability.
ISO 22000 food safety management and EU Machinery Directive 2006/42/EC shape equipment design protocols, forcing manufacturers to validate hygienic surface finishes and emergency stop architectures. The US FDA's Food Safety Modernization Act preventive controls extend compliance burdens to foreign shelling equipment exporters seeking American market access. Stakeholders must monitor evolving EU Green Deal carbon border adjustments and emerging battery-electric sheller prototypes that could disrupt established mechanical-pneumatic technology splits.
Market Dynamics
Food processing facilities across Southeast Asia are scaling automated shelling lines to reduce manual labor dependency, while REACH compliance in Europe and evolving FDA food-contact material rules in the US tighten equipment certification requirements. This dual pressure of automation economics and regulatory complexity is compressing vendor margins and favoring integrated solution providers over component specialists.
Growth Catalysts
- EU Green Deal carbon border adjustments:European processors face mounting pressure to document embodied emissions in imported shelling equipment, driving replacement cycles toward energy-efficient rotary drum systems certified under updated Machinery Directive protocols.
- Brazil's expanding soybean processing corridor:Commercial crushing facilities in Mato Grosso and Goiás states are installing high-throughput pneumatic shellers to handle rising export volumes destined for Chinese and European oilseed markets.
- Continuous shelling technology:Uninterrupted processing economics favor drum-and-bar configurations over batch systems in volume nut and grain applications, particularly where kernel integrity commands downstream premiums.
Market Restraints
- Stainless steel input volatility:Hygienic surface finish requirements under ISO 22000 force manufacturers to absorb 304 and 316-grade steel price swings, compressing margins on mid-range equipment lines.
- Certified mechanical technician scarcity:Maintenance and commissioning expertise concentrates in Swiss and German engineering clusters, limiting service reach in emerging processing markets.
- Legacy pneumatic system lock-in:Established nut processors in California's Central Valley face high switching costs when retrofitting delicate-shell lines, slowing adoption of next-generation impact-bar designs.
Strategic Opportunities
- India's groundnut belt mechanization:Gujarat and Andhra Pradesh processing cooperatives present untapped demand for semi-automated shellers bridging manual and fully automated throughput tiers.
- Battery-electric sheller prototypes:Early-stage electrification of pneumatic pressure differential systems offers pathway to zero-emission operations in carbon-intensive oilseed corridors.
- Specialty seed coating traceability:Batch sheller configurations with integrated lot-control software capture premium positioning in hybrid seed production where genetic purity documentation is mandatory.
Industry Challenges
- ISO 22000 and EU Machinery Directive validation timelines:Concurrent hygienic design and safety architecture certifications extend equipment launch cycles by 8-14 months, straining R&D amortization.
- Legacy system integration complexity:Retrofitting continuous shellers into existing grain handling infrastructure requires custom feed-and-conveyance engineering that erodes standardization economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Shelling Machines Market |
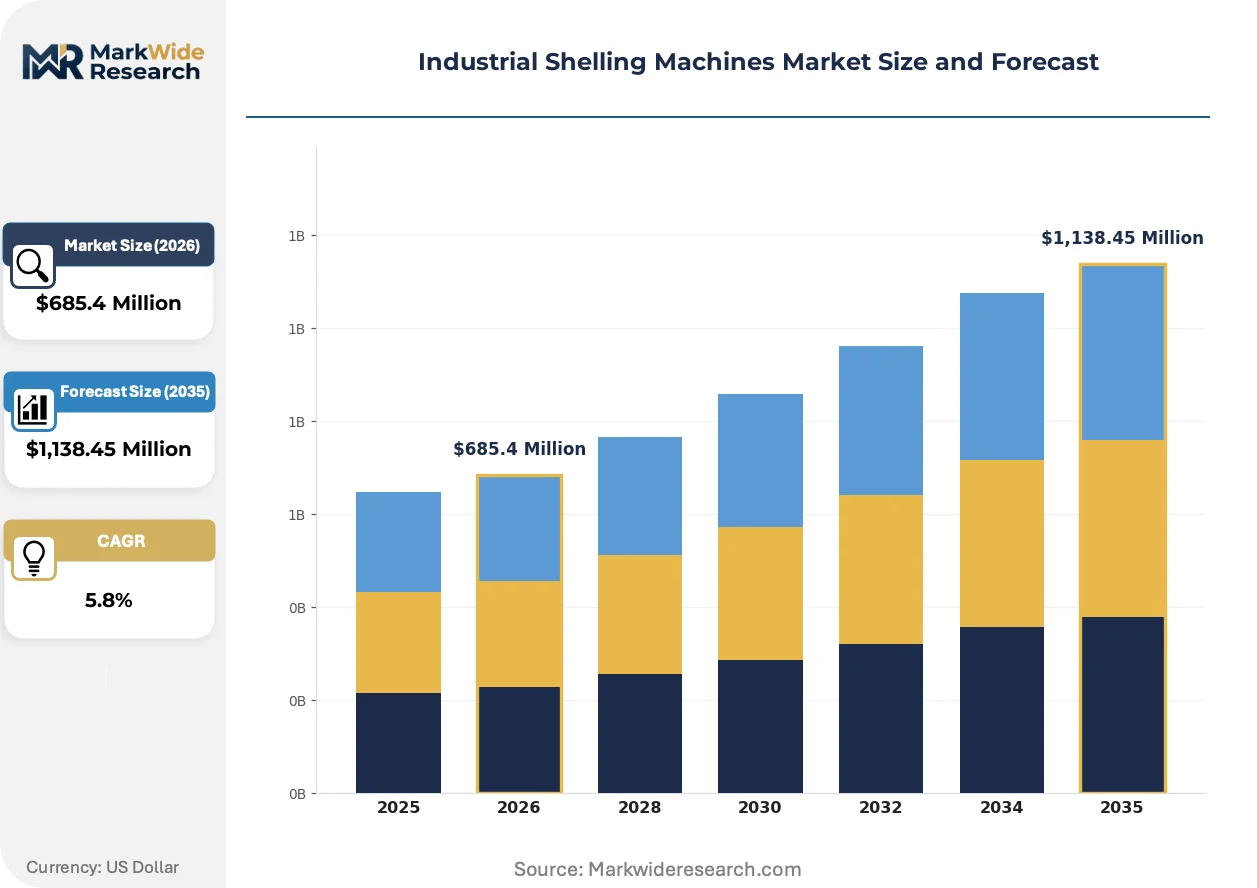
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Shellers, Hammer Mill, Batch Shellers, Continuous Shellers End User: Agriculture, Food Processing, Manufacturing, Packaging Technology: Mechanical, Pneumatic, Hydraulic, Electric Application: Nut Processing, Grain Shelling, Seed Coating, Feed Production |
| Companies Covered | Buhler AG, Satake Corporation, PETKUS Technologie GmbH, F. H. SCHULE Mühlenbau GmbH, Bratney Companies, John Deere, Lewis M. Carter Manufacturing, TABANLI Machinery, Tecnoceam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Shelling Machines Market Trends and Innovations
Automation architectures and regulatory compliance frameworks are actively restructuring competitive positioning across the industrial shelling machines sector. Equipment vendors must now engineer for simultaneous food safety validation, carbon footprint disclosure, and kernel-quality preservation.
Sensor-integrated shelling systems is bifurcating the technology landscape. Real-time moisture detection and kernel-damage monitoring enable processors to adjust drum speed and pneumatic pressure dynamically. Large-scale soybean and almond operations in Brazil and California are adopting these configurations fastest. The technology is bifurcating vendor tiers into precision-agriculture-integrated suppliers versus mechanical-only equipment makers.
REACH substance restrictions and evolving FDA food-contact notifications are reshaping material selection protocols. Equipment manufacturers must now validate that all polymer seals, lubricants, and surface coatings meet migrating-substance thresholds for direct food contact. Pneumatic sheller segments serving delicate nut applications face the steepest compliance burdens, with European vendors leading certification documentation.
Service unbundling is altering procurement patterns among mid-scale processors. Buyers increasingly separate equipment acquisition from installation, commissioning, and multi-year maintenance contracts, treating shelling lines as capital assets rather than turnkey solutions. This fragmentation is most pronounced in India's groundnut processing sector, where regional fabricators compete on initial price while specialized technicians command premium call-out fees.
Industrial Shelling Machines Market Segmentation
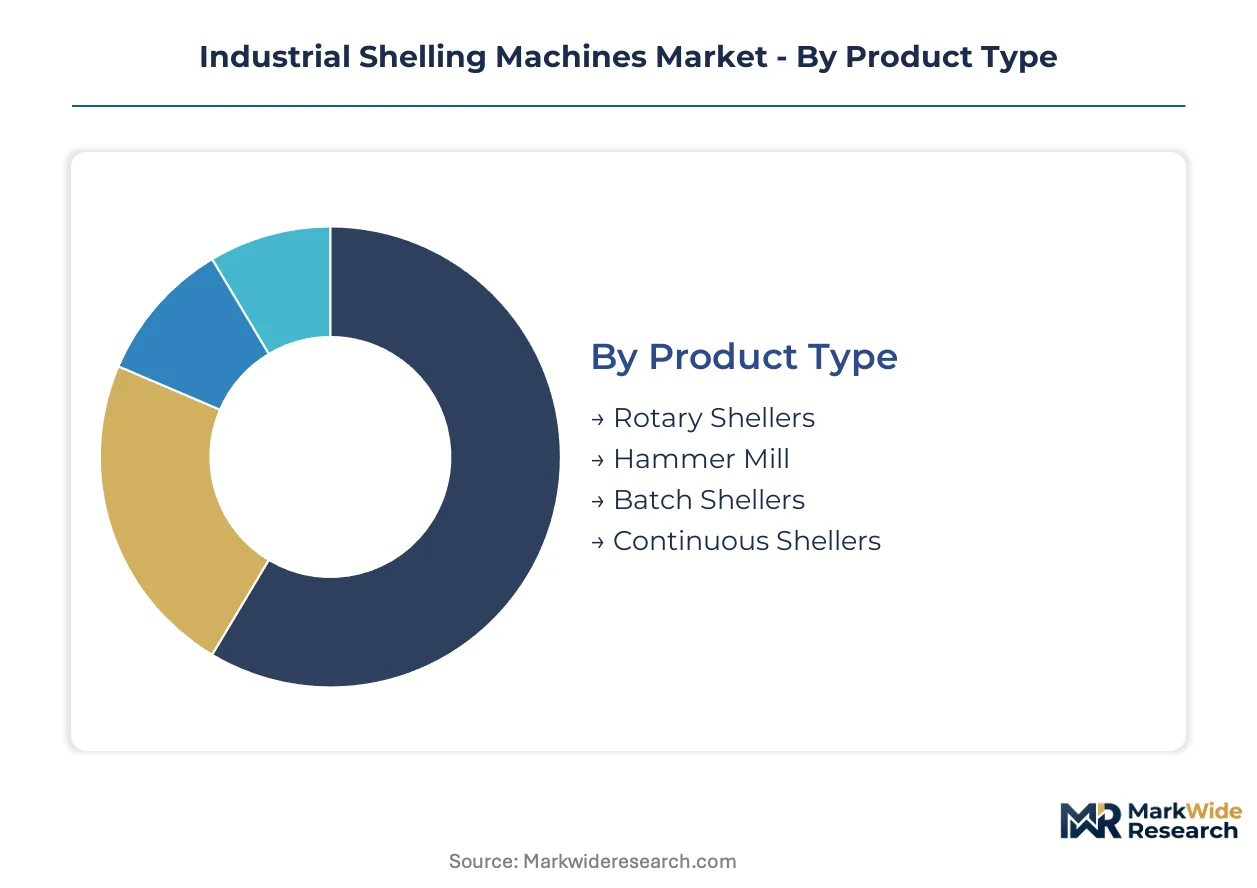
Equipment configuration choices in industrial shelling machines determine capital recovery timelines and kernel recovery rates. Segmentation reveals where pneumatic precision commands premium positioning against mechanical volume plays, and which end-use verticals drive replacement cycles.
Product Type:
Rotary shellers face substitution pressure from continuous-flow configurations in high-throughput oilseed corridors, while batch systems defend specialty positions where lot integrity overrides speed economics.
- Rotary Shellers:Drum-and-bar configurations dominate soybean and groundnut processing with throughput rates scaling from 2 to 50 tons per hour. Brazilian crushing facilities in Mato Grosso anchor demand as export volumes to Chinese markets climb. Kernel integrity specifications from European oilseed buyers drive specification upgrades.
- Continuous Shellers:Uninterrupted feed systems eliminate batch-changeover downtime, delivering superior economics in almond and walnut operations across California's Central Valley. Pneumatic integration options expand margin capture in delicate-shell applications where fracture rates determine downstream pricing tiers.
- Hammer Mill:Impact-based fragmentation serves feed production and oilseed preprocessing where kernel preservation is secondary to throughput velocity.
- Batch Shellers:Lot-controlled configurations retain mandatory positioning in hybrid seed coating operations requiring genetic traceability documentation.
Continuous shellers retain volume leadership; batch shellers hold the steepest expansion curve in specialty seed segments.
End User:
Customer scale and technical sophistication stratify procurement patterns, with integrated food manufacturers demanding predictive maintenance integration while agricultural cooperatives prioritize capital efficiency.
- Food Processing:Automated shelling lines in Southeast Asian facilities reduce manual labor dependency while meeting ISO 22000 hygiene protocols for export-ready nut and grain products. REACH compliance documentation requirements from European buyers extend equipment validation timelines.
- Agriculture:Primary producers and cooperatives in India's Gujarat groundnut belt drive semi-automated tier demand, bridging manual labor and fully capital-intensive installations.
- Manufacturing:Industrial ingredient suppliers integrate shelling stages into continuous process trains for oil extraction and flour milling operations.
- Packaging:Final-stage handlers require shelling-to-bagging integration with minimal kernel handling to preserve cosmetic grade specifications.
Food processing commands the dominant revenue share; agriculture presents the most rapid adoption acceleration in mechanizing regions.
Technology:
Power transmission architecture determines maintenance intervals, energy intensity, and suitability for moisture-variable feedstocks across climate-diverse growing regions.
- Pneumatic:Pressure-differential systems preserve kernel integrity in pistachio and macadamia applications where fracture rates directly impact commodity grading. California processors retrofit legacy lines to meet export market cosmetic standards.
- Mechanical:Direct-drive drum configurations dominate cost-sensitive grain corridors with proven durability in abrasive, high-silica feedstocks common in Brazilian soybean operations.
- Hydraulic:Variable torque systems accommodate density fluctuations in mixed nut streams without mechanical adjustment shutdowns.
- Electric:Servo-controlled precision shelling emerges in battery-electric prototypes targeting zero-emission processing commitments under EU Green Deal carbon border adjustments.
Mechanical systems anchor installed base volume; electric configurations are gaining share fastest in sustainability-mandated European markets.
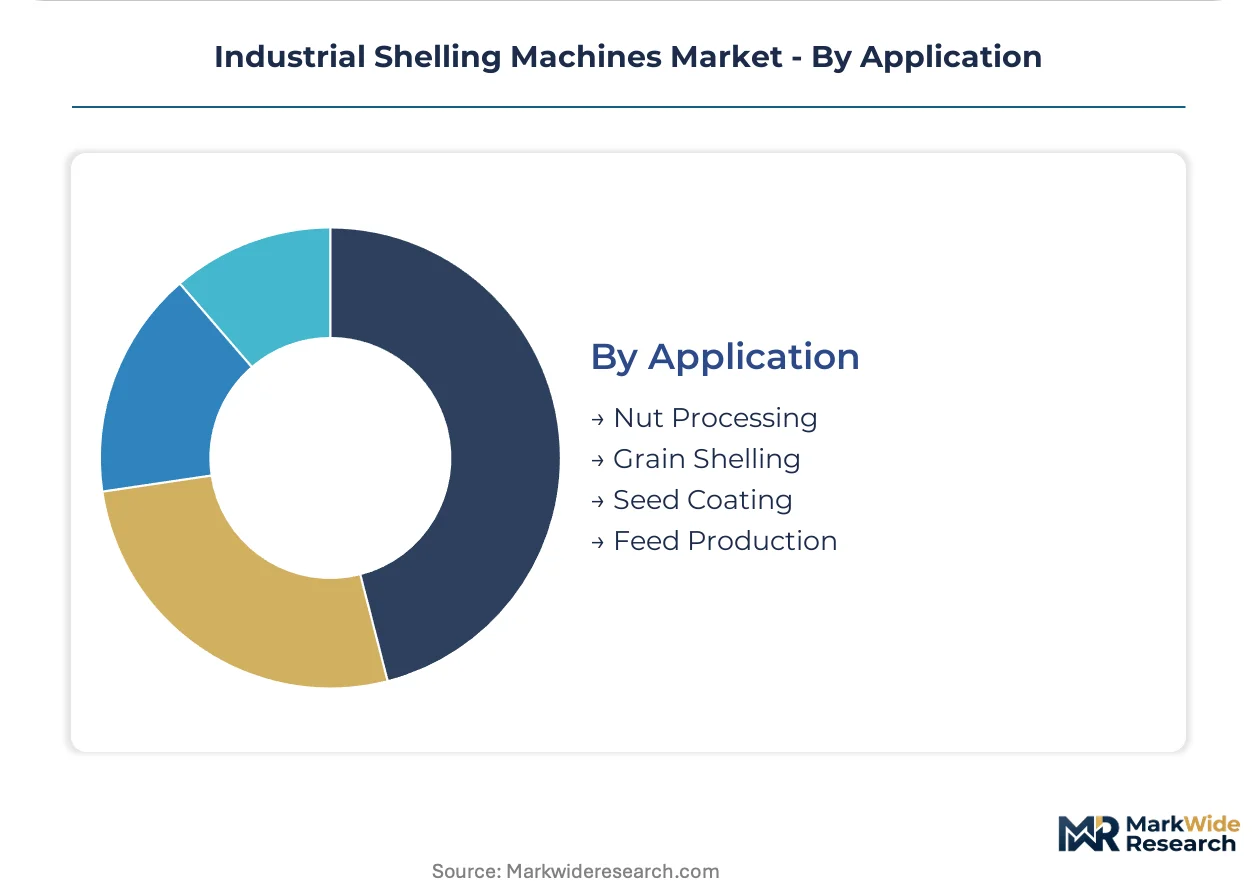
Application:
Downstream product specifications dictate shelling intensity, cleaning stage integration, and contamination tolerance thresholds that segment equipment performance requirements.
- Nut Processing:Delicate-shell almonds, pistachios, and macadamias require pneumatic or low-impact mechanical systems with real-time damage monitoring. California and Australian operations lead sensor-integrated adoption for premium export grades.
- Grain Shelling:High-volume rice and oat processing favors continuous rotary configurations with automated husk separation and pneumatic conveying integration.
- Seed Coating:Genetic purity mandates drive batch-controlled shelling with integrated lot-tracking software in hybrid corn and soybean seed production.
- Feed Production:Cost-minimized hammer mill and impact-bar systems prioritize throughput over kernel preservation for livestock and aquaculture ingredient streams.
Grain shelling retains volume leadership; nut processing maintains the premium pricing tier and technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian processors deploy pneumatic systems for export-grade soybean hulling, while Indian cooperatives favor semi-automated rotary units bridging manual labor gaps. European buyers mandate carbon documentation and REACH-compliant surface finishes, reshaping procurement specifications across origin markets.
United States
California's Central Valley almond and walnut processors drive sensor-integrated pneumatic retrofits to meet cosmetic grading standards for Asian and European export markets. FDA Food Safety Modernization Act preventive controls extend compliance burdens to foreign equipment vendors. Sacramento-Fresno corridor facilities concentrate capital investment in continuous-flow configurations with real-time kernel damage monitoring.
Brazil
Mato Grosso and Goiás soybean crushing corridors install high-throughput pneumatic shellers to handle rising export volumes destined for Chinese oilseed markets. ANVISA food-contact material notifications govern polymer seal and lubricant selection in equipment imports. Rondonópolis industrial cluster anchors South American processing capacity expansion with integrated drying-to-shelling process trains.
Germany
Engineering-intensive rotary drum manufacturers supply EU Green Deal carbon border adjustment documentation for energy-efficient equipment exports. EU Machinery Directive 2006/42/EC and REACH substance restrictions shape hygienic design validation protocols. Baden-Württemberg precision engineering clusters concentrate maintenance technician training programs addressing certified labor scarcity.
India
Gujarat and Andhra Pradesh groundnut processing cooperatives present untapped demand for semi-automated shellers bridging manual and fully automated throughput tiers. FSSAI food safety management system requirements and BIS equipment standards govern import and domestic manufacturing specifications. Rajkot-Surat industrial belt regional fabricators compete on initial capital cost while specialized technicians command premium service fees.
China
Domestic oilseed processors scale automated shelling lines to reduce labor dependency in soybean and rapeseed corridors serving internal edible oil demand. GB standards and SAMR food-contact material rules tighten equipment certification for both domestic production and export manufacturing. Yangtze River Delta machinery manufacturing clusters concentrate mid-range equipment production for Southeast Asian and African markets.
Industrial Shelling Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in industrial shelling machines. Swiss and German engineering heritage sustains premium positioning in precision rotary systems, while Asian fabricators capture mid-range volume through cost-efficient manufacturing. The competitive landscape stratifies into three archetypes: integrated solution providers with full process train capabilities, precision agriculture technology integrators, and regional component specialists. Dominant competitive moves include backward integration into sensor and control systems and geographic expansion through distribution partnerships in mechanizing agricultural belts.
Within the premium engineering tier, Buhler AG and Satake Corporation exemplify divergent geographic anchoring strategies. Buhler AG, a Swiss AG, represents European precision manufacturing heritage in food processing equipment. Satake Corporation, a Japanese entity, occupies a position bridging Asian supply chain integration with global grain processing expertise. Among German GmbH specialists, PETKUS Technologie GmbH and F. H. SCHULE Mühlenbau GmbH sit within the precision agriculture and custom oilseed configuration segments respectively, illustrating how national industrial specialization fragments competitive positioning even within contiguous European markets.
| Leading Market Players |
|---|
| Buhler AG |
| Satake Corporation |
| PETKUS Technologie GmbH |
| F. H. SCHULE Mühlenbau GmbH |
| Bratney Companies |
| John Deere |
| Lewis M. Carter Manufacturing |
| TABANLI Machinery |
| Tecnoceam |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Brazilian soybean processors and German equipment manufacturers lock in supply access for rotary drum systems while fixing price visibility against 304-grade stainless steel volatility. These arrangements insulate buyers from spot market swings in hygienic surface finish materials mandated by ISO 22000 and EU Machinery Directive protocols.
Pricing Analysis
Project-based pricing dominates capital-intensive shelling line procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by certification grade and after-sales service bundling. Price differentiation hinges on REACH compliance documentation and EU Green Deal carbon border adjustment certification. Cost compression in mid-range equipment lines is intensifying because Indian regional fabricators compete aggressively on initial capital outlay. Agricultural cooperatives in Gujarat and Andhra Pradesh exhibit highest price sensitivity, while integrated food manufacturers in California's Central Valley prioritize kernel integrity specifications over unit economics.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam elevates inbound logistics costs for precision-engineered components sourced from Baden-Württemberg manufacturing clusters. Supply concentration centers on Germany, Switzerland, and Japan for high-precision rotary systems, while China feeds mid-range equipment assembly. Component sourcing draws from 304 and 316-grade stainless steel mills, polymer seal manufacturers, and servo motor suppliers. Single-source vulnerability in certified mechanical technician training programs limits service reach. Distribution runs through OEM-direct channels for premium tiers and regional distributor networks for semi-automated configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Southeast Asian integrated food processors scaling automated shelling lines, fragmenting procurement leverage previously held by component specialists.
For Market Incumbents: Fortify service architecture by capturing certified technician training programs in Baden-Württemberg and expanding backward integration into sensor and control systems. Battery-electric sheller prototypes from emerging competitors threaten mechanical-pneumatic technology splits. Certification investment in EU Green Deal carbon documentation defends premium positioning against Asian cost competitors. For New Entrants and Emerging Players: Aftermarket service unbundling in India's groundnut belt represents the most penetrable white-space target, where regional fabricators under-deliver on commissioning and multi-year maintenance. Target semi-automated throughput tiers bridging manual labor gaps in Gujarat and Andhra Pradesh processing cooperatives. Lead with predictive maintenance integration as the go-to-market angle to differentiate from price-focused incumbents. For Investors and Strategic Acquirers: Precision agriculture technology integrators with sensor-embedded shelling capabilities offer the strongest acquisition target archetype for capturing margin expansion in nut processing applications. Long-term viability rests on electrification pathways and carbon border adjustment compliance across the analysis window. Monitor battery-electric sheller prototype commercialization as the inflection indicator for technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Systems | Captures predictive maintenance revenue streams from California almond processors. |
| EU Green Deal Certification Program | Unlocks carbon border adjustment-compliant exports to Mato Grosso crushing facilities. |
| Regional Service Partnership | Addresses certified technician scarcity in India's Rajkot-Surat industrial belt. |
| Batch Sheller Software Development | Secures genetic traceability positioning in hybrid seed coating operations. |
| Battery-Electric Prototype Scale-Up | Targets zero-emission commitments under EU Machinery Directive protocols. |
Research Methodology
The analysis maps rotary, continuous, and batch sheller configurations, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation from customs/trade data, SEC 10-K filings, ISO certification databases, and EU Machinery Directive registration records. Bottom-up equipment shipment tallies and top-down food processing capacity expansion estimates provide triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user scale, technology architecture, and application intensity. CAGRs derived from equipment replacement cycle analysis and regional mechanization penetration curves. Forecast inputs incorporate REACH substance restriction timelines and FDA food-contact material rule evolution.
Forecasts assume regulatory continuity in EU Green Deal implementation and FDA preventive controls enforcement; material policy shifts would require re-modeling. Stainless steel price volatility and certified technician availability represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
India Rice Milling Market