
 Japan Agricultural Machinery Market | 2026-2036
Japan Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Agricultural Machinery Market Foresight
Smallholder cooperatives is unwinding the historical dominance of individual farmers in equipment procurement. Kubota Corporation leverages its integrated engine-manufacturing footprint to dominate compact tractor supply across Japan's rice belt. Yanmar Company Limited anchors the precision agriculture segment through autonomous navigation platforms developed for narrow-field operations. Iseki & Co., Ltd. specializes in ultra-compact machinery calibrated for terraced slopes in western Japan's mountainous prefectures.
Japan agricultural machinery encompasses self-propelled and towed equipment engineered for soil preparation, crop cultivation, and harvest operations, typically featuring diesel or electric powertrains rated between 15 and 300 horsepower, with precision variants integrating real-time kinematic GPS guidance and variable-rate application controllers. Tractors occupy the largest installed base, though harvesters command premium pricing due to seasonal utilization constraints and technical complexity in rice-specific threshing mechanisms. GPS-enabled technology segments are expanding fastest as METI subsidies defray retrofit costs, while diesel-dominant fleets face gradual displacement under Japan's carbon neutrality roadmap for 2050.
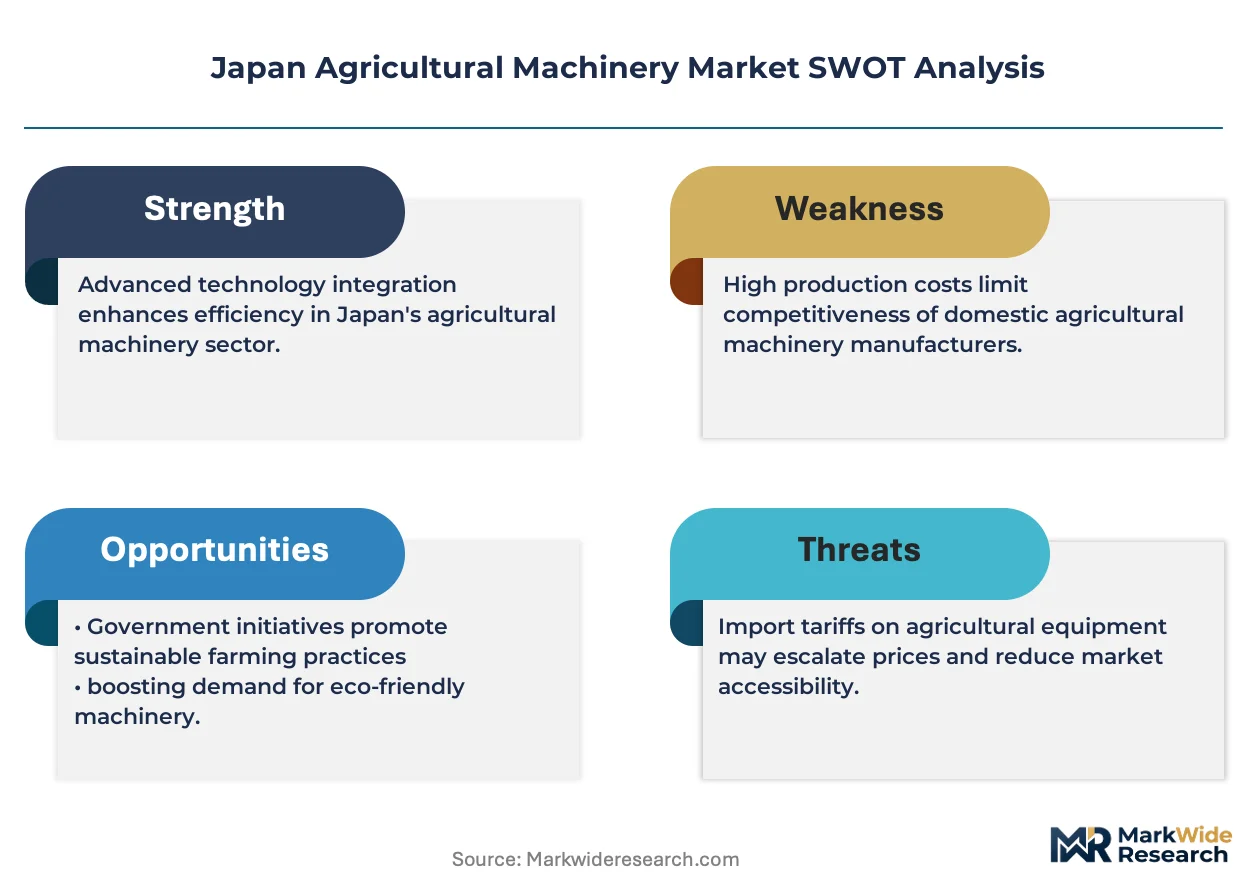
METI's Smart Agriculture promotion framework and JIS standards for autonomous machinery safety jointly determine product certification pathways and subsidy eligibility for domestic manufacturers. The Farm Land Act and regional agricultural committees shape cooperative purchasing power and fleet consolidation patterns across prefectural boundaries. Stakeholders must monitor the pace of subsidy phase-down for conventional diesel equipment against the readiness of battery-electric platforms for Japan's humidity-intensive operating environments.
Market Dynamics
METI's subsidy framework for precision agriculture equipment is redirecting capital flows from conventional diesel fleets toward autonomous navigation platforms, compressing replacement cycles across Japan's aging rural workforce.
Growth Catalysts
- Smart Agriculture subsidies:METI's financial support for GPS-enabled retrofit kits accelerates cooperative procurement in Hokkaido's grain belt.
- Hokkaido mechanization:Large-scale farming cooperatives in northern Japan expand fleet consolidation to offset labor shortages.
- Real-time kinematic guidance:Variable-rate application controllers reduce input waste for Kyushu's intensive vegetable producers.
Market Restraints
- Steel and semiconductor input costs:Volatility in powertrain components squeezes margins on compact tractor manufacturing.
- Battery-electric technical limitations:Humidity-intensive operating environments degrade lithium-ion performance in western Japan's terraced prefectures.
- JIS certification timelines:Autonomous machinery safety standards create extended approval bottlenecks for domestic manufacturers.
Strategic Opportunities
- Kyushu precision penetration:Intensive vegetable zones remain underpenetrated for variable-rate spraying technology.
- Cooperative fleet-as-a-service:Shared equipment pools reduce capital barriers for smallholders in Shikoku's fragmented landholdings.
- Carbon neutrality roadmap:METI's 2050 targets create regulatory tailwind for hydrogen fuel cell prototypes in heavy harvester segments.
Industry Challenges
- Autonomous systems integration:Retrofitting legacy diesel tractors with GPS guidance requires specialized technician training scarce in rural Tohoku.
- Interoperability standardization delays:Proprietary data protocols between Yanmar, Kubota, and Iseki fleets block seamless cooperative equipment sharing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Agricultural Machinery Market |
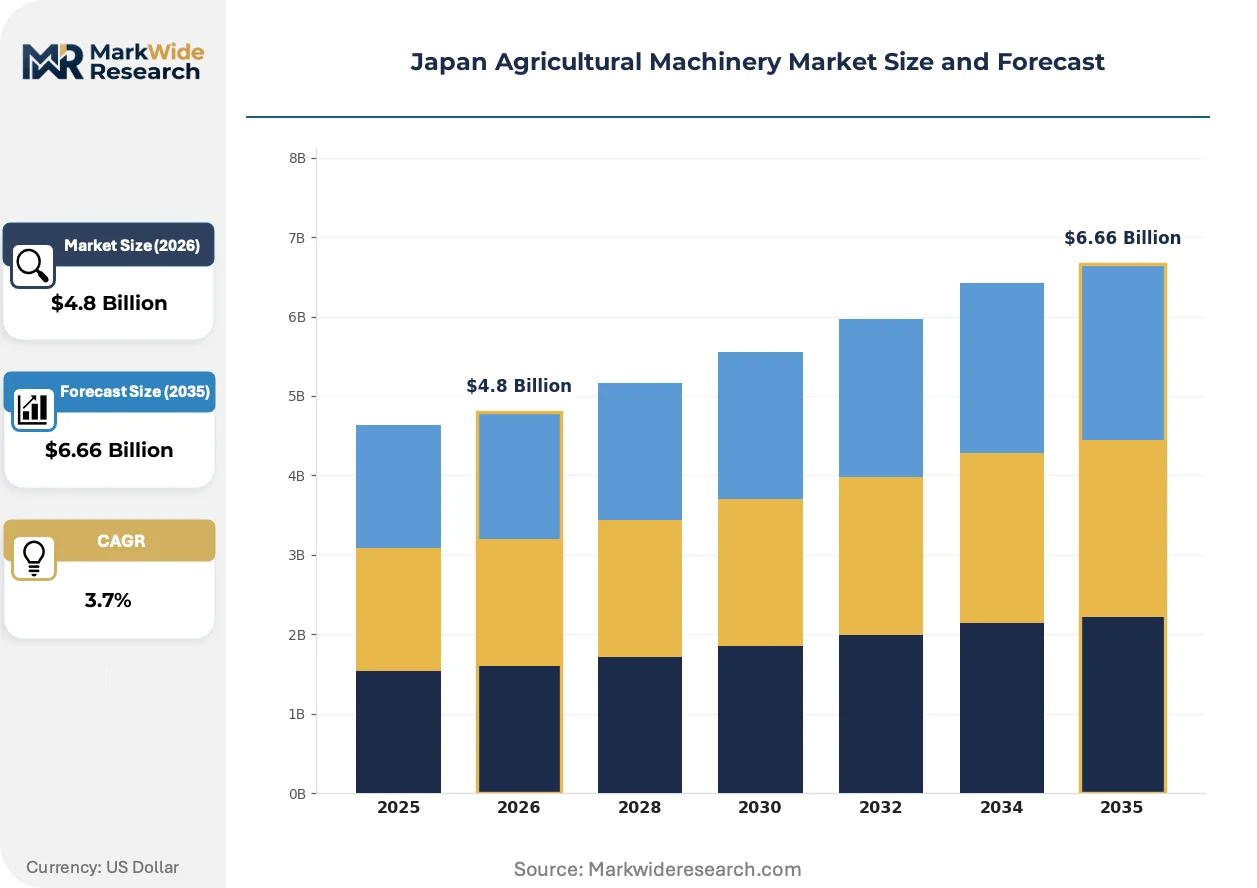
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Plows, Seeders Technology: GPS, IoT, Automation, Diesel End User: Farmers, Cooperatives, Agricultural Companies, Research Institutions Distribution Channel: Direct Sales, Dealers, Online Retail, Auctions |
| Companies Covered | Komatsu Ltd, Maruyama Mfg. Co., Inc., Kubota Corporation, Mitsubishi Mahindra Agricultural Machinery, Toyota Industries Corporation, Yanmar Company Limited, Hitachi Construction Machinery Co. Ltd, Kukje Machinery Company Limited, Iseki & Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Agricultural Machinery Market Shifts & Advancements
Electrification and autonomy are converging to redefine equipment specifications across Japan's topographically diverse farming regions, with subsidy eligibility increasingly tied to precision-enabled performance metrics.
Autonomous navigation platforms integrating real-time kinematic GPS guidance are displacing manual steering systems in compact tractor segments. Agricultural cooperatives in Hokkaido and Kyushu adopt these platforms at accelerating rates as METI subsidies defray retrofit costs. This displacement compresses the operational relevance of conventional mechanical control systems in medium-horsepower categories.
METI's Smart Agriculture promotion framework mandates interoperability standards for autonomous machinery safety certification under JIS guidelines. Domestic manufacturers must demonstrate collision-avoidance protocols and remote monitoring capabilities to qualify for procurement subsidies. Rice-specific threshing equipment faces the steepest compliance adjustments due to complex field geometries and seasonal density variations.
Equipment leasing through agricultural cooperatives is displacing individual farmer ownership in western Japan's mountainous prefectures. Smallholders in Shikoku and Chugoku regions access ultra-compact machinery through shared pools rather than capital purchase. This shift concentrates fleet management expertise within cooperative administrative structures and reduces manufacturer exposure to fragmented retail servicing networks.
Japan Agricultural Machinery Market Segmentation
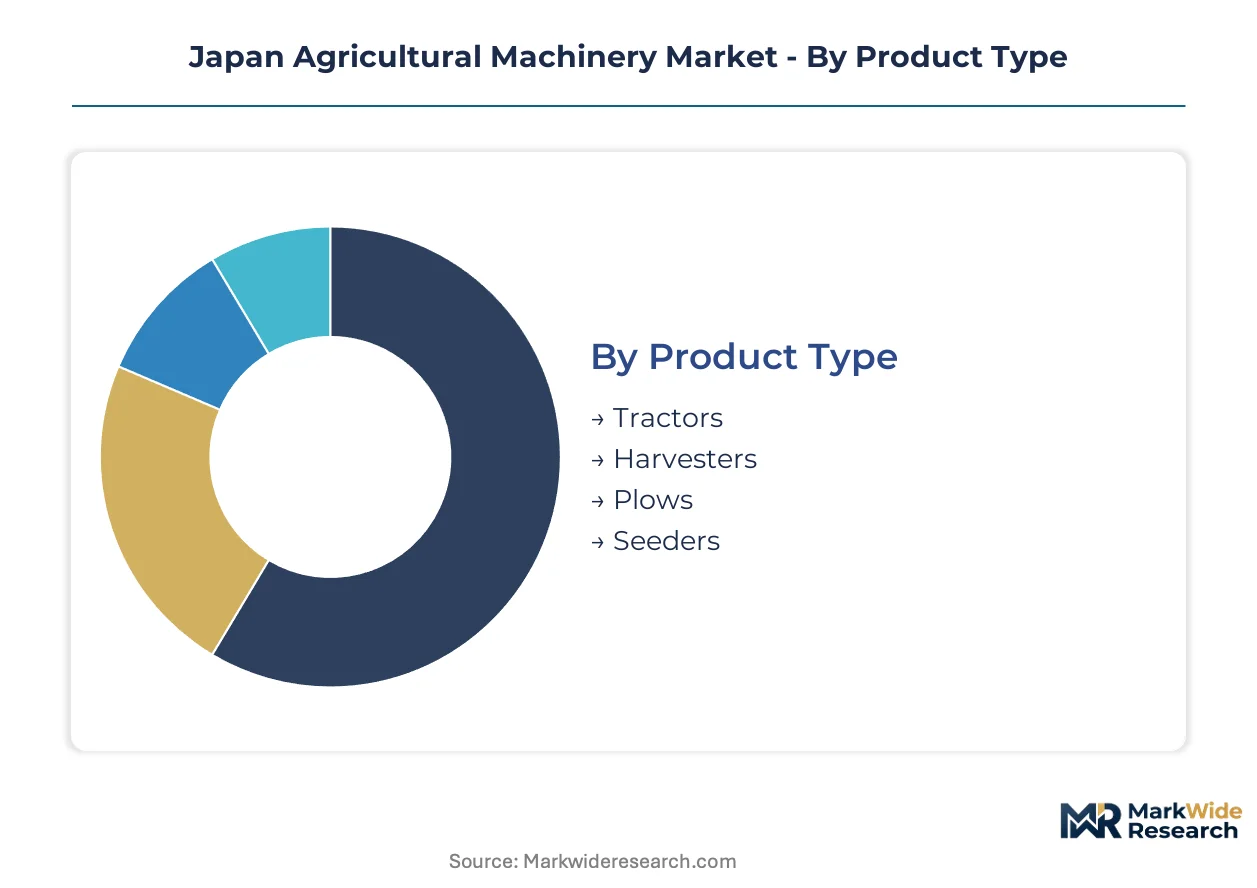
Japan's agricultural machinery market fragments across equipment specifications, precision technology tiers, and procurement channels that reflect the country's dual structure of Hokkaido-scale grain operations and Kyushu-intensive vegetable zones. Understanding these segment boundaries clarifies where METI subsidies concentrate and which customer groups drive replacement cycles.
Product Type:
Margin pools concentrate in harvesters due to seasonal utilization constraints and rice-specific engineering complexity, while tractors generate volume through cooperative fleet standardization.
- Tractors:Self-propelled equipment rated 15-300 horsepower dominates installed base across Japan's rice belt, with compact variants capturing cooperative procurement in terraced western prefectures where maneuverability limits larger units.
- Harvesters:Rice-specific threshing mechanisms command premium pricing due to technical complexity in handling seasonal density variations; demand concentrates in Hokkaido's grain belt where large-scale cooperatives justify capital intensity despite narrow seasonal windows.
- Plows:Towed soil preparation equipment serves secondary tillage operations in Shikoku's fragmented holdings where draft power requirements remain modest.
- Seeders:Precision planting units integrate with variable-rate controllers in Kyushu's intensive vegetable production zones.
The dominant share belongs to Tractors, while Harvesters is closing the gap fastest on margin contribution per unit.
Technology:
Cost tier stratification separates precision-enabled platforms qualifying for METI subsidies from legacy mechanical systems facing gradual displacement.
- GPS:Real-time kinematic guidance systems enable centimeter-level accuracy for autonomous navigation; retrofit demand accelerates in Hokkaido as subsidies defray installation costs for cooperative fleets.
- IoT:Remote monitoring platforms aggregate equipment performance data across cooperative administrative structures, reducing manufacturer exposure to fragmented servicing networks in rural Tohoku.
- Automation:Collision-avoidance protocols and unmanned operation capabilities require JIS safety certification; approval bottlenecks extend timelines for domestic manufacturers seeking subsidy eligibility.
- Diesel:Conventional powertrains retain installed base dominance but face procurement headwinds as METI's carbon neutrality roadmap redirects capital toward electrification alternatives.
GPS-enabled platforms are expanding most quickly, while Diesel retains the largest installed base despite subsidy phase-down pressure.
End User:
Volume concentration tracks cooperative purchasing power consolidation across prefectural boundaries, displacing historical individual farmer dominance.
- Farmers:Individual owner-operators in western Japan's mountainous prefectures shift toward equipment leasing as capital barriers rise for precision-enabled machinery.
- Cooperatives:Agricultural cooperatives aggregate procurement across smallholder networks in Shikoku and Chugoku, concentrating fleet management expertise and standardizing maintenance protocols.
- Agricultural Companies:Corporate farming operations in Hokkaido drive large-scale fleet consolidation to offset labor shortages through mechanization density.
- Research Institutions:University and government experimental stations pilot hydrogen fuel cell prototypes and autonomous navigation platforms under METI research grants.
Cooperatives hold the dominant procurement volume, while Agricultural Companies are gaining share fastest through Hokkaido consolidation.
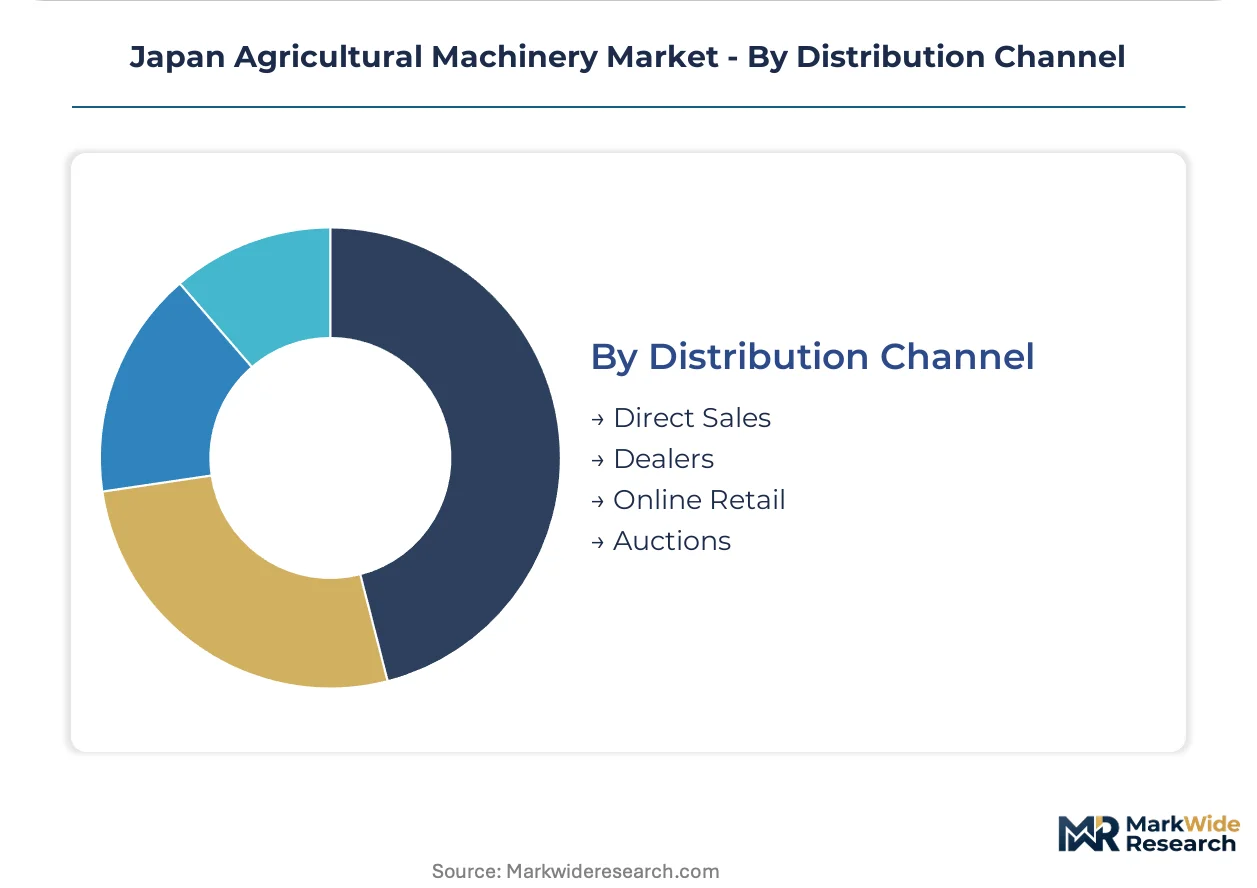
Distribution Channel:
Customer type dictates channel selection, with cooperative procurement favoring direct manufacturer relationships while fragmented smallholders rely on intermediary networks.
- Direct Sales:Manufacturer-to-cooperative relationships dominate large equipment transactions in Hokkaido, enabling customized fleet configurations and integrated service contracts.
- Dealers:Regional distribution networks retain relevance for individual farmers in Kyushu and western prefectures requiring localized maintenance support and trade-in facilitation.
- Online Retail:Digital procurement channels emerge for spare parts and retrofit components, though complete equipment transactions remain rare due to inspection requirements.
- Auctions:Secondary market liquidation channels absorb retiring diesel fleets as cooperatives upgrade to precision-enabled platforms.
Direct Sales commands the dominant transaction value, while Dealers maintains the broadest geographic coverage across rural prefectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tomakomai Port's grain handling infrastructure underwrites Hokkaido's dominance in large-scale mechanized agriculture, connecting northern Japan's cooperative fleets to international equipment supply chains.
Hokkaido
Hokkaido's expansive grain belt drives concentrated demand for high-horsepower tractors and combine harvesters as farming cooperatives consolidate landholdings. METI's Smart Agriculture subsidies prioritize this region for autonomous navigation platform deployment. Sapporo-based equipment pools coordinate fleet standardization across the Kamikawa and Tokachi sub-prefectures.
Kyushu
Kyushu's intensive vegetable production zones generate specialized demand for precision seeders and variable-rate sprayers calibrated to greenhouse operations. The region's humid subtropical climate accelerates corrosion concerns for electronic guidance systems. Fukuoka Prefecture's agricultural cooperatives pilot shared equipment pools for smallholder networks in the Chikugo Plain.
Kanto
Kanto's proximity to Tokyo-Yokohama manufacturing corridors positions the region as a testbed for hydrogen fuel cell prototypes in heavy harvester segments. The Narita International Airport logistics cluster facilitates rapid spare parts distribution to servicing depots. Ibaraki Prefecture's Tsukuba research corridor hosts METI-funded autonomous machinery validation programs.
Chugoku
Chugoku's terraced rice cultivation in Hiroshima and Okayama prefectures sustains demand for ultra-compact machinery engineered to slope gradients exceeding 15 degrees. Regional agricultural committees enforce cooperative purchasing agreements that standardize maintenance protocols across fragmented landholdings. The Seto Inland Sea ports enable cost-efficient import of precision retrofit components.
Tohoku
Tohoku's aging rural workforce accelerates mechanization investment as labor availability contracts in Aomori and Iwate prefectures. The region's tsunami recovery infrastructure includes rebuilt agricultural roads rated for heavier equipment transport. Sendai-based technical training centers address technician scarcity for GPS guidance system installation.
Japan Agricultural Machinery Market Competitive Landscape
Concentration sits with integrated engine manufacturers possessing captive powertrain production. The vendor base stratifies across three tiers: diversified industrial conglomerates with agricultural divisions, specialized machinery pure-plays, and regional cooperative equipment suppliers. Strategic moves center on cooperative fleet standardization contracts and JIS certification pre-emption for autonomous safety protocols.
Among Japan-based manufacturers, Kubota Corporation, Yanmar Company Limited, and Iseki & Co., Ltd. exemplify distinct competitive archetypes. Kubota represents the diversified industrial conglomerate model with integrated engine manufacturing capabilities. Yanmar occupies a position within precision agriculture specialization, particularly for autonomous navigation platforms. Iseki exemplifies the ultra-compact machinery specialist serving topographically constrained western prefectures.
| Leading Market Players |
|---|
| Komatsu Ltd |
| Maruyama Mfg. Co., Inc. |
| Kubota Corporation |
| Mitsubishi Mahindra Agricultural Machinery |
| Toyota Industries Corporation |
| Yanmar Company Limited |
| Hitachi Construction Machinery Co. Ltd |
| Kukje Machinery Company Limited |
| Iseki & Co., Ltd. |
| Others |
Supply & Pricing Matrix
Steel-to-aluminum substitution in powertrain housings simultaneously shifts procurement geography toward South Korean smelters and compresses margin structures for Japanese compact tractor manufacturers serving Hokkaido's cooperative fleets.
Pricing Analysis
Volume-discount tiering structures dominate transactions between manufacturers and agricultural cooperatives, with procurement scale determining per-unit pricing brackets. Price differentiation rests on JIS certification status and after-sales service bundling, where autonomous navigation platforms command premiums over mechanical control systems. Cost compression in economy-tier diesel tractors intensifies as METI subsidies redirect demand toward precision-enabled alternatives. Individual farmers in western prefectures exhibit highest price sensitivity, while Hokkaido cooperatives prioritize performance specifications over unit economics.
Supply Chain Analysis
Japan and South Korea anchor precision component fabrication, with Taiwan supplying semiconductor modules for GPS guidance systems. Domestic manufacturers draw from Chinese steel mills for chassis fabrication, German sensor suppliers for RTK positioning hardware, and domestic engine foundries for powertrain assembly. Single-source vulnerability concentrates in lithium-ion battery cells for electrification prototypes. Distribution runs through cooperative procurement consortia in northern prefectures and regional dealer networks in fragmented western holdings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against battery-electric substitution threats that METI's carbon neutrality roadmap accelerates, preserving installed base relevance through precision retrofit compatibility.
For Market Incumbents: Secure JIS certification pre-emption for autonomous safety protocols before subsidy eligibility windows narrow. Deepen backward integration into engine manufacturing to offset steel and semiconductor input volatility. Protect cooperative fleet standardization contracts against interoperability challengers.
For New Entrants and Emerging Players: Anchor in Kyushu's underpenetrated vegetable precision zones where variable-rate spraying technology lacks established vendors. Target Shikoku's fragmented smallholder networks through equipment-as-a-service models that bypass capital barriers. Pursue METI research grants for hydrogen fuel cell harvester prototypes.
For Investors and Strategic Acquirers: The market sits at a substitution acceleration phase that favors precision technology specialists over legacy mechanical manufacturers. Long-term viability hinges on electrification readiness across humidity-intensive operating environments. Acquisition targets should demonstrate JIS certification progress and cooperative channel relationships. Monitor METI subsidy phase-down announcements as inflection indicators for diesel fleet residual values.
| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Pre-emption | Secures subsidy eligibility for autonomous navigation platforms before competitor filings. |
| Cooperative Fleet Standardization | Concentrates procurement volume through Sapporo-based equipment pool contracts. |
| Backward Integration into Engines | Captive powertrain production shields Kubota and Yanmar from semiconductor volatility. |
| Precision Retrofit Compatibility | Extends legacy diesel tractor service life against battery-electric displacement pressure. |
| Hydrogen Fuel Cell Prototyping | Positions harvester segments for METI's 2050 carbon neutrality compliance pathway. |
Research Methodology
The analysis maps tractors, harvesters, precision guidance systems, and cooperative procurement channels, each validated through equipment procurement managers at agricultural cooperatives, plant engineers at domestic manufacturers, aftermarket service heads, and METI policy officers. Primary interviews combined with secondary validation against JIS standards documentation, METI subsidy disbursement records, prefectural agricultural committee reports, and customs machinery import data. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Consistency checks validated volume and value outputs against cooperative fleet consolidation patterns and subsidy uptake rates by technology tier. The analytical framework modeled equipment type, horsepower class, precision technology tier, end-user procurement structure, and regional agricultural zone characteristics across the analysis window. CAGRs derived from replacement cycle compression rates and subsidy-driven demand elasticity. Forecast inputs incorporated labor force aging trajectories and carbon neutrality compliance timelines.
Material uncertainties — subsidy phase-down schedules, battery-electric technical readiness, and JIS certification timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions about cooperative purchasing power consolidation and interoperability standardization progress. Recalibration cycles align with material shifts in METI policy announcements and autonomous machinery safety protocol approvals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Automated Turf Harvester Market
Agricultural Machinery
India Tractor Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
North America Agricultural Machinery Market