
 Out-Of-Band Authentication Market | 2026-2036
Out-Of-Band Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Out-Of-Band Authentication Market Analysis
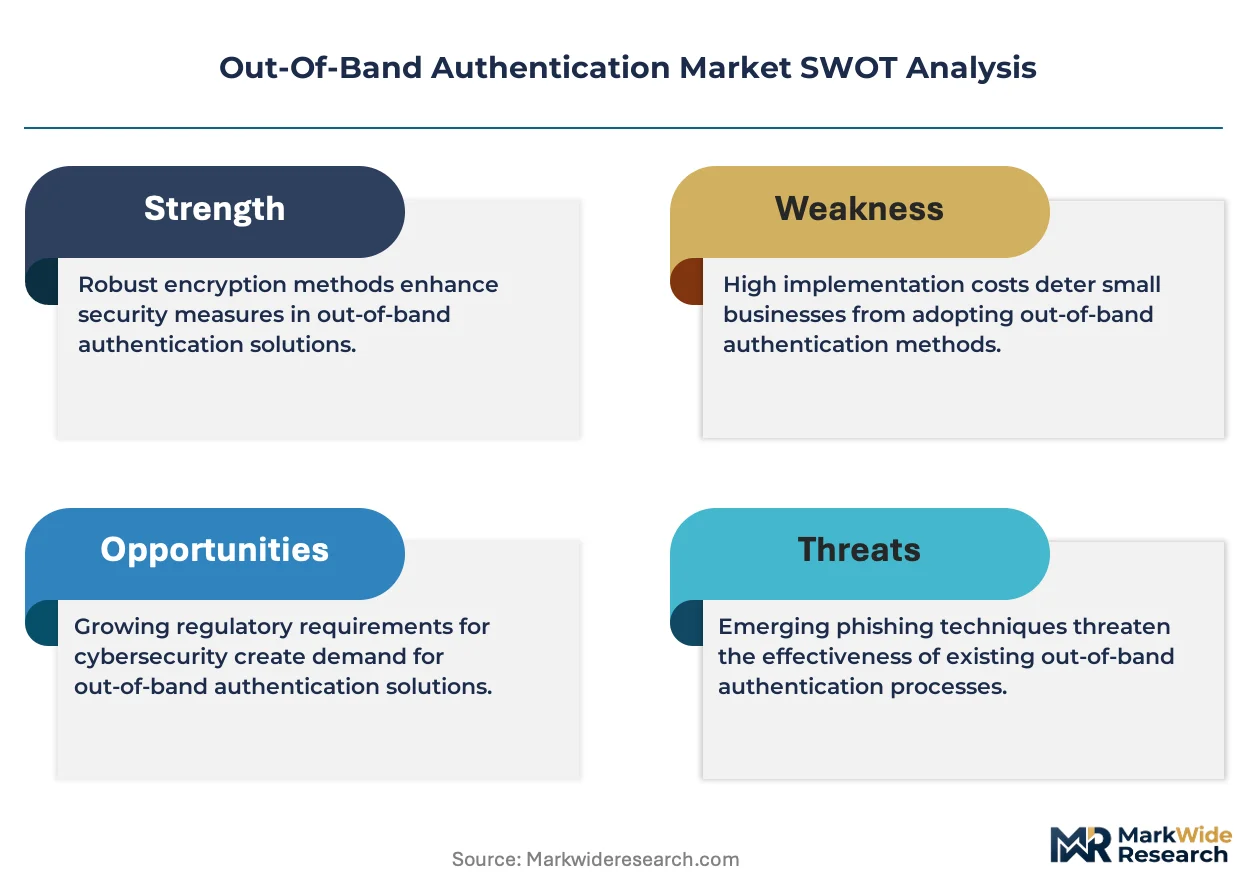
GDPR Article 32 is recalibrating the cost-of-entry calculus for authentication vendors serving European enterprises. OneSpan leverages its hardware security module heritage to anchor high-assurance deployments in regulated banking environments. Thales Group sustains competitive positioning through its Gemalto identity portfolio and deep credential manufacturing scale across government and telecom verticals. Ping Identity competes aggressively in cloud-native delivery, extending API-first architectures that reduce on-premise infrastructure overhead for mid-market financial services clients.
Out-of-band authentication refers to identity verification performed over a separate communication channel from the primary transaction pathway, typically employing SMS gateways, push notification protocols, or voice call relays to deliver one-time passcodes or biometric challenge responses. The mechanism creates protocol isolation that prevents man-in-the-middle interception even when primary session credentials become compromised. Cloud-based deployment models now capture the fastest expansion trajectory as financial institutions and healthcare providers migrate from on-premise token infrastructure to API-integrated managed services. Push notification authentication methods are displacing SMS verification in premium-tier deployments due to SIM-swapping vulnerabilities and NIST deprecation guidance, while voice call channels retain residual utility in rural connectivity environments and accessibility-compliant government service delivery.
The Federal Financial Institutions Examination Council in the United States, the European Banking Authority under PSD2, and the Reserve Bank of India's cyber security framework collectively mandate multi-factor authentication for remote financial transactions, directly expanding addressable demand for out-of-band verification infrastructure. Compliance deadlines and supervisory examination cycles create predictable procurement windows that vendors must align against. Stakeholders should monitor regulatory divergence between prescriptive technical standards and principles-based risk assessment frameworks, as this tension will determine whether product development resources flow toward configurable platforms or pre-certified compliance bundles.
Market Dynamics
Push notification protocols are compressing SMS-based verification timelines as financial institutions abandon SIM-vulnerable channels under NIST deprecation pressure. This channel migration is redistributing infrastructure spend toward API-integrated identity platforms and biometric relay systems.
Growth Catalysts
- PSD2 Strong Customer Authentication mandates:European Union member states enforce multi-factor requirements for remote payments, forcing retail banks to procure out-of-band verification stacks ahead of supervisory examination cycles.
- Healthcare digitization:Telemedicine platforms and electronic prescription systems in the United States deploy voice-call and push-notification channels to satisfy HIPAA security rule obligations for patient identity verification.
- Rural connectivity gaps:Voice call authentication retains procurement priority in Indian agricultural banking networks where smartphone penetration lags and SMS delivery failure rates exceed urban thresholds.
Market Restraints
- Telecom carrier dependency:SMS and voice relay costs fluctuate with wholesale termination rate negotiations, compressing margins for authentication-as-a-service providers serving high-volume transactional clients.
- Biometric sensor supply concentration:Fingerprint and facial recognition module fabrication clusters in East Asian contract manufacturers create single-source vulnerability for hardware-anchored deployments.
- GDPR Article 32 compliance friction:European data protection authorities impose encryption and breach notification standards that extend procurement cycles and elevate legal review costs for cloud-native authentication vendors.
Strategic Opportunities
- German Mittelstand banking segment:Regional cooperative banks lag multinational institutions in out-of-band deployment, creating whitespace for modular API solutions that bypass heavy on-premise token infrastructure.
- Convergence of behavioral biometrics with push channels:Keystroke dynamics and device fingerprinting layered atop notification-based challenge-response creates differentiated assurance tiers for high-value wire transfer authorization.
- Reserve Bank of India cyber security framework expansion:Scheduled compliance deadlines for non-bank payment system operators mandate multi-factor authentication, opening procurement windows for verification infrastructure vendors in the fintech aggregator segment.
Industry Challenges
- Legacy mainframe integration complexity:Core banking systems at established US financial institutions resist API-native authentication handshakes, forcing middleware development that delays deployment timelines and elevates professional services costs.
- FIDO2 certification timeline compression:Vendor engineering teams face backlog pressure as certification bodies process hardware security key and biometric authenticator submissions ahead of PSD2 enforcement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Out-Of-Band Authentication Market |
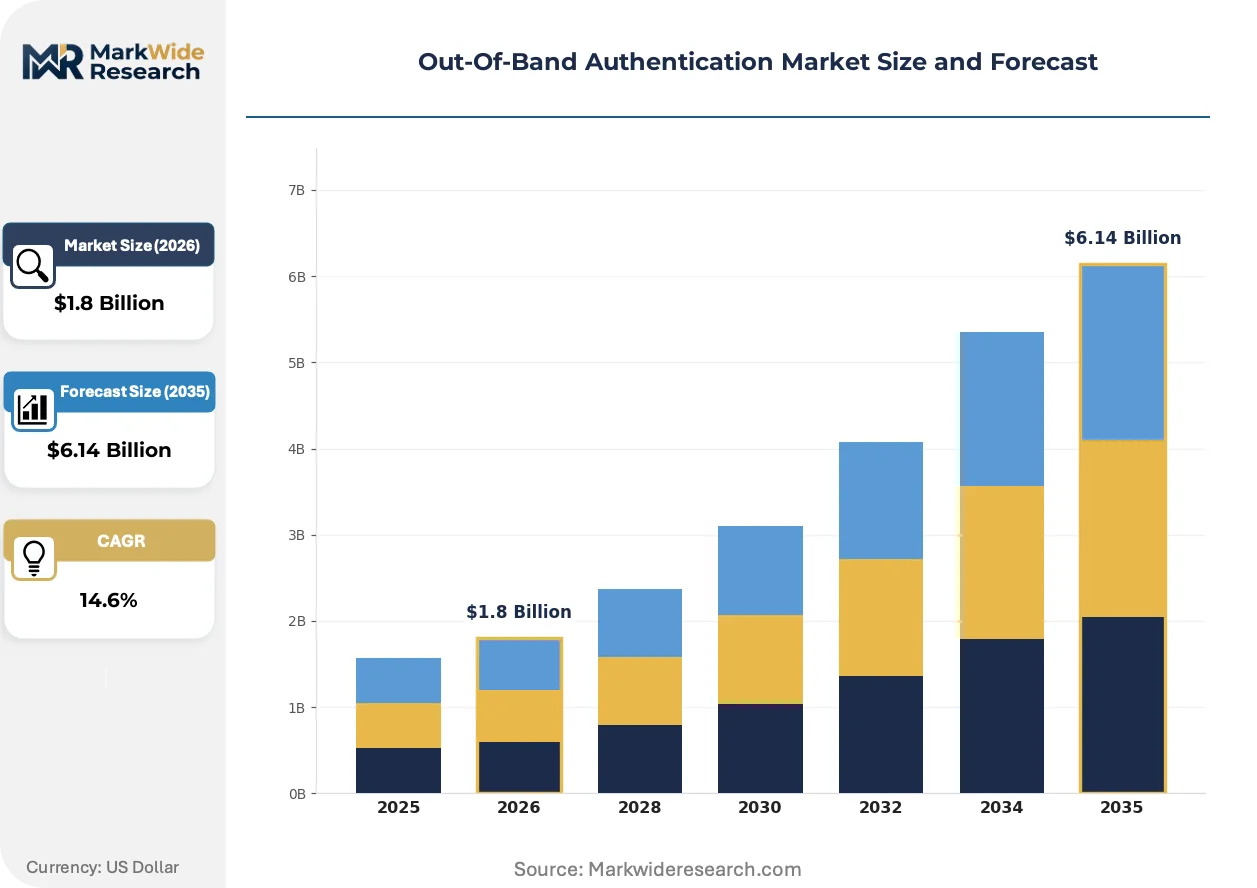
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Authentication Method: SMS Verification, Email Verification, Voice Call, Push Notification End User: Financial Institutions, E-Commerce, Government Agencies, Healthcare Providers Technology: SMS Gateway, API Integration, Mobile App, Biometric Authentication |
| Companies Covered | Deepnet Security, Early Warning Services, OneSpan, Ping Identity, RSA Security, Gemalto, Symantec, StrikeForce Technologies, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Out-Of-Band Authentication Market Emerging Trajectories
Authentication infrastructure is fragmenting into composable service layers that separate identity proofing, risk scoring, and channel delivery into independently upgradeable components. This decomposition is accelerating vendor specialization and buyer procurement flexibility.
Biometric challenge-response systems are modularizing around FIDO2 standards that separate cryptographic key storage from presentation-layer capture devices. Large US retail banks are adopting these architectures to swap fingerprint, facial, and voice modalities without core system rewrites. The decoupling is compressing vendor lock-in duration and enabling best-of-breed procurement across hardware and software tiers.
GDPR Article 32 enforcement is tightening encryption requirements for authentication data at rest and in transit across European deployments. National data protection authorities in Germany and France have issued specific guidance on biometric template storage that elevates hardware security module adoption. Financial services and healthcare providers in these jurisdictions are responding by specifying HSM-backed key management in procurement tenders.
Buyer preference is rotating toward consumption-based pricing that ties authentication costs to verified transaction volume rather than licensed seat counts. Mid-market fintech platforms in India and Germany are displacing perpetual license models with metered API calls. This shift is most visible among payment aggregators serving variable-volume merchant portfolios where transaction forecasting remains unreliable.
Out-Of-Band Authentication Market Segmentation
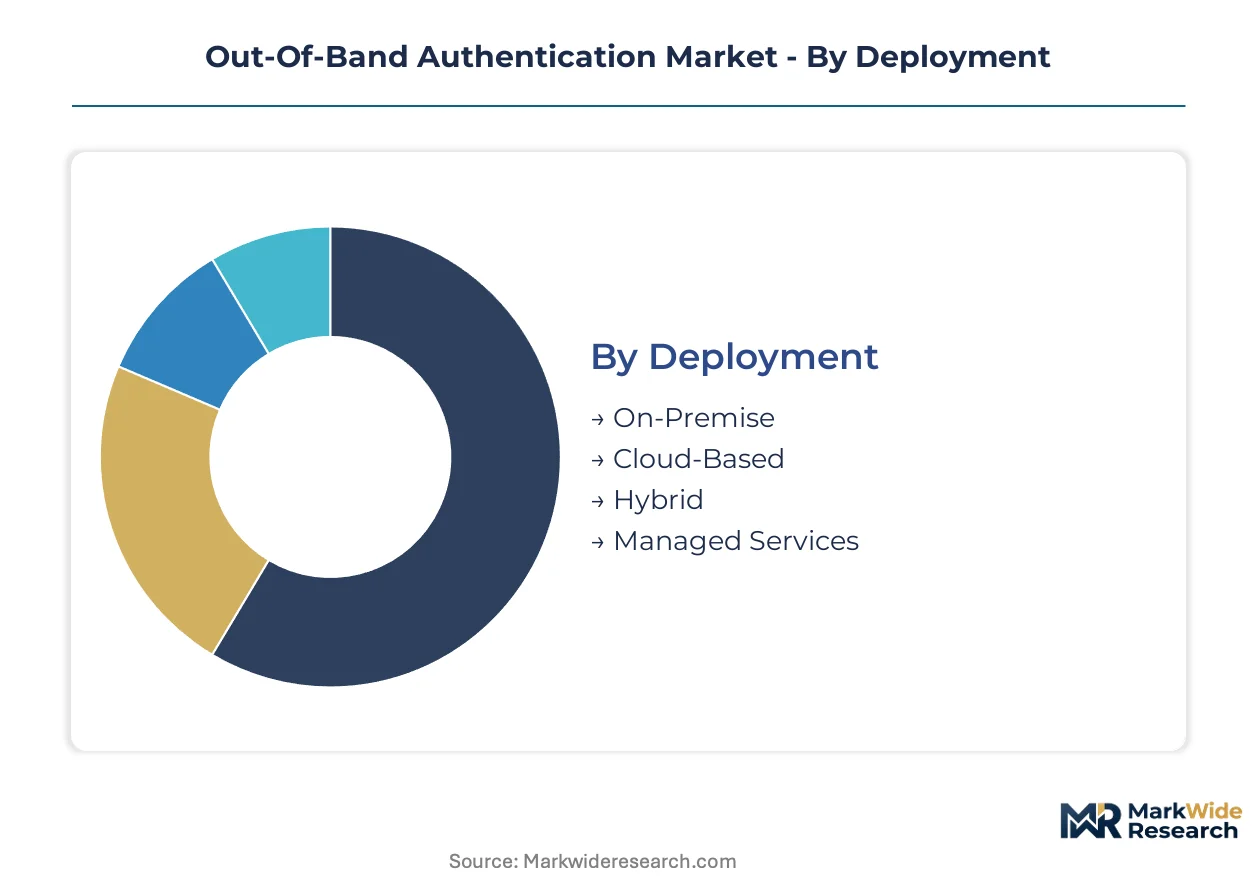
Segmentation in out-of-band authentication reveals how procurement decisions split between legacy infrastructure preservation and cloud-native modernization. Financial institutions prioritize deployment models and authentication channels that satisfy regulatory mandates while minimizing core system disruption.
Deployment:
Integration depth varies sharply across deployment modes, with standalone on-premise installations demanding heavy professional services while cloud-native options embed through API layers.
- On-Premise:Hardware security modules and token servers operate within institutional data centers, requiring dedicated rack space and internal key management. Large US retail banks with mainframe core systems favor this model to satisfy FFIEC examination protocols despite elevated capital expenditure.
- Cloud-Based:API-integrated managed services eliminate infrastructure ownership, enabling mid-market fintech platforms to scale verification volumes without capacity planning. German cooperative banks are migrating toward this model to bypass heavy token infrastructure investments.
- Hybrid:Sensitive cryptographic operations remain on-premise while channel delivery shifts to cloud relays. This architecture addresses data residency requirements under GDPR Article 32 for European financial institutions.
- Managed Services:Outsourced operations encompass key lifecycle management, certificate renewal, and carrier relationship negotiation. Indian payment system operators procure these bundles to meet RBI compliance deadlines without building internal security operations centers.
Cloud-based deployment leads volumes today; managed services is gaining share fastest among non-bank payment operators.
Authentication Method:
Channel selection reflects a risk-based trade-off between interception vulnerability, user friction, and accessibility compliance.
- SMS Verification:One-time passcodes delivered via cellular networks face elevated SIM-swapping attacks. NIST SP 800-63B deprecation guidance is compressing procurement timelines for this method at US financial institutions.
- Email Verification:Secondary channel authentication through SMTP relays serves low-risk transaction tiers and account recovery workflows. E-commerce merchants deploy this method for cart abandonment recovery where friction reduction outweighs assurance elevation.
- Voice Call:Interactive voice response systems deliver spoken passcodes to landline and basic mobile devices. Indian agricultural banking networks retain this channel where smartphone penetration lags and SMS delivery failure rates exceed urban thresholds.
- Push Notification:Cryptographically signed challenges transmitted through proprietary mobile app channels resist relay attacks and phishing interception. Premium-tier deployments at US healthcare providers satisfy HIPAA security rule obligations for patient identity verification.
Push notification leads volumes today; voice call retains residual priority in rural connectivity environments.
End User:
Vertical-specific compliance regimes and transaction value distributions shape authentication sophistication requirements.
- Financial Institutions:Retail banks, investment brokerages, and payment processors deploy multi-factor stacks for wire transfers, account openings, and high-risk transaction authorization. PSD2 Strong Customer Authentication mandates across EU member states force procurement ahead of supervisory examination cycles.
- E-Commerce:Merchant platforms and marketplaces balance checkout friction reduction with chargeback liability mitigation. Indian payment aggregators serving variable-volume merchant portfolios favor consumption-based API pricing models.
- Government Agencies:Citizen service portals and benefits distribution systems require accessibility-compliant channels. Voice call authentication satisfies Section 508 requirements for visually impaired users accessing US federal services.
- Healthcare Providers:Telemedicine platforms and electronic prescription systems verify patient identity before controlled substance authorization. US hospital systems layer push notifications atop existing patient portal infrastructure.
Financial institutions lead volumes today; healthcare providers are expanding procurement fastest following telemedicine platform scaling.
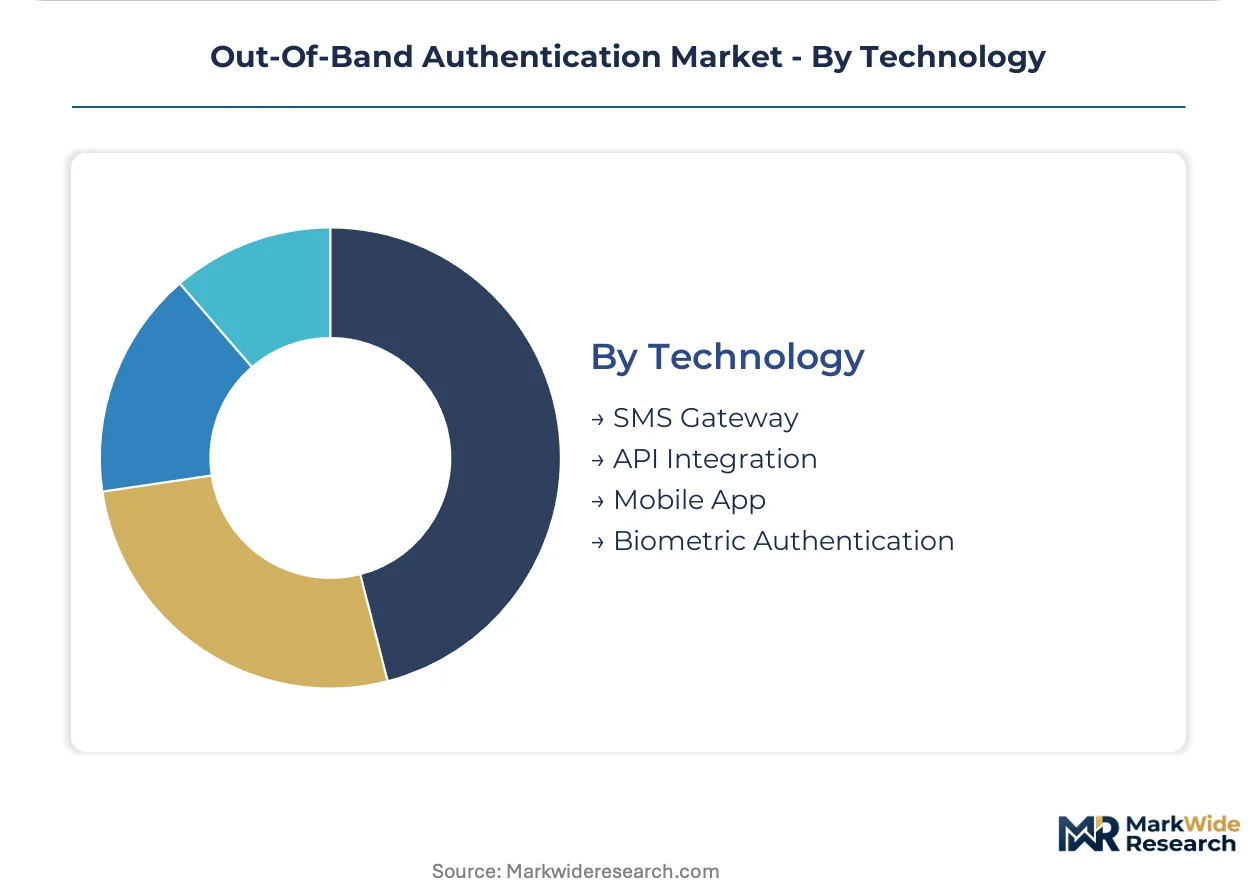
Technology:
Technology layers separate channel transport from cryptographic assurance, enabling modular upgrades without system replacement.
- SMS Gateway:Telecom carrier integrations route one-time passcodes through SS7 and SIGTRAN protocols. Wholesale termination rate negotiations create margin pressure for authentication-as-a-service providers.
- API Integration:RESTful and gRPC interfaces embed verification workflows into mobile banking and e-commerce checkout flows. German Mittelstand banks prioritize modular API solutions that bypass heavy on-premise token infrastructure.
- Mobile App:Proprietary smartphone applications host cryptographic key storage and biometric capture. FIDO2 standards decouple key storage from presentation-layer devices, enabling modality swaps without core system rewrites.
- Biometric Authentication:Fingerprint, facial, and voice recognition templates verify possession through inherence factors. German and French data protection authorities have issued specific guidance on biometric template storage that elevates hardware security module adoption.
API integration leads volumes today; biometric authentication is climbing the fastest as FIDO2 certification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Bangalore, Berlin, and Boston anchor the authentication infrastructure development pipeline. Cybersecurity workforce concentrations in these metros feed vendor R&D centers and financial institution security operations. Regulatory enforcement timelines in the United States, Germany, and India create synchronized procurement cycles that vendors must align against.
United States
Retail banking digitization and healthcare telemedicine expansion drive push notification deployment at scale. NIST SP 800-63B deprecation guidance for SMS verification compresses procurement timelines at financial institutions. The Boston-Washington corridor concentrates vendor R&D and bank security operations centers where FIDO2 certification backlogs create engineering bottlenecks.
Germany
Mittelstand cooperative banks lag multinational institutions in out-of-band deployment, creating whitespace for modular solutions. PSD2 Strong Customer Authentication mandates enforce multi-factor requirements ahead of European Banking Authority examination cycles. Frankfurt and Munich host the densest concentrations of banking IT procurement decision-makers specifying hardware security module-backed deployments.
India
Non-bank payment system operators face Reserve Bank of India cyber security framework compliance deadlines that mandate multi-factor authentication. Agricultural banking networks in rural districts retain voice call channels where smartphone penetration lags and SMS failure rates exceed urban thresholds. Mumbai and Bangalore concentrate fintech engineering talent building API-integrated verification stacks for payment aggregators.
United Kingdom
Open Banking API standards elevate authentication assurance requirements for third-party financial data providers. Financial Conduct Authority supervision of PSD2 implementation creates predictable procurement windows for verification infrastructure. London's fintech cluster drives demand for consumption-based pricing models that tie authentication costs to verified transaction volume.
France
CNIL guidance on biometric template storage elevates hardware security module specifications in procurement tenders. Healthcare digitization and electronic prescription systems deploy push notification channels to satisfy data protection obligations. Paris hosts the regional headquarters of major authentication vendors serving continental European financial institutions.
Out-Of-Band Authentication Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the authentication infrastructure landscape. The vendor base spans three strategic tiers: hardware security module heritage players, cloud-native API-first platforms, and telecom-integrated messaging specialists. Consolidation pressure concentrates among mid-scale providers lacking either manufacturing depth or cloud delivery scale. Dominant competitive moves include FIDO2 certification acceleration and hybrid deployment architecture development to address data residency requirements.
Among diversified technology conglomerates, Thales Group and Gemalto occupy positions anchored in credential manufacturing scale across government and telecom verticals. OneSpan represents the hardware security module heritage archetype serving regulated banking environments with high-assurance deployments. Ping Identity sits within the cloud-native delivery tier, extending API-first architectures that reduce infrastructure overhead for mid-market financial services clients. These three anchors exemplify how vendor specialization around deployment model and assurance tier shapes competitive positioning.
| Leading Market Players |
|---|
| Deepnet Security |
| Early Warning Services |
| OneSpan |
| Ping Identity |
| RSA Security |
| Gemalto |
| Symantec |
| StrikeForce Technologies |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Wholesale SMS termination rate indices cascade through authentication-as-a-service margins, compressing profitability for high-volume transactional clients and forcing unbundling of channel delivery from cryptographic assurance tiers. This cost pressure redistributes procurement toward API-integrated platforms that bypass carrier-dependent relay economics.
Pricing Analysis
Bundled managed services versus unbundled component licensing splits the procurement landscape. Per-transaction metered pricing dominates among Indian payment aggregators and German fintech platforms where volume forecasting remains unreliable. Price differentiation rests on FIDO2 certification tier and hardware security module integration depth. Cost compression in SMS-reliant tiers is intensifying because NIST deprecation guidance accelerates channel abandonment. Mid-market cooperative banks exhibit highest price sensitivity; regulated multinational institutions prioritize assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with East Asian contract manufacturers concentrating fingerprint and facial recognition module fabrication. Hardware security module production clusters in Germany, the United States, and Taiwan. Biometric sensor supply draws from South Korean and Chinese component foundries. Regulatory restriction risk materializes through GDPR Article 32 encryption mandates that extend procurement cycles. Distribution runs through telecom carrier integrations and API gateway providers serving cloud-native deployment architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German Mittelstand banks lag multinational institutions by multiple procurement cycles, creating cost-efficient entry points before PSD2 enforcement tightens.
For Market Incumbents: Lock in FIDO2 certification acceleration to defend against cloud-native API-first entrants. Prioritize hybrid deployment architecture development addressing GDPR data residency requirements. Channel control through carrier relationship consolidation protects margin position against wholesale termination rate volatility. For New Entrants and Emerging Players: Regional cooperative banks in Germany represent the most penetrable segment, with modular API solutions bypassing heavy on-premise token infrastructure. Indian non-bank payment operators facing RBI compliance deadlines offer whitespace for managed service bundles. Go-to-market positioning should emphasize consumption-based pricing that eliminates capacity planning burdens. For Investors and Strategic Acquirers: Asymmetric upside sits with biometric authentication specialists achieving FIDO2 decoupling between key storage and presentation-layer devices. Five-to-ten year viability favors vendors spanning both hardware security module heritage and cloud-native delivery capabilities. Watch for inflection when supervisory examination cycles trigger synchronized procurement windows across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2 Certification Acceleration | PSD2 enforcement windows compress engineering timelines for hardware security key submissions. |
| Hybrid Deployment Architecture Development | GDPR Article 32 data residency requirements drive on-premise cryptographic operation retention. |
| API-First Platform Integration | German Mittelstand banks bypass token infrastructure through RESTful and gRPC interface adoption. |
| Carrier Relationship Consolidation | Wholesale termination rate negotiations determine margins for SMS and voice relay channels. |
| Biometric Modularity Investment | Decoupling key storage from capture devices enables swaps between fingerprint, facial, and voice modalities. |
Methodological Framework
Multiple input streams — primary interviews with authentication vendor product managers, financial institution CISOs, and telecom carrier wholesale strategists; secondary validation against NIST SP 800-63B guidance documents, PSD2 regulatory filings, and RBI cyber security framework circulars; plus customs data on biometric sensor module trade flows — were reconciled through bottom-up deployment volume modeling and top-down market sizing triangulation.
Cross-referencing historical procurement cycle patterns against expert panel input on supervisory examination timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, authentication channel type, end-user vertical, and geographic regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and compliance deadline acceleration effects, with FIDO2 certification backlog duration and carrier termination rate trajectories serving as key forecast inputs.
Revisions become necessary when regulatory enforcement timelines shift, biometric sensor supply disruptions materialize, or wholesale telecom pricing structures renegotiate. Forecasts reflect assumptions about PSD2 implementation uniformity and NIST guidance adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
GCC Biometrics Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Voice Biometric Solutions Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
Biometrics Software Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
North America Biometrics in Government Market