
 Radiation Monitoring and Dosimeter Badges Market | 2026-2036
Radiation Monitoring and Dosimeter Badges Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Monitoring and Dosimeter Badges Market Analytics
The price-performance gap between premium and commodity tiers is hardening as healthcare systems demand hospital-grade accuracy while industrial buyers prioritize cost efficiency. Mirion Technologies Inc. leverages its nuclear power plant heritage to dominate high-reliability segments. Thermo Fisher Scientific Inc. sustains broad laboratory channel control through integrated instrumentation portfolios. Landauer Inc. anchors the North American service-contract model with recurring calibration revenue.
Radiation monitoring and dosimeter badges are wearable or area-mounted instruments that quantify cumulative or instantaneous ionizing radiation exposure, typically employing thermoluminescent crystals, optically stimulated luminescence materials, or solid-state electronic sensors with detection thresholds ranging from microsieverts to grays for personnel safety and regulatory compliance. Passive dosimeters retain latent signals for delayed readout while real-time electronic badges transmit instantaneous alerts, with the latter commanding premium positioning due to immediate intervention capability in nuclear medicine and interventional radiology workflows. Healthcare facilities represent the deepest end-user pool given expanding fluoroscopy and nuclear imaging volumes, whereas continuous monitoring systems are displacing film badge technology in industrial settings where networked area coverage replaces individual badge programs.
The FDA, EPA, and NRC collectively enforce occupational exposure limits and device performance standards that mandate accredited dosimetry services for US medical and nuclear workers, effectively creating a regulated service layer that insulates established providers from unqualified entrants. EMA and national EU competent authorities enforce the Medical Device Regulation and Euratom directives that standardize dose recording across member states, harmonizing cross-border worker monitoring for multinational nuclear operators. Stakeholders must weigh real-time connectivity investments against passive dosimeter cost structures as regulatory bodies on both sides of the Atlantic tighten documentation requirements for long-term exposure trending.
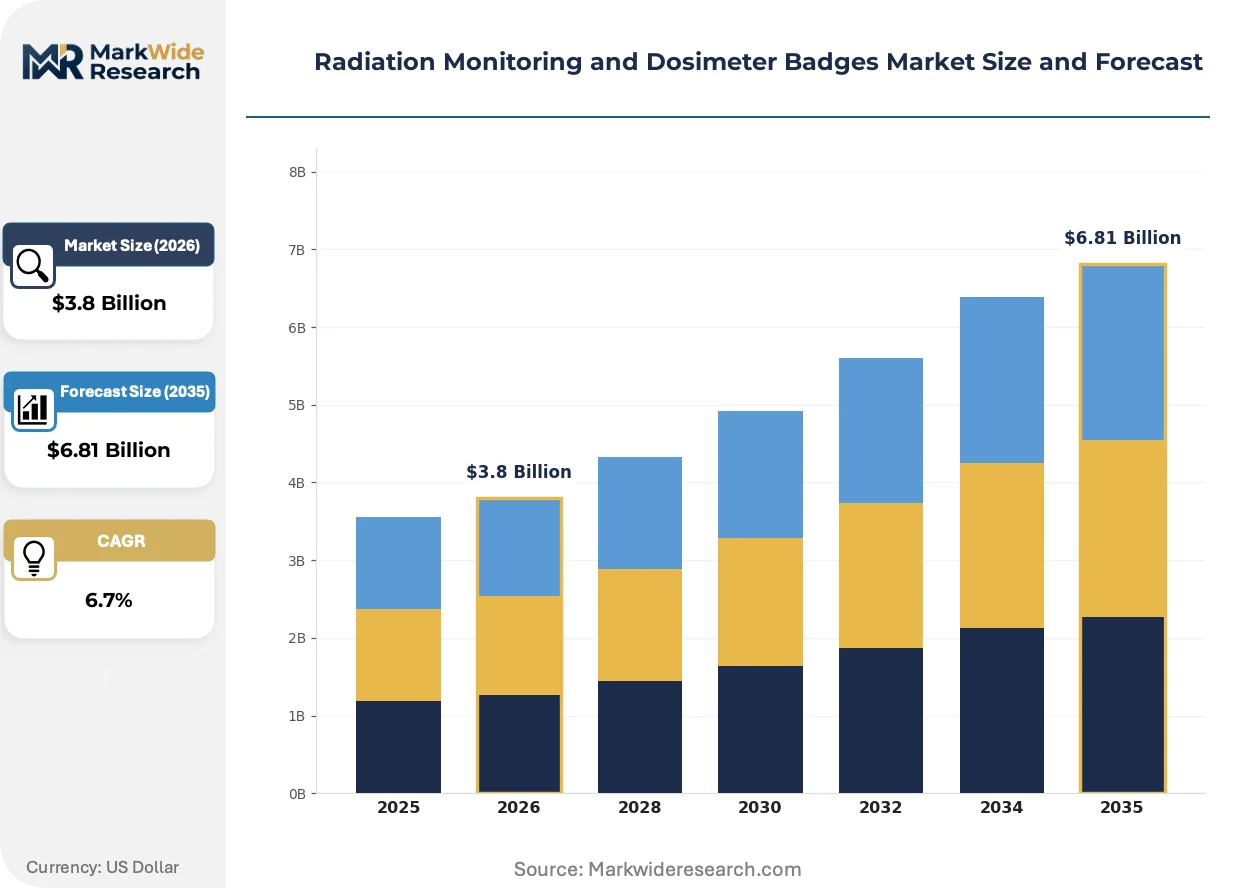
Market Dynamics
Real-time electronic dosimetry is compressing switching cycles across healthcare procurement, forcing passive badge providers to defend service-contract relationships against instantaneous-alert competitors that command premium positioning in interventional radiology and nuclear medicine workflows.
Growth Catalysts
- Fluoroscopy volume expansion:Rising interventional cardiology and pain management procedures in US hospital systems are mandating per-procedure dose tracking for cath lab staff, expanding badge deployment density beyond traditional radiology departments.
- Euratom dose record harmonization:Cross-border worker monitoring standardization enables multinational nuclear operators to consolidate dosimetry contracts across Germany, France, and Belgium under unified reporting frameworks.
- OSHA enforcement tightening:Enhanced US workplace inspection protocols for medical and dental radiation sources are driving non-compliant facilities toward accredited dosimetry services with documented calibration chains.
Market Restraints
- Lithium fluoride crystal supply concentration:Thermoluminescent material production clusters in East Asian specialty chemical zones create input vulnerability for passive dosimeter manufacturers.
- Real-time system capex barriers:Electronic badge infrastructure with networked area monitors requires hospital IT integration and recurring software licensing that squeezes capital-constrained community health systems.
- Film badge residual demand:Industrial radiography contractors in remote construction and pipeline inspection maintain legacy film programs due to offline operation requirements and minimal infrastructure dependency.
Strategic Opportunities
- India diagnostic imaging expansion:Private hospital chains in Mumbai, Delhi, and Bangalore are installing PET-CT and cath lab capacity without established dosimetry vendor relationships, creating first-mover positioning for service providers.
- AI-enabled predictive exposure modeling:Machine learning integration with electronic badge data streams enables anticipatory workflow adjustments in nuclear medicine suites before cumulative thresholds trigger alerts.
- Home healthcare radiation therapy:Portable radiopharmaceutical administration for thyroid and prostate cancer is extending monitoring requirements beyond institutional walls into visiting nurse networks.
Industry Challenges
- Medical physics specialist scarcity:Qualified professionals capable of interpreting complex badge data and managing ALARA programs are concentrated in academic medical centers, leaving community hospitals dependent on remote consultative support.
- Multi-vendor system integration:Hospitals operating mixed fleets of passive and electronic dosimeters face data reconciliation complexity when consolidating exposure records for regulatory reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Monitoring and Dosimeter Badges Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Dosimeters, Real-Time Dosimeters, Ionization Chambers, Continuous Monitoring Systems End User: Healthcare Facilities, Nuclear Power Plants, Research Laboratories, Industrial Sites Technology: Optically Stimulated Luminescence, Thermoluminescent Dosimetry, Electronic Dosimeters, Film Badge Technology Application: Radiation Safety Monitoring, Patient Dosimetry, Environmental Monitoring, Occupational Health |
| Companies Covered | Radiation Detection Company, Fuji Electric Co., Ltd., Mirion Technologies Inc., Polimaster Ltd., Ludlum Measurements Inc., Landauer Inc., Unfors RaySafe, Tracerco Limited, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Monitoring and Dosimeter Badges Market Evolving Landscape
Sensor miniaturization and wireless connectivity are converging to collapse the functional gap between laboratory-grade area monitors and personal wearable devices, enabling continuous exposure tracking that was previously technically or economically impractical.
Optically stimulated luminescence materials with re-read capability are rewriting dose verification protocols in radiation therapy departments. Linear accelerator QA teams at major cancer centers are adopting OSL-based secondary verification for patient-specific dosimetry, compressing the addressable market for single-read thermoluminescent alternatives while expanding total serviceable opportunity through higher verification frequency.
The FDA's updated guidance on occupational radiation exposure in fluoroscopy environments is mandating documented badge utilization rates and corrective action protocols for overexposure events. US hospitals are responding by integrating dosimetry data directly into credentialing systems, with interventionalists losing procedural privileges when badge compliance falls below institutional thresholds, tightening vendor accountability for data accuracy and timeliness.
Hospital supply chain consolidation is unbundling calibration and analysis services from badge hardware procurement. Large health systems in Texas, California, and New York are negotiating direct relationships with accredited laboratories while sourcing passive dosimeters through group purchasing organizations, compressing margins for integrated service providers and forcing specialization into high-complexity electronic monitoring segments where technical support retains pricing power.
Radiation Monitoring and Dosimeter Badges Market Segmentation
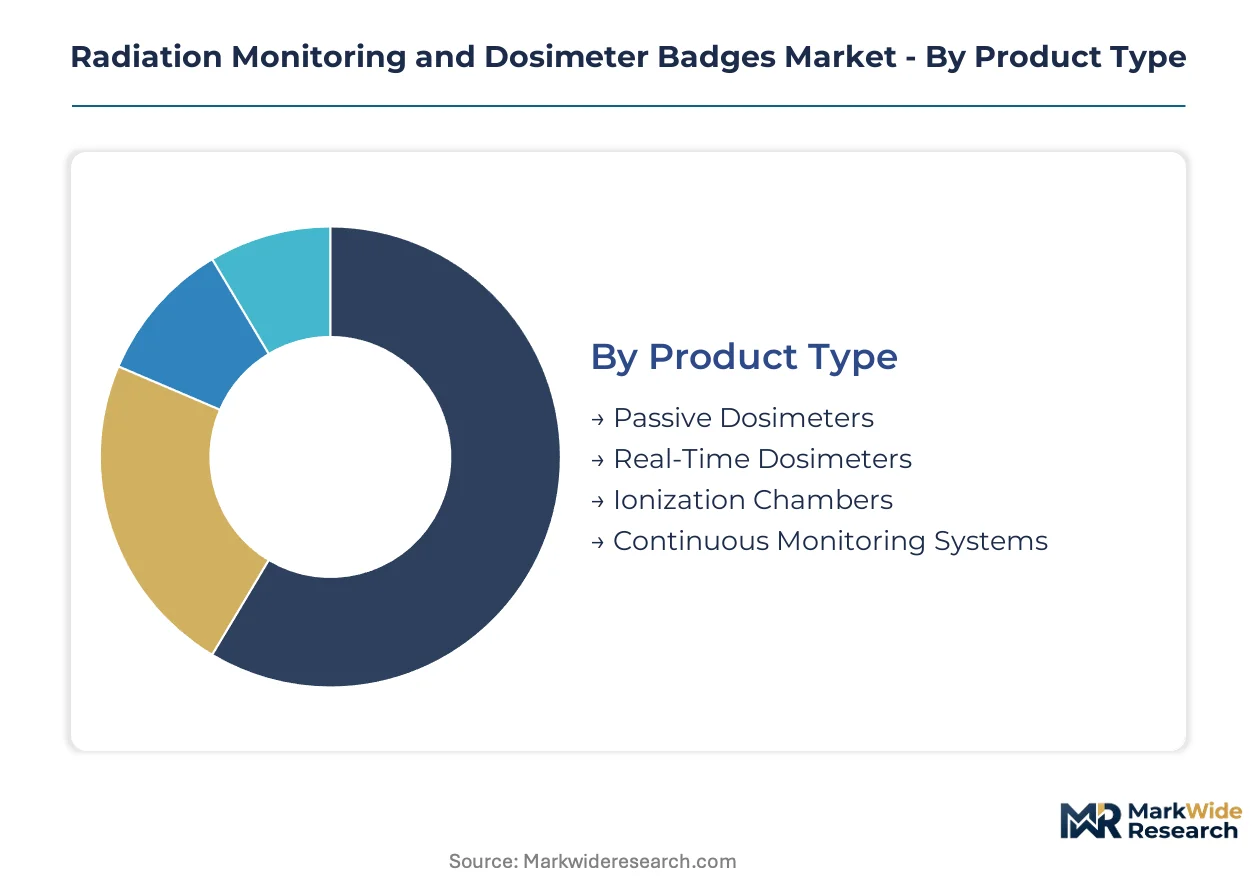
Technology selection in radiation dosimetry determines regulatory compliance pathways and service economics. Procurement patterns diverge sharply between healthcare systems prioritizing real-time intervention capability and industrial operators minimizing per-unit monitoring costs.
Product Type:
Detection modality dictates capital intensity, readout infrastructure requirements, and service contract structures across end-use environments.
- Passive Dosimeters:Thermoluminescent and optically stimulated luminescence devices store latent radiation signals for batch laboratory analysis. Healthcare facilities in Germany and France maintain dense deployment for staff compliance programs under Euratom dose record harmonization requirements.
- Real-Time Dosimeters:Solid-state electronic sensors with wireless connectivity transmit instantaneous exposure alerts to area monitors. Interventional cardiology suites and nuclear medicine departments command premium positioning for these systems due to immediate workflow intervention capability.
- Ionization Chambers:Gas-filled detectors deliver laboratory-grade accuracy for calibration reference standards and regulatory audit trails.
- Continuous Monitoring Systems:Networked area sensors with centralized data logging displace individual badge programs in industrial radiography and nuclear power containment zones.
Mature deployment sits with passive dosimeters. Newer deployment is concentrated in real-time dosimeters.
End User:
Regulatory exposure severity and workforce density shape procurement scale and technology sophistication requirements.
- Healthcare Facilities:Hospitals and imaging centers face tightening FDA guidance on fluoroscopy occupational exposure. US academic medical centers integrate badge data directly into physician credentialing systems with privilege suspension protocols for non-compliance.
- Nuclear Power Plants:Reactor operators and maintenance contractors require redundant monitoring layers for high-dose zones. German and Belgian utilities consolidate dosimetry contracts under unified Euratom reporting frameworks.
- Research Laboratories:Cyclotron facilities and radioisotope production sites demand specialized neutron-sensitive configurations.
- Industrial Sites:Non-destructive testing contractors and pipeline inspection crews in remote locations favor offline-capable passive systems over infrastructure-dependent electronics.
Procurement volume concentrates in healthcare facilities. Technology upgrade urgency peaks in nuclear power plants.
Technology:
Material science differentiation separates single-read legacy systems from re-analyzable verification platforms.
- Optically Stimulated Luminescence:Aluminum oxide crystals enable non-destructive re-read for dose verification disputes. Linear accelerator QA teams at major cancer centers adopt OSL-based secondary verification, compressing demand for single-read alternatives.
- Thermoluminescent Dosimetry:Lithium fluoride crystals retain historical deployment density but face supply concentration risk from East Asian specialty chemical production clusters.
- Electronic Dosimeters:Silicon diode and scintillation sensors with Bluetooth or proprietary radio transmission enable wearable form factors previously impractical.
- Film Badge Technology:Silver halide emulsions persist in construction radiography and offshore inspection where environmental extremes degrade electronic components.
Adoption momentum favors optically stimulated luminescence. Film badge technology retains residual demand in infrastructure-constrained environments.
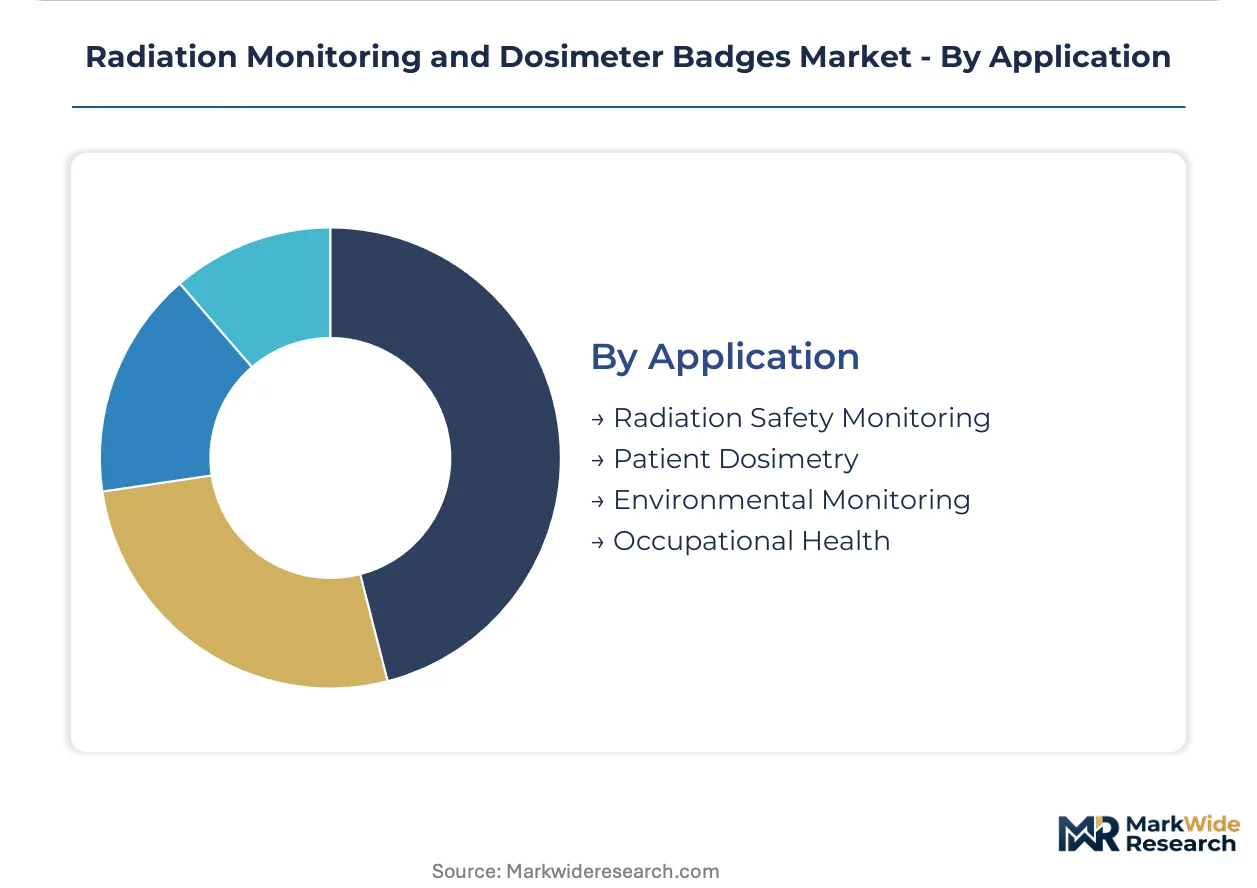
Application:
Regulatory jurisdiction determines data retention periods, accuracy thresholds, and corrective action protocols.
- Radiation Safety Monitoring:Personnel protection programs in interventional radiology and nuclear medicine require documented badge utilization rates under FDA updated guidance.
- Patient Dosimetry:Secondary verification for radiation therapy dose delivery demands OSL re-read capability for clinical dispute resolution.
- Environmental Monitoring:Area dosimeters track cumulative exposure in cyclotron vaults and radioisotope storage facilities.
- Occupational Health:Longitudinal exposure trending for nuclear workers spans decades under NRC and EPA record-keeping mandates.
Compliance complexity peaks in radiation safety monitoring. Data retention burdens weigh heaviest on occupational health applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's dense cluster of university hospitals and nuclear medicine centers anchors European demand for high-accuracy dosimetry systems. The city's radiology departments are expanding real-time badge deployment ahead of Euratom directive deadlines.
United States
Interventional cardiology volume at Cleveland Clinic and Mayo Clinic campuses is mandating per-procedure dose tracking for cath lab staff. The FDA's updated fluoroscopy guidance tightens badge utilization documentation requirements. Texas Medical Center in Houston integrates dosimetry data directly into physician credentialing systems with privilege suspension protocols.
Germany
Deutsche Klinik für Diagnostik and Charité Berlin are consolidating multi-site dosimetry contracts under unified reporting frameworks. The country's national regulator enforces Medical Device Regulation compliance for cross-border worker monitoring. Bavaria's nuclear power maintenance corridor between Gundremmingen and Isar demands redundant monitoring layers for high-dose zones.
Japan
Tokyo's cyclotron facilities and radioisotope production sites require specialized neutron-sensitive badge configurations. METI standards govern occupational exposure limits for nuclear medicine technicians. Osaka's cancer centers are adopting optically stimulated luminescence verification for linear accelerator quality assurance programs.
India
Private hospital chains in Mumbai, Delhi, and Bangalore are installing PET-CT capacity without established vendor relationships. The Central Drugs Standard Control Organization regulates medical device imports for radiation safety equipment. Telangana's diagnostic imaging corridor around Hyderabad is creating first-mover positioning opportunities for accredited service providers.
France
Gustave Roussy and Institut Curie are expanding badge deployment density for radiation therapy departments. ANSM enforces dose record harmonization for multinational nuclear operators under Euratom directives. The nuclear medicine cluster around Lyon and Grenoble concentrates demand for real-time electronic monitoring systems.
Radiation Monitoring and Dosimeter Badges Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology sophistication spectrum. The vendor base stratifies between integrated service providers with recurring calibration revenue and hardware-focused manufacturers competing on unit economics. Three archetypes dominate: nuclear heritage specialists leveraging power plant credibility, laboratory instrumentation conglomerates controlling distribution channels, and regional service contractors anchoring local compliance relationships. Consolidation is accelerating through accredited laboratory acquisitions, while portfolio diversification into AI-enabled predictive analytics represents the second dominant competitive vector.
Within the nuclear heritage tier, Mirion Technologies Inc. and Polimaster Ltd. occupy positions shaped by high-reliability segment credibility. Thermo Fisher Scientific Inc. exemplifies the laboratory channel control archetype through integrated instrumentation portfolios. Landauer Inc. anchors the North American service-contract model with recurring calibration revenue streams.
| Leading Market Players |
|---|
| Radiation Detection Company |
| Fuji Electric Co., Ltd. |
| Mirion Technologies Inc. |
| Polimaster Ltd. |
| Ludlum Measurements Inc. |
| Landauer Inc. |
| Unfors RaySafe |
| Tracerco Limited |
| Thermo Fisher Scientific Inc. |
| Others |
Value Network & Pricing Analysis
Lithium fluoride crystal pricing cascades from East Asian specialty chemical zones through passive dosimeter manufacturing tiers, with thermoluminescent material costs separating premium hospital-grade badges from industrial commodity units. This input concentration grants calibrated-laboratory networks pricing power over hardware-focused manufacturers competing on per-unit economics.
Pricing Analysis
Real-time alert capability anchors value-based pricing for interventional radiology and nuclear medicine workflows, where immediate dose intervention justifies premium positioning over passive batch-read alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification grade, wireless connectivity sophistication, and calibration chain documentation depth. Cost compression in standard-tier passive badges intensifies as group purchasing organizations unbundle hardware from analysis services. Community health systems exhibit highest price sensitivity, while academic medical centers prioritize accuracy and integration over per-unit cost.
Supply Chain Analysis
FDA and NRC accreditation requirements gate entry to the US hospital procurement channel, filtering unqualified component suppliers from downstream badge assembly. Thermoluminescent crystal production clusters in Japan and China, optically stimulated luminescence substrate fabrication concentrates in Germany and the United States, and solid-state sensor packaging anchors in South Korean electronics foundries. Single-source vulnerability in lithium fluoride supply creates exposure to East Asian logistics disruptions. Distribution runs through accredited dosimetry service laboratories that control calibration infrastructure and regulatory documentation chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
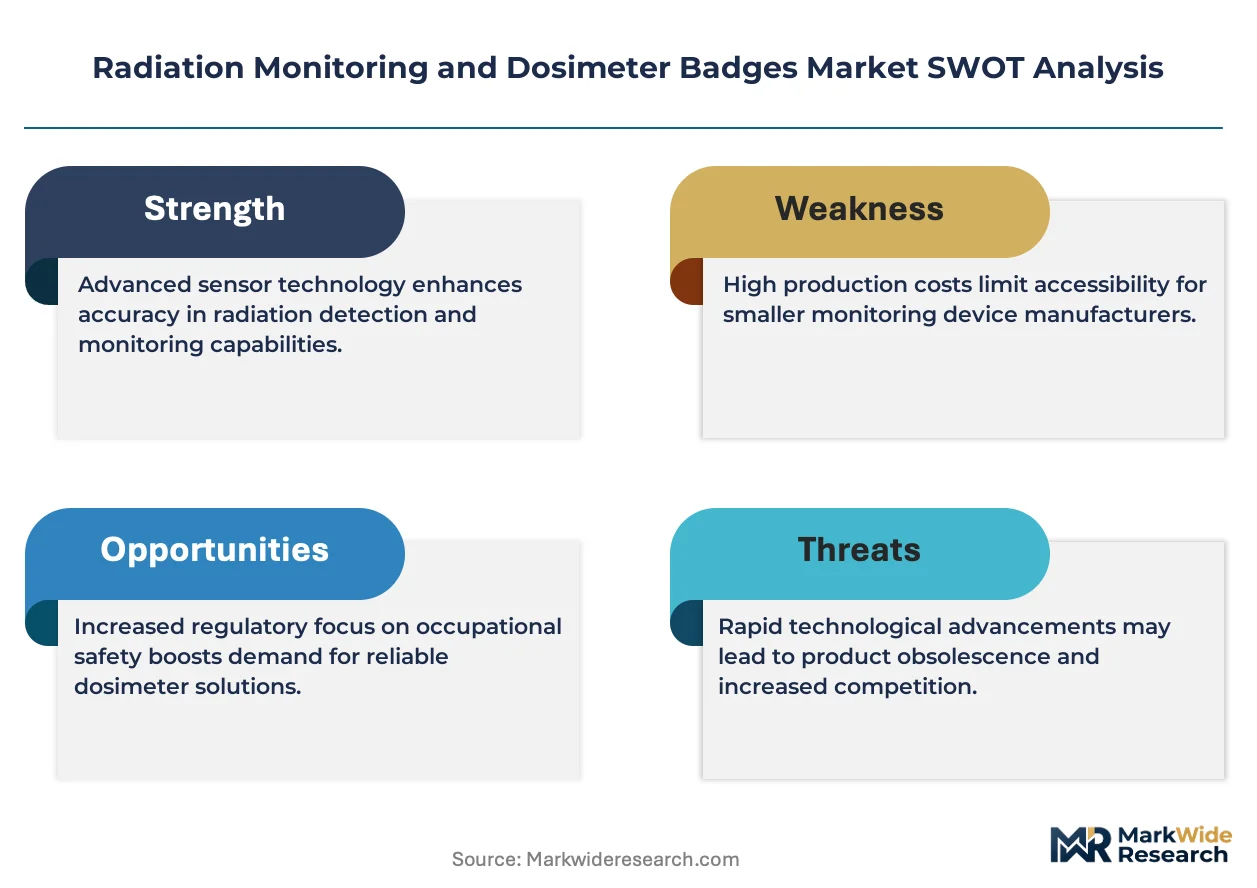
Electronic real-time dosimetry is displacing passive badge technology in high-dose clinical environments, compressing switching cycles and forcing legacy service providers toward predictive analytics differentiation.
For Market Incumbents: To counter electronic badge vendors capturing interventional radiology procurement, passive dosimeter specialists must deepen calibration laboratory networks and integrate AI-enabled exposure trending into service contracts. Backward integration into OSL crystal production reduces East Asian supply vulnerability. Channel control through exclusive hospital system partnerships retains pricing power against hardware commoditization.
For New Entrants and Emerging Players: Direct-to-hospital digital platforms bypass established service-contract relationships in India's diagnostic imaging expansion corridor. Private hospital chains in Mumbai, Delhi, and Bangalore lack entrenched vendor ties, creating first-mover positioning for accredited providers offering integrated electronic monitoring with local calibration support. Remote industrial radiography contractors represent an underserved segment requiring offline-capable passive systems with minimal infrastructure dependency.
For Investors and Strategic Acquirers: FDA guidance mandating badge utilization documentation is the leading indicator that compliance-tech integration will separate viable acquisition targets from stranded assets. Long-term viability favors accredited laboratories with recurring calibration revenue streams and software companion development capability. Consolidation through regional service provider acquisition accelerates market share capture. The signal to monitor is hospital system unbundling of hardware procurement from analysis services, which compresses integrated provider margins and forces specialization.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Predictive Analytics Development | Machine learning integration with electronic badge data enables anticipatory workflow adjustments before cumulative thresholds trigger alerts. |
| Accredited Laboratory Acquisition | Regional calibration infrastructure purchases consolidate service-contract relationships and create barriers to unqualified entrants under FDA requirements. |
| Hospital System Partnership Expansion | Direct relationships with Texas Medical Center and Cleveland Clinic campuses bypass group purchasing organization margin compression. |
| OSL Crystal Production Integration | In-house aluminum oxide substrate manufacturing reduces dependency on East Asian specialty chemical supply clusters. |
| Home Healthcare Monitoring Extension | Portable radiopharmaceutical administration networks create new addressable market beyond institutional walls. |
Research Methodology
Multi-period observation of fluoroscopy procedure volumes, badge deployment density, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with hospital biomedical engineers, GPO contracts managers, medical physicists, and dosimetry service laboratory directors. Secondary validation drew from FDA guidance documents, NRC dose record databases, hospital procurement contracts, and Euratom directive implementation reports. Bottom-up facility-level deployment estimates triangulated against top-down market sizing from accredited service provider revenue disclosures.
Input-output matrices mapped detection modality adoption rates against end-user regulatory exposure severity across the projection horizon. Segmentation dimensions modeled include technology type, application environment, and healthcare system scale tier. CAGRs derived from procedure volume growth trajectories, regulatory mandate implementation timelines, and technology substitution elasticities. Forecast inputs incorporated interventional cardiology expansion rates and nuclear medicine imaging volume projections without year-specific anchoring.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time electronic badge pricing transparency introduce uncertainty bands around premium-tier market sizing. Forecasts reflect modeling assumptions about regulatory enforcement consistency and technology substitution pace. A model refresh is warranted upon material change in FDA fluoroscopy guidance implementation or East Asian lithium fluoride supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Law Enforcement and Military Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market