
 Biometric Scan Software Market | 2026-2036
Biometric Scan Software Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Scan Software Market Analysis
Healthcare access control is decoupling from legacy password systems as hospitals deploy biometric workstations. NEC Corporation anchors large-scale government identity projects across multiple continents. Thales differentiates through integrated civil ID and border management platforms. IDEMIA sustains R&D intensity in multimodal biometric fusion algorithms.
Biometric scan software comprises algorithmic engines that extract, encode, and match unique biological traits against enrolled templates using minutiae pattern analysis or neural embedding vectors, typically operating with false acceptance rates below 0.001% for high-security deployments. Fingerprint recognition occupies the largest installed base due to mature sensor economics and established forensic interoperability. Facial recognition represents the fastest expansion vector as liveness detection and 3D depth sensing mitigate spoofing vulnerabilities. Machine learning underpins next-generation accuracy gains while cloud computing enables scalable authentication-as-a-service delivery.
The EU AI Act classifies remote biometric identification as high-risk, mandating conformity assessments before market deployment. India's BIS certification requirements and UIDAI standards govern Aadhaar-compatible software specifications. Stakeholders must monitor evolving interoperability mandates between national ID systems and private-sector authentication platforms.
Market Dynamics
The EU AI Act's high-risk classification for remote biometric identification is forcing immediate architectural redesigns across algorithmic transparency and audit trail capabilities. Compliance investments now consume disproportionate engineering bandwidth relative to feature development cycles.
Growth Catalysts
- Financial Services Authentication Mandates:Banking regulators across Germany, Singapore, and Brazil now require multi-factor biometric verification for high-value transactions, expanding enterprise software procurement pipelines.
- India's Aadhaar-Linked Ecosystem:UIDAI's authentication volume targets for welfare distribution and digital payments create sustained demand for certified biometric middleware vendors.
- 3D Depth Sensing Maturation:Structured light and time-of-flight sensor cost curves enable liveness detection deployment at price points viable for mid-tier smartphone manufacturers.
Market Restraints
- Algorithm Training Data Concentration:High-quality facial datasets with proper demographic diversity reside with fewer than ten commercial entities, creating vendor lock-in risks.
- Silicon Supply Fragility:Specialized biometric sensor ASICs depend on Taiwan-based foundry capacity subject to geopolitical contingency planning.
- Template Storage Interoperability Gaps:ISO/IEC 19794-2 fingerprint minutiae formats remain inconsistently implemented across legacy government identity systems, complicating multi-vendor deployments.
Strategic Opportunities
- Healthcare Workstation Biometrics:HIPAA-covered entities in the US Midwest and Southeast hospital networks remain underpenetrated for palm-vein and iris-based access control systems.
- Edge AI Convergence:On-device neural inference engines combined with federated learning architectures enable privacy-preserving authentication without cloud dependency.
- EU Digital Identity Wallet Mandate:eIDAS 2.0 framework incentives accelerate demand for interoperable biometric verification modules in member state digital infrastructure procurements.
Industry Challenges
- Adversarial Attack Defense:Deepfake injection and presentation attack sophistication outpaces academic research-to-productization cycles for commercial liveness detection vendors.
- Cross-Border Certification Fragmentation:India's BIS testing protocols, US NIST evaluations, and EU notified body assessments impose redundant validation costs without mutual recognition agreements.
- Legacy System API Integration:Mainframe-based banking cores and decades-old physical access control hardware lack modern biometric plugin architectures, requiring expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Scan Software Market |
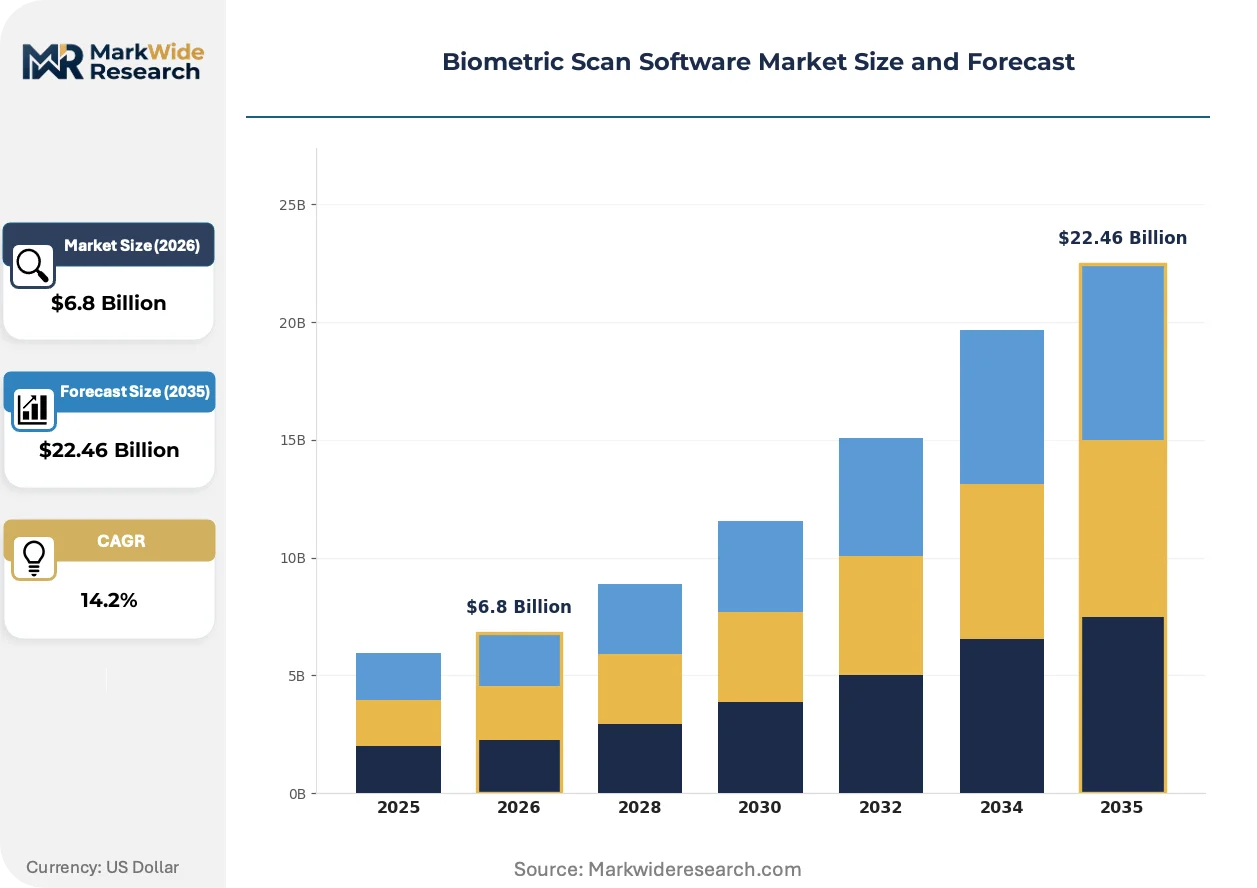
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition End User: Government, Financial Institutions, Healthcare, Retail Technology: Artificial Intelligence, Image Processing, Machine Learning, Cloud Computing Application: Identity Verification, Access Control, Time Management, Fraud Prevention |
| Companies Covered | Aware Inc., NEC Corporation, Thales, IDEMIA, ImageWare Systems Inc., Corvus Integration Inc., TECH5, Fulcrum Biometrics, Bayometric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Scan Software Market Emerging Trajectories
Algorithmic architectures are fragmenting from centralized cloud inference toward distributed processing models. This shift compresses latency budgets while expanding addressable use cases beyond network-dependent environments.
On-device neural embedding generation is decentralizing authentication logic from hyperscale data centers to edge silicon. Automotive OEMs in Germany and Japan now specify biometric driver monitoring systems with local inference to satisfy GDPR data minimization principles. This topology eliminates round-trip latency for real-time drowsiness detection while reducing cloud egress cost exposure.
The EU AI Act's conformity assessment requirements are restructuring vendor go-to-market timelines. Biometric identification systems must complete notified body reviews before EU market deployment, extending product launch cycles by 8-14 months. French and Dutch healthcare procurement authorities now embed AI Act compliance certificates as mandatory bid evaluation criteria.
Enterprise buyers are consolidating authentication vendor relationships to reduce integration complexity. Large US retailers and logistics operators now issue multi-year framework agreements spanning physical access, workforce management, and customer-facing identity verification. This procurement compression favors platform vendors with multimodal algorithm portfolios over point-solution specialists.
Biometric Scan Software Market Segmentation
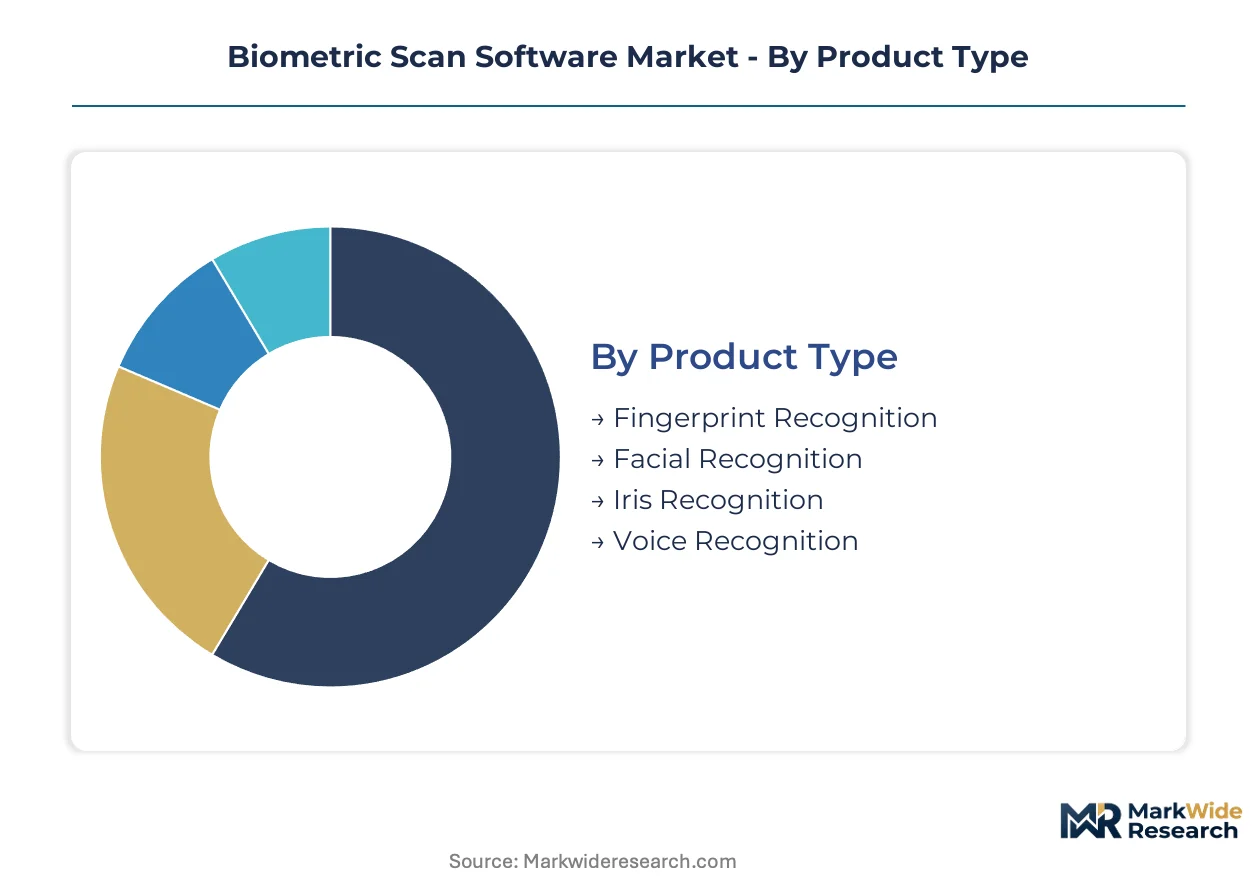
Biometric scan software vendors configure algorithmic engines around distinct biological modalities, each demanding specialized sensor integration and template storage architectures. Segmentation clarity enables procurement teams to match false acceptance rate specifications against deployment environment risk profiles.
Product Type:
Supply concentration in minutiae extraction libraries and neural embedding frameworks varies sharply across biometric modalities, with mature sensor ecosystems dominating volume production.
- Fingerprint Recognition:Minutiae pattern matching against ISO/IEC 19794-2 templates remains the most deployed architecture, with capacitive and ultrasonic sensor costs now viable for mid-tier device integration. Demand concentrates in India's Aadhaar authentication infrastructure, where UIDAI certification requirements lock in specific algorithmic vendors.
- Facial Recognition:Neural embedding vectors generated through deep convolutional architectures enable 1:N identification at scale, though liveness detection against presentation attacks consumes disproportionate R&D bandwidth. German automotive OEMs and Singaporean banking regulators now mandate 3D depth sensing for high-assurance deployments.
- Iris Recognition:Textured pattern encoding delivers the lowest false acceptance rates among mainstream modalities, limiting addressable markets to high-security government and data center applications.
- Voice Recognition:Spectral feature extraction against text-dependent or text-independent utterances occupies niche authentication scenarios where hands-free operation is mandatory.
Fingerprint recognition absorbs the bulk of installed capacity; facial recognition is expanding most quickly.
End User:
Procurement sophistication and compliance burden intensity diverge across buyer categories, with regulated industries imposing certification requirements that filter vendor participation.
- Government:National ID systems and border management platforms require algorithmic transparency documentation under EU AI Act high-risk classifications, extending sales cycles but securing multi-year revenue visibility.
- Financial Institutions:Multi-factor biometric verification for high-value transactions is now mandated by banking regulators in Germany, Singapore, and Brazil, creating sustained enterprise software procurement pipelines.
- Healthcare:HIPAA-covered entities in the US Midwest and Southeast hospital networks are decoupling access control from legacy password systems, driving demand for palm-vein and iris-based workstation authentication.
- Retail:Customer-facing identity verification for loyalty program authentication and frictionless checkout remains experimental, with privacy litigation risk constraining deployment velocity.
Government deployments anchor vendor revenue stability; financial institutions are climbing the fastest as regulatory mandates harden.
Technology:
Algorithmic architecture choices determine inference latency, template storage requirements, and audit trail capabilities that regulators now scrutinize under conformity assessment frameworks.
- Artificial Intelligence:Deep learning architectures for feature extraction and matching have displaced classical computer vision approaches in facial and behavioral biometric modalities, though training data concentration with fewer than ten commercial entities creates vendor lock-in exposure.
- Image Processing:Classical filtering, enhancement, and segmentation operations remain embedded in fingerprint and iris preprocessing pipelines where computational efficiency outweighs accuracy gains from neural approaches.
- Machine Learning:Support vector machines and random forest classifiers persist in resource-constrained edge deployments where neural inference would exhaust battery or thermal budgets.
- Cloud Computing:Authentication-as-a-service delivery enables scalable template storage and matching without capital-intensive data center investment, though GDPR data minimization principles and EU AI Act audit requirements complicate cross-border processing architectures.
Artificial intelligence commands the steepest R&D allocation; cloud computing is gaining share fastest as edge-to-cloud hybrid topologies mature.
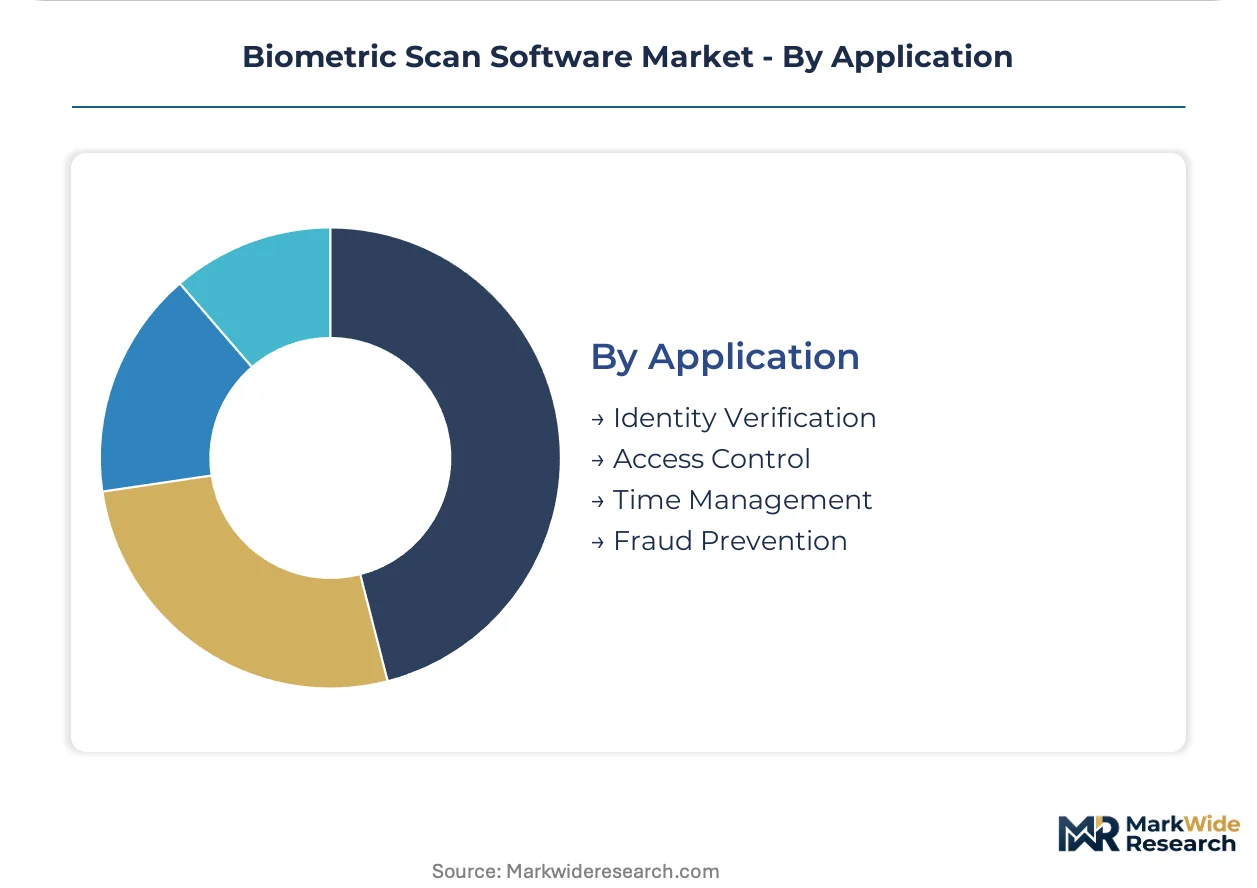
Application:
Use case specificity drives template storage location decisions, latency tolerance thresholds, and integration complexity with legacy identity management infrastructure.
- Identity Verification:1:1 matching against government-issued credentials underpins India's Aadhaar-linked welfare distribution and digital payment authentication, with BIS certification and UIDAI standards governing software specifications.
- Access Control:Physical and logical entry management for healthcare facilities, data centers, and corporate campuses requires liveness detection integration to mitigate tailgating and credential sharing vulnerabilities.
- Time Management:Workforce attendance tracking represents a price-sensitive segment where fingerprint modalities dominate due to mature sensor economics, though privacy litigation in European jurisdictions constrains deployment expansion.
- Fraud Prevention:Presentation attack detection and synthetic identity screening in financial services demand the highest algorithmic accuracy tiers, with NIST evaluation participation now table stakes for vendor credibility.
Identity verification absorbs the bulk of transaction volume; fraud prevention is expanding most quickly as deepfake sophistication accelerates defense procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of biometric scan software concentrates in the United States, Japan, and France, while consumption clusters in India, Germany, and Brazil where regulatory mandates and digital identity infrastructure drive deployment velocity.
United States
HIPAA-covered hospital networks in the Midwest and Southeast are decoupling access control from legacy password systems. The FDA maintains oversight of biometric devices used in clinical settings, though software algorithms fall under broader FTC consumer protection frameworks. Boston and Austin host concentrated development clusters where vendors engineer palm-vein and iris-based workstation authentication systems.
India
UIDAI's authentication volume targets for welfare distribution and digital payments create sustained demand for certified biometric middleware. BIS certification requirements and UIDAI standards govern Aadhaar-compatible software specifications, filtering vendor participation. Bengaluru and Hyderabad anchor development centers where vendors optimize fingerprint and iris matching engines for billion-scale 1:N identification.
Germany
Automotive OEMs in Stuttgart and Munich now specify biometric driver monitoring systems with local edge inference to satisfy GDPR data minimization principles. The KBA coordinates with EU AI Act implementation timelines for vehicle-integrated identification systems. Frankfurt's financial regulator mandates multi-factor biometric verification for high-value transactions, expanding enterprise procurement pipelines.
France
The CNIL enforces strict conformity assessment timelines under EU AI Act high-risk classifications, extending product launch cycles by 8-14 months. Paris hosts NEC Corporation's European civil ID project coordination center. Healthcare procurement authorities in Lyon and Marseille now embed AI Act compliance certificates as mandatory bid evaluation criteria.
Brazil
ANVISA regulates biometric devices deployed in healthcare settings while the central bank mandates multi-factor verification for high-value financial transactions. São Paulo anchors Latin America's largest concentration of banking technology procurement, with Banco Central do Brasil driving authentication standardization. Rio de Janeiro hosts government identity project offices specifying facial recognition for border management platforms.
Biometric Scan Software Market Vendor Landscape
Top-tier vendors anchor government and financial services contracts, while mid-tier specialists compete on modality-specific accuracy benchmarks and regional certification speed. The vendor base organizes around three strategic archetypes: platform vendors with multimodal algorithm portfolios, point-solution specialists in single biometric modalities, and systems integrators bundling hardware-software packages. Dominant competitive moves include geographic expansion into India's Aadhaar-certified vendor pool and technology licensing partnerships to accelerate EU AI Act compliance documentation.
Within the platform vendor tier, NEC Corporation and Thales exemplify integrated civil ID and border management positioning, while IDEMIA occupies a position in multimodal biometric fusion algorithm development. Aware Inc. and ImageWare Systems Inc. represent North American software-focused archetypes, with TECH5 and Fulcrum Biometrics anchoring specialized middleware and sensor integration segments respectively.
| Leading Market Players |
|---|
| Aware Inc. |
| NEC Corporation |
| Thales |
| IDEMIA |
| ImageWare Systems Inc. |
| Corvus Integration Inc. |
| TECH5 |
| Fulcrum Biometrics |
| Bayometric |
| Others |
Supply Flow & Price Mechanics
UIDAI's mandatory BIS certification for Aadhaar-compatible software compresses vendor pools and forces supply chains toward pre-qualified algorithmic libraries, elevating pricing power for certified middleware providers while squeezing uncertified competitors into commodity tiers.
Pricing Analysis
Short lead-time premiums for EU AI Act conformity documentation now separate urgent deployment budgets from standard procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and audit trail depth, with government buyers absorbing premium tiers while mid-tier smartphone manufacturers drive cost compression in liveness detection modules. Price differentiation hinges on ISO/IEC 19794-2 template interoperability and NIST evaluation participation. Pricing pressure stems from Taiwan foundry capacity constraints on biometric sensor ASICs. Retail and logistics operators exhibit highest price sensitivity; government identity projects demonstrate lowest.
Supply Chain Analysis
India's domestic-content mandates for Aadhaar ecosystem participation redirect algorithmic development toward Bengaluru and Hyderabad engineering centers. Algorithmic engine production concentrates in the United States, Japan, and France; sensor ASIC fabrication draws from Taiwan and South Korea. Specialized inputs include structured light modules, time-of-flight sensors, and neural training datasets. Single-source vulnerability around Taiwan-based foundry capacity exposes delivery timelines. Distribution runs through systems integrators bundling hardware-software packages for government and financial services procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints on certified biometric middleware prop pricing premiums, with UIDAI vendor pool limits and EU AI Act conformity bottlenecks creating durable scarcity for compliant algorithm providers.
For Market Incumbents: Hedge against algorithm training data concentration risks by securing exclusive licensing agreements with demographic-diverse dataset curators. Expand backward integration into edge AI silicon to reduce Taiwan foundry dependency. Prioritize R&D in adversarial attack defense as deepfake sophistication accelerates.
For New Entrants and Emerging Players: Federated learning architectures for privacy-preserving authentication offer entry into HIPAA-covered US hospital networks still decoupling from legacy password systems. Target Midwest and Southeast healthcare access control as the most penetrable white-space segment. Pursue EU Digital Identity Wallet certification as a go-to-market anchor for member state procurement.
For Investors and Strategic Acquirers: The window for entry favors multimodal biometric fusion specialists with existing BIS or NIST credentials. Mid-cap algorithm vendors with government contract visibility and R&D intensity in liveness detection present viable acquisition profiles across a multi-year horizon. Monitor EU AI Act notified body assessment backlogs as an inflection signal for compliance-service demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Notified body assessments now gate EU market access for remote biometric identification systems. |
| Multimodal Algorithm Portfolio Expansion | Enterprise buyer consolidation favors vendors spanning fingerprint, facial, and iris modalities. |
| India Aadhaar Certification Pursuit | UIDAI standards filter vendor participation in billion-scale authentication infrastructure. |
| Edge AI Inference Development | Automotive OEMs in Germany specify local processing to satisfy GDPR data minimization. |
| Adversarial Defense R&D Intensification | Deepfake injection sophistication outpaces commercial liveness detection productization cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biometric software engineering leads, government identity project managers, hospital biomedical engineers, financial services authentication officers, and hyperscaler cloud procurement specialists. Secondary sources encompassed UIDAI technical specifications, EU AI Act implementing texts, NIST evaluation reports, BIS certification databases, and SEC disclosures from publicly traded vendors. Bottom-up algorithm vendor revenue aggregation reconciled against top-down national ID procurement budget analysis.
Data-stream reconciliation across shipment volumes, certification timelines, and procurement award values informed projection modeling across the analysis window. Segmentation dimensions spanned biometric modality, end-user vertical, deployment architecture, and regional regulatory cluster. CAGRs derived from algorithmic adoption curves weighted against compliance investment cycles and sensor cost trajectories. Forecast inputs incorporated Aadhaar authentication volume targets and EU Digital Identity Wallet implementation schedules.
Several conditions sit outside the modeled scope, including geopolitical contingency effects on Taiwan foundry capacity, adversarial attack breakthroughs rendering liveness detection obsolete, and mutual recognition agreements collapsing cross-border certification fragmentation. Forecasts reflect documented assumptions regarding regulatory timeline adherence and training data availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometrics Software Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
North America Enterprise Biometrics Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
Biometric Passport Market