
 Automated Machine Learning Market | 2026-2036
Automated Machine Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Machine Learning Market Intelligence
The capital-intensity divergence between hyperscaler-backed platforms and independent software vendors is redrawing competitive boundaries in automated machine learning. Microsoft Azure AutoML leverages its cloud infrastructure to embed AutoML within broader enterprise workflows. DataRobot sustains its position through specialized model governance tools that appeal to regulated industries. Google Cloud AI competes by integrating AutoML with its proprietary tensor processing hardware.
Automated machine learning denotes software systems that algorithmically automate the selection, training, and optimization of machine learning models without requiring manual intervention by data scientists; these systems typically handle feature engineering, hyperparameter tuning, and model validation through neural architecture search or Bayesian optimization pipelines. Cloud-based deployment leads in enterprise adoption due to elastic compute scaling and reduced infrastructure overhead, while edge computing represents the fastest-growing segment as manufacturers deploy real-time anomaly detection on production lines. The solution dimension shows predictive analytics capturing the deepest margin pools because enterprise buyers pay premiums for forecast accuracy in supply chain and revenue planning.
The EU AI Act imposes risk-based classification requirements on automated decision systems, compelling vendors to embed explainability and audit trails into their platforms. The US Food and Drug Administration scrutinizes AutoML-derived diagnostic algorithms under software-as-a-medical-device pathways, slowing healthcare deployment timelines. ISO and IEC standards for artificial intelligence management systems are gaining traction as procurement prerequisites in European public-sector tenders. Stakeholders must monitor regulatory divergence between jurisdictions to avoid architectural lock-in that complicates cross-border deployment.
Market Dynamics
The EU AI Act's risk-based classification system is forcing vendors to rearchitect platforms for explainability and auditability, compressing development timelines while opening procurement pathways in regulated European sectors.
Growth Catalysts
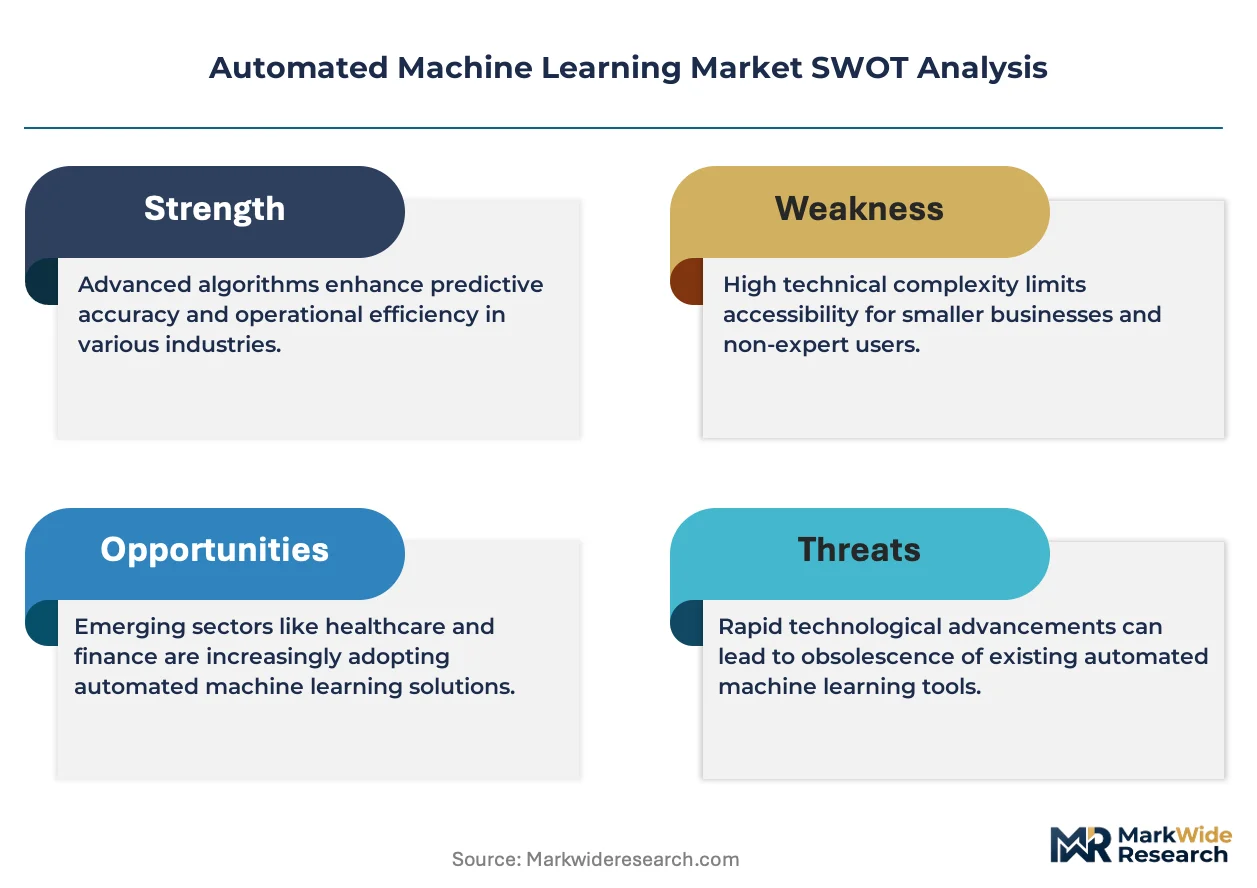
- EU AI Act compliance mandates:Risk classification requirements for automated decision systems create procurement pull from European financial services and healthcare providers seeking pre-certified platforms.
- Edge computing deployment:Manufacturers integrate real-time anomaly detection directly onto production equipment, eliminating latency penalties from cloud round-trips.
- Neural architecture search maturation:Algorithmic model optimization reduces data scientist labor hours per deployment, lowering total cost of ownership for mid-market enterprises.
Market Restraints
- GPU supply concentration:Training pipeline acceleration depends on semiconductor fabrication capacity concentrated in Taiwan and South Korea, creating input bottlenecks.
- FDA software-as-medical-device pathways:Diagnostic algorithm validation timelines extend healthcare deployment schedules by 18-36 months compared to non-regulated sectors.
- Interpretability-versus-performance tradeoffs:Explainable model architectures sacrifice predictive accuracy, limiting adoption in high-stakes forecasting applications.
Strategic Opportunities
- ISO/IEC AI management system standards:Certification requirements in European public-sector tenders create vendor differentiation for compliant platforms.
- Small language model convergence:Compressed architectures deploy on edge hardware without cloud dependency, opening manufacturing and agricultural applications.
- India's digital public infrastructure:Unified Payments Interface data streams enable fraud detection AutoML deployment across banking and fintech sectors.
Industry Challenges
- MLOps engineering scarcity:Production-grade model monitoring and drift detection require specialized talent pools concentrated at hyperscalers.
- Cross-border regulatory fragmentation:Divergent explainability requirements between EU AI Act and FDA guidance complicate unified platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Machine Learning Market |
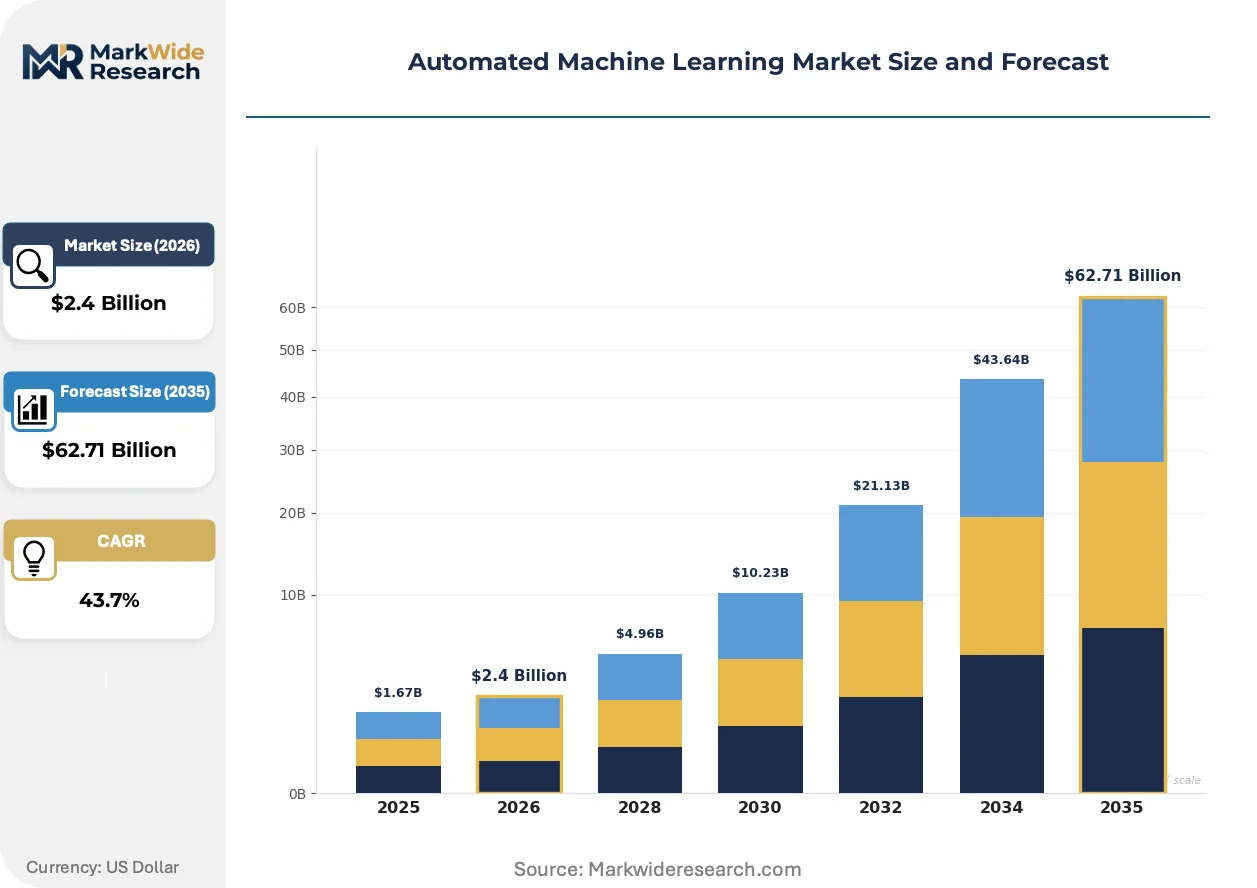
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $62.71 Billion |
| CAGR (2026 – 2036) | 43.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Financial Services, Healthcare, Retail, Manufacturing Solution: Fraud Detection, Predictive Analytics, Customer Insights, Workflow Automation Application: Image Recognition, Natural Language Processing, Time Series Forecasting, Anomaly Detection |
| Companies Covered | H2O.ai, Microsoft Azure AutoML, DataRobot, SAS Viya, Databricks, Google Cloud AI, IBM Watsonx, Alteryx, Amazon SageMaker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Machine Learning Market Strategic Shifts & Innovations
Automated machine learning platforms are bifurcating between hyperscaler-integrated stacks and specialized governance tools, with architectural choices increasingly dictated by regulatory exposure rather than pure performance benchmarks.
Neural architecture search is fragmenting model development workflows by automating hyperparameter optimization and network topology selection. Pharmaceutical firms deploy these tools for molecular property prediction, compressing discovery timelines. The technology is fragmenting competitive moats previously held by elite data science teams.
The EU AI Act's high-risk system designation triggers conformity assessment obligations for credit scoring and recruitment algorithms. Vendors embed automated documentation pipelines to satisfy audit trail requirements. Financial services buyers in Germany and France now mandate explainability dashboards as standard procurement clauses.
Enterprise buyers now unbundle model development from operational deployment, selecting best-of-breed components rather than end-to-end platforms. This pattern disrupts traditional software licensing in favor of usage-based consumption. North American manufacturing verticals exhibit the fastest migration toward modular procurement.
Automated Machine Learning Market Segmentation
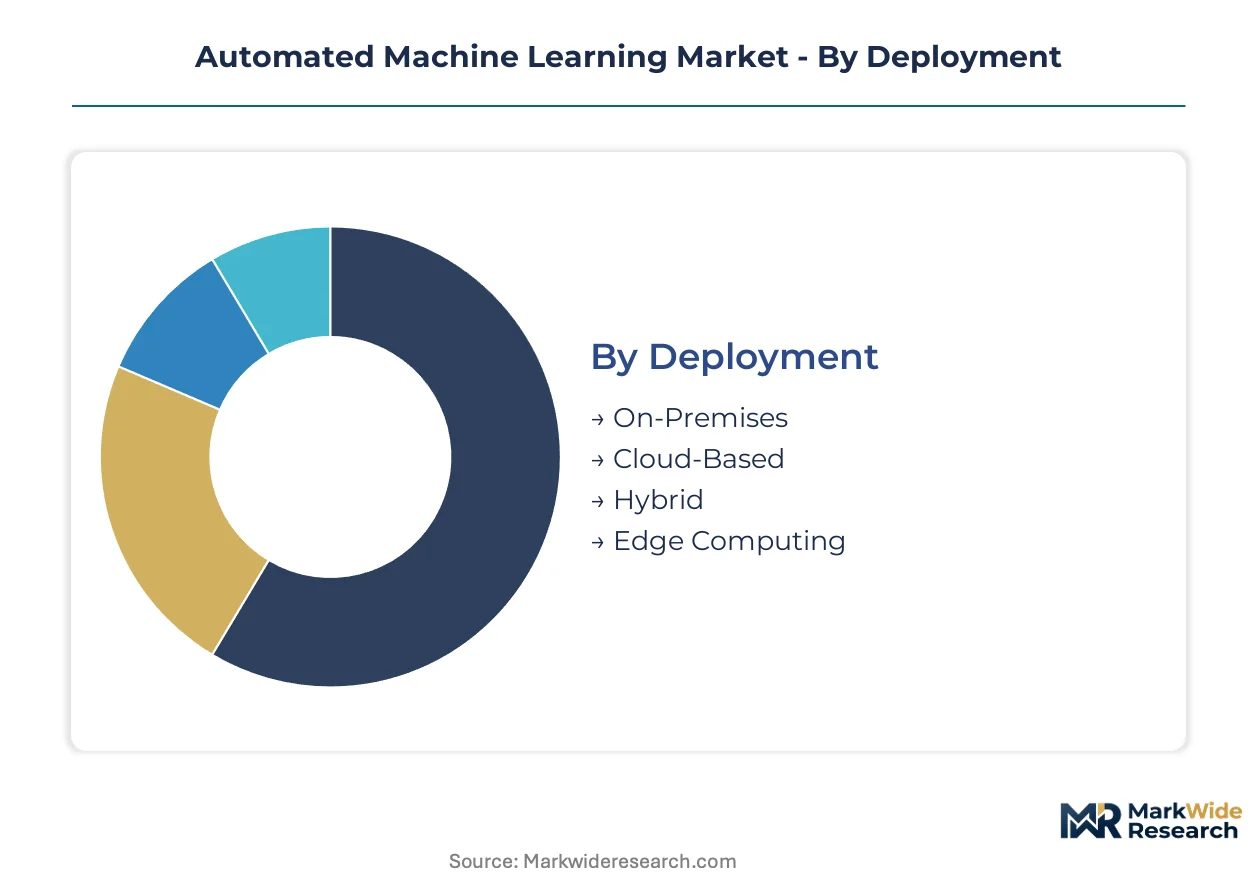
Segmentation in automated machine learning reveals how architectural choices cascade into procurement patterns. Buyers select deployment modes and solution types based on latency tolerance, regulatory exposure, and existing cloud commitments rather than algorithmic performance alone.
Deployment:
Margin pools concentrate in cloud-based configurations where hyperscalers bundle compute with platform licensing, while edge deployments command premium pricing for latency-critical manufacturing use cases.
- On-Premises:Self-managed infrastructure within enterprise data centers satisfies financial services firms with data sovereignty mandates. Demand clusters among German and Swiss banking consortia responding to national financial regulator requirements for domestic data residency.
- Cloud-Based:Elastic compute scaling through vendor-managed infrastructure dominates enterprise adoption. Procurement concentrates in United States technology corridors where venture-backed firms prioritize speed-to-deployment over capital expenditure control.
- Hybrid:Split workloads between private infrastructure and public cloud balance compliance with flexibility. Japanese automotive suppliers favor this model for protecting proprietary design data while leveraging cloud-based model training.
- Edge Computing:Real-time inference on production equipment eliminates network latency. South Korean semiconductor fabs deploy these configurations for wafer defect detection at line speed.
Cloud-based holds installed capacity. Edge computing is rotating up the share rankings.
End User:
Application complexity and regulatory burden determine customer lifetime value across verticals, with healthcare and financial services sustaining the longest implementation cycles.
- Financial Services:Algorithmic trading and credit risk modeling drive platform sophistication requirements. United States regional banks under OCC supervision deploy AutoML for anti-money laundering while managing model risk management framework compliance.
- Healthcare:Diagnostic imaging and clinical decision support impose FDA software-as-medical-device validation timelines. Mayo Clinic and Cleveland Clinic anchor demand for explainable model architectures that satisfy clinical workflow integration standards.
- Retail:Demand forecasting and dynamic pricing optimization prioritize speed over interpretability. Walmart and Target procurement teams evaluate platforms on SKU-level prediction accuracy rather than regulatory documentation depth.
- Manufacturing:Predictive maintenance and quality control applications favor edge-deployed inference. Siemens and Bosch facilities in Bavaria integrate AutoML with existing SCADA infrastructure for real-time equipment monitoring.
Financial services holds installed capacity. Healthcare is rotating up the share rankings.
Solution:
Revenue concentration follows problem complexity, with fraud detection commanding premium pricing due to regulatory scrutiny and direct profit impact.
- Fraud Detection:Real-time transaction scoring with sub-100 millisecond latency requirements. India's Unified Payments Interface transaction volume drives adoption among Mumbai and Bangalore fintech clusters seeking RBI-compliant anomaly detection.
- Predictive Analytics:Supply chain and revenue forecasting applications prioritize accuracy metrics. Amazon and FedEx procurement teams evaluate vendors on out-of-sample forecast error reduction across seasonal demand patterns.
- Customer Insights:Segmentation and churn prediction for marketing automation. European retailers under GDPR constraints demand differential privacy guarantees in customer data processing pipelines.
- Workflow Automation:Document classification and routing for operational efficiency. United Kingdom National Health Service trusts deploy these tools for patient referral processing within NHS Digital interoperability frameworks.
Fraud detection holds installed capacity. Predictive analytics is rotating up the share rankings.
Application:
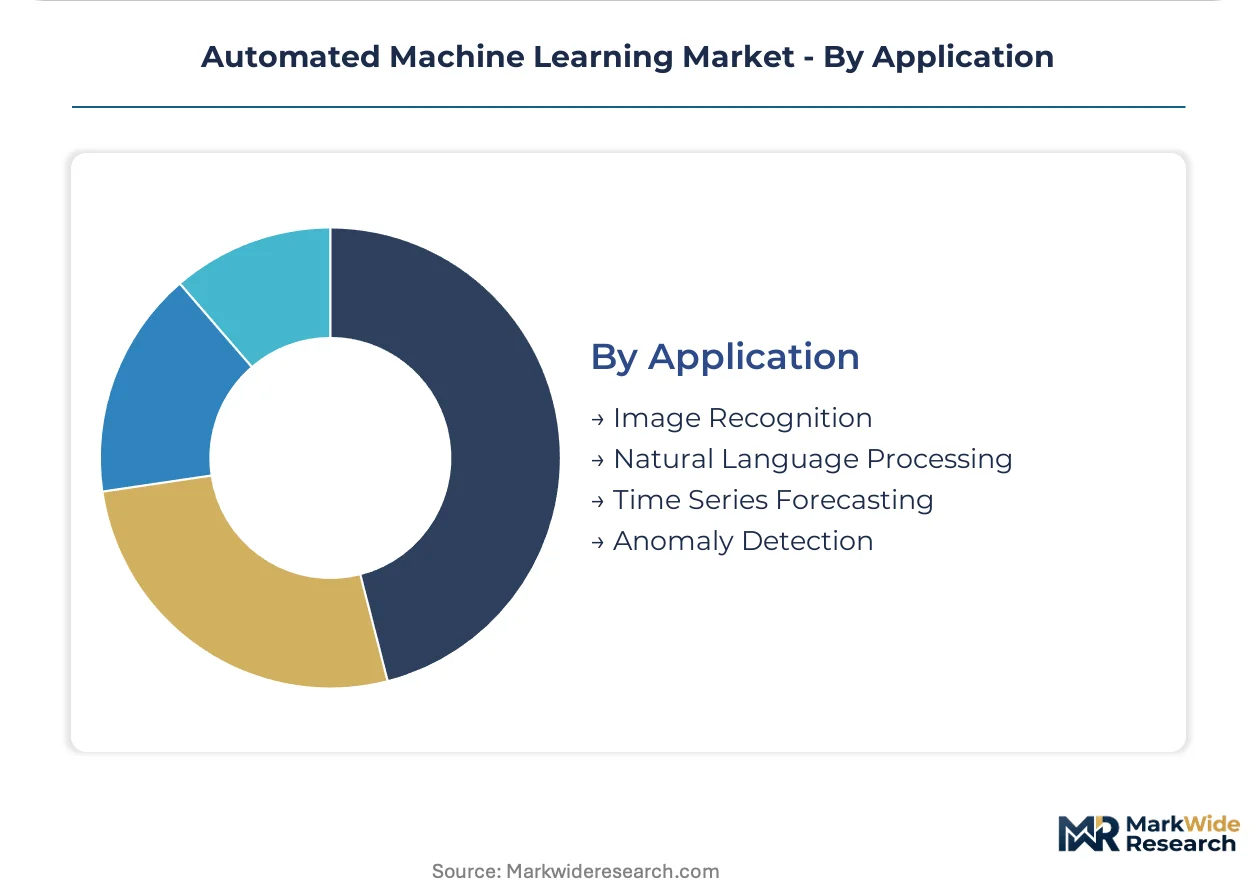
Technical maturity varies widely, with image recognition achieving production reliability while natural language processing remains experimentation-heavy.
- Image Recognition:Convolutional neural network architectures for visual inspection and medical imaging. Tesla and BYD manufacturing lines deploy these systems for battery cell quality verification at gigafactory scale.
- Natural Language Processing:Transformer-based models for document understanding and sentiment analysis. Bloomberg and Reuters terminal teams prioritize financial news classification with entity extraction accuracy benchmarks.
- Time Series Forecasting:Recurrent and attention-based architectures for sequential data. California ISO and ERCOT grid operators evaluate platforms on electricity demand prediction accuracy during extreme weather events.
- Anomaly Detection:Unsupervised learning for identifying deviations in operational data. Saudi Aramco upstream operations deploy these models for wellhead pressure monitoring under SAMR environmental compliance requirements.
Image recognition holds installed capacity. Natural language processing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland exhibit the lowest price elasticity, absorbing premium pricing for compliance-embedded platforms, while Indian fintech clusters drive the steepest cost compression through open-source toolchains and cloud-native deployment.
United States
Venture-backed enterprises in Silicon Valley and Boston prioritize speed-to-deployment over licensing costs, fueling hyperscaler platform adoption. FDA software-as-medical-device pathways extend validation timelines for diagnostic algorithms by 18-36 months. Mayo Clinic in Minnesota anchors demand for explainable model architectures in clinical workflows.
Germany
Automotive suppliers and banking consortia demand ISO/IEC AI management system certifications as procurement prerequisites. BaFin national financial regulator requirements mandate domestic data residency for credit scoring algorithms. Bavarian manufacturing clusters around Munich integrate AutoML with SCADA infrastructure for real-time equipment monitoring.
India
Unified Payments Interface transaction volumes exceeding 10 billion monthly transactions drive fraud detection AutoML deployment across Mumbai and Bangalore fintech clusters. RBI compliance mandates for real-time anomaly detection create procurement pull from neobanks. Hyderabad's technology corridor hosts specialized model governance talent pools serving domestic and export markets.
United Kingdom
NHS Digital interoperability frameworks standardize document classification and patient referral processing automation. Financial Conduct Authority scrutiny of algorithmic credit decisions compels explainability dashboard investments. London's quantitative hedge funds deploy neural architecture search for high-frequency trading signal generation.
South Korea
Semiconductor fabs demand sub-10 millisecond inference latency for wafer defect detection at production line speed. MFDS medical device regulations shape diagnostic algorithm deployment timelines in Seoul hospital networks. Samsung and SK Hynix manufacturing complexes in Gyeonggi Province anchor edge computing AutoML adoption.
Automated Machine Learning Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with hyperscaler-backed platforms dominating scale economics while specialized vendors capture premium pricing through governance tooling. The market structure consolidates around cloud-integrated stacks with a fragmented tier of vertical specialists. Three archetypes define competitive positioning: infrastructure-embedded platforms, compliance-specialized independents, and open-source commercializers. Dominant competitive moves include strategic partnerships with semiconductor fabricators and geographic expansion through regulatory pre-certification in European jurisdictions.
Within the infrastructure-embedded tier, Microsoft Azure AutoML and Google Cloud AI exemplify hyperscaler leverage through compute-platform bundling. DataRobot occupies a position among compliance-specialized independents serving regulated industries with model governance differentiation. These three anchors represent the archetype spectrum from scale-driven cloud integration to premium governance tooling.
| Leading Market Players |
|---|
| H2O.ai |
| Microsoft Azure AutoML |
| DataRobot |
| SAS Viya |
| Databricks |
| Google Cloud AI |
| IBM Watsonx |
| Alteryx |
| Amazon SageMaker |
| Others |
Cost & Logistics Intelligence
Hyperscaler cloud capacity utilization above eighty percent creates scale economies that compress price floors for independent AutoML vendors while elevating switching costs for enterprise buyers. Taiwan Semiconductor Manufacturing and Samsung Foundry fabrication constraints cascade through GPU availability, tethering platform pricing power to semiconductor supply schedules and cloud reservation commitments.
Pricing Analysis
Extended support and model governance service contracts generate the highest lifetime value ratios among enterprise AutoML deployments. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler-integrated stacks with bundled compute from specialized governance tools and open-source commercializers. Price differentiation rests on ISO/IEC AI management system certification tier and vertical-specific compliance embedding. Cost compression in the mid-market tier is intensifying because Indian fintech clusters deploy open-source toolchains with cloud-native orchestration. Retail procurement teams exhibit the lowest price sensitivity, absorbing premium licensing for forecast accuracy guarantees in seasonal demand planning.
Supply Chain Analysis
Inventory lead times for NVIDIA H100 and AMD MI300X accelerators stretch twelve to eighteen months, constraining training pipeline throughput for vendors without cloud reservation guarantees. GPU supply concentrates in Taiwan and South Korea, with advanced packaging capacity anchored in Malaysia and Vietnam. Raw material dependencies span high-bandwidth memory from SK Hynix and Micron, advanced substrates from Unimicron and Ibiden, and rare earth elements for magnetics in cooling systems. Single-source vulnerability around TSMC CoWoS packaging capacity threatens platform scaling timelines. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with European public-sector tenders requiring certified channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated machine learning exhibits defensive moat characteristics rooted in regulatory entrenchment—EU AI Act conformity assessment obligations and FDA software-as-medical-device pathways create switching costs that cement incumbent positions.
For Market Incumbents: Fortify platform stickiness through embedded model governance tooling that satisfies BaFin domestic data residency mandates and FDA audit trail requirements. Deepen backward integration into specialized silicon by securing allocation agreements with TSMC and Samsung Foundry for training accelerator capacity. Threat: Open-source commercializers erode mid-market pricing power through cloud-native deployment patterns. For New Entrants and Emerging Players: Differentiate on edge-optimized small language model architectures that deploy without cloud dependency for South Korean semiconductor fabs and German automotive suppliers. Target India's Unified Payments Interface fraud detection segment, where RBI compliance mandates create procurement pull for pre-certified anomaly detection platforms. Go-to-market: Partner with Mumbai and Bangalore systems integrators possessing existing banking relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compliance-specialized independents serving German banking consortia and United States regional banks under OCC supervision. Long-term viability favors vendors with ISO/IEC AI management system certification traction in European public-sector tenders. Acquisition target archetype: Model governance tooling specialists with BaFin and FDA validation pathways. Signal to watch: Edge computing deployment velocity in manufacturing verticals as indicator of architectural shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification | EU AI Act conformity assessment opens procurement pathways in German and French financial services. |
| Semiconductor Fabricator Partnership | GPU allocation agreements with TSMC secure training pipeline capacity against supply bottlenecks. |
| Edge-Optimized Model Compression | Small language model architectures enable real-time inference on production equipment without cloud dependency. |
| Vertical Specialist Acquisition | Model governance tooling targets BaFin and FDA compliance requirements in regulated industries. |
| Geographic Expansion Through Certification | ISO/IEC AI management system standards create vendor differentiation in European public-sector tenders. |
Research Approach
A standing panel of AutoML platform engineers, enterprise IT procurement officers, financial services model risk managers, and healthcare regulatory affairs leads provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against hyperscaler capex disclosures, FDA software-as-medical-device filing databases, EU AI Act implementation guidance documents, and RBI fintech compliance circulars. Bottom-up deployment estimates triangulated against top-down cloud infrastructure spending patterns.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler earnings call commentary and European public-sector tender award databases. The analytical framework segmented across deployment model, organization size, vertical regulatory exposure, integration complexity, and regional adoption pattern throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to enterprise technology adoption histories, with inputs including GPU supply forecasts from semiconductor equipment manufacturers and regulatory timeline assumptions from EU and FDA guidance documents.
Material uncertainties—GPU fabrication capacity constraints, EU AI Act enforcement variance, and FDA diagnostic algorithm pathway revisions—sit outside the modeled envelope. Forecasts reflect assumptions about cloud migration velocity and regulatory harmonization that may shift with macroeconomic conditions or geopolitical developments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market