
 Cloud Machine Learning Market | 2026-2036
Cloud Machine Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Machine Learning Market Analysis
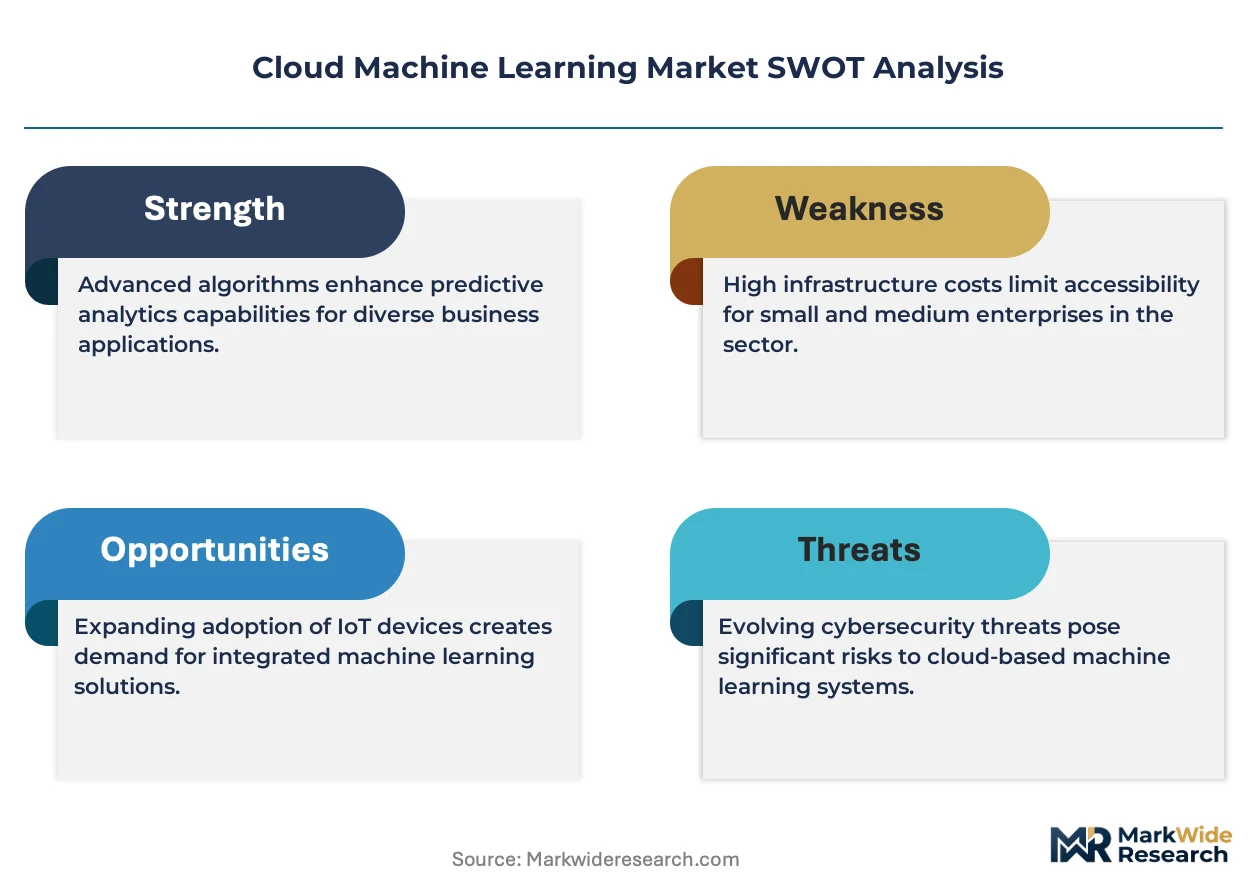
The EU AI Act is hardening compliance thresholds for cloud-hosted machine learning workloads, forcing providers to re-architect data governance and audit trails. Amazon Web Services leverages its global infrastructure footprint to pre-certify regions for regulated workloads. Microsoft Azure anchors enterprise trust through its compliance portfolio spanning ISO, SOC, and sector-specific frameworks.
Cloud machine learning denotes the delivery of algorithmic training, inference, and model management capabilities via distributed computing infrastructure accessed over networks. These platforms abstract GPU clusters, tensor processing units, and auto-scaling orchestration layers so organizations can execute neural network workloads without owning physical silicon. The service segment captures the fastest expansion as managed offerings reduce talent barriers for mid-market adopters. Hybrid cloud deployments are gaining structural share where data residency requirements collide with burst-compute needs for large foundation model training.
FDA scrutiny of machine learning in medical devices, FCC net-neutrality rulings affecting cloud transit costs, and SEC guidance on AI-generated investment advice collectively reshape where models train versus where they deploy. GDPR data-localization mandates in Europe and China's GB standards for algorithmic recommendation systems add further jurisdictional complexity. Stakeholders must map regulatory perimeters before committing inference architecture to specific cloud regions.
Market Dynamics
Foundation model training clusters are consolidating into hyperscaler-controlled GPU farms, concentrating computational sovereignty among three infrastructure operators while fragmenting access economics for mid-market enterprises.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making audit requirements are forcing financial services firms to migrate inference workloads onto certified cloud substrates, expanding addressable market for governed ML services.
- FDA digital health pre-certification pathway:Streamlined review for software-as-medical-device is accelerating clinical AI deployment onto cloud-native infrastructure, opening regulated healthcare verticals previously blocked by on-premise validation burdens.
- Tensor processing unit cost-performance curves:Specialized silicon architectures are collapsing training economics for computer vision and natural language workloads, enabling model proliferation among capital-constrained research institutions.
Market Restraints
- NVIDIA GPU supply concentration:Taiwan Semiconductor Manufacturing dependency for advanced node fabrication creates single-point-of-failure exposure for training infrastructure scaling timelines.
- GDPR data-localization enforcement:European regulators are prohibiting cross-border model training on personal data, fragmenting dataset liquidity and inflating regional infrastructure duplication costs.
- On-premise inference latency advantages:Edge-deployed neural accelerators are capturing real-time applications where cloud round-trip penalties degrade user experience, constraining cloud ML addressable market in autonomous systems.
Strategic Opportunities
- Sovereign cloud mandates in Germany and France:National data residency requirements are creating protected procurement pools for EU-headquartered providers with domestic infrastructure footprints.
- Federated learning architectures:Distributed training protocols enabling model improvement without centralizing raw data are unlocking regulated industries—healthcare, defense intelligence—previously inaccessible due to classification barriers.
- SEC climate disclosure rules:Mandatory Scope 3 emissions reporting is accelerating demand for carbon-aware compute scheduling, creating differentiation for providers with renewable-powered training clusters.
Industry Challenges
- MLOps engineering talent scarcity:Production-grade model monitoring, drift detection, and automated retraining pipelines require specialized practitioners whose supply lags demand by estimated 40% in North American technology hubs.
- Model provenance documentation:Training data lineage, versioning, and bias audit trails must satisfy multiple regulatory frameworks simultaneously—EU AI Act, FDA QSR, ISO 42001—creating compliance engineering bottlenecks.
- Hybrid architecture integration friction:Enterprises maintaining sensitive data on-premise while bursting training to cloud require seamless orchestration layers that most legacy IT organizations lack capability to architect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Machine Learning Market |
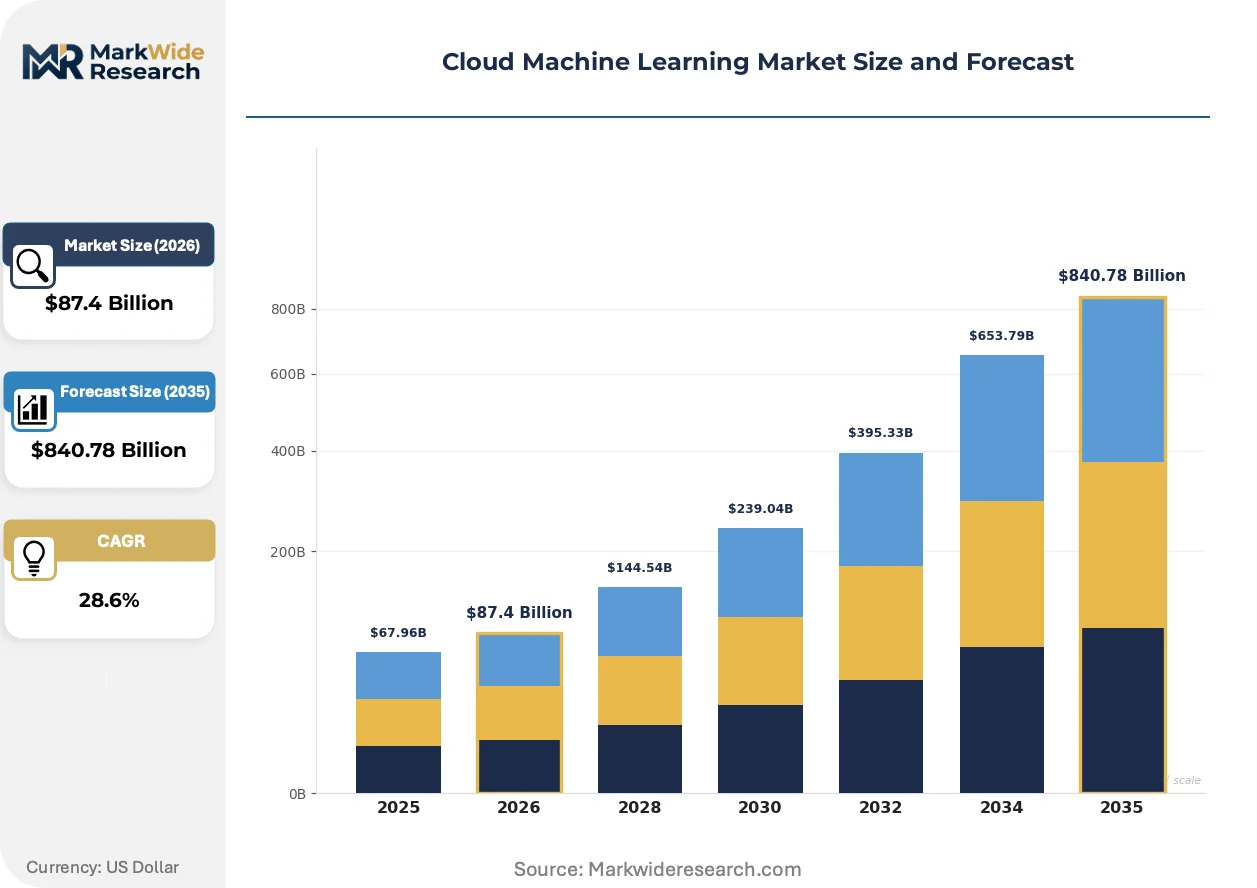
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $840.78 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platform, Framework, Service, Tool End User: Enterprise, Developer, Data Scientist, Research Institution Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Application: Predictive Analytics, Natural Language Processing, Computer Vision, Recommendation Systems |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Watson, Oracle Cloud Infrastructure, Databricks, DataRobot, H2O.ai, Alibaba Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Machine Learning Market Emerging Trajectories
Model-serving infrastructure is fragmenting from monolithic platforms into composable microservices, enabling buyers to assemble specialized pipelines rather than accepting vendor-determined capability bundles.
Serverless GPU inference is modularizing how enterprises consume neural compute, allowing machine learning teams to deploy models without provisioning persistent clusters. Mid-market SaaS vendors are adopting this pattern fastest, converting fixed infrastructure costs into variable consumption aligned with query volume. The shift is compressing time-to-production for computer vision and recommendation applications from quarters to weeks.
China's GB standards for algorithmic recommendation systems are mandating interpretability disclosures and user opt-out mechanisms for cloud-hosted inference services. Domestic providers must architect explainability pipelines into production workflows, increasing engineering overhead but creating compliance moats against foreign competitors. Consumer internet platforms are responding by segmenting model versions—fully transparent for regulated jurisdictions, opaque optimized variants elsewhere.
Consumption-based pricing is displacing reserved instance commitments as the dominant procurement mode for training workloads. Enterprise data science teams are rejecting long-term capacity contracts in favor of spot-market compute access, forcing providers to develop dynamic pricing engines. This pattern is most pronounced among biotechnology startups in Boston and San Francisco, where grant-funded research cycles resist capital-intensive infrastructure planning.
Cloud Machine Learning Market Segmentation
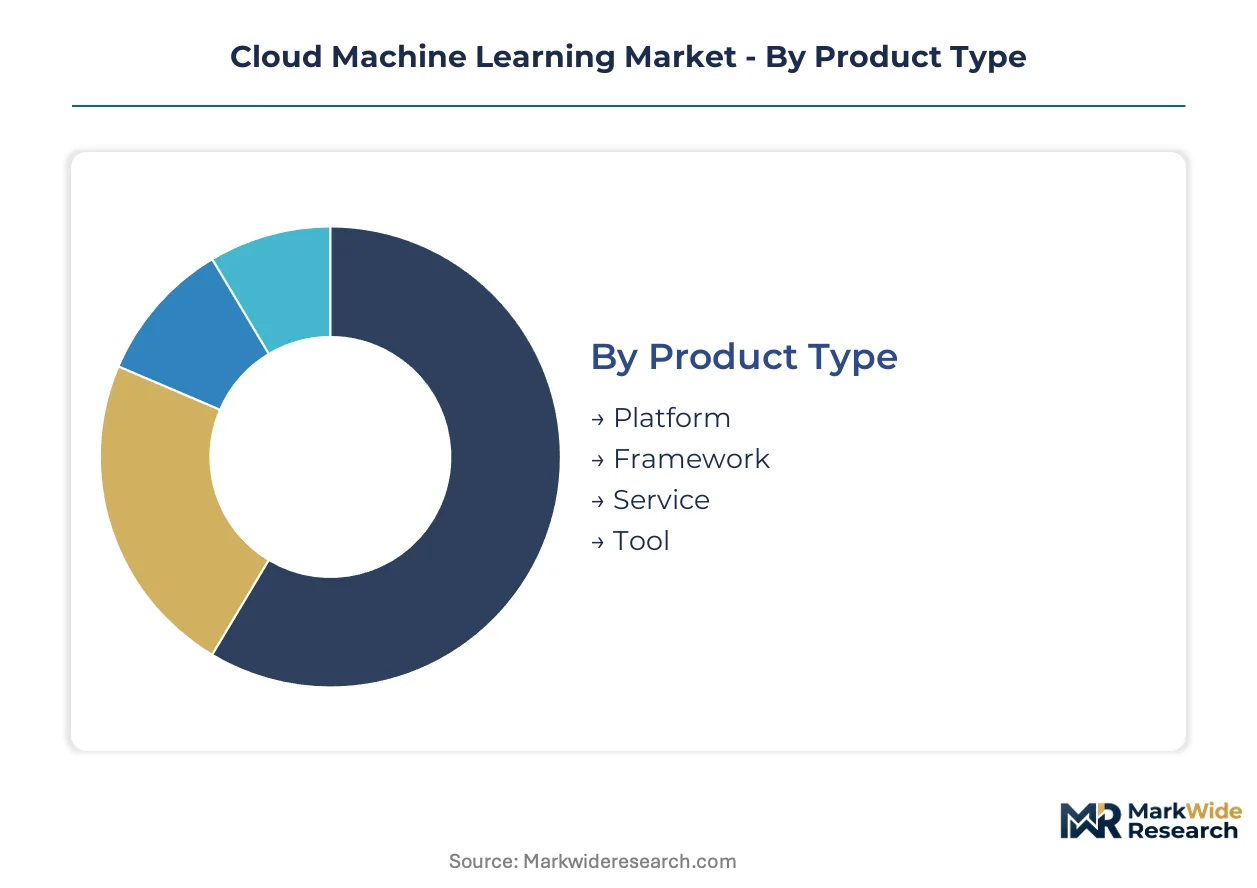
Cloud machine learning segmentation reveals how capital allocation, compliance requirements, and workload characteristics fragment purchasing patterns across infrastructure tiers. Buyers optimize across GPU provisioning models, data residency constraints, and model serving architectures that each demand distinct commercial and technical evaluation frameworks.
Product Type:
Platform offerings demand the heaviest upfront engineering investment, while services and tools lower barriers through consumption-based economics.
- Platform:Integrated environments bundling compute orchestration, model versioning, and experiment tracking into unified control planes. Financial services firms in the United States concentrate procurement here to satisfy SEC audit requirements for algorithmic trading systems.
- Framework:Open-source libraries and abstraction layers—TensorFlow, PyTorch, JAX—that standardize neural network construction across hardware backends. Research institutions in Germany and France leverage these to maintain portability between cloud regions under GDPR constraints.
- Service:Managed APIs for speech recognition, translation, and vision tasks billed per inference call. Mid-market SaaS vendors in Boston and San Francisco adopt these fastest to compress time-to-production.
- Tool:Specialized utilities for data labeling, feature engineering, and model monitoring that slot into broader MLOps pipelines.
Platform absorbs the bulk of installed capacity; Service is expanding most quickly.
End User:
Procurement authority concentrates with enterprise IT governance functions, while developer and researcher segments drive experimental adoption that later validates enterprise commitments.
- Enterprise:Fortune 500 technology, healthcare, and financial services organizations with centralized cloud centers of excellence. These buyers negotiate reserved capacity contracts and demand ISO 42001 compliance documentation for EU AI Act readiness.
- Developer:Individual engineers and small product teams accessing serverless inference APIs through corporate procurement cards. Their consumption patterns are shifting from reserved instances to spot-market compute access.
- Data Scientist:Specialized practitioners requiring notebook environments, distributed training clusters, and experiment tracking. MLOps engineering talent scarcity constrains how quickly this segment can operationalize models.
- Research Institution:Universities and national laboratories training foundation models on government grants. Tensor processing unit cost-performance curves are collapsing training economics for this capital-constrained segment.
Enterprise commands the largest committed spend; Developer segments are climbing the fastest as self-service tooling proliferates.
Deployment:
Data residency mandates and latency requirements fragment architectural choices across sovereignty-conscious and performance-sensitive use cases.
- Public Cloud:Shared infrastructure pools delivering auto-scaling GPU clusters and managed MLOps pipelines. Hyperscalers pre-certify regions for regulated workloads to capture EU AI Act-driven migration.
- Private Cloud:Dedicated single-tenant environments isolating training data from multi-tenant attack surfaces. Healthcare systems deploy here to satisfy FDA digital health pre-certification pathway requirements.
- Hybrid Cloud:Architectures maintaining sensitive data on-premise while bursting training to cloud. GDPR data-localization enforcement is fragmenting dataset liquidity and inflating infrastructure duplication costs for this pattern.
- Multi-Cloud:Workload distribution across AWS, Azure, and GCP to avoid vendor lock-in and optimize spot pricing. This pattern demands sophisticated orchestration layers most legacy IT organizations lack capability to architect.
Public Cloud holds dominant share; Hybrid Cloud is gaining structural share where data residency requirements collide with burst-compute needs.
Application:
Regulatory scrutiny intensity and compute intensity vary dramatically across use cases, reshaping where models train versus where they deploy.
- Predictive Analytics:Statistical and machine learning models forecasting demand, risk, and operational outcomes. Financial services firms are expanding adoption here, with automated decision-making audit requirements forcing migration onto certified cloud substrates.
- Natural Language Processing:Foundation model training and fine-tuning for text generation, classification, and extraction. China's GB standards for algorithmic recommendation systems mandate interpretability disclosures that increase engineering overhead.
- Computer Vision:Image classification, object detection, and segmentation for medical imaging and autonomous systems. FDA scrutiny of machine learning in medical devices reshapes validation burdens for cloud-native deployment.
- Recommendation Systems:Collaborative filtering and content-based algorithms for consumer internet platforms. Domestic Chinese providers architect explainability pipelines to create compliance moats against foreign competitors.
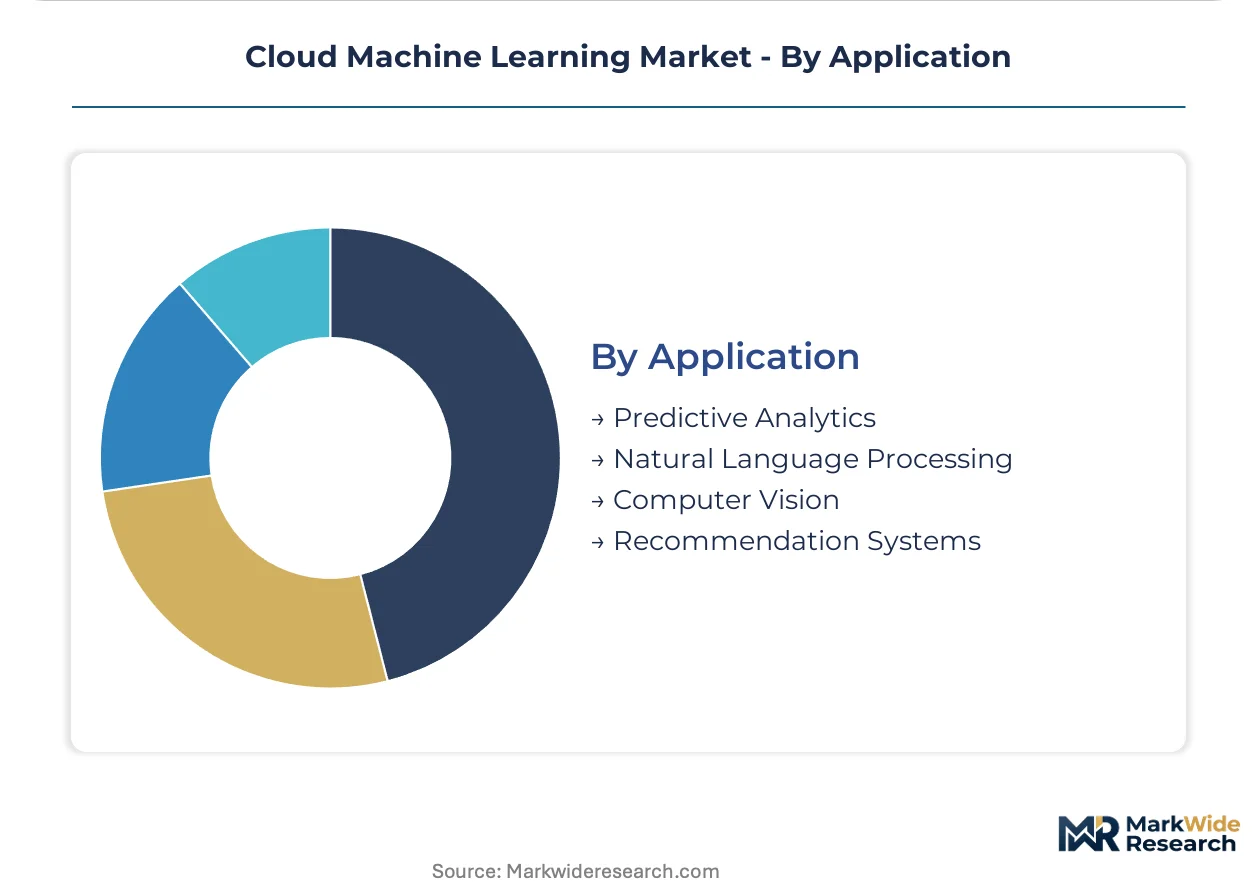
Predictive Analytics retains the largest installed base; Natural Language Processing is on the steepest expansion trajectory as foundation model proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate cloud machine learning infrastructure investment through tax holidays and duty exemptions on GPU imports. These zones anchor hyperscaler expansion decisions. Regulatory divergence across jurisdictions fragments where models train versus deploy.
United States
Financial services firms in New York and Chicago expand predictive analytics procurement, with SEC guidance on AI-generated investment advice forcing audit trail upgrades. FDA scrutiny of machine learning in medical devices reshapes validation burdens for Boston and San Francisco health-tech clusters. Hyperscaler infrastructure investments scale fastest in Northern Virginia and Oregon data center corridors.
Germany
Automotive OEMs in Stuttgart and Munich deploy computer vision workloads for quality inspection, with sovereign cloud mandates creating protected procurement pools for domestic providers. EU AI Act compliance thresholds harden requirements for automated decision-making audit trails. The Rhine-Ruhr industrial belt concentrates federated learning pilots for supply chain optimization without centralizing proprietary design data.
China
Consumer internet platforms in Beijing and Hangzhou segment model versions to satisfy GB standards for algorithmic recommendation systems. MIIT cloud service licensing requirements constrain foreign provider market access. The Yangtze River Delta anchors domestic hyperscaler expansion as Shanghai and Suzhou build AI-dedicated data center capacity.
United Kingdom
London-based fintechs adopt serverless GPU inference for real-time fraud detection, with FCA expectations on model explainability influencing procurement criteria. Research institutions in Cambridge and Oxford leverage tensor processing unit cost-performance curves for foundation model training on government grants. The UK-EU data transfer framework uncertainty fragments training dataset liquidity.
India
Bengaluru and Hyderabad host GCCs of US technology firms expanding managed ML service consumption. RBI guidelines on AI in credit decisioning force audit architecture upgrades for Mumbai-based lenders. PLI scheme incentives for semiconductor assembly attract GPU packaging investments to Gujarat and Tamil Nadu.
Cloud Machine Learning Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across infrastructure, platform, and application layers. Hyperscalers leverage global data center footprints to pre-certify regions for regulated workloads, while vertical specialists anchor trust through sector-specific compliance documentation. Three archetypes dominate: full-stack infrastructure operators, managed service intermediaries, and domain-specific application vendors. Competitive moves concentrate on strategic partnerships with silicon fabricators and geographic expansion through sovereign cloud deployments.
Within the infrastructure tier, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify full-stack operators whose global region certification strategies capture EU AI Act-driven migration demand. These entities anchor enterprise procurement through compliance portfolios spanning ISO, SOC, and sector-specific frameworks. Databricks occupies a position bridging platform and service archetypes for mid-market adopters seeking reduced talent barriers.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Watson |
| Oracle Cloud Infrastructure |
| Databricks |
| DataRobot |
| H2O.ai |
| Alibaba Cloud |
| Others |
Supply Flow & Price Mechanics
MLOps engineering talent scarcity in Northern Virginia and San Francisco Bay Area data center corridors widens pricing-tier spreads between premium managed services and commodity compute pools. Labor-cost differentials between hyperscaler-certified regions and secondary markets compress margins for mid-tier providers while concentrating pricing power with infrastructure operators controlling scarce GPU provisioning expertise.
Pricing Analysis
Short lead-time premiums for NVIDIA H100 clusters command substantial markups over spot-market reserved capacity, with financial services firms in New York paying steep premiums for immediate inference deployment. Three-tier pricing structure across premium certified, standard managed, and economy spot levels segments buyer archetypes by compliance urgency and workload criticality. Cost compression in economy tiers is intensifying because biotechnology startups in Boston increasingly reject long-term contracts in favor of dynamic spot access. Enterprise IT governance functions show lowest price sensitivity due to audit-trail requirements, while individual developers accessing serverless APIs through procurement cards drive race-to-the-bottom pressure on per-inference rates.
Supply Chain Analysis
Advanced packaging engineer availability in Taiwan, South Korea, and Arizona constrains how quickly TSMC and Samsung can scale CoWoS capacity for AI accelerators. Taiwan Semiconductor Manufacturing draws from photoresist chemicals sourced from Japan, palladium substrates from Russia and South Africa, and specialized epoxy molding compounds from China. Single-source vulnerability around TSMC's 3nm node dominance creates concentration risk for training infrastructure scaling timelines. Distribution runs through direct hyperscaler procurement contracts and secondary channel partners serving research institutions with grant-funded purchasing cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model training cluster availability functions as the binding capacity constraint, with NVIDIA GPU supply concentration propping pricing power for infrastructure operators controlling scarce silicon allocation.
For Market Incumbents: Anticipate regulatory fragmentation by pre-certifying additional sovereign cloud regions before EU AI Act enforcement hardens compliance thresholds. Defend margin position through backward integration into custom silicon development, reducing dependency on TSMC allocation cycles. Channel control through exclusive partnerships with national research laboratories in Germany and France locks out mid-market competitors lacking compliance documentation depth. For New Entrants and Emerging Players: EU AI Act in Germany and France opens a window for domestic providers with sovereign infrastructure footprints to capture protected procurement pools. Target federated learning architectures for healthcare and defense intelligence segments previously inaccessible due to classification barriers. Go-to-market through partnerships with MLOps engineering consultancies in Bengaluru and Hyderabad bypasses direct hyperscaler competition on raw compute pricing. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists anchoring trust through FDA digital health pre-certification documentation given clinical AI deployment acceleration. Long-term viability favors platform-layer vendors bridging infrastructure and application tiers with proprietary experiment tracking and model monitoring capabilities. Watch hyperscaler capex guidance revisions as the inflection signal for whether GPU supply constraints ease or deepen.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Deployment | EU AI Act compliance mandates in Germany and France create protected procurement pools for domestic infrastructure operators. |
| Custom Silicon Development | Google Cloud's TPU cost-performance curves reduce training economics dependency on NVIDIA allocation cycles. |
| Federated Learning Partnership | Distributed training protocols unlock healthcare and defense verticals blocked by data classification barriers. |
| Carbon-Aware Compute Scheduling | SEC climate disclosure rules differentiate providers with renewable-powered training clusters in Oregon and Northern Virginia. |
| MLOps Platform Integration | Databricks and DataRobot reduce talent barriers for mid-market SaaS vendors compressing time-to-production. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cloud machine learning market assessment. Primary interviews with cloud center of excellence directors, MLOps engineering leads, biomedical researchers, and hyperscaler solution architects combined with bottom-up triangulation against SEC 10-K capex disclosures, EU AI Act implementation guidance, and FDA digital health pre-certification pathway documentation. Top-down validation cross-checked against hyperscaler infrastructure investment announcements and national AI strategy white papers from Germany's BMWK and China's MIIT.
Granularity-level modeling deployed separate forecast tracks for platform, framework, service, and tool product types crossed with enterprise, developer, data scientist, and research institution end-user segments. Deployment architecture splits across public, private, hybrid, and multi-cloud patterns incorporated GDPR data-localization enforcement intensity and FDA scrutiny of machine learning in medical devices as regulatory overlay dimensions. CAGRs derived from elasticity-adjusted adoption curves reflecting tensor processing unit cost-performance improvements and serverless GPU inference penetration rates across biotechnology startup clusters in Boston and San Francisco.
Caveats apply where NVIDIA GPU supply concentration or Taiwan Semiconductor Manufacturing capacity allocation could materially shift the outlook. Forecasts reflect assumptions about EU AI Act enforcement timelines, FDA digital health pre-certification pathway throughput, and hyperscaler infrastructure investment sustainability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Speech-To-Text API Market