
 Global Computational Creativity Market | 2026-2036
Global Computational Creativity Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computational Creativity Market Foresight
A shortage of trained generative AI specialists is redrawing competitive boundaries across the sector. NVIDIA leverages its GPU infrastructure to dominate training workloads for visual art generation models. Adobe anchors its position through deep integration of generative features into established creative workflows. OpenAI competes by extending large language model capabilities into interactive narrative and automated storytelling domains.
Computational creativity encompasses software systems that autonomously generate or assist in producing novel artistic, design, or narrative outputs through algorithmic processes, typically employing neural networks trained on extensive corpora of human-created works to produce original compositions, imagery, or text. These systems serve commercial purposes by accelerating content pipelines, reducing manual iteration cycles, and enabling personalized output at scale. Synthetic media solutions command significant investment as enterprises seek scalable video and image generation, while interactive narrative tools attract game studios pursuing dynamic player experiences. Educational tools remain comparatively nascent, though institutions are piloting automated assessment and personalized curriculum design applications.
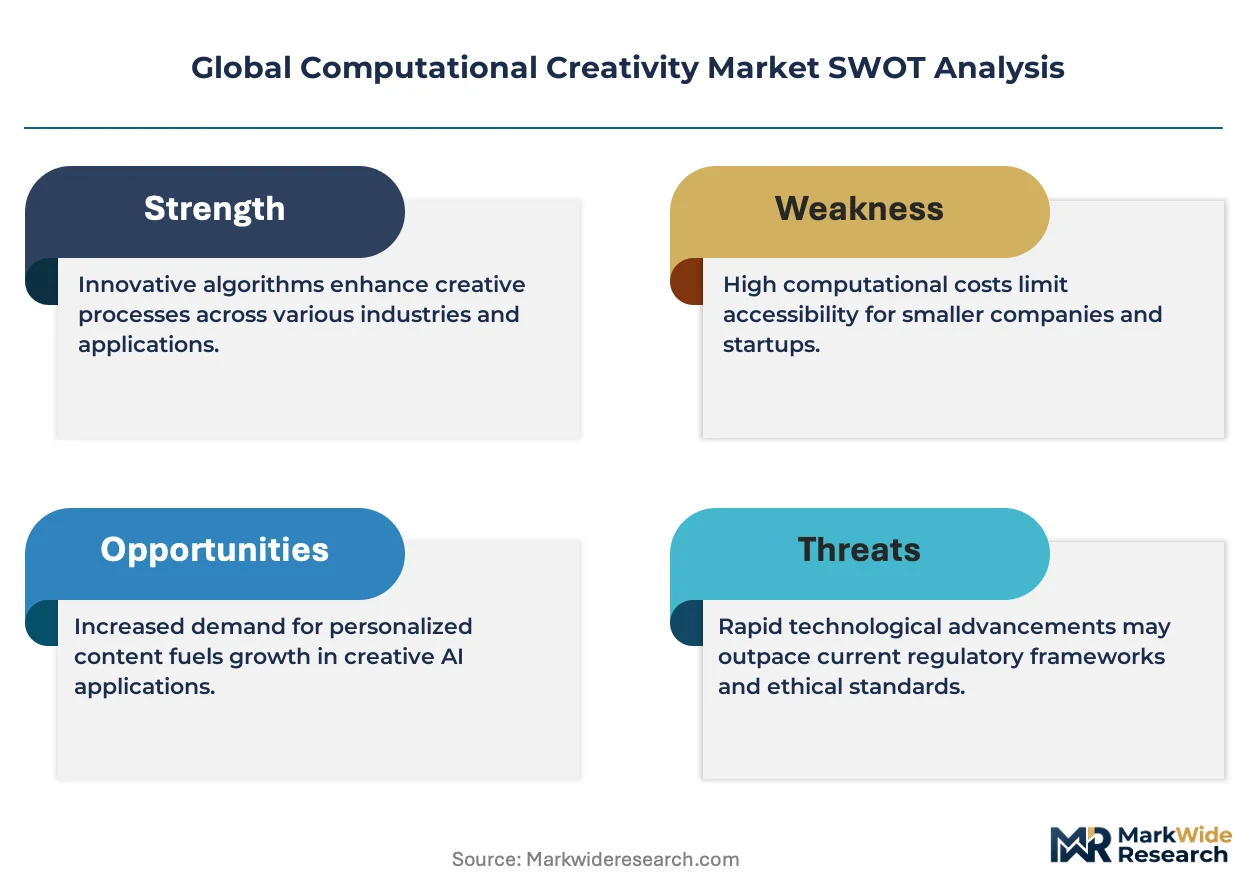
The EU AI Act imposes disclosure obligations on synthetic media outputs, compelling vendors to embed provenance metadata and restrict deceptive deepfake deployments. The FDA and FTC in the United States are scrutinizing health-related and commercial claims in AI-generated advertising content, tightening compliance burdens for creative agencies deploying automated tools. ISO and IEC standards frameworks for AI risk management are gaining traction as procurement prerequisites among enterprise buyers. Stakeholders must monitor evolving liability allocations between tool providers and end users as jurisdictions clarify accountability for AI-generated outputs.
Market Dynamics
The EU AI Act's disclosure mandates for synthetic media are forcing tool providers to re-architect output pipelines around embedded provenance metadata, compressing deployment timelines for entertainment studios and creative agencies.
Growth Catalysts
- Generative video pipelines:Entertainment content creation studios are expanding adoption of automated production tools to accelerate iteration cycles and reduce manual rendering overhead.
- EU AI Act transparency frameworks:Disclosure obligations for synthetic media outputs are creating procurement pull from enterprises seeking compliant tool stacks for marketing and communications.
- GPU infrastructure concentration in the United States:Cloud providers and creative agencies in California and New York are accessing training clusters that lower barriers for visual art model development.
Market Restraints
- Specialist talent scarcity:Shortages of trained generative AI engineers and prompt engineering specialists are inflating compensation costs and extending hiring cycles.
- Compute cost volatility:NVIDIA GPU allocation constraints and cloud pricing fluctuations are destabilizing operating cost forecasts for model training operations.
- Provenance standard fragmentation:Competing metadata schemas from C2PA, IPTC, and vendor-specific formats are complicating interoperability across creative toolchains.
Strategic Opportunities
- Interactive narrative for game studios:Dynamic player experience engines that generate branching storylines represent underpenetrated white space in AAA and indie development pipelines.
- Educational content automation:Institutions in Germany and South Korea are piloting automated assessment and personalized curriculum design applications with nascent vendor coverage.
- Convergence of diffusion models with real-time rendering:Unreal Engine and Unity integrations are opening new channels for procedural asset generation within established game development workflows.
Industry Challenges
- Cross-border IP licensing complexity:Training data provenance disputes and rights-holder litigation are extending legal review cycles for commercial model deployments.
- Legacy creative software integration friction:API limitations and workflow disruption risks are slowing enterprise adoption of standalone generative tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computational Creativity Market |
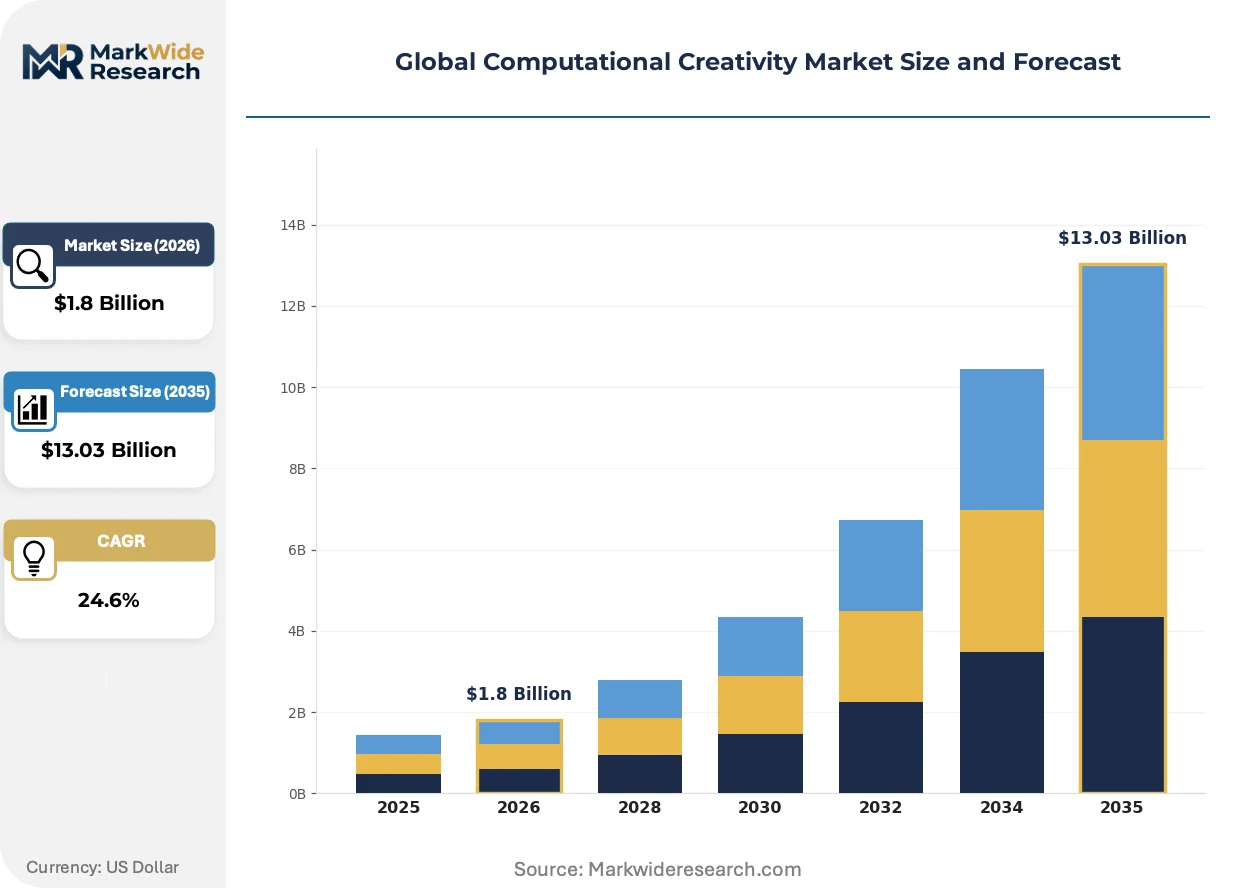
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Algorithmic Composition, Generative Design, Automated Storytelling, Visual Art Generation, Interactive Narrative, Synthetic Media Technology: Machine Learning, Natural Language Processing, Evolutionary Computing, Rule-Based Systems, Neural Networks, Multi-Agent Systems Application: Advertising, Entertainment Content Creation, Game Development, Artistic Expression, Educational Tools, Product Design End User: Creative Agencies, Media Production Houses, Game Studios, Publishing Firms, Educational Institutions, Design Consultancies |
| Companies Covered | Google, Microsoft, Adobe, OpenAI, IBM, Autodesk, NVIDIA, Canva, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computational Creativity Market Shifts & Advancements
Diffusion-based image generation architectures are compressing production timelines across commercial photography and advertising workflows. Regulatory disclosure requirements are redefining output packaging standards. Buyer procurement patterns are rotating toward bundled tool subscriptions.
Diffusion models for photorealistic imagery are supplanting traditional 3D rendering and stock photography licensing in commercial advertising pipelines. Mid-sized creative agencies in the United Kingdom and Netherlands are adopting these tools within six-month procurement cycles. The technology is supplanting location-based photoshoots and manual retouching workflows, collapsing production costs for seasonal campaign refreshes.
The EU AI Act's synthetic media disclosure obligations are mandating embedded provenance metadata and watermarking for all AI-generated visual outputs distributed within the European Union. Tool vendors must re-engineer export pipelines to comply, adding development overhead and certification delays. Entertainment studios with EU distribution exposure are prioritizing compliant tool stacks, creating procurement preference for vendors with pre-certified metadata infrastructure.
Enterprise buyers are consolidating point-solution subscriptions into integrated creative suites that bundle generative capabilities with asset management and collaboration features. Standalone image generation tools are losing procurement share to platform-embedded alternatives from established workflow providers. This consolidation pattern is most visible among creative agencies in the United States with 50-200 employee headcounts seeking to reduce vendor management overhead.
Global Computational Creativity Market Segmentation
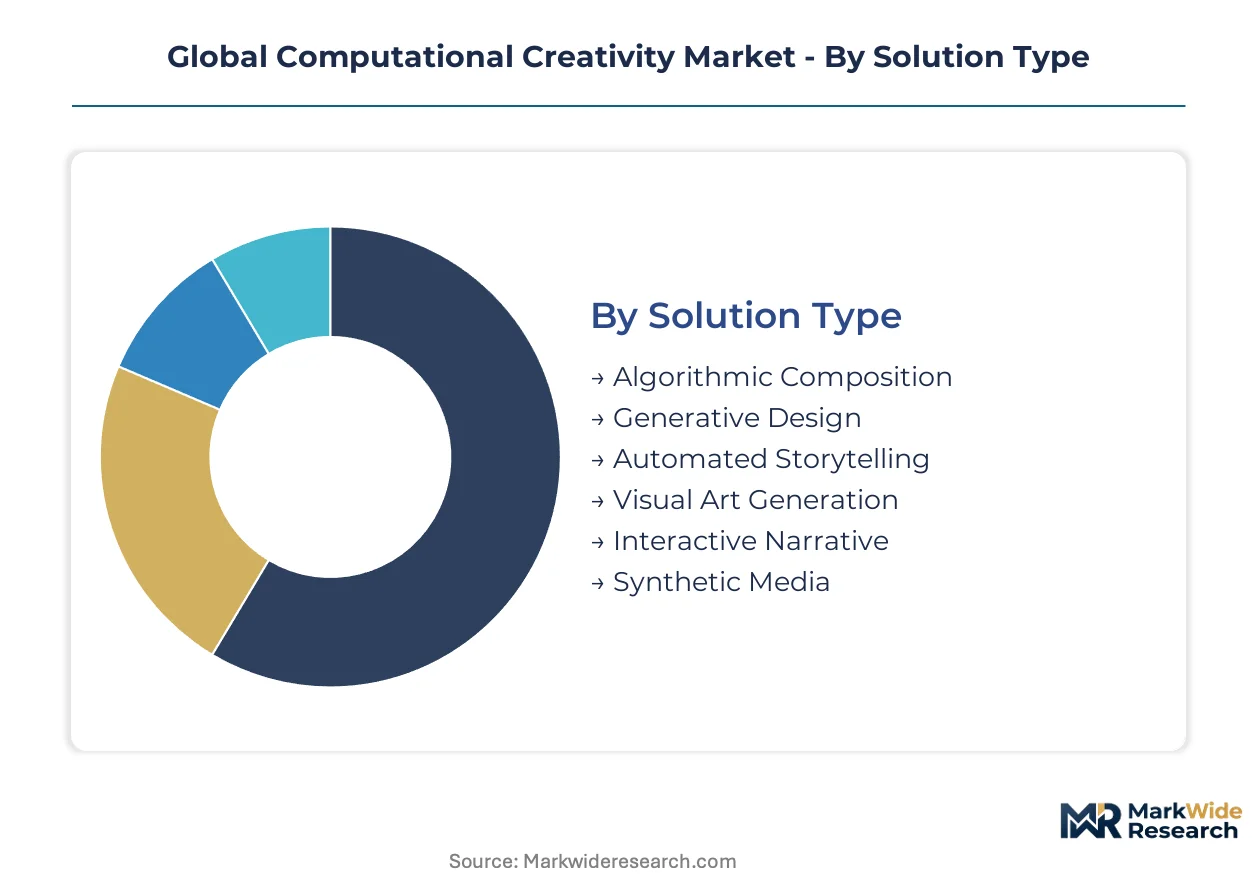
Computational creativity vendors architect their portfolios around distinct solution architectures, each carrying unique compliance footprints under the EU AI Act and diverging compute requirements. Segmentation clarity enables buyers to match procurement specifications against regulatory exposure and workflow integration depth.
Solution Type:
The EU AI Act's synthetic media disclosure mandates create sharp regulatory differentiation across solution categories, with visual outputs facing stricter provenance requirements than text-based or procedural systems.
- Visual Art Generation:Diffusion-based architectures produce photorealistic imagery and stylized compositions through latent space manipulation. Creative agencies in the United Kingdom and Netherlands are compressing campaign production cycles from weeks to days using these tools, though EU distribution requires embedded C2PA metadata compliance.
- Synthetic Media:Systems generating video, audio, and multimodal outputs face the heaviest regulatory burden under Article 52 disclosure obligations. Entertainment studios with EU distribution exposure are prioritizing vendors with pre-certified watermarking pipelines, creating procurement preference for established workflow platforms.
- Algorithmic Composition:Autonomous music generation systems employing recurrent neural networks and transformer architectures.
- Generative Design:Parametric optimization tools for structural and aesthetic object creation in manufacturing contexts.
- Automated Storytelling:Large language model applications for narrative structure generation and dialogue synthesis.
- Interactive Narrative:Dynamic branching story engines for player-driven game experiences with procedural content generation.
Visual Art Generation handles the majority of throughput; Synthetic Media is gaining share fastest as video generation quality crosses commercial thresholds.
Technology:
Cost tier stratification separates capital-intensive neural network training from lightweight rule-based deployments, with cloud infrastructure concentration in the United States creating geographic asymmetry in access.
- Neural Networks:Deep learning architectures including transformers, diffusion models, and generative adversarial networks demand substantial GPU clusters for training. California and New York-based creative agencies access cloud training infrastructure at lower effective cost than European counterparts, concentrating advanced capability development.
- Machine Learning:Supervised and unsupervised learning approaches for pattern recognition and predictive content optimization. Mid-sized creative agencies deploy these for audience-targeted campaign iteration without the capital intensity of foundation model training.
- Natural Language Processing:Text parsing, generation, and semantic analysis systems for narrative and dialogue applications.
- Evolutionary Computing:Genetic algorithms and swarm optimization for iterative design refinement.
- Rule-Based Systems:Deterministic procedural generation using handcrafted constraints and grammars.
- Multi-Agent Systems:Distributed autonomous agents collaborating on complex creative tasks.
Neural Networks absorb the largest share of vendor R&D investment; Natural Language Processing is expanding most quickly as large language model capabilities mature.
Application:
Customer type divergence separates high-volume, low-margin advertising deployments from bespoke, high-margin artistic commissions, with procurement patterns clustering around workflow integration requirements.
- Advertising:Automated generation of campaign assets, copy variations, and personalized creative at scale. Creative agencies with 50-200 employees in the United States are consolidating point solutions into bundled suites to reduce vendor management overhead.
- Entertainment Content Creation:Film, television, and streaming production pipelines employing generative tools for previsualization and asset generation. Studios face EU AI Act compliance deadlines for synthetic media outputs distributed in European markets.
- Game Development:Procedural asset generation, NPC behavior scripting, and dynamic world building.
- Artistic Expression:Individual creator tools for fine art, music composition, and experimental media.
- Educational Tools:Automated assessment and personalized curriculum design piloted in Germany and South Korea.
- Product Design:Industrial design optimization and rapid prototyping workflows.
Advertising commands the highest transaction volume; Educational Tools shows the steepest expansion trajectory as institutional pilot programs scale.
End User:
Margin structure varies sharply across buyer categories, with media production houses accepting premium pricing for provenance-certified tool stacks while educational institutions demand subsidized entry points.
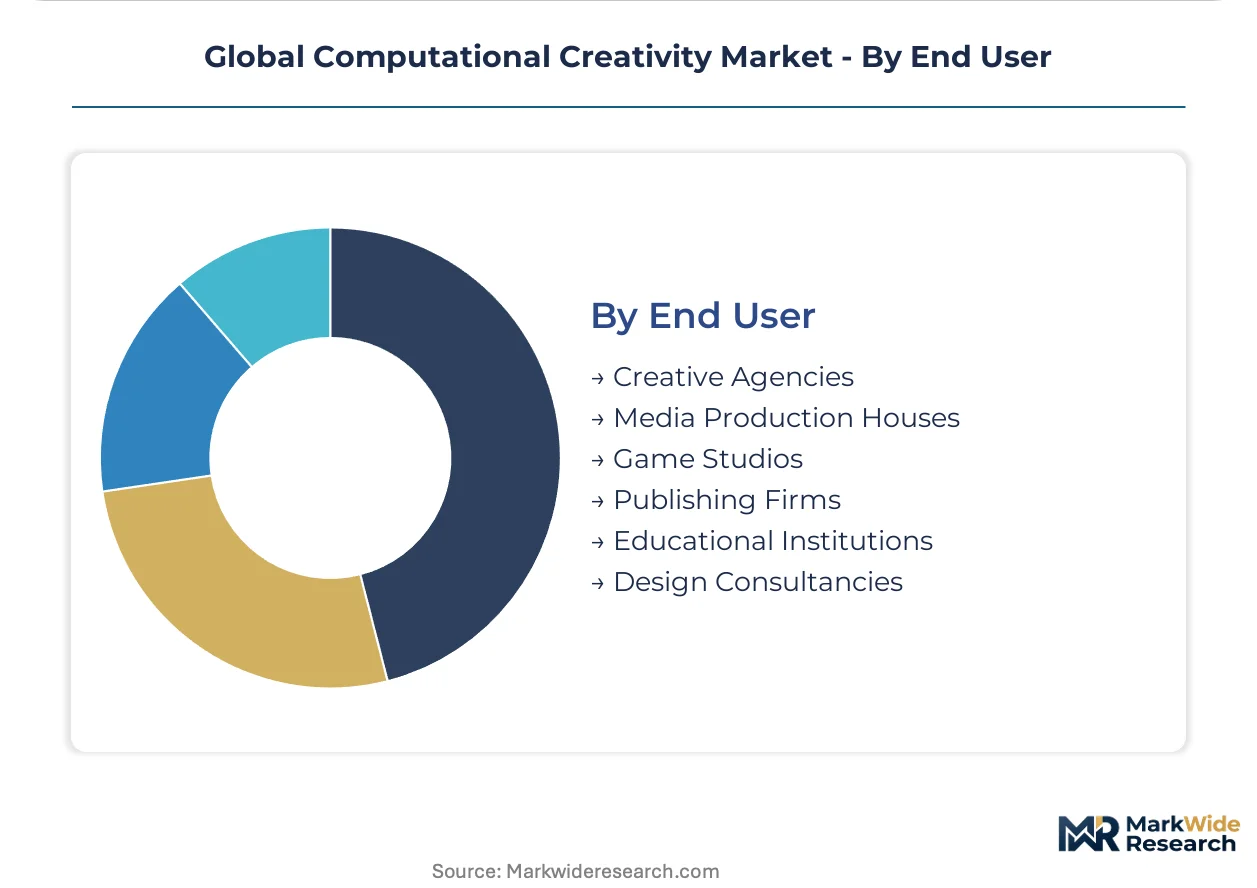
- Creative Agencies:Full-service marketing and design firms integrating generative tools into client delivery workflows. Procurement concentrates among mid-sized agencies in the United States seeking to compress campaign iteration cycles.
- Media Production Houses:Film, television, and commercial production studios with complex asset management requirements. EU distribution exposure drives prioritization of compliant metadata infrastructure.
- Game Studios:AAA and indie developers deploying procedural generation for asset pipelines and dynamic narrative systems.
- Publishing Firms:Book, magazine, and digital content publishers automating layout and illustration workflows.
- Educational Institutions:Universities and K-12 systems piloting automated assessment and curriculum personalization.
- Design Consultancies:Specialized firms applying generative methods to architectural and industrial design challenges.
Creative Agencies represent the largest installed base; Game Studios are climbing the fastest as Unreal Engine and Unity integrations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Creative agencies in the United States deploy generative tools for high-velocity advertising iteration, while German studios prioritize compliant metadata infrastructure for EU distribution. South Korean educational institutions pilot automated curriculum systems absent elsewhere.
United States
California and New York creative agencies access concentrated GPU cloud infrastructure for visual art model training. The FTC scrutinizes health-related claims in AI-generated advertising content. Los Angeles entertainment studios compress previsualization timelines using generative asset pipelines.
Germany
Industrial design consultancies apply parametric optimization tools to automotive and manufacturing workflows. The EU AI Act mandates embedded provenance metadata for synthetic media outputs distributed in European markets. Berlin-based creative agencies prioritize C2PA-compliant tool stacks for cross-border campaign delivery.
United Kingdom
Mid-sized advertising firms in London and Manchester adopt diffusion-based image generation within accelerated procurement cycles. The country's national data protection authority enforces transparency requirements for automated decision-making in creative outputs. Manchester media production houses integrate generative tools into commercial photography workflows.
South Korea
Educational institutions in Seoul and Gyeonggi Province pilot automated assessment and personalized curriculum design applications. The MFDS evaluates regulatory frameworks for AI-generated content in educational and commercial contexts. Seoul-based game studios deploy dynamic narrative engines for branching player experiences.
Japan
Tokyo game developers integrate procedural asset generation with Unreal Engine and Unity workflows. METI promotes standards adoption for AI risk management across creative industries. Osaka publishing firms automate layout and illustration pipelines for digital content distribution.
Global Computational Creativity Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the computational creativity market. Cloud infrastructure providers and established creative software platforms command premium positioning through workflow integration depth. Three archetypes dominate: GPU-accelerated training platforms, suite-embedded generative features, and standalone synthetic media tools. Competitive moves concentrate on strategic partnerships with game engines and portfolio diversification into adjacent creative verticals.
Within the integrated platform tier, Google and Microsoft occupy positions anchored by cloud infrastructure scale and productivity suite distribution. Adobe exemplifies the workflow-embedded archetype through deep integration of generative capabilities into established creative software. NVIDIA represents the infrastructure-dominant vector, leveraging GPU hardware concentration to control training economics for visual generation models.
| Leading Market Players |
|---|
| Microsoft |
| Adobe |
| OpenAI |
| IBM |
| Autodesk |
| NVIDIA |
| Canva |
| Amazon Web Services |
| Others |
Supply & Pricing Matrix
GPU cluster rentals displacing on-premise NVIDIA hardware purchases are redrawing supply geography toward California and New York cloud hubs while compressing pricing power for capital-intensive training operations.
Pricing Analysis
Long-term cloud compute offtake contracts dominate enterprise procurement for foundation model training, with spot pricing reserved for experimental workloads and peak rendering bursts. Three-tier pricing structure across premium, standard, and economy levels separates certified provenance-metadata stacks from basic watermarking and unmarked outputs. Cost compression in mid-market creative agency tiers is intensifying because bundled suite subscriptions are displacing point-solution renewals. Small indie game studios exhibit highest price sensitivity; Los Angeles entertainment studios with EU distribution exposure accept premium pricing for pre-certified compliance infrastructure.
Supply Chain Analysis
Inventory lead times for NVIDIA H100 and A100 clusters stretch 12-20 weeks, forcing creative agencies into advance reservation commitments or second-tier cloud provider alternatives. Taiwan, South Korea, and the United States concentrate advanced semiconductor fabrication for AI training hardware. The supply chain draws from specialized memory components, liquid cooling systems, and high-bandwidth interconnects. Single-source vulnerability around TSMC's advanced packaging capacity exposes training pipeline schedules to disruption. Distribution runs through hyperscaler marketplaces and direct vendor API integrations rather than traditional software reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The computational creativity market sits at a cyclical recovery phase driven by entertainment studios replenishing generative tool budgets after post-pandemic production delays.
For Market Incumbents: Fortify workflow integration moats by embedding generative capabilities deeper into existing creative suites before standalone challengers achieve API parity. Adobe's deep Creative Cloud integration exemplifies this defensive posture. Invest in C2PA-compliant metadata infrastructure ahead of EU AI Act enforcement deadlines to capture procurement preference from media production houses with European distribution exposure. For New Entrants and Emerging Players: Differentiate on interactive narrative engines for indie game studios, a white-space segment where Unreal Engine and Unity plugin ecosystems remain underdeveloped. Target educational institutions in Germany and South Korea piloting automated assessment systems, where incumbent vendor coverage is thinnest. Pursue direct institutional sales partnerships rather than marketplace distribution to bypass established creative suite bundling advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-embedded capabilities over standalone tools. Long-term viability over a 5-10 year window hinges on regulatory compliance infrastructure and game engine integration depth. Acquisition target archetype: mid-sized synthetic media vendors with pre-certified EU AI Act pipelines and existing entertainment studio relationships. Watch GPU allocation pricing volatility as the inflection indicator for training economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding generative features into Adobe Creative Cloud and Autodesk Maya preserves user workflow continuity and reduces churn. |
| Strategic Partnership | Unreal Engine and Unity plugin development opens distribution channels into AAA and indie game development pipelines. |
| Acquisition of Specialist Firm | Buying provenance-metadata vendors accelerates EU AI Act compliance certification for synthetic media output pipelines. |
| Geographic Expansion | Establishing cloud training clusters in Germany addresses EU data sovereignty requirements for European creative agencies. |
| Product Launch | Releasing real-time diffusion model APIs targets live streaming and broadcast applications with sub-second latency requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from creative software vendors, hyperscaler capex disclosures, and EU regulatory documentation. Primary interviews engaged CTOs at creative agencies, platform engineers at cloud infrastructure providers, regulatory affairs leads at synthetic media vendors, and procurement officers at entertainment studios. Secondary validation drew from FDA and FTC enforcement actions, EU AI Act implementation guidance, ISO/IEC AI risk management standards, and customs data on GPU import flows. Bottom-up sizing of vendor revenue streams triangulated against top-down addressable market calculations from creative industry employment and software spend data.
Segmentation dimensions modeled span solution type, technology architecture, application vertical, and end-user category across the analysis window. CAGRs were derived from trend extrapolation of adoption curves in comparable software automation markets, adjusted for regulatory compliance friction and talent scarcity constraints. Forecast inputs incorporated GPU infrastructure expansion timelines, entertainment production pipeline recovery patterns, and educational institution procurement cycle lengths.
The analysis sits within stated boundaries; outcomes outside sustained cloud infrastructure investment and stable regulatory enforcement timelines would require recalibration. Forecasts reflect assumptions about synthetic media disclosure mandate adherence rates and game engine integration velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Machine Learning (ML) Market