
 Artificial Intelligence and Advanced Machine Learning Market | 2026-2036
Artificial Intelligence and Advanced Machine Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence and Advanced Machine Learning Market Outlook
The shift from general-purpose foundation models to domain-specific fine-tuned architectures is tilting how enterprises deploy intelligence at scale. NVIDIA Corporation dominates specialized silicon supply for training workloads, while Google LLC anchors cloud-native machine learning platforms through its tensor processing infrastructure. Microsoft Corporation leverages its enterprise software footprint to embed copilot-style agents directly into productivity workflows, creating distribution advantages that competitors struggle to replicate.
Artificial intelligence and advanced machine learning encompass computational systems that learn patterns from data through statistical optimization, typically requiring training datasets exceeding millions of samples, inference latencies measured in milliseconds, and specialized hardware accelerators such as GPUs or TPUs to execute matrix operations at scale. These technologies serve primarily to automate complex decision-making, generate predictive outputs, and enable autonomous behavior across digital and physical systems. Deep learning within the technology segment captures the largest share of capital deployment due to its performance breakthroughs in unstructured data processing, while edge computing deployment is expanding fastest as manufacturers demand localized inference without cloud dependency. Natural language processing applications attract disproportionate R&D investment following breakthroughs in transformer architectures, though predictive analytics retains the broadest installed base across legacy enterprise accounts.
The EU AI Act and GDPR collectively impose risk-classification frameworks and data governance mandates that reshape product development timelines for vendors seeking European market access. In the United States, the FDA regulates machine-learning-enabled medical devices through predetermined change control plans, while the SEC scrutinizes algorithmic trading systems for market manipulation risks. China's SAMR and MIIT enforce algorithmic recommendation transparency rules that affect how recommendation engines operate domestically. Stakeholders must monitor divergent regulatory trajectories across jurisdictions, as compliance fragmentation threatens to fragment model architectures and increase operational complexity for globally deployed systems.
Market Dynamics
Foundation model commoditization is compressing margins for general-purpose AI providers while amplifying returns for vertically specialized architectures trained on proprietary domain corpora.
Growth Catalysts
- FDA Predetermined Change Control Plans:Medical device manufacturers now deploy continuously learning diagnostic algorithms without repeated 510(k) submissions, accelerating clinical AI commercialization.
- Defense procurement concentration:United States federal agencies mandate sovereign AI infrastructure, creating captive demand for domestic training clusters and inference edge nodes.
- Transformer architecture maturation:Attention mechanisms optimized for protein folding and molecular simulation are displacing physics-based simulation in pharmaceutical discovery pipelines.
Market Restraints
- High-bandwidth memory supply concentration:HBM3E stack production concentrates among three Korean suppliers, creating input cost volatility for training accelerator procurement.
- EU AI Act risk-classification friction:High-risk system compliance timelines extend product development cycles by 14-18 months for vendors seeking European market access.
- Deterministic inference limitations:Stochastic large language model outputs remain unsuitable for safety-critical autonomous vehicle decision layers, constraining automotive deployment.
Strategic Opportunities
- Indian pharmaceutical AI services:Contract research organizations in Hyderabad and Bangalore are building proprietary molecular generative models for global drug discovery clients.
- Edge inference silicon diversification:RISC-V-based neural processing units are penetrating industrial vision systems previously locked to ARM or x86 architectures.
- EU Green Deal compute efficiency mandates:Carbon-intensity disclosure requirements for data centers are favoring liquid-cooled training facilities with waste heat recovery systems.
Industry Challenges
- MLops talent scarcity:Production-grade model deployment, monitoring, and rollback expertise remains concentrated among specialists commandering compensation premiums exceeding 40% above software engineering baselines.
- Legacy enterprise system integration:Mainframe and COBOL-based core banking infrastructure requires expensive API abstraction layers to feed real-time data into modern inference pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence and Advanced Machine Learning Market |
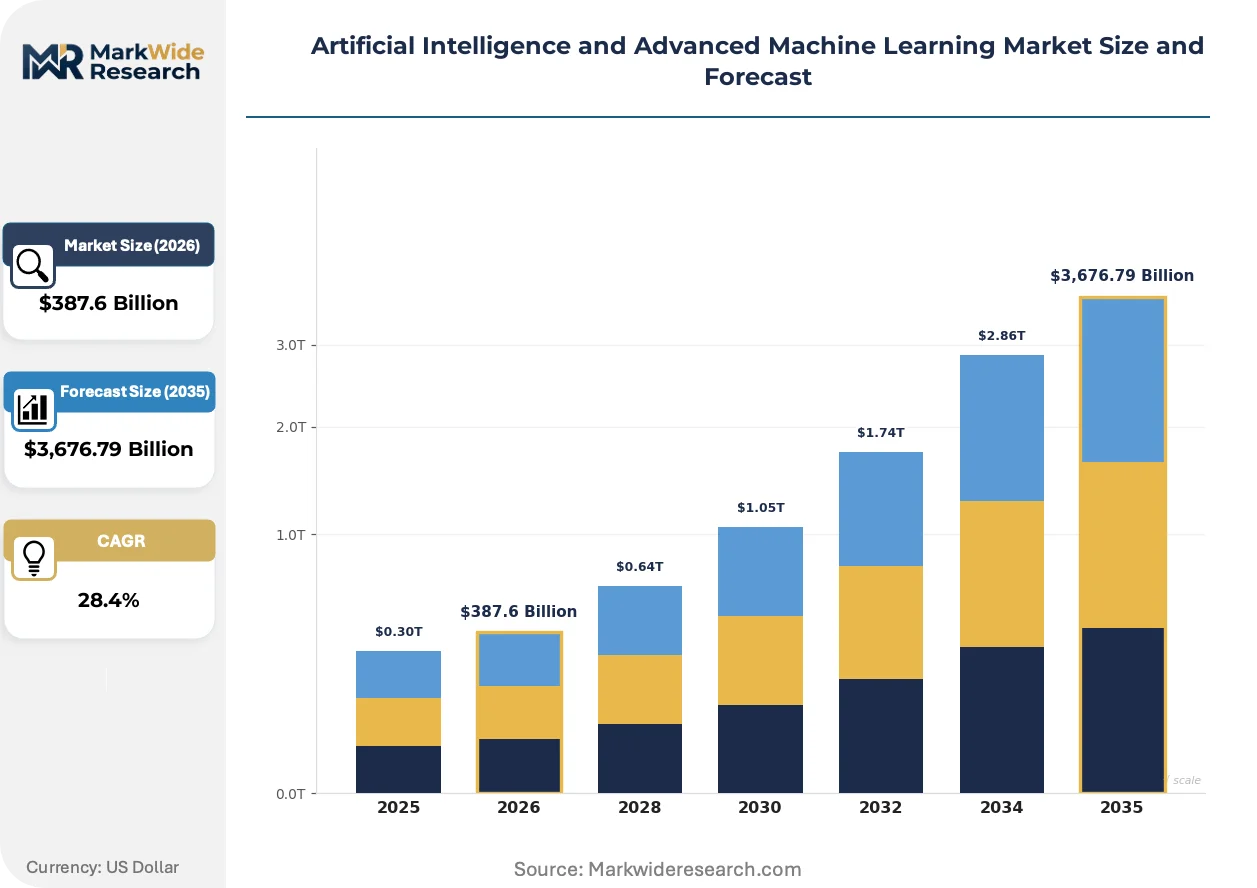
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $3,676.79 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Supervised Learning, Unsupervised Learning, Reinforcement Learning, Deep Learning Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Natural Language Processing, Image Recognition, Predictive Analytics, Robotics End User: Finance, Healthcare, Retail, Manufacturing |
| Companies Covered | Microsoft Corporation, Google LLC, Amazon Web Services, NVIDIA Corporation, IBM Corporation, Intel Corporation, SAP SE, Oracle Corporation, H2O.ai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence and Advanced Machine Learning Market Strategic Shifts
Computational architectures are bifurcating between massive centralized training clusters and atomized edge inference nodes, with the middleware layer between them undergoing rapid functional consolidation.
Mixture-of-experts routing is collapsing the cost curve for serving trillion-parameter models by activating only subset pathways per inference request. Cloud hyperscalers are deploying sparse architectures across their GPU fleets, reducing per-token energy consumption by 60-70% versus dense alternatives. This efficiency gain is compressing the economic viability threshold for consumer-facing generative applications previously restricted to enterprise pricing tiers.
The EU AI Act's conformity assessment requirements are forcing medical imaging vendors to rearchitect development pipelines around documented risk management systems and post-market monitoring protocols. German notified bodies are experiencing 8-12 month backlogs for high-risk AI certification reviews, delaying product launches for computer-aided detection systems. Manufacturers are responding by establishing dedicated regulatory affairs functions in Brussels and pre-submission consultation programs with BfArM.
Enterprise procurement of foundation model access is consolidating toward annual committed-use contracts with single-primary-provider structures, displacing the previous multi-vendor experimental purchasing pattern. Financial services institutions in New York and London are negotiating exclusive inference capacity reservations directly with cloud infrastructure operators, bypassing traditional software procurement channels. This concentration is most visible among asset managers deploying systematic trading strategies requiring sub-10 millisecond model refresh cycles.
Artificial Intelligence and Advanced Machine Learning Market Segmentation

Segmentation in artificial intelligence and advanced machine learning reveals how technical architectures, infrastructure choices, and domain applications create distinct commercial battlegrounds. Vendors must align capabilities against specific deployment constraints and regulatory requirements rather than pursuing horizontal dominance.
Technology:
Use cases span deterministic classification tasks through autonomous decision systems requiring continuous environmental feedback.
- Deep Learning:Multi-layer neural networks process unstructured data through backpropagation optimization. Healthcare providers in the United States deploy convolutional architectures for diagnostic imaging, constrained by FDA predetermined change control plan documentation requirements. German medical device manufacturers face EU AI Act conformity assessment backlogs extending certification timelines.
- Reinforcement Learning:Agent-based systems optimize sequential decisions through reward signal feedback. Robotics manufacturers in Japan apply policy gradient methods to industrial automation, driven by METI productivity targets and labor shortage mitigation. Autonomous vehicle developers remain blocked from safety-critical deployment due to stochastic output non-determinism.
- Supervised Learning:Labeled training datasets enable predictive classification across structured enterprise data.
- Unsupervised Learning:Pattern discovery algorithms segment customer populations and detect anomalous transactions without ground-truth labels.
The dominant share belongs to Deep Learning, while Reinforcement Learning is closing the gap fastest.
Deployment:
Infrastructure location determines latency budgets, data sovereignty compliance, and operational cost structures.
- Edge Computing:Localized inference executes on-device without network round-trips. Industrial vision systems in South Korea deploy RISC-V neural processing units for quality inspection, meeting MFDS medical device traceability mandates. Korean HBM3E supply concentration creates accelerator procurement cost volatility.
- Cloud-Based:Centralized training clusters and elastic inference APIs eliminate capital expenditure requirements. Financial services institutions in London negotiate exclusive capacity reservations with infrastructure operators for sub-10 millisecond model refresh cycles. EU Green Deal carbon-intensity disclosures favor liquid-cooled facilities with waste heat recovery.
- On-Premises:Sovereign infrastructure satisfies classified workloads and data residency mandates.
- Hybrid:Orchestrated workloads split training and inference across environments based on sensitivity and latency requirements.
Cloud-Based deployments command the largest installed base, though Edge Computing is expanding most quickly as manufacturers reject cloud dependency.
Application:
Functional capabilities align with data modality and decision automation requirements across enterprise workflows.
- Natural Language Processing:Transformer architectures process sequential text through attention mechanisms. Enterprise software vendors embed copilot-style agents directly into productivity workflows, leveraging existing distribution channels. Mixture-of-experts routing reduces per-token energy consumption substantially versus dense alternatives.
- Image Recognition:Convolutional and vision transformer architectures classify visual inputs for medical and industrial contexts. German notified bodies experience 8-12 month certification backlogs for computer-aided detection systems under EU AI Act high-risk classification.
- Predictive Analytics:Statistical models forecast demand, risk, and maintenance requirements across legacy enterprise accounts.
- Robotics:Perception-planning-control pipelines enable physical task automation in structured environments.
Natural Language Processing attracts disproportionate R&D investment, while Image Recognition gains share fastest from healthcare diagnostic deployment.
End User:
Sector-specific regulatory frameworks and data availability shape adoption trajectories and vendor selection criteria.
- Healthcare:Diagnostic and therapeutic applications face stringent safety validation requirements. United States providers accelerate adoption of imaging systems powered by deep learning algorithms under FDA streamlined review pathways. EU AI Act risk-classification extends development cycles substantially for European market access.
- Finance:Algorithmic trading and risk management applications demand deterministic outputs and audit trails. SEC scrutiny of trading systems for market manipulation risks constrains model complexity. Annual committed-use contracts with single-primary-provider structures displace multi-vendor experimental purchasing.
- Retail:Recommendation engines and demand forecasting optimize inventory and personalization.
- Manufacturing:Predictive maintenance and quality inspection reduce downtime and defect rates.
Healthcare captures the dominant deployment value, while Finance is climbing the fastest as systematic strategies demand sub-10 millisecond inference.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in AI software and cloud services while importing specialized training accelerators from South Korea and Taiwan. Germany and China maintain near-balanced positions in industrial AI applications. India's services exports dominate its AI trade profile.
United States
Defense contractors and federal agencies mandate sovereign AI infrastructure, creating captive demand for domestic training clusters. The FDA streamlines clinical AI commercialization through predetermined change control plans for diagnostic algorithms. Seattle and San Francisco anchor cloud-native machine learning platform development for enterprise productivity workflows.
Germany
Industrial manufacturers deploy computer-aided detection systems for quality inspection and predictive maintenance. BfArM and German notified bodies enforce EU AI Act conformity assessments with 8-12 month certification backlogs. Munich and Stuttgart concentrate automotive AI development constrained by stochastic output limitations in safety-critical layers.
China
Domestic technology firms build proprietary foundation models for consumer and enterprise applications. SAMR and MIIT enforce algorithmic recommendation transparency rules affecting recommendation engine operations. Beijing and Shenzhen house the largest centralized training clusters, though HBM3E supply concentration creates accelerator procurement volatility.
India
Contract research organizations in Hyderabad and Bangalore construct molecular generative models for global pharmaceutical clients. The country's national technology regulator promotes domestic cloud infrastructure for data residency compliance. Bengaluru's AI services corridor expands fastest among Asia-Pacific delivery locations for model training and deployment outsourcing.
South Korea
Industrial vision systems deploy RISC-V neural processing units for localized quality inspection meeting MFDS traceability mandates. HBM3E stack production concentrates among domestic suppliers, creating regional supply leverage for training accelerator procurement. Seoul anchors edge inference silicon design for manufacturing automation.
Artificial Intelligence and Advanced Machine Learning Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability layers: hyperscale cloud infrastructure, specialized silicon fabrication, and vertical application software. The vendor base separates cleanly between capital-intensive hardware providers and asset-light model service layers. Dominant competitive moves include exclusive inference capacity reservations by financial institutions and sovereign infrastructure mandates by defense procurement agencies. Technology licensing agreements and strategic cloud partnerships constitute the primary expansion mechanisms.
Within the hyperscale infrastructure tier, Microsoft Corporation and Google LLC anchor cloud-native machine learning platforms through contrasting distribution strategies. NVIDIA Corporation occupies a singular position in specialized silicon supply for training workloads. These three entities exemplify the structural division between general-purpose foundation model provision and domain-specific deployment channels.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services |
| NVIDIA Corporation |
| IBM Corporation |
| Intel Corporation |
| SAP SE |
| Oracle Corporation |
| H2O.ai |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on HBM3E stack production concentrates pricing power among Korean suppliers while forcing buyers into long-term offtake commitments that widen tier spreads between sovereign-capable and commodity inference deployments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA certification tier for medical applications and sovereign infrastructure compliance for defense procurement. Cost compression in the standard tier is intensifying because foundation model commoditization collapses per-token margins. Defense contractors exhibit least price sensitivity due to mandated domestic sourcing requirements, while mid-market software vendors face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on advanced GPU clusters limit flows from United States suppliers to Chinese end-users, fragmenting procurement channels. Geographic supply concentration centers on South Korea for HBM3E memory, Taiwan for advanced logic fabrication, and United States for training accelerator design. Raw material dependencies include high-purity silicon wafers, specialty photoresists, and rare-earth magnet components for cooling systems. Single-source vulnerability in Korean memory supply creates procurement risk. Distribution runs through hyperscale cloud operators and direct OEM procurement teams.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital expenditure cycles in cloud infrastructure are recovering from prior-year contraction, with hyperscaler training cluster investments signaling renewed expansion.
For Market Incumbents: Entrench position through backward integration into specialized silicon design and exclusive capacity reservations with Korean HBM3E suppliers. Regulatory fragmentation across FDA, EU AI Act, and SAMR jurisdictions threatens product architecture standardization. Certification investment in Brussels-based regulatory affairs functions defends European market access against conformity assessment delays. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian pharmaceutical AI services and RISC-V-based edge inference silicon for industrial vision. Contract research organizations in Hyderabad represent the most penetrable segment due to global drug discovery outsourcing demand. Go-to-market positioning should emphasize molecular generative model specialization over general-purpose foundation model competition. For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors vertically integrated training cluster operators with sovereign compliance capabilities. Long-term viability hinges on control over memory supply and liquid-cooled facility assets. Acquisition targets should demonstrate EU AI Act conformity assessment progress. Watch hyperscaler capex guidance as the inflection indicator for demand cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Inference Capacity Reservation | Financial services institutions in London secure sub-10 millisecond model refresh cycles bypassing traditional software channels. |
| Regulatory Affairs Function Establishment | Medical imaging vendors pre-position for BfArM consultation programs amid German notified body certification backlogs. |
| Liquid-Cooled Training Facility Deployment | EU Green Deal carbon-intensity disclosures favor waste heat recovery systems for data center compliance. |
| Mixture-of-Experts Architecture Migration | Cloud hyperscalers reduce per-token energy consumption substantially versus dense alternatives across GPU fleets. |
| RISC-V Neural Processing Unit Design | Industrial vision manufacturers in South Korea escape ARM and x86 architecture lock-in for quality inspection systems. |
Study Parameters
The analysis maps deep learning deployment, reinforcement learning applications, edge inference infrastructure, and cloud-native machine learning platforms, each validated through conversations with platform engineers, IT procurement officers at financial institutions, biomedical engineers at German notified bodies, and hyperscaler infrastructure planners. Secondary validation draws from SEC filings, hyperscaler capex disclosures, FDA 510(k) submission databases, and EU AI Act implementation guidance. Bottom-up segment sizing and top-down macro constraint triangulation ensure cross-verification.
Assumptions held fixed include regulatory enforcement timelines for EU AI Act conformity assessments and Korean HBM3E supply concentration, while model architecture efficiency gains and sovereign procurement mandates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass deployment mode, end-user vertical, technology architecture, and regional regulatory cluster. CAGRs derive from installed base progression analysis and replacement cycle timing. Industry-specific inputs include FDA predetermined change control plan adoption rates and defense procurement budget allocation patterns.
Sensitivities concentrate around export-control expansion, memory supply disruption, and regulatory timeline acceleration. Forecasts reflect these documented assumptions and scenario boundaries. Material shifts in Korean supplier output or EU notified body staffing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Natural Language Processing Market