
 Europe Machine Learning As a Service Market | 2026-2036
Europe Machine Learning As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Machine Learning As a Service Market Analytics
Enterprise-grade inference latency is collapsing as the baseline specification for production ML deployments across European regulated industries. Microsoft Azure sustains competitive positioning through dedicated European data residency zones and sovereign cloud architectures. SAP SE anchors its presence by embedding predictive models directly into ERP workflows for manufacturing clients. Google Cloud differentiates via specialized silicon and custom TPU availability in Frankfurt and London regions.
Machine Learning As a Service denotes cloud-delivered access to algorithm training, model deployment, and inference infrastructure without on-site hardware ownership, typically exposing REST APIs with sub-100ms response thresholds for real-time applications. The primary commercial purpose centers on enabling organizations to operationalize pattern recognition and automated prediction without maintaining specialized data science infrastructure or GPU clusters. Public Cloud deployment leads European uptake as hyperscalers achieve GDPR-aligned data processing certifications, while Predictive Analytics solutions capture disproportionate investment from BFSI end users seeking credit risk and fraud detection capabilities. Natural Language Processing is accelerating fastest as enterprises automate multilingual document processing and customer interaction workflows across the region.
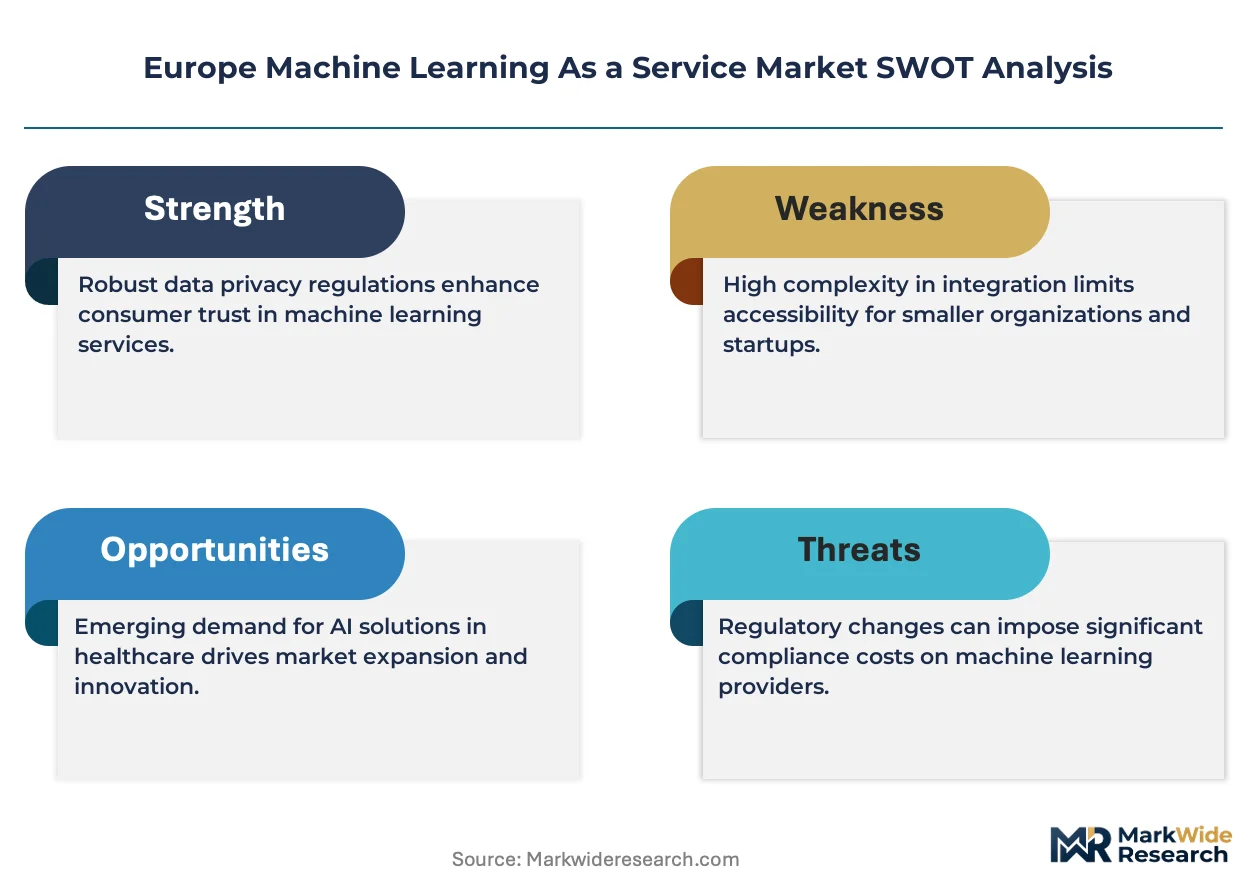
EMA guidelines on AI-enabled medical devices and the EU AI Act's risk classification framework shape product development timelines and compliance costs for healthcare and financial services deployments. GDPR's automated decision-making provisions constrain model explainability requirements, directly influencing architectural choices for European ML pipeline design. Stakeholders must monitor evolving CE marking interpretations for AI systems and anticipate convergence between sector-specific regulators and horizontal AI governance mechanisms.
Market Dynamics
The EU AI Act's risk classification framework is compressing product development timelines for automated decision-making systems, forcing vendors to front-load compliance architecture into ML pipeline design before commercial deployment.
Growth Catalysts
- EMA guidelines on AI-enabled medical devices:Healthcare providers in Germany are accelerating validation protocols for diagnostic algorithms, expanding managed ML infrastructure procurement.
- GDPR automated decision-making provisions:Financial services firms in London are investing in explainable model architectures to satisfy supervisory scrutiny of credit scoring workflows.
- Hyperscaler data residency zones:Frankfurt and Paris cloud regions now host sovereign-certified GPU clusters, removing legal barriers for regulated industry adoption.
Market Restraints
- NVIDIA H100 supply concentration:Training infrastructure procurement faces allocation bottlenecks from single-source GPU fabrication.
- CE marking interpretation divergence:National competent authorities apply inconsistent conformity assessment criteria for AI system market entry.
- On-premise legacy data centers:Existing capital-intensive compute investments create substitution friction against fully managed service migration.
Strategic Opportunities
- Polish and Romanian enterprise segments:Underpenetrated mid-market manufacturers lack in-house MLOps capability, creating channel partner expansion potential.
- Edge inference deployment:Convergence of 5G low-latency networks with containerized model serving enables predictive maintenance at automotive production lines.
- CSRD sustainability reporting mandates:Automated ESG data extraction from unstructured documents drives Natural Language Processing procurement in France and the Netherlands.
Industry Challenges
- MLOps engineering scarcity:European labor markets lack sufficient practitioners capable of productionizing research-grade models into fault-tolerant inference pipelines.
- Horizontal AI Act compliance:High-risk system providers face extended conformity assessment timelines before CE marking authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Machine Learning As a Service Market |
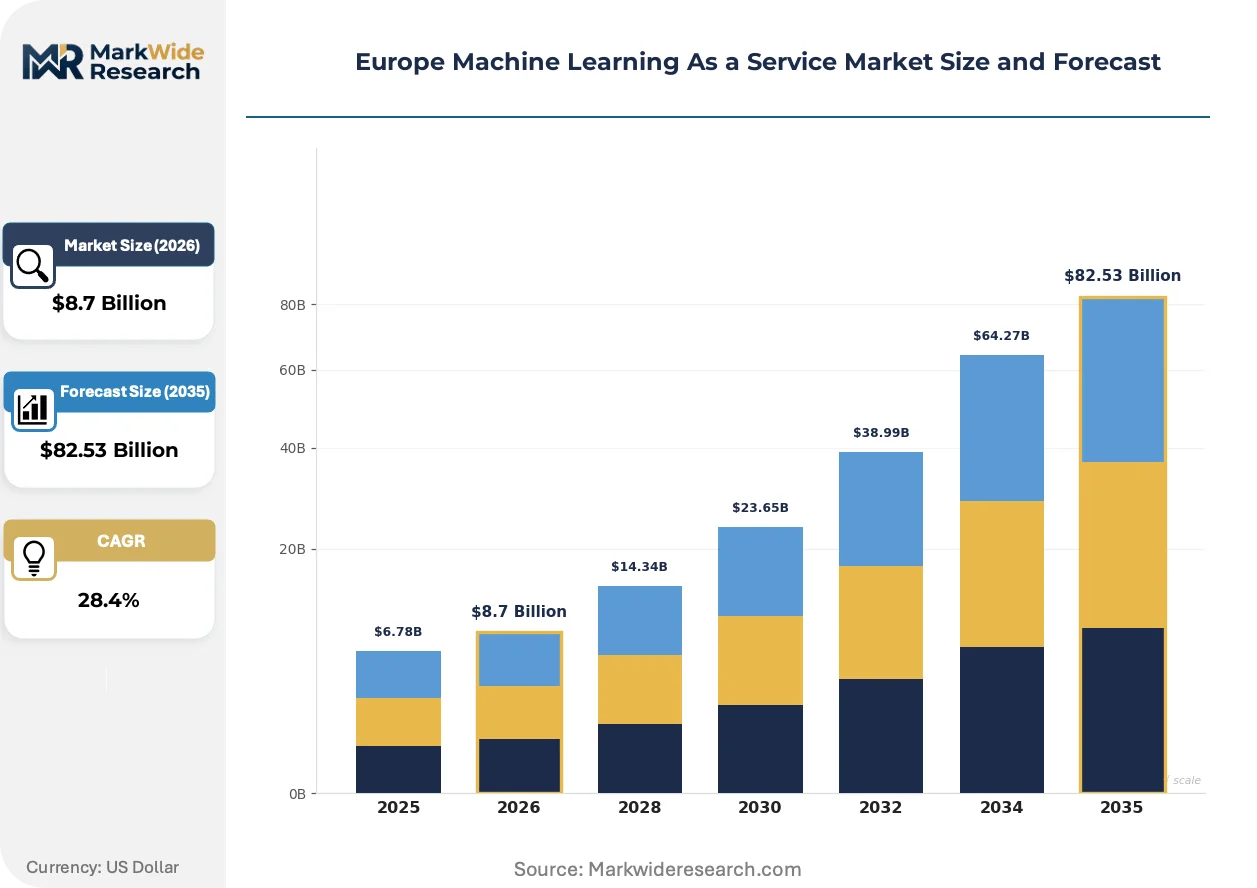
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Healthcare, BFSI, Retail, Manufacturing Solution: Natural Language Processing, Predictive Analytics, Computer Vision, Data Mining Service Type: Consulting, Deployment, Support, Training |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, SAP SE, IBM Watson, DataRobot, H2O.ai, KNIME AG, Shift Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Machine Learning As a Service Market Evolving Landscape
Foundation model architectures are fragmenting deployment patterns across European regulated industries, compressing the traditional divide between general-purpose and domain-specific ML capabilities.
Retrieval-augmented generation is decomposing monolithic large language model deployments into modular knowledge-base query systems. German automotive suppliers are adopting these architectures for technical documentation search. The approach is decomposing vendor lock-in risks by enabling model-agnostic knowledge retrieval layers.
The EU AI Act's conformity assessment procedures are mandating pre-market documentation of training data provenance and model performance benchmarks. Medical device manufacturers face the steepest compliance burden under Class III AI system classifications. French and Dutch notified bodies are developing specialized technical competencies to handle accelerated review queues.
Consumption-based pricing for inference workloads is displacing fixed-capacity reserved instances among UK and Scandinavian financial services buyers. Managed service providers are responding with granular per-token billing for generative AI endpoints. This shift is most visible in London's quantitative trading and fraud detection application segments.
Europe Machine Learning As a Service Market Segmentation
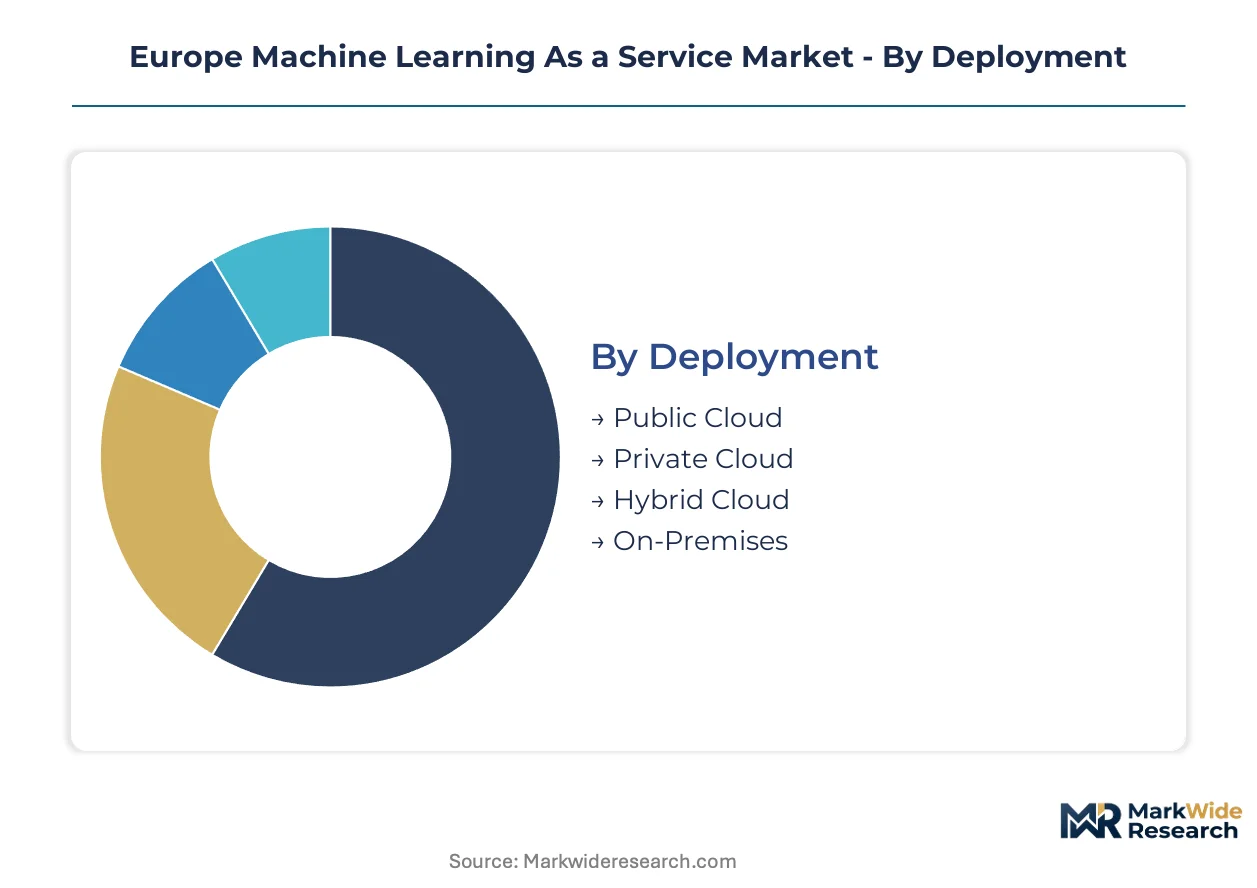
Segmentation in the European MLaaS market reveals distinct procurement patterns shaped by GDPR data residency requirements and sector-specific AI Act risk classifications. Deployment architecture and solution type drive the largest margin differentials as regulated industries prioritize sovereign cloud infrastructure.
Deployment:
Margin pools concentrate in hybrid configurations that balance compliance certification with elastic compute scaling.
- Public Cloud:Multi-tenant infrastructure delivers algorithm training and inference via hyperscaler-managed GPU clusters with sub-100ms latency SLAs. German financial services firms in Frankfurt are consolidating procurement here to leverage sovereign-certified data residency zones without capital expenditure. The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest.
- Private Cloud:Dedicated single-tenant environments provide isolated compute for high-risk AI system classifications under EU AI Act conformity requirements. French healthcare providers deploying diagnostic algorithms favor this model to satisfy EMA validation protocols and CE marking documentation needs.
- Hybrid Cloud:Workload portability between on-premise and cloud infrastructure enables burst capacity for model training while retaining sensitive inference locally. UK BFSI adopters use this architecture for credit scoring workflows requiring explainable model governance.
- On-Premises:Fully captive GPU clusters serve defense and critical infrastructure operators with air-gapped security requirements.
Hybrid architectures are expanding most quickly as enterprises seek to partition training and inference across compliance boundaries.
End User:
Application intensity varies sharply by sector regulatory maturity and AI Act risk classification exposure.
- BFSI:Credit risk modeling, fraud detection, and algorithmic trading consume the majority of managed ML inference capacity. London-based quantitative funds and Frankfurt banking consortia are standardizing on consumption-based pricing for real-time prediction endpoints. BFSI commands the largest procurement volumes, though Healthcare is gaining share fastest.
- Healthcare:Diagnostic imaging and clinical decision support systems face stringent EMA pre-market validation and Class III AI system documentation burdens. German hospital networks are accelerating procurement of validated ML pipelines for radiology workflow integration.
- Manufacturing:Predictive maintenance and quality inspection drive edge inference deployment at automotive production lines in Stuttgart and Wolfsburg.
- Retail:Demand forecasting and customer segmentation applications concentrate in French and Dutch omnichannel operators.
BFSI retains the dominant procurement position, while Healthcare shows the steepest expansion trajectory under diagnostic automation mandates.
Solution:
Technology maturity and integration complexity create tiered pricing structures across capability layers.
- Predictive Analytics:Statistical pattern recognition and time-series forecasting for credit scoring, inventory optimization, and equipment failure prediction. UK and German BFSI buyers represent the core demand concentration for fraud detection and risk scoring workflows. Predictive Analytics holds the established revenue base, while Natural Language Processing is expanding most rapidly.
- Natural Language Processing:Multilingual document extraction, sentiment analysis, and conversational interfaces automate customer service and regulatory reporting. French and Dutch enterprises are procuring NLP pipelines to satisfy CSRD sustainability disclosure automation requirements.
- Computer Vision:Defect detection, medical imaging classification, and autonomous quality inspection deploy at manufacturing and healthcare sites.
- Data Mining:Unsupervised pattern discovery and feature engineering support exploratory analytics for mid-market enterprises lacking in-house data science capacity.
Predictive Analytics maintains the largest installed base, with Natural Language Processing climbing the fastest on generative AI adoption.
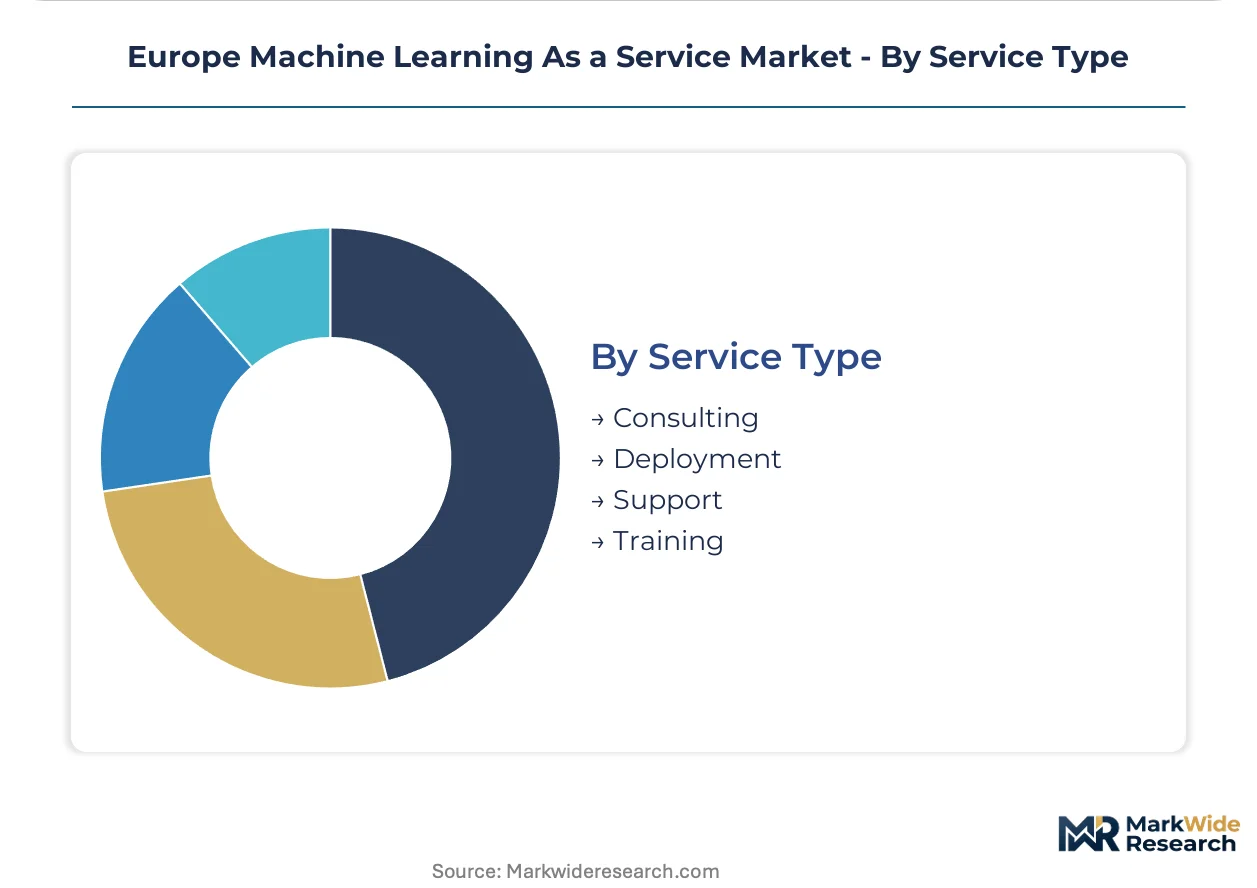
Service Type:
Revenue concentration shifts toward recurring managed services as enterprises outsource MLOps engineering scarcity.
- Deployment:Production pipeline configuration, model serving infrastructure, and CI/CD automation for inference endpoints. German automotive suppliers and UK financial services firms are procuring managed deployment to bypass internal MLOps capability gaps. Deployment services capture the dominant share, while Support is expanding fastest.
- Consulting:Use-case identification, data strategy, and AI Act compliance architecture for high-risk system classification. French healthcare manufacturers engage consultants to navigate CE marking and EMA validation requirements.
- Training:Workforce upskilling on model interpretation, prompt engineering, and responsible AI governance.
- Support:24/7 model monitoring, drift detection, and retraining automation with guaranteed latency SLAs.
Deployment services generate the largest revenue pool, while Support is gaining share fastest on operational reliability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European MLaaS procurement. Scandinavian buyers prioritize sovereign-certified infrastructure regardless of premium positioning, while Polish and Romanian mid-market manufacturers negotiate aggressively on per-token inference costs.
Germany
Frankfurt's banking consortia and Stuttgart automotive clusters drive the continent's densest concentration of managed ML infrastructure. EMA guidelines on AI-enabled medical devices compress validation timelines for diagnostic algorithm deployments. Bavarian hospital networks are accelerating procurement of CE-marked clinical decision support systems.
United Kingdom
London quantitative funds and fraud detection specialists consume disproportionate inference capacity under consumption-based pricing models. GDPR automated decision-making provisions mandate explainable model architectures for credit scoring workflows. The Square Mile's regulatory technology vendors are embedding compliance documentation directly into ML pipeline orchestration.
France
Parisian cloud regions host sovereign-certified GPU clusters removing legal barriers for regulated industry adoption. CSRD sustainability reporting mandates automate ESG data extraction from unstructured documents via natural language processing pipelines. Île-de-France healthcare manufacturers engage consultants to navigate CE marking and ANSM validation requirements.
Netherlands
Amsterdam-based financial services firms and Rotterdam port logistics operators standardize on hybrid deployment architectures. The Dutch central bank's scrutiny of algorithmic trading models drives investment in model interpretability tooling. Eindhoven's semiconductor equipment manufacturers deploy edge inference for predictive maintenance at fabrication facilities.
Poland
Warsaw enterprise segments and Kraków shared service centers represent underpenetrated mid-market manufacturing demand. The country's national data protection authority applies GDPR provisions with particular attention to cross-border model training data flows. Silesian automotive suppliers lack in-house MLOps capability, creating channel partner expansion potential for managed deployment services.
Europe Machine Learning As a Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European MLaaS market. Hyperscalers with dedicated European data residency zones dominate sovereign cloud infrastructure procurement, while specialized platform vendors capture premium pricing for vertical-specific compliance tooling. The competitive structure fragments across three strategic archetypes: full-stack cloud providers, ERP-embedded ML platforms, and independent model operations specialists. Dominant competitive moves include strategic partnerships with national telecom operators for edge deployment and portfolio diversification into retrieval-augmented generation architectures.
Among full-stack cloud providers, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by silicon specialization and regional certification depth. SAP SE anchors the ERP-embedded tier by embedding predictive models directly into manufacturing client workflows. These named entities exemplify how competitive positioning stratifies between horizontal infrastructure scale and vertical integration depth.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| SAP SE |
| IBM Watson |
| DataRobot |
| H2O.ai |
| KNIME AG |
| Shift Technology |
| Others |
Value Network & Pricing Analysis
Ninety-day GPU allocation lead times for NVIDIA H100 clusters have compressed vendor pricing power and forced hyperscalers into strategic stockpiling commitments across Frankfurt and London cloud regions. This inventory pressure concentrates procurement leverage among hyperscalers with direct foundry relationships while squeezing margin pools for channel-dependent service providers.
Pricing Analysis
Consumption-based inference billing drives lifetime value through multi-year managed service contracts with guaranteed latency SLAs. Three-tier pricing structure across premium sovereign-certified, standard GDPR-aligned, and economy multi-tenant tiers separates regulated financial services buyers from mid-market manufacturers. Cost compression in economy tiers is intensifying because Polish and Romanian buyers negotiate aggressively on per-token rates. Healthcare providers in France and Germany show least price sensitivity due to EMA validation requirements.
Supply Chain Analysis
Just-in-time GPU provisioning dominates hyperscaler operations while strategic stockpiling of sovereign-certified inference capacity secures compliance positioning for EU AI Act high-risk deployments. Supply concentrates in Taiwan for advanced silicon fabrication, USA for NVIDIA GPU design, and Netherlands for ASML lithography equipment. Training infrastructure procurement draws from single-source GPU fabrication and specialized memory components. Tariff exposure on semiconductor equipment imports threatens capacity expansion timelines. Distribution runs through direct hyperscaler sales teams and specialized channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated Frankfurt and London banking consortia that negotiate collective procurement frameworks, fragmenting pricing leverage for individual vendors.
For Market Incumbents: Consolidate sovereign cloud certification depth as the primary defensive moat against emerging vertical-specialist challengers. Deepen backward integration into custom silicon design to reduce NVIDIA supply dependency. Expand capacity in Paris and Frankfurt regions to capture CE-marking workflow demand from French healthcare manufacturers.
For New Entrants and Emerging Players: MLOps engineering scarcity in Polish and Romanian mid-market manufacturing presents immediate service-layer opportunity. Target Silesian automotive suppliers lacking in-house pipeline deployment capability. Pursue channel partnership routes with national telecom operators for edge inference deployment at production facilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial software parents divesting non-core ML operations under portfolio rationalization pressure. Five-to-ten year viability hinges on EU AI Act compliance tooling differentiation. Monitor CE marking authorization queue lengths at French and Dutch notified bodies as inflection indicator for healthcare segment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | GDPR-aligned data residency zones unlock regulated industry procurement in Frankfurt and Paris regions. |
| Retrieval-Augmented Generation Deployment | Modular knowledge-base architectures reduce vendor lock-in for German automotive documentation search. |
| Edge Inference Partnership | 5G network convergence enables predictive maintenance at Stuttgart automotive production lines. |
| CE Marking Pathway Investment | Pre-market documentation capabilities capture EMA validation demand from Bavarian hospital networks. |
| Consumption-Based Pricing Transition | Per-token billing aligns London quantitative funds with real-time fraud detection workload patterns. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with cloud platform engineers, MLOps specialists at Frankfurt banking consortia, healthcare IT procurement leads in Bavarian hospital networks, and regulatory compliance officers navigating EU AI Act classifications. Secondary validation drew from hyperscaler capex disclosures, EMA guideline publications, CE marking authorization databases, and GDPR enforcement precedent records. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending projections.
Across the analysis window, the forecasting framework modeled deployment architecture segmentation, solution type tiers, end-user industry intensity, and regional regulatory compliance maturity. CAGRs derived from infrastructure investment run-rates, GPU cluster commissioning timelines, and enterprise workload migration patterns. Inference latency benchmarks and sovereign certification availability shaped adoption curve assumptions.
Underlying assumptions cover EU AI Act implementation timelines, NVIDIA supply allocation continuity, and hyperscaler regional expansion commitments, with deviation risk concentrated in CE marking interpretation divergence across national competent authorities. Revision becomes warranted when notified body queue lengths or GPU supply shocks cross thresholds that alter enterprise procurement timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Data Science Platform Market