
 Europe Machine Learning in Pharmaceutical Industry Market | 2026-2036
Europe Machine Learning in Pharmaceutical Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Machine Learning in Pharmaceutical Industry Market Analytics
CE marking under the EU Medical Device Regulation is reorganizing which machine learning vendors can serve European pharmaceutical clients. NVIDIA Corporation leverages its GPU-accelerated computing infrastructure to dominate training workloads for molecular simulation. Microsoft Corporation anchors enterprise adoption through Azure's compliance-bound cloud environments. SAP SE specializes in embedding predictive models into existing pharmaceutical ERP and supply chain workflows.
Europe Machine Learning in Pharmaceutical Industry encompasses algorithmic systems, software platforms, and computational frameworks that process biological, chemical, and clinical datasets to generate predictive insights, typically requiring validation against ISO 13485 quality management standards when deployed in regulated environments. These systems serve the primary commercial purpose of compressing discovery timelines and improving probability-of-success metrics in drug development pipelines. Drug discovery applications currently command the largest share of deployed solutions, while patient monitoring represents the fastest-expanding segment as continuous digital biomarker streams gain regulatory traction. Public cloud deployment dominates among mid-cap biotechnology firms seeking elastic compute access, though hybrid architectures are gaining ground among large pharmaceutical companies managing proprietary genomic datasets under GDPR constraints.
The European Medicines Agency maintains centralized guidance on AI-enabled drug development tools, while national regulators such as Germany's BfArM and France's ANSM issue supplementary position papers that create a layered compliance landscape. GDPR data-processing requirements directly shape how patient data feeds into training pipelines, often necessitating federated learning architectures that keep records within national borders. Stakeholders must monitor how the EU AI Act's risk-classification framework will recategorize diagnostic algorithms and predictive clinical models, as this will determine conformity assessment pathways and time-to-market for new offerings.
Market Dynamics
The EU AI Act's risk-classification framework is reorganizing which algorithmic systems pharmaceutical companies can deploy in clinical environments, forcing vendors to redesign conformity assessment pathways before the 2025 implementation deadlines.
Growth Catalysts
- CE marking under MDR:The EU Medical Device Regulation creates a harmonized entry path for AI-enabled diagnostic tools, reducing fragmentation across national approval processes and accelerating vendor market access.
- Federated learning architectures:GDPR-mandated data localization is spurring investment in privacy-preserving computation methods that keep patient records within national borders while enabling multi-site model training.
- Berlin-Munich cluster density:Germany's concentration of AI-native biotech startups alongside established pharmaceutical R&D centers generates talent pipelines and partnership networks that compress technology transfer timelines.
Market Restraints
- GPU supply concentration:Training infrastructure for molecular simulation depends on NVIDIA's datacenter accelerators, creating single-source vulnerability for compute-intensive discovery workloads.
- ISO 13485 validation timelines:Quality management certification for regulated deployments adds 18-24 months to product development cycles, delaying revenue recognition for platform vendors.
- Hybrid cloud capex requirements:Large pharmaceutical companies managing proprietary genomic datasets under GDPR constraints face substantial infrastructure investments to maintain on-premise data sovereignty.
Strategic Opportunities
- France's ANSM supplementary guidance:National regulators issuing position papers on AI-enabled drug development tools create early-mover advantages for vendors establishing compliance templates.
- Continuous digital biomarker streams:Patient monitoring applications represent underdeveloped deployment territory as wearable-derived data gains regulatory traction for post-market surveillance.
- Quantum-classical algorithm convergence:Hybrid computational methods for protein folding prediction open new service lines for vendors with access to emerging quantum hardware.
Industry Challenges
- Computational biology talent scarcity:The intersection of machine learning expertise and pharmaceutical domain knowledge remains thinly staffed, inflating compensation costs for qualified hires.
- Legacy ERP integration complexity:Embedding predictive models into existing SAP workflows requires substantial customization, extending implementation timelines and eroding project margins.
- Algorithmic interpretability standards:Explanability requirements under the EU AI Act's high-risk system category demand architectural redesigns that trade predictive accuracy for auditability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Machine Learning in Pharmaceutical Industry Market |
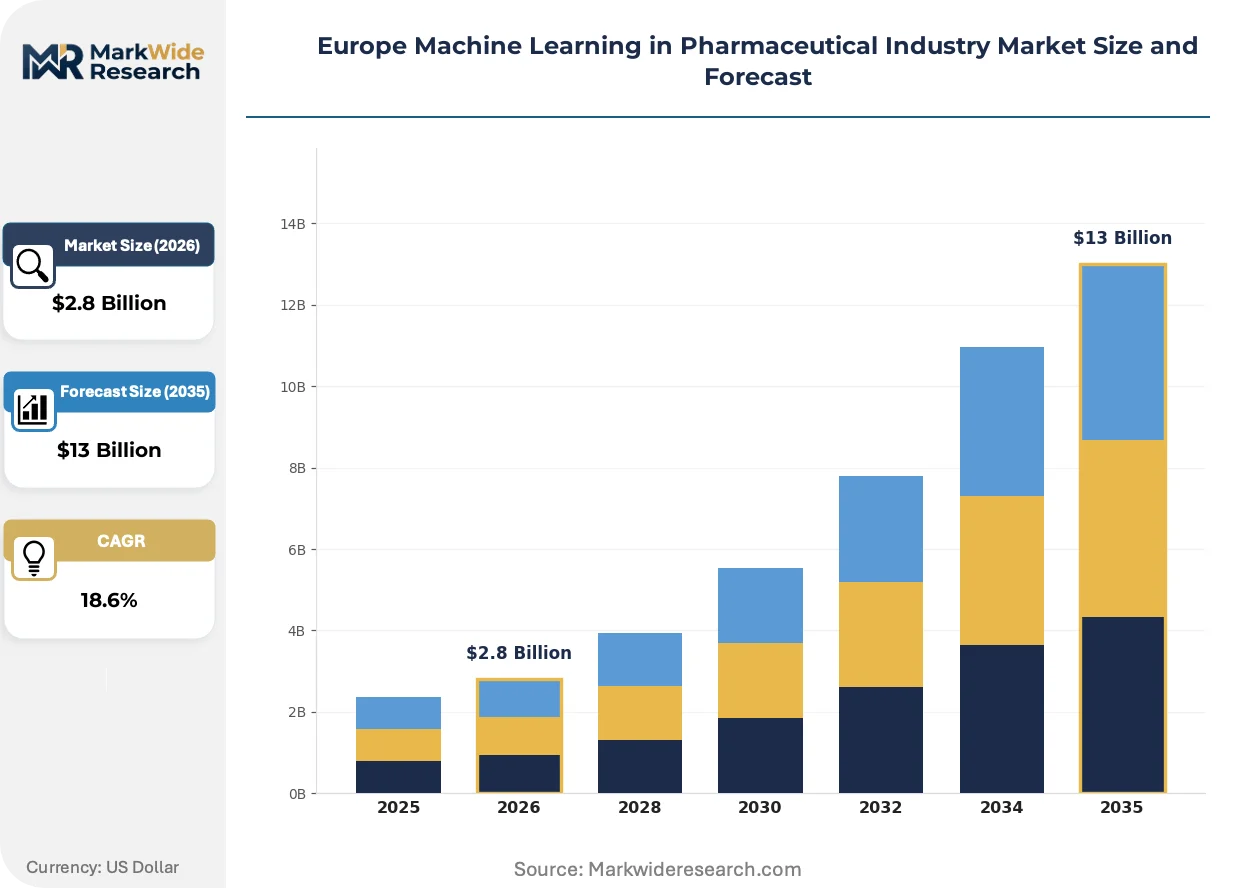
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Algorithm, Framework, Software, Platform Application: Drug Discovery, Clinical Trials, Patient Monitoring, Sales Forecasting Deployment Model: Public Cloud, Private Cloud, On-Premises, Hybrid End User: Pharmaceutical Companies, Research Labs, Contract Research Organizations, Biotechnology Firms |
| Companies Covered | NVIDIA Corporation, Microsoft Corporation, Alphabet Inc, International Business Machines Corporation, SAP SE, Shift Technology, KNIME AG, Cyclica Inc, BioSymetrics Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Machine Learning in Pharmaceutical Industry Market Evolving Landscape
Generative architectures trained on chemical structure databases are compressing molecular design cycles, while regulatory frameworks catch up to deployment velocity. Three shifts dominate the near-term landscape.
Transformer-based models for de novo molecular generation are decomposing traditional structure-activity relationship workflows. Mid-cap biotechnology firms with elastic cloud access are adopting these platforms fastest. The technology is decomposing the 4-6 year lead optimization phase into iterative computational cycles that run in weeks.
EMA's centralized guidance on AI-enabled drug development tools is converging with Germany's BfArM position papers to create a layered compliance architecture. Vendors must now map multiple regulatory pathways simultaneously. Small molecule discovery teams face the steepest adaptation burden as they revalidate existing algorithmic tools against emerging standards.
Pharmaceutical procurement departments are bundling model validation services with cloud compute contracts, unbundling traditional software licensing. Large-cap buyers now demand outcome-linked pricing tied to probability-of-success metrics. This shift is most visible in Germany, where procurement centralization across Merck, Bayer, and Boehringer Ingelheim sets regional contracting templates.
Europe Machine Learning in Pharmaceutical Industry Market Segmentation
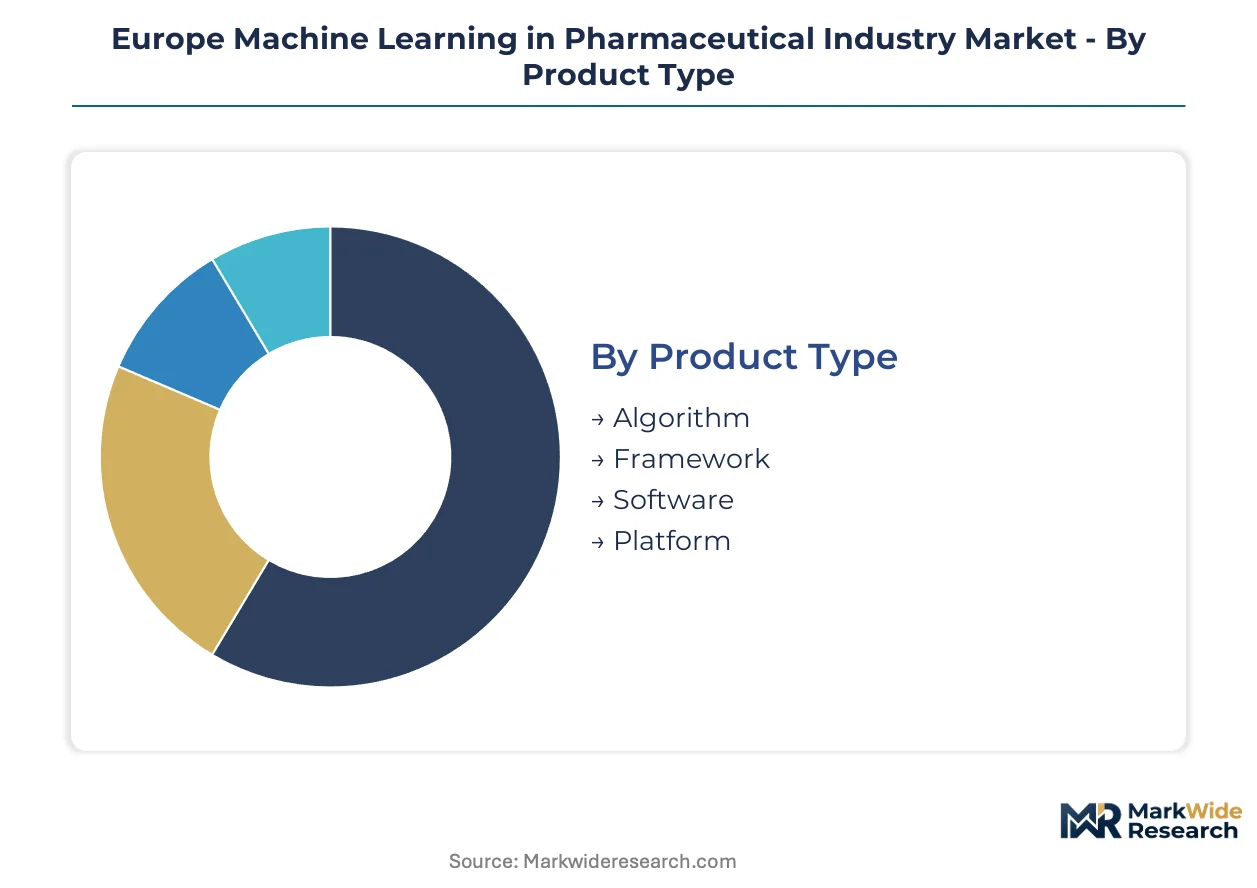
Machine learning deployments in European pharma fragment across four structural dimensions. Product architecture determines validation burden under EU AI Act risk classifications. Application focus shapes whether vendors pursue EMA centralized pathways or national regulator approvals.
Product Type:
Margin pools concentrate in integrated platforms commanding annual recurring revenue, while discrete algorithms compete on per-project pricing.
- Platform:End-to-end environments bundling data ingestion, model training, and regulatory documentation tools. Demand clusters in Germany's Berlin-Munich corridor where AI-native biotechs require turnkey compliance solutions against BfArM guidance.
- Software:Purpose-built applications for specific workflow stages such as compound screening or toxicity prediction. French and UK research labs drive procurement here, prioritizing CE marking readiness under MDR for faster deployment timelines.
- Algorithm:Modular predictive components requiring integration into existing pipelines. Contract research organizations in Spain and Italy favor these for flexibility across diverse sponsor requirements.
- Framework:Open-source or licensed code libraries demanding substantial in-house development. Large pharmaceutical companies with captive data science teams in Switzerland and the Netherlands dominate uptake.
The dominant share belongs to Platform, while Software is closing the gap fastest as mid-cap firms seek validated shortcuts to regulatory compliance.
Application:
Commercial traction splits between established discovery workflows and emerging surveillance use cases with divergent certification requirements.
- Drug Discovery:Molecular generation, target identification, and lead optimization algorithms trained on chemical structure databases. Germany and Switzerland anchor demand as Merck, Bayer, and Roche compress 4-6 year optimization phases into computational cycles.
- Patient Monitoring:Continuous digital biomarker analysis from wearables and connected devices for post-market surveillance. France's ANSM supplementary guidance on real-world evidence is accelerating regulatory traction here.
- Clinical Trials:Patient stratification, site selection, and adaptive trial design tools. UK and Nordic CROs deploy these to reduce recruitment timelines under EMA centralized trial frameworks.
- Sales Forecasting:Demand prediction and territory optimization for commercial operations. Southern European markets with fragmented healthcare procurement show strongest adoption.
Drug Discovery captures the largest revenue pool, though Patient Monitoring exhibits the steepest expansion trajectory as continuous data streams gain EMA recognition.
Deployment Model:
Infrastructure choices reflect GDPR data sovereignty requirements and genomic dataset sensitivity tiers.
- Public Cloud:Elastic compute access via Azure, AWS, or GCP with pre-configured compliance boundaries. Mid-cap biotechnology firms across Europe favor this for molecular simulation workloads without capital expenditure.
- Hybrid:Split architectures keeping proprietary genomic data on-premise while bursting training workloads to cloud. Large pharmaceutical companies in Germany and France invest here to satisfy GDPR localization mandates.
- Private Cloud:Dedicated tenant environments with single-organization isolation. Swiss and Austrian firms with strict data residency requirements dominate this segment.
- On-Premises:Fully captive infrastructure for highest-sensitivity datasets. National health service research divisions in the UK and Scandinavian university hospitals maintain these deployments.
Public Cloud holds the dominant position, yet Hybrid architectures are gaining share fastest as GDPR enforcement tightens around cross-border genomic data flows.
End User:
Procurement sophistication varies sharply between centralized pharma procurement functions and fragmented research lab purchasing.
- Pharmaceutical Companies:Integrated R&D and commercial divisions with centralized vendor qualification. German, Swiss, and UK headquarters drive enterprise platform adoption with outcome-linked pricing demands.
- Biotechnology Firms:VC-backed development-stage companies prioritizing speed-to-insight over compliance depth. Dense clusters in Cambridge, Berlin, and Paris favor public cloud algorithm access.
- Contract Research Organizations:Multi-sponsor service providers requiring flexible tooling across diverse therapeutic areas. Spanish and Italian CROs concentrate demand for modular software components.
- Research Labs:Academic and government institutions with grant-funded procurement cycles. Nordic and Benelux university hospitals lead in federated learning pilots for multi-site studies.
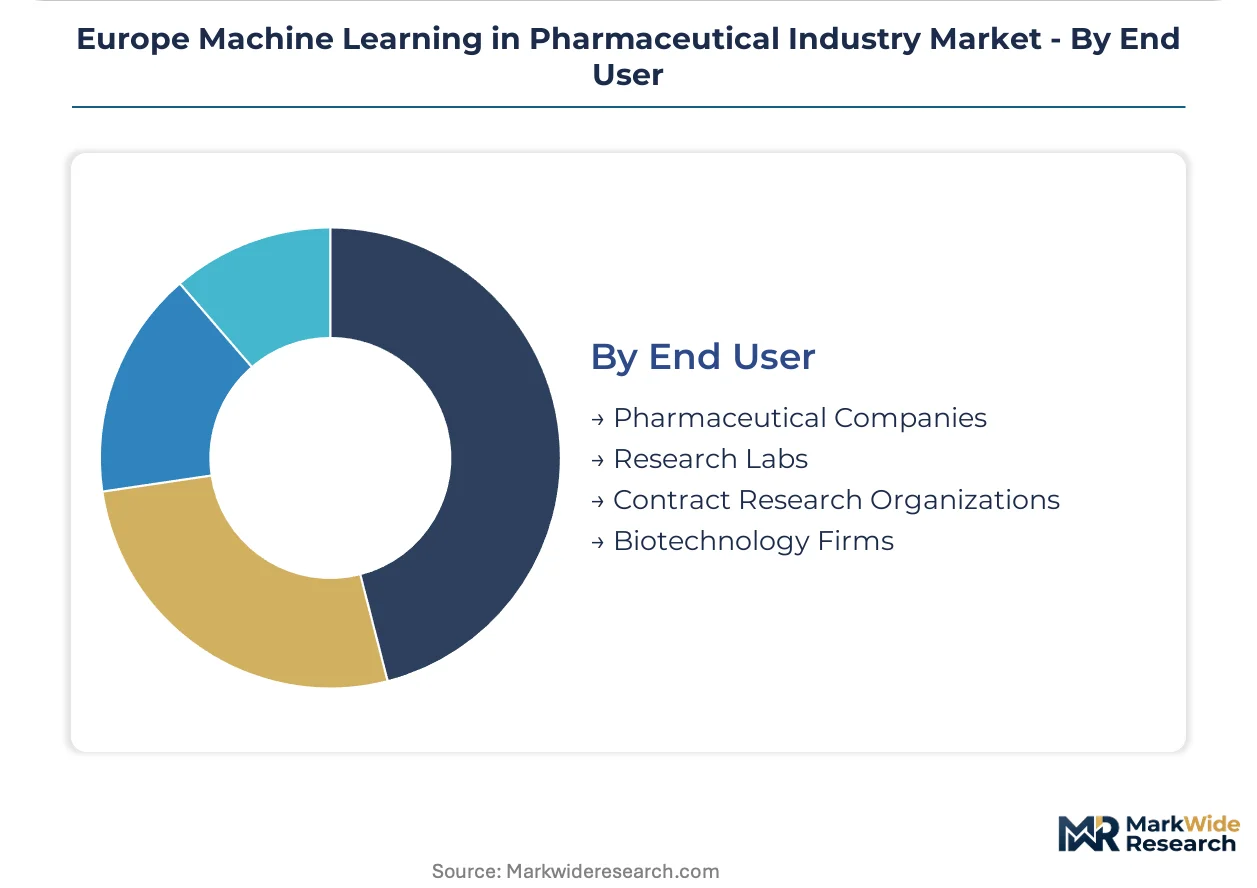
Pharmaceutical Companies command the dominant share, though Biotechnology Firms are expanding most quickly as AI-native startup formation accelerates across European clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement functions in Germany, the UK, France, Switzerland, and the Netherlands concentrate demand for machine learning platforms, with centralized vendor qualification processes favoring enterprise-scale deployments.
Germany
Berlin and Munich host dense clusters of AI-native biotech startups alongside Merck, Bayer, and Boehringer Ingelheim R&D centers. BfArM issues supplementary position papers on AI-enabled drug development tools that vendors must navigate alongside EMA centralized guidance. The procurement centralization across these headquarters establishes regional contracting templates that neighboring markets often adopt.
United Kingdom
Cambridge and London anchor demand from contract research organizations deploying patient stratification and adaptive trial design tools. MHRA alignment with EMA frameworks simplifies regulatory pathways for AI-enabled diagnostics seeking UK market access. Academic medical centers in Oxford and Manchester pilot federated learning architectures for multi-site genomic studies under NHS research divisions.
France
Paris-based biotechnology firms and Sanofi R&D operations drive adoption of continuous digital biomarker platforms. ANSM supplementary guidance on real-world evidence accelerates regulatory traction for wearable-derived post-market surveillance applications. The Île-de-France region concentrates both startup formation and pharmaceutical headquarters procurement functions.
Switzerland
Roche and Novartis headquarters in Basel command enterprise platform deployments with strict data residency requirements. Swissmedic maintains alignment with EU regulatory frameworks while preserving independent assessment pathways for high-risk AI systems. Zurich and Geneva host captive data science teams favoring framework-level toolkits over turnkey platforms.
Netherlands
Amsterdam and Rotterdam biotech clusters prioritize public cloud molecular simulation workloads with GDPR-compliant boundaries. The Dutch national pharmaceutical regulator implements EMA guidance with streamlined conformity assessment procedures for lower-risk algorithmic tools. Eindhoven's technical university partnerships supply computational biology talent to regional CROs.
Europe Machine Learning in Pharmaceutical Industry Market Competitive Landscape
Player mix skews toward cloud infrastructure providers and specialized AI platform vendors, with limited pure-play pharmaceutical software specialists. NVIDIA Corporation and Microsoft Corporation anchor the infrastructure layer through GPU-accelerated computing and compliance-bound cloud environments respectively. SAP SE occupies a distinct position embedding predictive models into existing ERP workflows. Strategic moves concentrate on federated learning partnerships and outcome-linked pricing models tied to probability-of-success metrics.
Within the infrastructure tier, NVIDIA Corporation and Microsoft Corporation exemplify divergent approaches to serving pharmaceutical R&D compute requirements. SAP SE represents the enterprise software archetype seeking to embed machine learning within established operational workflows. Alphabet Inc and International Business Machines Corporation occupy positions spanning cloud infrastructure and specialized health AI divisions. KNIME AG and Shift Technology illustrate the European specialist model targeting workflow-specific automation rather than end-to-end platform dominance.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft Corporation |
| Alphabet Inc |
| International Business Machines Corporation |
| SAP SE |
| Shift Technology |
| KNIME AG |
| Cyclica Inc |
| BioSymetrics Inc |
| Others |
Value Network & Pricing Analysis
GPU-accelerated cloud instances replacing on-premise HPC clusters simultaneously shift compute procurement toward Azure and AWS European regions and compress per-simulation pricing as pharmaceutical buyers aggregate volumes across federated learning networks.
Pricing Analysis
Cost-plus contracts with NVIDIA datacenter accelerator indexation dominate training workload procurement. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-validated platforms from CE-marked software and unvalidated algorithm components. Price differentiation rests on certification depth and genomic data sovereignty guarantees. Pricing pressure intensifies in the algorithm tier as open-source frameworks erode licensing value. Biotechnology firms exhibit highest price sensitivity; Swiss and German pharmaceutical headquarters tolerate premium positioning for validated compliance documentation.
Supply Chain Analysis
Just-in-time cloud bursting prevails among mid-cap firms, while large pharmaceutical companies maintain strategic stockpiles of proprietary genomic datasets on-premise. Compute infrastructure concentrates in Ireland, Germany, and the Netherlands where hyperscaler regions satisfy GDPR localization. Supply chains draw from NVIDIA's Taiwan fabrication, Samsung's South Korean memory production, and ASML's Dutch lithography systems. Single-source vulnerability in GPU accelerators creates concentration risk. Distribution runs through direct enterprise sales teams and specialized pharmaceutical IT integrators serving Berlin-Munich and Cambridge-London clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification creates a regulatory inflection that will bifurcate vendor viability between compliant platforms and legacy toolkits.
For Market Incumbents: Consolidate federated learning partnerships with German BfArM and French ANSM to preempt compliance template standardization. Acquire ISO 13485-certified algorithm vendors in Switzerland and the Netherlands before conformity assessment bottlenecks inflate valuations. Lock in outcome-linked pricing contracts with Merck, Bayer, and Roche procurement functions to defend margin position against cloud-native entrants.
For New Entrants and Emerging Players: Post-market surveillance software for wearable-derived digital biomarkers represents the most penetrable white-space where incumbent platforms lack validated deployment templates. Target French biotechnology firms navigating ANSM supplementary guidance with lightweight, CE-marked SaaS tools. Pursue channel partnerships with Spanish and Italian contract research organizations seeking modular algorithm access across diverse sponsor portfolios.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European AI platform vendors holding BfArM compliance templates but lacking enterprise scale. Five-to-ten year viability hinges on EU AI Act implementation enforcement consistency. Watch for EMA centralized guidance convergence with national regulator position papers as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding predictive models into SAP ERP workflows compresses implementation timelines for German pharmaceutical headquarters. |
| Regulatory Approval Pathway | CE marking under MDR creates harmonized entry for AI-enabled diagnostics across EU member states. |
| Strategic Partnership | Federated learning alliances with NHS research divisions enable GDPR-compliant multi-site genomic studies. |
| Acquisition of Specialist Firm | ISO 13485-certified algorithm vendors in Switzerland supply validated components for regulated deployments. |
| Geographic Expansion | Azure compliance-bound regions in Ireland and Germany satisfy pharmaceutical data sovereignty requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA guidance documents, BfArM position papers, and hyperscaler capex disclosures. Conversations with drug development executives, regulatory affairs leads, and hospital procurement managers inform deployment timeline assumptions. Bottom-up triangulation across platform vendor revenue disclosures and top-down validation against pharmaceutical R&D expenditure patterns anchor market sizing.
Segmentation dimensions modeled span product architecture, application focus, deployment model, and end-user procurement sophistication across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves for transformer-based molecular generation tools and federated learning pilot expansions. Treatment line stratification and regional regulatory cluster differentiation refine forecast granularity.
Material uncertainties — EU AI Act risk-classification enforcement timing, GPU supply concentration disruptions, and GDPR cross-border genomic data flow rulings — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory convergence and cloud infrastructure availability. Revision becomes warranted when BfArM or ANSM guidance diverges substantially from EMA centralized frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Data Science Platform Market