
 Semantic Knowledge Discovery Software Market | 2026-2036
Semantic Knowledge Discovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Semantic Knowledge Discovery Software Market Outlook
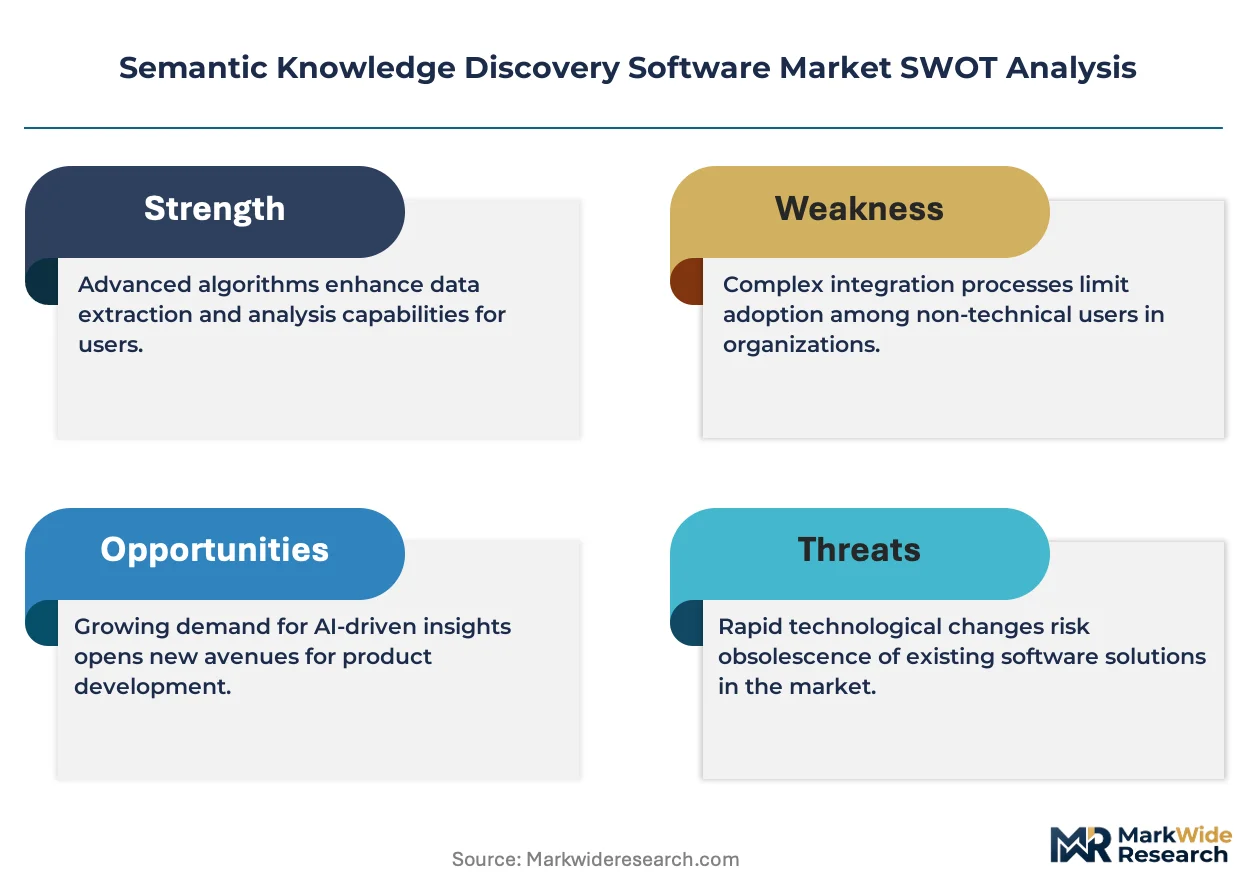
Data engineering talent scarcity is rotating enterprise procurement toward platforms with embedded ontology management and low-code graph construction interfaces. Cambridge Semantics leverages its Anzo suite to anchor complex data integration deployments in regulated industries. PoolParty sustains competitive differentiation through specialized taxonomy management and semantic tagging capabilities. Ontotext dominates the European market with GraphDB deployments that emphasize RDF store performance at enterprise scale.
Semantic knowledge discovery software comprises systems that apply formal ontologies, natural language processing, and graph-based inference to extract implicit relationships from heterogeneous data sources, typically operating across structured databases and unstructured document corpora with sub-second query response thresholds for real-time analytics. The primary commercial purpose centers on transforming siloed enterprise information into navigable knowledge networks that support automated reasoning and contextual search. Cloud-based solutions now lead deployment preferences as organizations prioritize elastic compute for large-scale graph analytics workloads, while hybrid solutions capture the fastest expansion among financial institutions managing sensitive data residency requirements. Text analytics applications sit at the margin center due to specialized licensing models for domain-specific linguistic pipelines in healthcare and legal sectors.
The EU AI Act and GDPR jointly shape European demand by mandating traceability in automated knowledge extraction systems, compelling vendors to architect provenance logging at the triple-store level. The US FDA and NIST frameworks influence healthcare and federal procurement by requiring validated semantic interoperability for clinical decision support tools. Stakeholders must monitor how divergent transatlantic compliance architectures affect cross-border knowledge graph deployments and data federation strategies.
Market Dynamics
The EU AI Act's risk-classification framework for automated decision systems is embedding explainability modules directly into semantic query engines, forcing vendors to architect provenance logging at the triple-store level across European deployments.
Growth Catalysts
- GDPR-Compliant Knowledge Extraction:The EU AI Act and GDPR jointly mandate traceability in automated knowledge extraction systems, compelling pharmaceutical companies to adopt semantic knowledge discovery platforms for validated clinical decision support pipelines.
- Federated Automotive Supply Chains:Industrial consortia in Germany are deploying federated knowledge discovery systems across automotive supply chains to enable real-time parts traceability and supplier risk analytics.
- Low-Code Graph Construction:Data engineering talent scarcity is rotating enterprise procurement toward platforms with embedded ontology management and drag-and-drop graph construction interfaces that reduce dependency on specialized RDF engineers.
Market Restraints
- Compute Cost Volatility:Large-scale graph analytics workloads on cloud infrastructure face unpredictable egress and compute pricing, compressing margins for vendors offering elastic semantic query services.
- RDF Store Performance Ceiling:Sub-second query response thresholds for real-time analytics strain triple-store architectures when traversing billion-node knowledge graphs, creating technical bottlenecks in enterprise-scale deployments.
- Cross-Border Compliance Friction:Divergent transatlantic compliance architectures between the EU AI Act and US FDA frameworks complicate cross-border knowledge graph deployments and data federation strategies for multinational enterprises.
Strategic Opportunities
- Healthcare Text Analytics Licensing:Specialized linguistic pipelines for clinical NLP in healthcare and legal sectors operate under underpenetrated licensing models, creating white space for domain-specific semantic tagging solutions.
- Hybrid Cloud Financial Deployments:Financial institutions managing sensitive data residency requirements are driving fastest expansion in hybrid deployment models that combine on-premise RDF stores with cloud burst analytics.
- Convergent Neuro-Symbolic AI:Integration of deep learning embeddings with symbolic reasoning engines is decomposing traditional boundaries between statistical and knowledge-based approaches, opening new application domains.
Industry Challenges
- Ontology Engineering Talent Gap:Scarcity of practitioners skilled in OWL, SHACL, and SKOS standards limits enterprise ability to maintain and evolve domain-specific knowledge graphs without vendor dependency.
- Legacy System Integration Complexity:Semantic knowledge discovery platforms must bridge heterogeneous structured databases and unstructured document corpora, requiring costly custom ETL pipelines and data harmonization projects.
- Explainability Certification Timelines:Validating semantic interoperability for clinical decision support tools under FDA and NIST frameworks extends procurement cycles and delays revenue recognition for healthcare-focused vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semantic Knowledge Discovery Software Market |
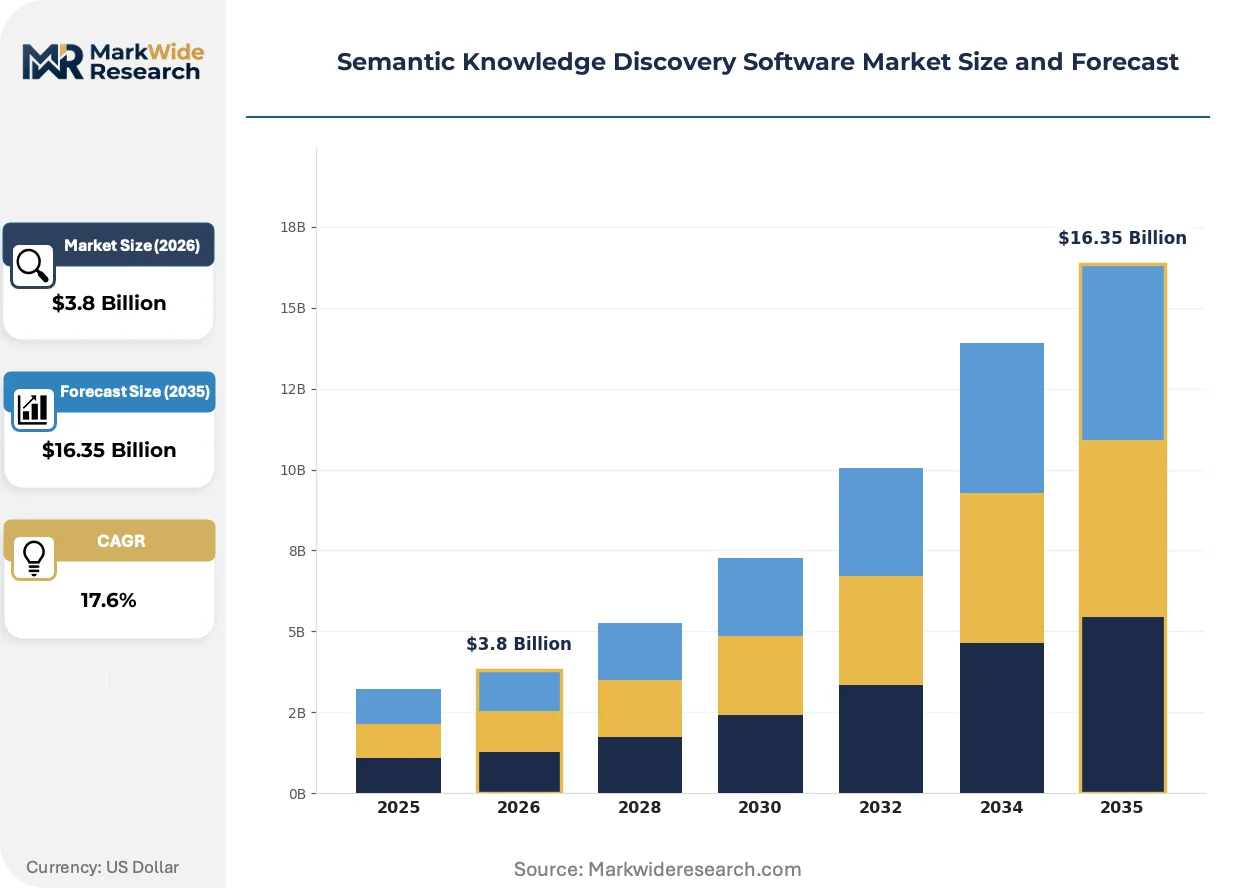
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Open Source Platforms End User: Healthcare Providers, Financial Institutions, Educational Institutions, Government Agencies Deployment: Private Cloud, Public Cloud, Hybrid Cloud, Edge Deployment Application: Data Integration, Predictive Analytics, Business Intelligence, Text Analytics |
| Companies Covered | MAANA, Cambridge Semantics, Expert System SpA, PoolParty, Nervana Intel, Collexis Elsevier, Ontotext, Stardog, ChemAxon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semantic Knowledge Discovery Software Market Strategic Shifts
Neuro-symbolic AI architectures are actively reshaping competitive positioning in semantic knowledge discovery by merging statistical pattern recognition with formal logical inference, compressing the traditional trade-off between scalability and explainability.
Vector embedding stores paired with symbolic knowledge graphs is decomposing the historical separation between semantic search and neural retrieval. Pharmaceutical companies are adopting these hybrid architectures to accelerate drug repurposing pipelines. This convergence is compressing vendor differentiation around pure-play RDF stores versus pure-play vector databases.
The EU AI Act's mandatory risk classification for automated decision systems is forcing vendors to embed explainability modules directly into semantic query engines. Industrial consortia in Germany are responding by requiring federated knowledge discovery systems that log provenance at the triple-store level. Healthcare deployments across Europe face the steepest compliance burden as clinical decision support tools fall under high-risk system definitions.
Enterprise buyers are consolidating vendor relationships around platforms offering embedded ontology management and low-code graph construction interfaces. Financial institutions with sensitive data residency requirements are displacing pure cloud deployments with hybrid solutions that keep core triple stores on-premise while bursting analytics workloads to elastic compute. This pattern is most visible in German automotive supply chains and US federal healthcare procurement.
Semantic Knowledge Discovery Software Market Segmentation
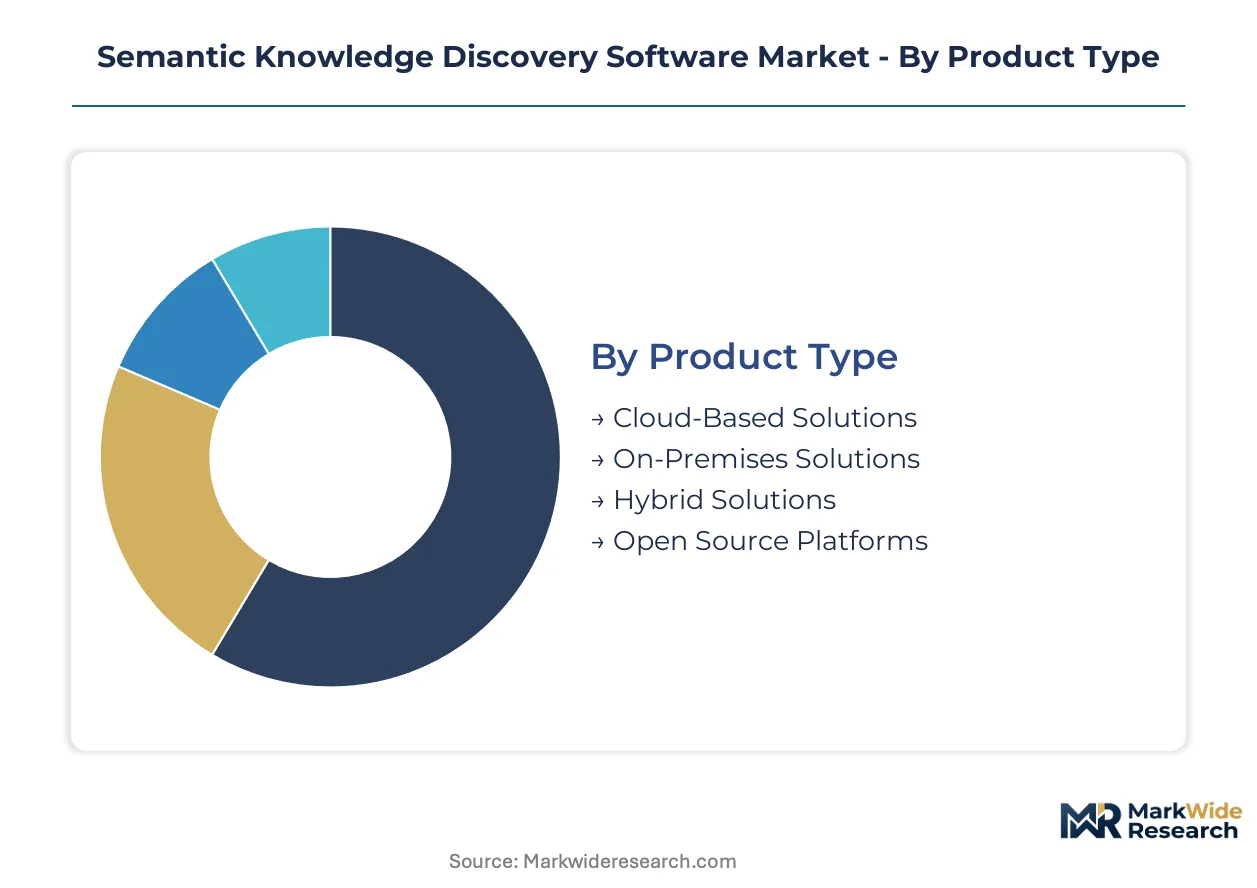
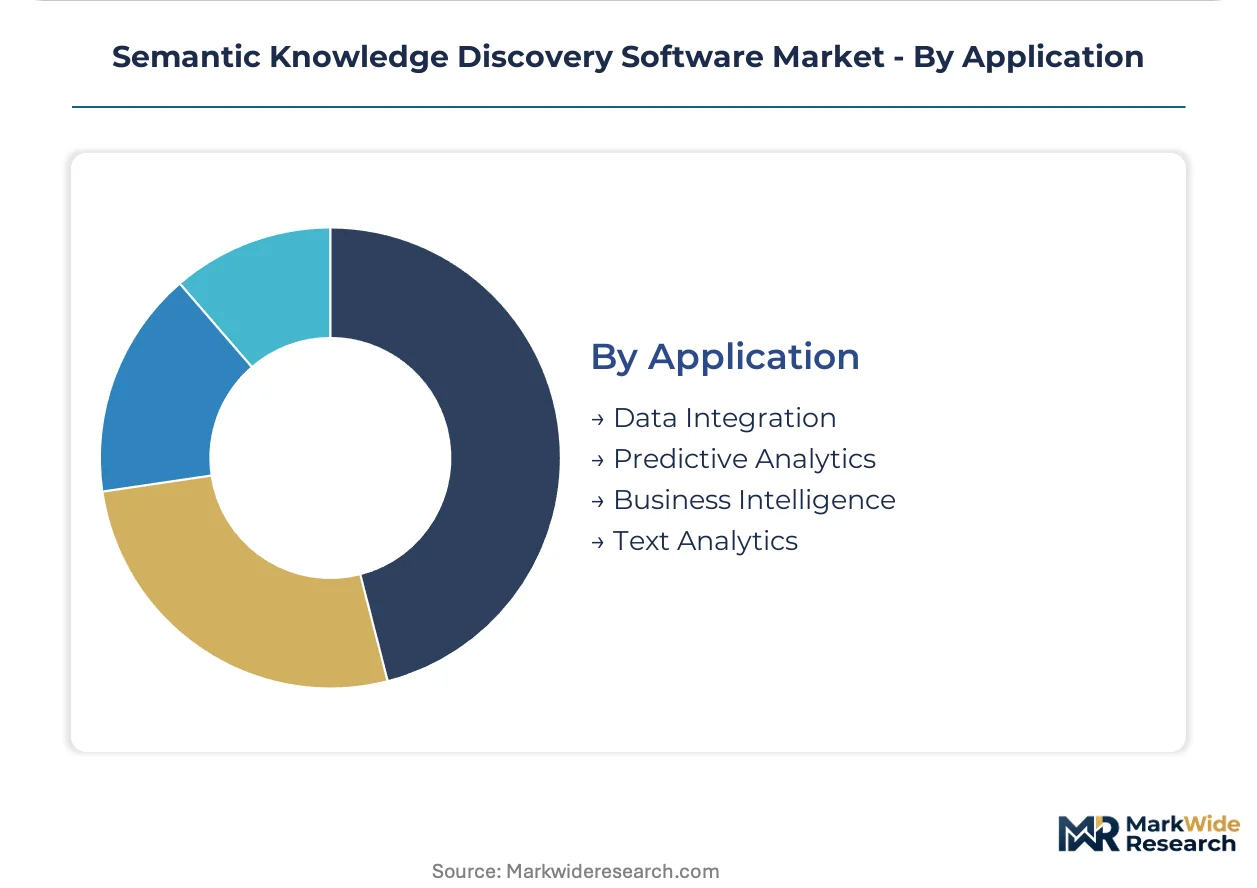
Semantic knowledge discovery software segments diverge sharply in architectural requirements and procurement economics. Cloud-native architectures face displacement pressure from hybrid models as data residency mandates tighten across regulated industries.
Product Type:
Substitution pressure runs strongest against pure cloud deployments as financial institutions and healthcare providers retreat from full SaaS dependency.
- Cloud-Based Solutions:Multi-tenant architectures with elastic compute provisioning dominate initial enterprise adoption. Pharmaceutical companies in Germany and the United States anchor demand for burst-capable graph analytics processing drug repurposing pipelines.
- Hybrid Solutions:On-premise RDF stores paired with cloud analytics burst capacity address strict data residency requirements. Financial institutions in Frankfurt and Singapore drive fastest expansion as Basel III and MAS guidelines harden custody rules for sensitive knowledge graphs.
- On-Premises Solutions:Air-gapped deployments persist in defense and intelligence sectors with validated security certifications.
- Open Source Platforms:Apache Jena and RDF4J foundations support academic and mid-market prototyping with limited commercial support ecosystems.
Cloud-based solutions retain volume leadership; hybrid solutions hold the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade deployments from departmental pilots across buyer categories.
- Healthcare Providers:Clinical decision support systems require validated semantic interoperability under FDA and EMA frameworks. Hospital networks in Boston and Munich concentrate procurement around explainable knowledge extraction for diagnostic assistance.
- Financial Institutions:Anti-money laundering and know-your-customer pipelines leverage federated knowledge graphs for counterparty risk analytics. Tier-1 banks in London and Zurich anchor demand for real-time entity resolution across transaction networks.
- Government Agencies:Federal knowledge management systems emphasize provenance logging and audit trails for FOIA compliance.
- Educational Institutions:Research libraries and digital humanities centers deploy lightweight taxonomy management for scholarly metadata federation.
Healthcare providers command the premium pricing tier; financial institutions show the most aggressive procurement velocity.
Deployment:
Application-critical workloads drive divergence between sovereign cloud requirements and cost-optimized public infrastructure.
- Private Cloud:Dedicated tenant environments with single-customer isolation satisfy GDPR Article 44 transfer restrictions. Automotive suppliers in Stuttgart and Wolfsburg mandate private infrastructure for supplier knowledge federation.
- Hybrid Cloud:Core triple-store residency on-premise with elastic query processing in public cloud balances latency against scale. This architecture gains fastest traction among insurers in Munich managing cross-border policy knowledge graphs.
- Public Cloud:Shared infrastructure delivers lowest unit economics for non-sensitive analytics workloads.
- Edge Deployment:Embedded semantic reasoning on manufacturing equipment supports real-time quality control with limited connectivity.
Private cloud maintains the largest installed base; hybrid cloud deployment is expanding most quickly across European regulated sectors.
Application:
Technology maturity separates established data integration use cases from emerging neuro-symbolic analytics frontiers.
- Text Analytics:Clinical NLP and legal document extraction command specialized licensing premiums due to domain-specific linguistic pipeline requirements. Healthcare systems in the United States and Germany concentrate procurement for unstructured EHR mining.
- Predictive Analytics:Knowledge graph embeddings power supply chain risk forecasting and pharmaceutical target identification. Industrial consortia deploy federated models across German automotive networks for supplier default prediction.
- Data Integration:Enterprise master data management and semantic ETL remain the foundational revenue base.
- Business Intelligence:Self-service knowledge exploration interfaces compete with established BI platforms for analyst attention.
Data integration retains volume leadership; text analytics holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive supply chains deploy federated knowledge discovery for real-time parts traceability, while US healthcare systems prioritize FDA-validated clinical decision support. Japanese industrial consortia emphasize hybrid cloud architectures for sensitive manufacturing data.
United States
Hospital networks in Boston and the Research Triangle anchor procurement for diagnostic assistance platforms. The FDA's framework for clinical decision support tools mandates validated semantic interoperability, extending procurement cycles for healthcare-focused vendors. Pharmaceutical companies in New Jersey and California deploy knowledge graphs to accelerate drug repurposing pipelines.
Germany
Industrial consortia across Baden-Württemberg and Bavaria mandate federated knowledge discovery systems for supplier risk analytics. The EU AI Act's risk-classification framework compels vendors to embed explainability modules directly into semantic query engines. Stuttgart and Wolfsburg automotive suppliers require private infrastructure for cross-border knowledge federation.
United Kingdom
Tier-1 banks in London leverage federated knowledge graphs for counterparty risk analytics and anti-money laundering pipelines. The Financial Conduct Authority's operational resilience requirements shape procurement for real-time entity resolution systems. Cambridge and Oxford research clusters drive academic adoption of open-source semantic platforms.
Japan
Manufacturing conglomerates in the Chubu region deploy hybrid cloud architectures balancing on-premise RDF stores with elastic analytics. METI's data governance guidelines influence enterprise preferences for sovereign cloud deployments. Osaka-based industrial groups integrate semantic reasoning with legacy ERP systems for supply chain optimization.
Switzerland
Zurich financial institutions anchor demand for real-time knowledge graph analytics across transaction networks. Swissmedic's regulatory framework shapes requirements for provenance logging in pharmaceutical knowledge discovery deployments. Basel and Geneva private banks prioritize hybrid solutions meeting strict data residency mandates.
Semantic Knowledge Discovery Software Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in semantic knowledge discovery software. The upper tier combines ontology management, graph database engines, and low-code construction interfaces into unified platforms. Specialist vendors concentrate on taxonomy management, clinical NLP pipelines, or RDF store performance optimization. Dominant competitive moves include embedding explainability modules for EU AI Act compliance and expanding hybrid cloud architectures for financial services procurement.
Within the integrated platform tier, Cambridge Semantics and Ontotext exemplify archetypes combining data integration engines with enterprise-scale graph databases. PoolParty occupies a position representing specialized taxonomy management and semantic tagging capabilities. Stardog anchors the segment of vendors emphasizing knowledge graph virtualization and data fabric architectures. These companies collectively represent the competitive spectrum from full-stack platforms to domain-focused specialists.
| Leading Market Players |
|---|
| MAANA |
| Cambridge Semantics |
| Expert System SpA |
| PoolParty |
| Nervana Intel |
| Collexis Elsevier |
| Ontotext |
| Stardog |
| ChemAxon |
| Others |
Value Chain & Pricing Dynamics
EU AI Act certification gates both vendor qualification and price differentiation in semantic knowledge discovery software, forcing buyers to pay premiums for explainability modules and provenance logging while restricting procurement to pre-qualified suppliers.
Pricing Analysis
Long-term enterprise licensing agreements dominate procurement, though project-based professional services for ontology engineering command spot-market premiums. Three-tier pricing structure across premium, standard, and economy levels separates validated clinical deployments from departmental pilots. Pricing pressure stems from open-source alternatives like Apache Jena compressing entry-level margins. Healthcare providers exhibit highest price sensitivity due to extended FDA validation timelines, while financial institutions accept premium tiers for real-time federated analytics.
Supply Chain Analysis
Specialized RDF engineering talent concentration in Germany, the United Kingdom, and the United States creates a chokepoint limiting platform customization velocity. Graph database engines draw from cloud infrastructure providers, GPU acceleration hardware, and domain-specific linguistic corpora. Single-source vulnerability runs through hyperscaler compute provisioning for elastic analytics workloads. Distribution runs through direct enterprise sales teams with embedded solution architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hospital networks and Tier-1 banks, compressing vendor margins and extending procurement cycles through consolidated RFP processes.
For Market Incumbents: Shield installed base relationships by embedding proprietary ontology libraries that increase switching costs. Accelerate certification investment for EU AI Act high-risk system compliance before smaller competitors achieve validation. Deepen backward integration into clinical NLP pipeline development to capture healthcare text analytics premiums.
For New Entrants and Emerging Players: Differentiate on neuro-symbolic AI architectures that merge vector embeddings with symbolic reasoning, addressing capability gaps in incumbent RDF stores. Target mid-market pharmaceutical companies in Germany seeking drug repurposing acceleration without full enterprise platform commitments. Pursue channel partnerships with systems integrators possessing existing healthcare compliance expertise.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid cloud infrastructure deployments as data residency mandates harden. Focus acquisition screening on taxonomy management specialists with proven EU regulatory track records. Watch for inflection when FDA issues draft guidance on semantic interoperability validation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cambridge Semantics and Ontotext are consolidating ontology management with graph engines to capture full-stack procurement budgets. |
| Acquisition of Specialist Firm | PoolParty's taxonomy expertise commands premium valuations as GDPR compliance drives semantic tagging demand. |
| Geographic Expansion | Stardog is penetrating Frankfurt financial institutions with knowledge graph virtualization for Basel III risk analytics. |
| Strategic Partnership | Industrial consortia in Stuttgart require federated deployments linking automotive suppliers through shared semantic infrastructure. |
| Product Launch | Explainability modules embedding provenance logging at triple-store level address EU AI Act high-risk system mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured dialogues with chief data officers, clinical informaticists, regulatory affairs leads at pharmaceutical companies, and semantic platform engineers; and secondary validation against FDA 510(k) filings, EMA qualification opinions, EU AI Act implementation guidance, and hyperscaler healthcare vertical disclosures. Bottom-up sizing triangulated deployment counts with top-down spend allocation patterns across enterprise IT budgets.
The projection horizon spans from baseline market characterization through forecast endpoint without year-specific anchoring. Segmentation dimensions modeled include deployment architecture, end-user vertical, application type, and regional regulatory cluster complexity. CAGRs derived from slope-intercept analysis of adoption curve inflection points, calibrated against cloud infrastructure spend growth and knowledge graph patent filing velocity.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or stable cloud compute pricing would require recalibration. Forecasts reflect assumptions about ontology engineering talent pipeline expansion and pharmaceutical R&D digitization continuity. Revision becomes warranted when FDA semantic interoperability guidance crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Natural Language Processing Market