
 Semantic Knowledge Graphing Market | 2026-2036
Semantic Knowledge Graphing Market Size, Share, and Industry Trends Forecast 2026-2036
Semantic Knowledge Graphing Market Analytics
Multi-source procurement of graph database engines is shifting toward hybrid deployments that blend cloud elasticity with on-premises data sovereignty. IBM Corporation leverages its Watson knowledge graph stack to anchor enterprise accounts in regulated industries. Neo4j Inc. specializes in native graph storage architectures that differentiate performance for real-time recommendation engines. Google LLC competes through deep integration of its Knowledge Graph API with cloud analytics pipelines.
Semantic knowledge graphing denotes the practice of encoding entities, relationships, and ontologies into machine-readable graph structures—typically using RDF triples or property graphs with labeled edges—to enable inference, disambiguation, and contextual retrieval across heterogeneous data sources. Graph databases and ontology management tools constitute the core technology layer, while SPARQL query engines provide standardized access patterns for federated knowledge bases. Cloud-based deployment captures the largest installed base as enterprises migrate from legacy data warehouses, though hybrid architectures gain traction among organizations subject to data residency constraints. Semantic search and knowledge discovery applications attract disproportionate R&D investment because they directly reduce manual data preparation overhead in analytics workflows.
The EU AI Act mandates explainability for high-risk automated systems, compelling vendors to build provenance-tracking features into graph platforms. The SEC's cybersecurity disclosure rules in the United States require granular asset inventories that knowledge graphs naturally support through entity resolution. ISO standards for semantic interoperability, including ISO/IEC 21838 for top-level ontologies, shape procurement criteria in government and research institution segments. Stakeholders must evaluate whether their graph infrastructure investments satisfy emerging auditability requirements before regulators finalize compliance timelines.
Market Dynamics
The EU AI Act's explainability mandates are forcing financial institutions to replace opaque neural networks with auditable graph architectures that expose decision pathways through explicit relationship mappings.
Growth Catalysts
- EU AI Act compliance mandates:High-risk automated decision systems in banking and insurance must maintain transparent audit trails. Knowledge graphs satisfy this by encoding every inference step as traversable triples.
- Supply chain interoperability standards:German industrial consortia deploy semantic ontologies to synchronize multi-tier supplier data across automotive and machinery sectors, reducing integration friction.
- Real-time fraud detection architectures:Property graph databases enable millisecond-scale pattern matching across transaction networks, replacing batch-processed rule engines in payment processing.
Market Restraints
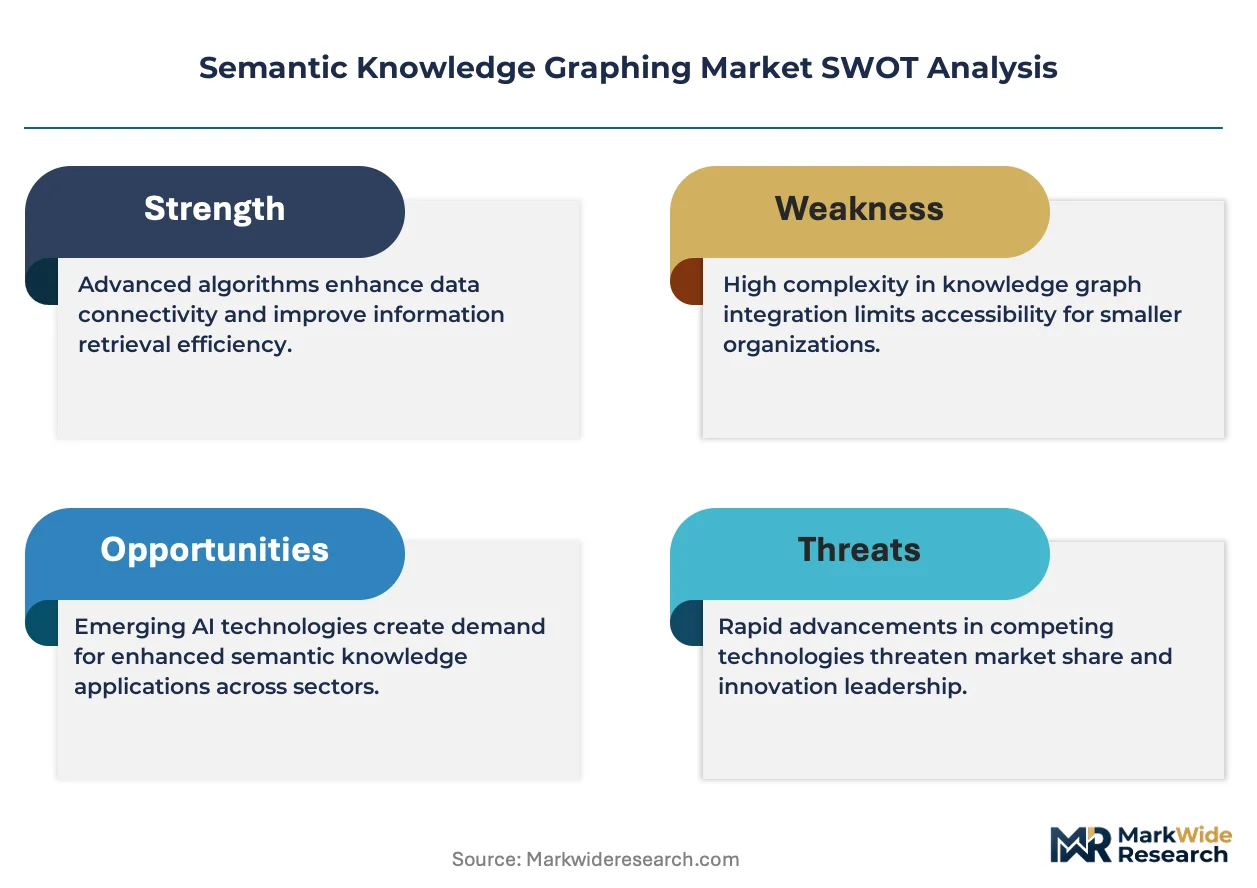
- Ontology engineering talent scarcity:The specialized skill set combining formal logic, domain expertise, and graph query optimization commands premium compensation, inflating implementation costs.
- Cloud infrastructure concentration:Hyperscale providers control the underlying compute layers for most managed graph services, creating vendor lock-in risks for data sovereignty-sensitive deployments.
- RDF triple store performance ceilings:Pure semantic architectures struggle with high-velocity streaming data compared to native property graph engines, limiting use cases requiring sub-second latency.
Strategic Opportunities
- Life sciences knowledge discovery:Biopharma researchers apply graph neural networks to protein interaction networks, accelerating target identification pipelines previously dependent on manual literature review.
- SEC cybersecurity disclosure alignment:Public companies must maintain granular asset inventories under new rules, creating demand for automated entity resolution systems that knowledge graphs natively provide.
- Convergence of vector embeddings and symbolic reasoning:Hybrid architectures combining LLM-generated embeddings with structured ontologies address the hallucination limitations of pure neural approaches in enterprise search.
Industry Challenges
- SPARQL expertise deficit:The standardized query language for RDF data remains unfamiliar to most data engineering teams trained in SQL, slowing migration timelines and requiring expensive retraining.
- Legacy data warehouse integration complexity:Enterprises with decades of accumulated relational schemas face expensive transformation pipelines to expose graph-traversable relationship structures without disrupting operational systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semantic Knowledge Graphing Market |
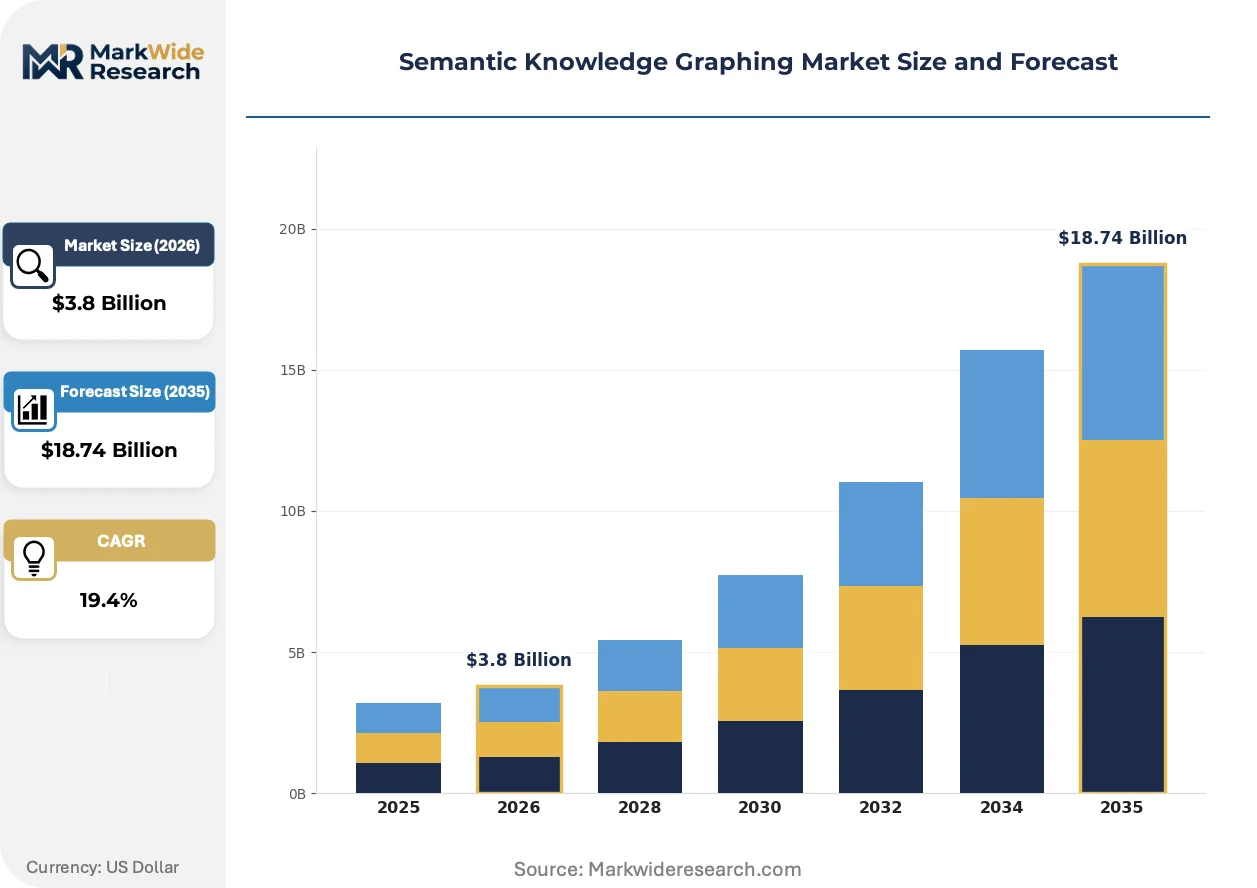
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Graph Databases, RDF, SPARQL, Ontology Management Deployment: Cloud-based, On-premises, Hybrid, Multi-Cloud Application: Data Integration, Knowledge Discovery, Business Intelligence, Semantic Search End User: Enterprises, SMEs, Government, Research Institutions |
| Companies Covered | IBM Corporation, Ontotext AD, Google LLC, Stardog, Franz Inc., Microsoft Corporation, Neo4j Inc., Cambridge Semantics, Amazon.com Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semantic Knowledge Graphing Market Evolving Landscape
Automated ontology generation from unstructured text is compressing the traditional months-long knowledge engineering cycle into days, reshaping how enterprises bootstrap graph infrastructure.
Graph-native machine learning is automating feature engineering for predictive models by extracting topological patterns—node centrality, community structure, and multi-hop relationships—directly from relationship data without manual variable construction. Pharmaceutical companies adopt these capabilities to predict drug repurposing candidates. The technique eliminates the domain expert bottleneck that previously constrained graph analytics adoption.
The EU AI Act's risk classification framework is compelling vendors to embed provenance tracking at the triple level, creating immutable audit logs for every inference chain. Financial services firms in Frankfurt and Paris prioritize platforms with built-in lineage capabilities. This regulatory pressure is differentiating compliant graph engines from general-purpose alternatives lacking forensic transparency.
Enterprise buyers increasingly demand consumption-based pricing for graph database services rather than perpetual licenses tied to core counts. Managed service providers in London and Singapore respond with serverless architectures that scale query throughput independently from storage. The shift favors cloud-native engines over self-managed deployments requiring dedicated infrastructure teams.
Semantic Knowledge Graphing Market Segmentation
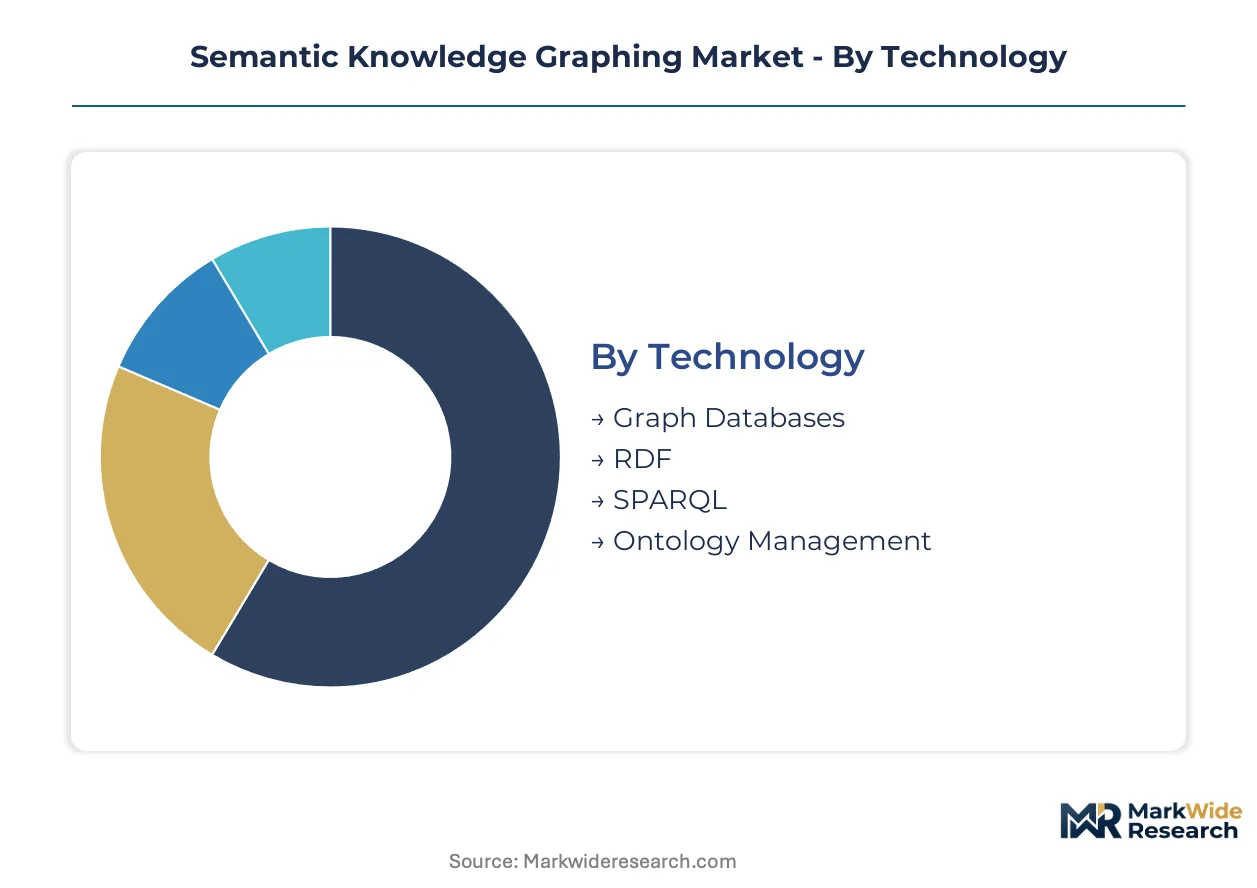
Segmentation reveals how procurement patterns diverge across technology maturity levels and regulatory exposure. Buyers with strict audit requirements favor provenance-heavy architectures, while latency-sensitive applications drive native engine selection.
Technology:
ISO/IEC 21838 certification burdens fall heaviest on RDF and ontology management segments, while graph databases face lighter standardization overhead.
- Graph Databases:Native storage engines optimized for property graph models with labeled edges and index-free adjacency. Financial services firms in Frankfurt deploy these for real-time fraud pattern matching where millisecond traversal speed determines system viability.
- RDF:Triple-store architectures encoding subject-predicate-object statements for semantic web interoperability. German automotive consortia mandate RDF for supply chain data exchange under industry-specific semantic standards, though SPARQL query latency limits streaming applications.
- SPARQL:Standardized query language for RDF data federation across distributed knowledge bases. Research institutions in Paris and Munich maintain the largest installed base despite persistent talent scarcity.
- Ontology Management:Tools for formal concept specification, reasoning rule definition, and taxonomy versioning. Biopharma researchers in Basel apply these for protein interaction network curation.
Graph databases sit at the top of the volume ranking, with ontology management climbing the fastest.
Deployment:
Cost tiering separates sovereign-heavy configurations from elastic consumption models.
- Cloud-based:Managed services with serverless query scaling and consumption-based pricing. London-based financial firms favor these for rapid experimentation cycles.
- On-premises:Self-managed infrastructure behind organizational firewalls. German machinery manufacturers insist on this mode to satisfy data residency constraints under national industrial data regulations.
- Hybrid:Split architectures keeping sensitive ontologies local while pushing compute-intensive inference to cloud bursts. Singaporean banks pioneered this pattern for EU AI Act compliance.
- Multi-Cloud:Federated deployments across competing hyperscale providers to mitigate concentration risk. Large European enterprises negotiate cross-cloud failover guarantees.
Cloud-based deployments hold the volume lead, with hybrid configurations expanding most quickly.
Application:
Customer type concentration varies sharply across use case complexity.
- Data Integration:Entity resolution and schema mapping across siloed enterprise systems. Automotive suppliers in Stuttgart apply semantic mediation to synchronize tiered supplier databases.
- Knowledge Discovery:Automated hypothesis generation from relationship patterns in scientific literature. Swiss pharmaceutical researchers deploy graph neural networks for drug repurposing candidate identification.
- Business Intelligence:Relationship-aware analytics replacing traditional star-schema warehouses. French insurers query policyholder connection networks for risk concentration detection.
- Semantic Search:Contextual retrieval systems disambiguating entity references through ontological grounding. German publishing houses license these for technical documentation portals.
Data integration commands the highest deployment volume, with knowledge discovery gaining share fastest.
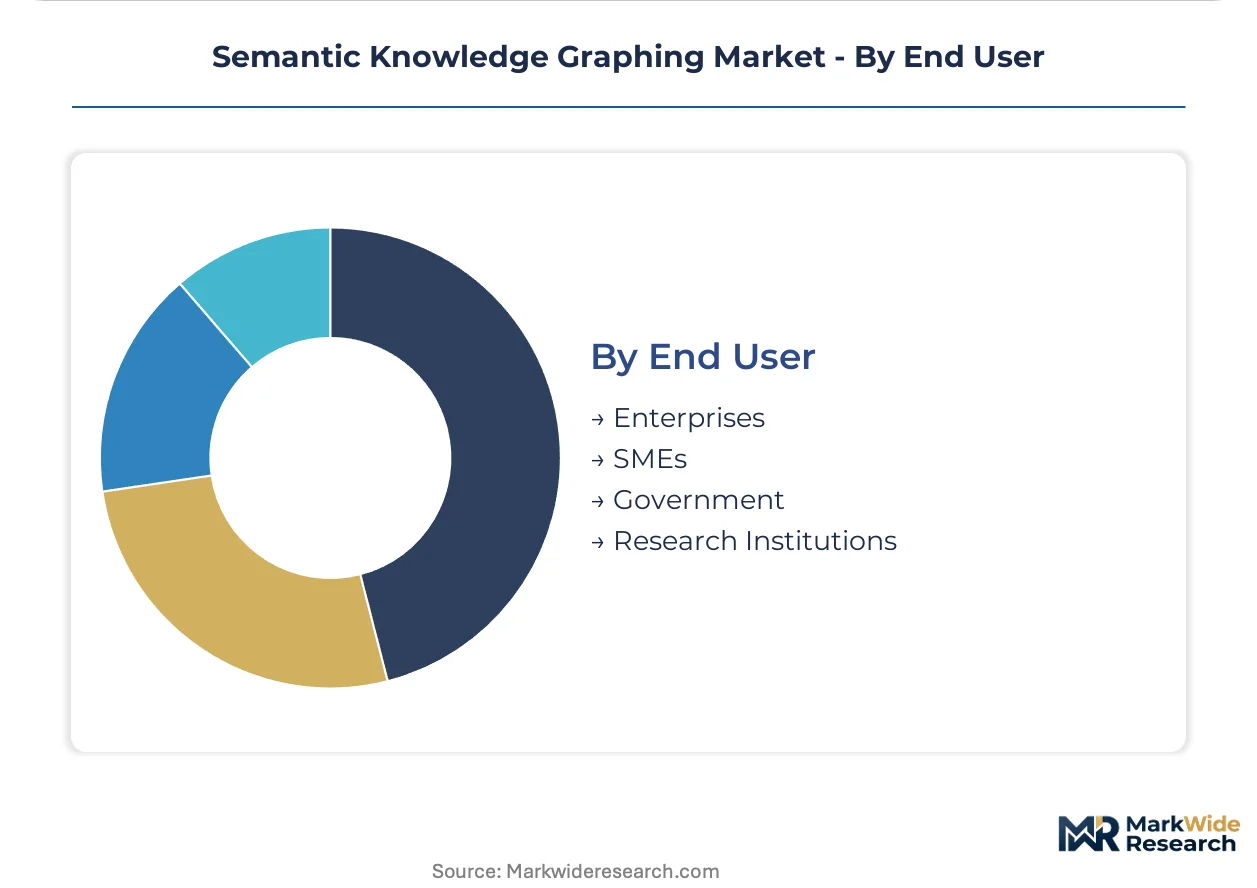
End User:
Margin structures diverge between procurement sophistication levels.
- Enterprises:Fortune 500-scale deployments with dedicated graph engineering teams. Frankfurt and Paris headquarters of major banks maintain the largest individual contract values.
- SMEs:Mid-market buyers purchasing through managed service bundles rather than direct platform licenses. Singaporean fintech startups represent the fastest-expanding cohort.
- Government:Public sector procurements emphasizing open standards and audit transparency. German federal agencies specify ISO-compliant ontology libraries.
- Research Institutions:Academic and non-profit users with grant-funded infrastructure. Basel and Munich university hospitals lead biopharma knowledge graph consortia.
Enterprises dominate current volume, with research institutions showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's financial district concentrates the highest density of knowledge graph deployments for regulatory compliance. German industrial consortia in Stuttgart and Munich drive semantic standardization for supply chain interoperability. The EU AI Act's transparency mandates are reshaping procurement patterns across European banking hubs.
Germany
Frankfurt-based insurers deploy graph architectures for EU AI Act audit trails. The country's national data protection authority enforces strict data residency requirements for financial AI systems. Stuttgart automotive suppliers apply semantic ontologies to synchronize tiered supplier databases across machinery and component networks.
United States
New York financial institutions replace opaque neural networks with traversable graph inference chains. The SEC's cybersecurity disclosure rules mandate granular asset inventories that entity resolution systems natively support. Boston biotech researchers apply graph neural networks to protein interaction networks for drug repurposing pipelines.
United Kingdom
London fintech startups adopt serverless graph architectures with consumption-based pricing for rapid experimentation cycles. The country's national data regulator enforces GDPR-aligned transparency requirements for automated decision systems. The city's insurance sector queries policyholder connection networks for risk concentration detection.
France
Paris headquarters of major banks prioritize platforms with built-in provenance tracking for forensic transparency. The EU AI Act's risk classification framework compels vendors to embed lineage capabilities at the triple level. Research institutions in the capital maintain substantial SPARQL query engine installations despite persistent talent scarcity.
Singapore
Singaporean banks pioneered hybrid deployment patterns keeping sensitive ontologies local while pushing compute-intensive inference to cloud bursts. The country's central bank and financial regulator enforce stringent data governance standards for cross-border AI operations. The city-state's fintech ecosystem represents the fastest-expanding mid-market buyer cohort for managed graph service bundles.
Semantic Knowledge Graphing Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and data sovereignty dimensions. The vendor landscape organizes into three tiers: hyperscale cloud providers with integrated analytics stacks, specialized native graph engine developers, and ontology management tool vendors. Strategic differentiation centers on provenance-tracking capabilities for regulatory compliance and hybrid deployment architectures for data residency constraints. M&A activity targets ontology engineering talent and vertical-specific knowledge bases.
Within the enterprise platform tier, IBM Corporation and Microsoft Corporation anchor positions in regulated industries through comprehensive cloud analytics integration. Neo4j Inc. exemplifies the specialized native graph engine archetype with labeled-edge storage architectures. Google LLC occupies a position among hyperscale providers competing through deep API integration with cloud analytics pipelines.
| Leading Market Players |
|---|
| IBM Corporation |
| Ontotext AD |
| Google LLC |
| Stardog |
| Franz Inc. |
| Microsoft Corporation |
| Neo4j Inc. |
| Cambridge Semantics |
| Amazon.com Inc. |
| Others |
Value Network & Pricing Analysis
Captive cloud infrastructure development by hyperscale providers anchors both supply positioning and pricing power in the semantic knowledge graphing market. IBM Corporation and Google LLC control underlying compute layers for managed graph services, enabling consumption-based pricing models that squeeze independent database vendors.
Pricing Analysis
Input-cost pass-through from cloud infrastructure fees dominates pricing structures for managed graph services. Three-tier pricing structure across enterprise, professional, and developer levels differentiates by query throughput limits and provenance-tracking depth. Pricing pressure stems from serverless architecture commoditization as Neo4j Inc. and Amazon.com Inc. compete on millisecond-latency benchmarks. SMEs exhibit highest price sensitivity, while Frankfurt-based financial institutions accept premium tiers for EU AI Act audit capabilities.
Supply Chain Analysis
ISO/IEC 21838 certification gating restricts ontology management tool sourcing to vendors with formal standards compliance. Germany, the United States, and Singapore concentrate supply for graph-native machine learning components and SPARQL query engine development. The supply chain draws from specialized chip architectures for vector embedding acceleration and open-source RDF libraries. Single-source vulnerability concentrates in hyperscale cloud regions serving European data residency requirements. Distribution runs through direct enterprise sales for regulated sectors and managed service bundles for mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between German data sovereignty requirements and Singaporean cloud elasticity creates margin expansion opportunities for vendors with hybrid deployment architectures. The EU AI Act's audit trail mandates impose compliance costs in Frankfurt that Singaporean banks avoid through burst-compute models.
For Market Incumbents: Deploy provenance-tracking capabilities as a defensive moat against emerging cloud-native competitors. IBM Corporation and Microsoft Corporation should accelerate ISO/IEC 21838 certification roadmaps to preempt regulatory displacement. Graph database vendors must integrate vector embedding pipelines before pure-play AI search vendors capture semantic search market share.
For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for specialized audit-trail platforms serving Tier 2 automotive suppliers. Ontology engineering talent scarcity in Paris and Munich creates acquisition opportunities for remote-first development teams. Target biopharma knowledge discovery in Basel through graph neural network partnerships with university research hospitals.
For Investors and Strategic Acquirers: Consolidation pressure builds where ontology engineering talent scarcity intersects with vertical-specific knowledge base ownership. Long-term viability favors platforms with hybrid deployment architectures spanning Frankfurt data centers and Singapore cloud regions. Acquisition targets should demonstrate ISO-compliant ontology libraries and proven life sciences customer traction. Watch SPARQL-to-vector query engine convergence as an inflection signal for platform obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Architecture Development | Frankfurt-Singapore split configurations satisfy EU AI Act residency rules while preserving cloud elasticity. |
| Provenance-Tracking Platform Integration | Triple-level audit logs differentiate compliant engines from general-purpose alternatives lacking forensic transparency. |
| Graph Neural Network Capability Acquisition | Swiss pharmaceutical researchers prioritize platforms with automated drug repurposing candidate identification. |
| SPARQL Query Engine Modernization | Latency improvements address streaming data limitations that constrain RDF adoption in payment processing. |
| Vertical Ontology Library Licensing | German automotive consortia mandate industry-specific semantic standards for supply chain data exchange. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged graph database engineering leads, EU AI Act compliance officers at Frankfurt banks, ontology architects in Stuttgart automotive consortia, and procurement managers at Singaporean fintech startups. Secondary validation drew from SEC cybersecurity disclosure filings, EMA regulatory guidance documents, ISO standards publication records, and hyperscaler cloud service revenue breakdowns. Bottom-up deployment counts triangulated against top-down vendor revenue estimates across the analysis window.
Segment-weighting approaches applied differential growth assumptions by deployment model and end-user sophistication. Technology segmentation modeled graph databases, RDF triple stores, SPARQL engines, and ontology management tools. Geographic clustering captured German industrial data regulations, US SEC disclosure requirements, and Singaporean cross-border AI governance standards. CAGRs derived from vendor revenue trajectories and enterprise procurement survey data. Forecast inputs incorporated EU AI Act implementation timelines and SPARQL talent availability indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or hyperscale cloud pricing wars. Assumptions reflect current regulatory draft language and vendor product roadmaps. Deviation in ontology engineering graduate pipeline output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Cloud Machine Learning Market