
 Machine Learning in Communication Market | 2026-2036
Machine Learning in Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Learning in Communication Market Intelligence
The EU AI Act is restructuring procurement criteria for automated customer engagement platforms across European telecom carriers. Nokia leverages its Bell Labs research pipeline to sustain algorithmic leadership in radio access network optimization. Ericsson anchors its competitive position through specialized ML models for predictive maintenance across 5G infrastructure deployments. Huawei competes aggressively on manufacturing scale for edge-based communication chips, though geopolitical restrictions limit its addressable markets in North America and parts of Europe.
Machine learning in communication encompasses algorithmic systems that analyze, predict, and automate information exchange across network infrastructures, typically processing signal data through neural architectures with latency thresholds under 50 milliseconds for real-time applications. These systems optimize bandwidth allocation, detect anomalies in traffic patterns, and personalize content delivery across cellular, fiber, and satellite channels. Natural language processing dominates the technology segment as carriers deploy conversational AI for subscriber support, while deep learning applications in voice recognition capture expanding margin pools from enterprise unified communications contracts. Cloud-based deployment leads in commercial traction due to elastic scaling for seasonal traffic spikes, though edge computing configurations are gaining ground among latency-sensitive industrial IoT users.
The FCC in the United States enforces net neutrality principles that shape how ML traffic management algorithms prioritize data flows, while GDPR in Europe constrains the training datasets available for sentiment analysis tools processing subscriber communications. China's MIIT mandates GB standards for algorithmic transparency in automated calling systems, creating divergent compliance pathways for multinational equipment vendors. Stakeholders must monitor the interplay between emerging spectrum allocation policies and the computational requirements of generative AI models poised to transform voice synthesis and real-time translation services.
Market Dynamics
Telecom infrastructure vendors face intensifying pressure from the EU AI Act's algorithmic transparency mandates, which force redesigns of automated network management systems and reshape procurement evaluation criteria across European carrier procurement departments.
Growth Catalysts
- Edge computing deployments:Industrial IoT users in Germany and Japan demand sub-50 millisecond latency for predictive maintenance applications, pulling ML inference closer to radio access network nodes.
- FCC net neutrality frameworks:Traffic prioritization rules in the United States create compliance-driven demand for sophisticated bandwidth allocation algorithms that optimize quality-of-service without violating open internet principles.
- 5G infrastructure rollouts:Predictive maintenance models for antenna arrays and base stations generate recurring software revenue streams from tier-one carriers upgrading radio access networks.
Market Restraints
- GPU supply concentration:Taiwan-based foundries control advanced semiconductor manufacturing for neural network training hardware, creating single-source vulnerability for edge AI chip procurement.
- GDPR data constraints:European sentiment analysis tools face restricted training dataset access for subscriber communications, limiting model accuracy in customer engagement platforms.
- Geopolitical fragmentation:Export controls on Chinese equipment vendors fragment global standards for ML-optimized baseband processors, forcing dual supply chain configurations.
Strategic Opportunities
- Generative AI voice synthesis:Real-time translation and synthetic voice services for enterprise unified communications represent underexploited margin pools in North American and European business segments.
- India's PLI scheme:Production-linked incentives for telecom equipment manufacturing attract ML chip packaging investments serving South Asian and Middle Eastern carrier markets.
- Convergence with digital twins:Network digital twin platforms integrating ML-driven simulation create new subscription revenue models for infrastructure planning and failure prediction.
Industry Challenges
- Radio frequency engineering talent scarcity:The intersection of machine learning expertise and wireless propagation physics creates recruitment bottlenecks for algorithm development teams.
- Legacy OSS/BSS integration:Carrier operational support systems built on 1990s architectures resist API-based connectivity with cloud-native ML platforms, extending deployment timelines.
- Model certification delays:National regulators in France and Germany impose extended validation periods for AI systems managing emergency calling routing, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Learning in Communication Market |
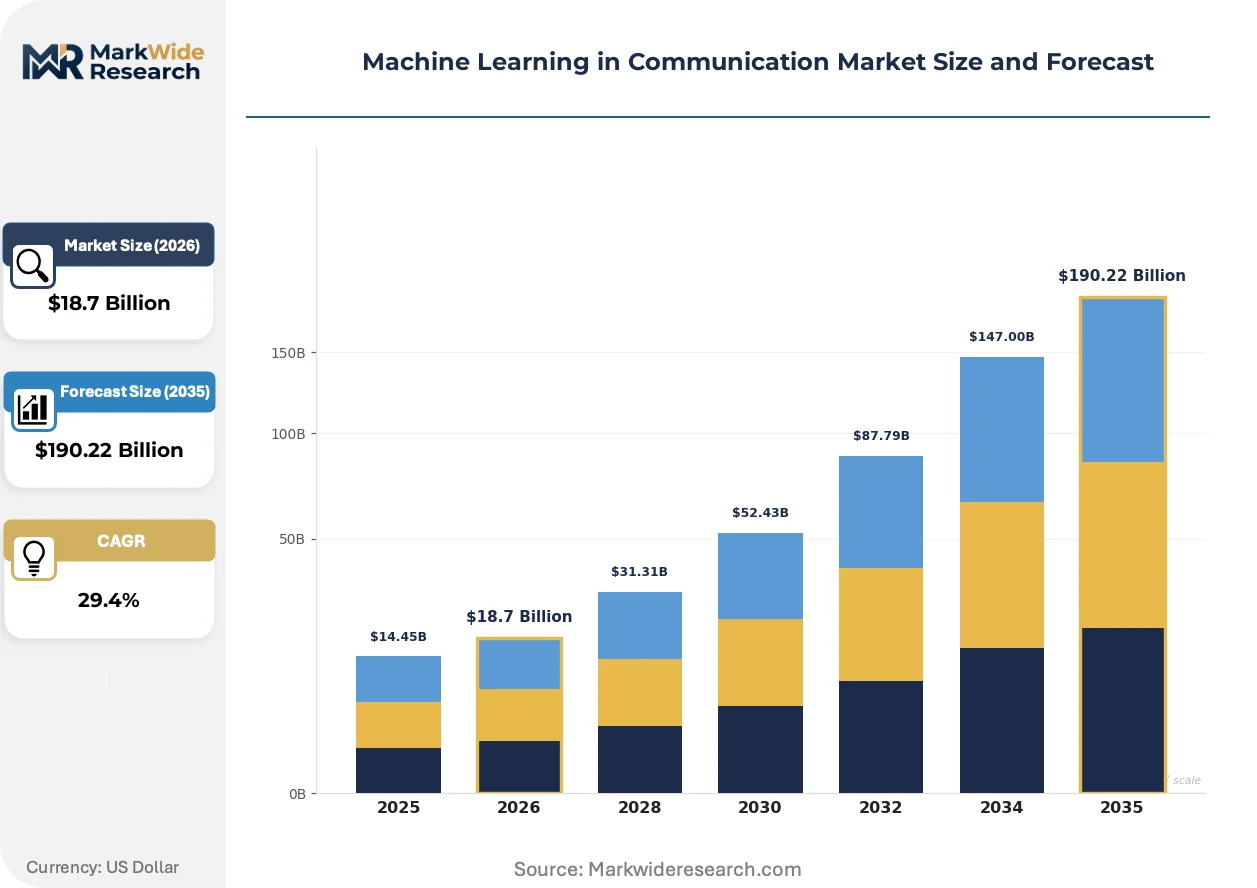
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $190.22 Billion |
| CAGR (2026 – 2036) | 29.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Chatbots, Predictive Analytics, Voice Recognition, Sentiment Analysis Technology: Natural Language Processing, Neural Networks, Deep Learning, Regression Analysis End User: Telecom, Education, E-commerce, Healthcare Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Nokia, Ericsson, Huawei, Cisco Systems, IBM, Google, Amazon Web Services, Microsoft, ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Learning in Communication Market Strategic Shifts & Innovations
Neural architectures for real-time signal processing are compressing development cycles for intelligent communication platforms, while regulatory frameworks force algorithmic accountability into product roadmaps. Three developments dominate vendor strategy.
Federated learning architectures are overtaking centralized training paradigms for subscriber behavior modeling. European carriers under GDPR pressure adopt distributed approaches that keep raw call detail records on-device while aggregating only model updates. This shift reduces data center bandwidth costs and accelerates compliance timelines for cross-border traffic analysis.
The EU AI Act's risk classification system imposes documentation burdens on automated network optimization tools deemed high-risk. Equipment vendors must maintain technical files proving algorithmic robustness for base station load balancing. German and French regulators lead enforcement, creating competitive advantage for vendors with pre-existing quality management systems certified under MDR frameworks.
Enterprise buyers now unbundle AI-powered analytics from core connectivity contracts. Large manufacturing firms in the United States negotiate separate agreements for predictive network performance tools, bypassing traditional carrier bundles. This procurement fragmentation favors specialized software vendors with direct sales relationships to industrial automation teams.
Machine Learning in Communication Market Segmentation
Machine learning applications in communication infrastructure fragment across integration depths, from embedded algorithms in network hardware to standalone platforms for subscriber engagement. Understanding these segment boundaries clarifies procurement patterns and margin structures for equipment vendors and service providers.
Application:
Standalone platforms dominate customer-facing deployments, while embedded algorithms handle network optimization without direct subscriber interaction.
- Chatbots:Conversational AI systems automate subscriber support through natural language interfaces, typically handling billing inquiries and service troubleshooting. North American carriers deploy these most aggressively for cost reduction in call center operations, driven by FCC net neutrality compliance requirements that favor automated over human traffic management interventions.
- Predictive Analytics:Algorithmic models forecast network congestion, equipment failures, and subscriber churn using historical traffic patterns. European operators under GDPR constraints favor federated learning architectures that process data locally at base stations, limiting cross-border data transfers while maintaining forecasting accuracy for radio access network planning.
- Voice Recognition:Speech-to-text and speaker identification systems authenticate callers and transcribe communications for compliance archiving.
- Sentiment Analysis:Emotion detection algorithms process customer interactions to prioritize escalations and personalize retention offers.
Predictive analytics leads volumes today; chatbots are gaining share fastest.
Technology:
Cost tiers separate foundation models requiring massive training infrastructure from lightweight inference engines deployable at network edge.
- Natural Language Processing:Text analysis and generation systems power conversational interfaces and automated content moderation across messaging platforms. Enterprise unified communications contracts in the United States drive premium pricing for multilingual NLP pipelines that support real-time translation in video conferencing applications.
- Neural Networks:Layered computational architectures process signal data for radio frequency optimization and anomaly detection. Japanese industrial IoT deployments demand sub-50 millisecond inference latency, pulling neural network inference onto specialized edge accelerators co-located with factory floor access points.
- Deep Learning:Multi-layered architectures train on massive datasets for voice synthesis and speaker verification tasks.
- Regression Analysis:Statistical methods predict network performance metrics and subscriber lifetime value with interpretable outputs.
Neural networks lead volumes today; deep learning is expanding most quickly.
End User:
Application maturity varies sharply across customer types, with telecom carriers representing established demand and healthcare emerging as a compliance-intensive growth vertical.
- Telecom:Network operators deploy ML across radio access optimization, predictive maintenance, and subscriber engagement platforms. German carriers face EU AI Act documentation requirements for automated base station load balancing, creating procurement preference for vendors with pre-certified quality management systems.
- Healthcare:Telemedicine providers and connected medical device manufacturers process patient communications through privacy-preserving algorithms. HIPAA constraints in the United States limit training data sharing, driving adoption of federated learning approaches that keep clinical conversations within hospital network perimeters.
- Education:Universities and online learning platforms automate administrative communications and personalize student outreach.
- E-commerce:Retailers optimize customer service routing and fraud detection in payment communications.
Telecom leads volumes today; healthcare is climbing the fastest.
Deployment:
Supply concentration in cloud infrastructure contrasts with distributed edge manufacturing, creating divergent procurement risk profiles for carrier technology teams.
- Cloud-Based:Centralized data center deployment enables elastic scaling for seasonal traffic spikes and model retraining at scale. United States carriers leverage AWS, Azure, and Google Cloud regions for subscriber analytics, though FCC net neutrality enforcement creates compliance complexity for traffic prioritization algorithms running on shared infrastructure.
- Edge Computing:Localized inference at radio access nodes and customer premises equipment minimizes latency for industrial automation and emergency services. Germany's automotive manufacturing corridors drive concentrated demand for edge ML in predictive maintenance applications requiring sub-50 millisecond response times.
- On-Premises:Dedicated hardware installations within carrier facilities satisfy data sovereignty requirements.
- Hybrid:Architectures split training workloads to cloud and inference to edge for optimized cost-latency tradeoffs.
Cloud-based leads volumes today; edge computing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The machine learning in communication industry traces its commercial origins to Bell Labs innovations in New Jersey and subsequent algorithmic research at NTT in Japan, with contemporary deployment patterns now spanning carrier networks across five distinct national markets.
United States
Cloud hyperscalers and tier-one carriers drive demand for intelligent network optimization platforms. FCC net neutrality enforcement shapes how ML algorithms manage traffic prioritization across shared infrastructure. Seattle and Northern Virginia host concentrated development of conversational AI tools for enterprise unified communications.
Germany
Automotive manufacturing corridors generate specialized demand for sub-50 millisecond edge inference in predictive maintenance applications. EU AI Act documentation requirements force algorithmic transparency redesigns for automated base station management. Munich and Stuttgart anchor concentrated procurement of ML-optimized radio access network equipment.
China
Domestic equipment vendors scale manufacturing of edge-based communication chips despite export control limitations. MIIT mandates GB standards for algorithmic transparency in automated calling systems. Shenzhen and Beijing clusters concentrate development of neural architectures for signal processing.
Japan
Industrial IoT deployments pull ML inference onto specialized accelerators co-located with factory floor access points. METI standards guide spectrum allocation policies affecting computational requirements for real-time translation services. Nagoya and Osaka manufacturing belts drive concentrated adoption of predictive maintenance models.
India
Production-linked incentive schemes attract ML chip packaging investments serving South Asian carrier markets. TRAI regulations shape data localization requirements for subscriber behavior modeling platforms. Bangalore and Hyderabad anchor development centers for natural language processing pipelines in regional languages.
Machine Learning in Communication Market Key Industry Players
Premium-margin players sit above commodity-margin players across algorithmic specialization depth, with consolidated control of radio access network optimization contrasting fragmented competition in subscriber-facing conversational AI. The vendor base separates into three archetypes: infrastructure incumbents with integrated hardware-software stacks, cloud hyperscalers leveraging elastic compute scale, and specialized chip designers targeting edge inference latency thresholds. Dominant competitive moves include strategic partnerships between carriers and algorithm developers, plus geographic expansion through localized compliance certification.
Within the infrastructure incumbent tier, Nokia and Ericsson occupy positions defined by research lineage and carrier relationships respectively. Huawei sits within a manufacturing-scale archetype despite geopolitically constrained addressable markets. Cloud-native competition concentrates among Amazon Web Services, Microsoft, and Google, each exemplifying platform-scale deployment of ML inference infrastructure.
| Leading Market Players |
|---|
| Nokia |
| Ericsson |
| Huawei |
| Cisco Systems |
| IBM |
| Amazon Web Services |
| Microsoft |
| ZTE Corporation |
| Others |
Cost & Logistics Intelligence
GPU memory module spot prices cascade through ML communication equipment tiers, compressing margins at the edge inference layer while inflating premium-tier SaaS subscriptions for cloud-native network optimization platforms. Taiwan foundry capacity constraints transmit upstream into European carrier procurement budgets, forcing algorithmic transparency investments under EU AI Act mandates to compete for capital against hardware refresh cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs ML communication platforms, with premium tiers capturing carriers requiring sub-50 millisecond latency guarantees and ISO 27001-certified data handling. Price differentiation rests on inference latency thresholds and GDPR-compliant federated learning architectures, with German automotive manufacturers least sensitive to cost and Indian PLI-scheme beneficiaries most price-conscious. Cost compression in standard-tier edge chip procurement is intensifying because NVIDIA H100 supply rationing favors hyperscaler direct allocations over carrier distribution channels.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing for ML chip packaging serving South Asian carrier markets, pulling assembly investments from traditional Malaysia and Vietnam hubs. Advanced semiconductor manufacturing concentrates in Taiwan and South Korea, while edge AI chip design feeds from ARM architectural licenses and RISC-V open-source cores. Single-source vulnerability in TSMC 3nm node access threatens carrier deployment timelines. Distribution runs through carrier procurement consortiums in Germany and Japan, bypassing traditional IT channel partners for direct equipment vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play: EU AI Act compliance costs in Germany and France run triple India's PLI-scheme subsidized certification pathways, creating margin expansion for vendors with dual-quality-management systems.
For Market Incumbents: Acquire radio frequency engineering talent pools in Nagoya and Stuttgart to defend against cloud hyperscaler poaching of wireless propagation expertise. Anchor defensive positioning through backward integration into edge AI chip design, captive-supplying inference accelerators for factory-floor predictive maintenance contracts. Pre-certify quality management systems under MDR frameworks to compress EU AI Act validation timelines for automated base station load balancing tools. For New Entrants and Emerging Players: Cloud hyperscaler marketplace listings offer the fastest channel to carrier technology evaluation committees, bypassing legacy OSS/BSS integration barriers that stall direct sales cycles. White-space concentration sits in healthcare telemedicine federated learning platforms, where HIPAA constraints limit incumbent training data advantages. Target Indian regional-language NLP pipelines for TRAI-mandated data localization compliance, using Bangalore development partnerships as beachhead infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized edge inference chip designers holding sub-50 millisecond latency IP for industrial IoT radio access nodes. Long-term viability over the next decade hinges on spectrum allocation policy convergence with generative AI computational requirements. Watch for FCC net neutrality enforcement actions against traffic-prioritization algorithms as inflection signal for cloud-native vendor valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Bell Labs-derived radio access optimization IP anchors algorithmic differentiation against Ericsson's predictive maintenance portfolio. |
| Strategic Partnership | Carrier consortiums in Germany negotiate direct edge computing procurement, bypassing traditional IT distribution markups. |
| Platform Integration | API-native ML platforms displace legacy OSS/BSS stacks, accelerating deployment timelines for cloud-native network optimization. |
| Geographic Expansion | EU AI Act pre-certification in France and Germany creates procurement preference against vendors lacking MDR quality frameworks. |
| Product Launch | Real-time generative AI voice synthesis for enterprise unified communications captures underexploited margin pools in North America. |
Research Approach
Bottom-up carrier deployment modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with radio access network planners, carrier procurement directors, edge AI chip architects, and EU AI Act compliance officers combined with secondary validation from FCC net neutrality filings, ETSI standards documentation, TRAI spectrum allocation records, and MIIT GB standard publications. Cross-referencing carrier capex disclosures against foundry capacity reports enables triangulation of hardware-software revenue splits.
Historical trendline analysis of ML communication platform adoption across cloud, edge, and on-premises configurations anchors the projection framework. Segmentation dimensions span deployment model, latency threshold tier, end-use vertical, and regional regulatory cluster. CAGRs derive from carrier technology refresh cycles, spectrum auction timelines, and industrial IoT penetration curves. Model inputs incorporate GPU supply rationing impacts on edge inference pricing and GDPR enforcement intensity variations across European national regulators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export control expansion on Chinese equipment vendors and generative AI computational requirements outstripping edge hardware capabilities. Forecasts reflect documented assumptions regarding carrier cloud migration pace and federated learning architecture adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Global Cognitive Data Management Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Cloud Machine Learning Market