
 Global Machine Learning in Manufacturing Market | 2026-2036
Global Machine Learning in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Machine Learning in Manufacturing Market Foresight
ISO/IEC 23053 for AI system trustworthiness is rotating vendor eligibility across industrial ML procurement cycles. NVIDIA Corporation leverages GPU-accelerated inference architectures to dominate real-time defect detection pipelines. Siemens anchors its position through deep integration with OPC UA-based shop floor connectivity. IBM Corporation competes via Watson-based predictive maintenance suites tailored for pharmaceutical assemblers.
Machine learning in manufacturing encompasses supervised and unsupervised algorithms deployed for pattern recognition in sensor telemetry, typically processing vibration spectra, thermal imaging, and dimensional tolerances at sub-millisecond latency for automated decision-making. Predictive maintenance commands the largest solution-type revenue pool due to measurable downtime reduction, while edge computing deployment is displacing cloud-only architectures where latency constraints govern. Quality control applications attract premium pricing in aerospace fabricators because traceability requirements exceed standard consumer goods thresholds.
FDA software-as-medical-device guidelines, EU AI Act conformity assessments, and China's GB standards for intelligent manufacturing collectively elevate compliance costs for cross-border solution providers. The EU Green Deal's embedded carbon tracking mandates are forcing energy management modules into baseline ML offerings. Stakeholders must monitor divergence between FDA's risk-based AI framework and EMA's evolving algorithmic validation expectations when architecting multi-jurisdictional deployment roadmaps.
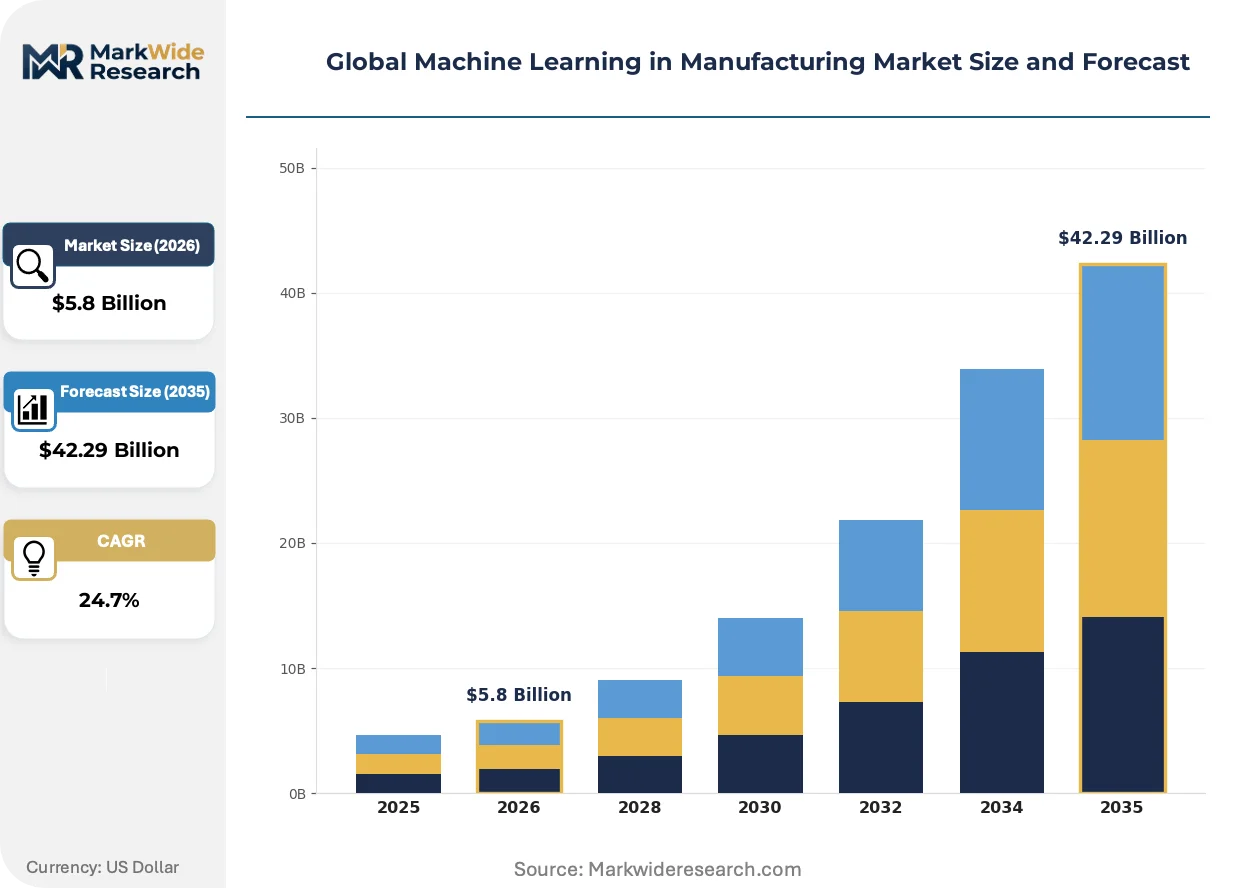
Market Dynamics
Edge-native inference architectures are compressing decision latency below 10 milliseconds, forcing a wholesale re-architecture of quality control pipelines away from centralized cloud processing.
Growth Catalysts
- EU AI Act Conformity Pathways:The regulation's risk-tiered assessment framework is accelerating procurement standardization across German automotive OEMs and their tiered supplier networks.
- Vibration Telemetry Fusion:Multi-sensor spectral analysis combining accelerometer and acoustic emission data is unlocking predictive maintenance contracts in aerospace turbine servicing.
- Stuttgart-Munich Automation Corridor:Concentrated demand from precision tooling manufacturers is creating localized ecosystem effects for ML-enabled process optimization vendors.
Market Restraints
- GPU Supply Concentration:Taiwan-based foundry capacity constraints for high-throughput inference accelerators are extending lead times for real-time defect detection deployments.
- ISO/IEC 23053 Certification Costs:Third-party AI system trustworthiness audits are adding 18-24 month pre-qualification cycles to industrial procurement processes.
- Legacy OPC UA Migration Friction:Brownfield facilities with proprietary fieldbus architectures face protocol translation complexity when integrating ML-driven control loops.
Strategic Opportunities
- India's PLI Scheme for Manufacturing:Production-linked incentives for advanced cell chemistry and semiconductor packaging are creating greenfield ML deployment opportunities in Gujarat and Tamil Nadu.
- Digital Twin Convergence:Physics-informed neural networks combined with real-time sensor feeds are enabling closed-loop process optimization in pharmaceutical continuous manufacturing.
- EU Green Deal Embedded Carbon Tracking:Mandatory Scope 3 emissions disclosure is forcing energy management modules into baseline predictive maintenance offerings.
Industry Challenges
- Industrial Data Science Talent Scarcity:The intersection of domain metallurgy expertise and MLOps proficiency remains critically under-supplied across Midwest US manufacturing hubs.
- FDA-EMA Validation Divergence:Pharmaceutical assemblers face conflicting algorithmic retraining documentation requirements when deploying across US and European facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Machine Learning in Manufacturing Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $42.29 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Type: Predictive Maintenance, Quality Control, Supply Chain Optimization, Demand Forecasting, Process Automation Application: Defect Detection, Equipment Monitoring, Inventory Management, Production Scheduling, Energy Management End User Industry: Electronics Manufacturers, Aerospace Fabricators, Consumer Goods Producers, Pharmaceutical Assemblers, Food Processing Units |
| Companies Covered | NVIDIA Corporation, IBM Corporation, Siemens, Microsoft Corporation, Rockwell Automation, Intel Corporation, SAP SE, ABB, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Machine Learning in Manufacturing Market Shifts & Advancements
Federated learning architectures and on-device model compression are redistributing computational load across the manufacturing stack, collapsing the traditional cloud-edge hierarchy that governed industrial AI deployment.
Neuromorphic inference chips are displacing conventional GPU arrays in sub-millisecond quality inspection stations. Automotive stamping plants in Bavaria and South Carolina are piloting these event-driven processors for real-time surface defect classification. The technology is displacing legacy FPGA-based vision systems that required extensive hand-tuned feature engineering.
China's GB standards for intelligent manufacturing are mandating interoperability testing for AI-enabled process control systems. Domestic equipment vendors must demonstrate compliance with prescribed data interface specifications before qualifying for state procurement programs. Foreign solution providers are responding by establishing localized joint ventures with state-owned automation enterprises.
Performance-based contracting is replacing perpetual license models for predictive maintenance software. Aerospace maintenance, repair, and overhaul operators in Toulouse and Hamburg now specify uptime guarantees rather than feature checklists in vendor selection criteria. This shift concentrates vendor risk while compressing sales cycles for proven solution providers.
Global Machine Learning in Manufacturing Market Segmentation
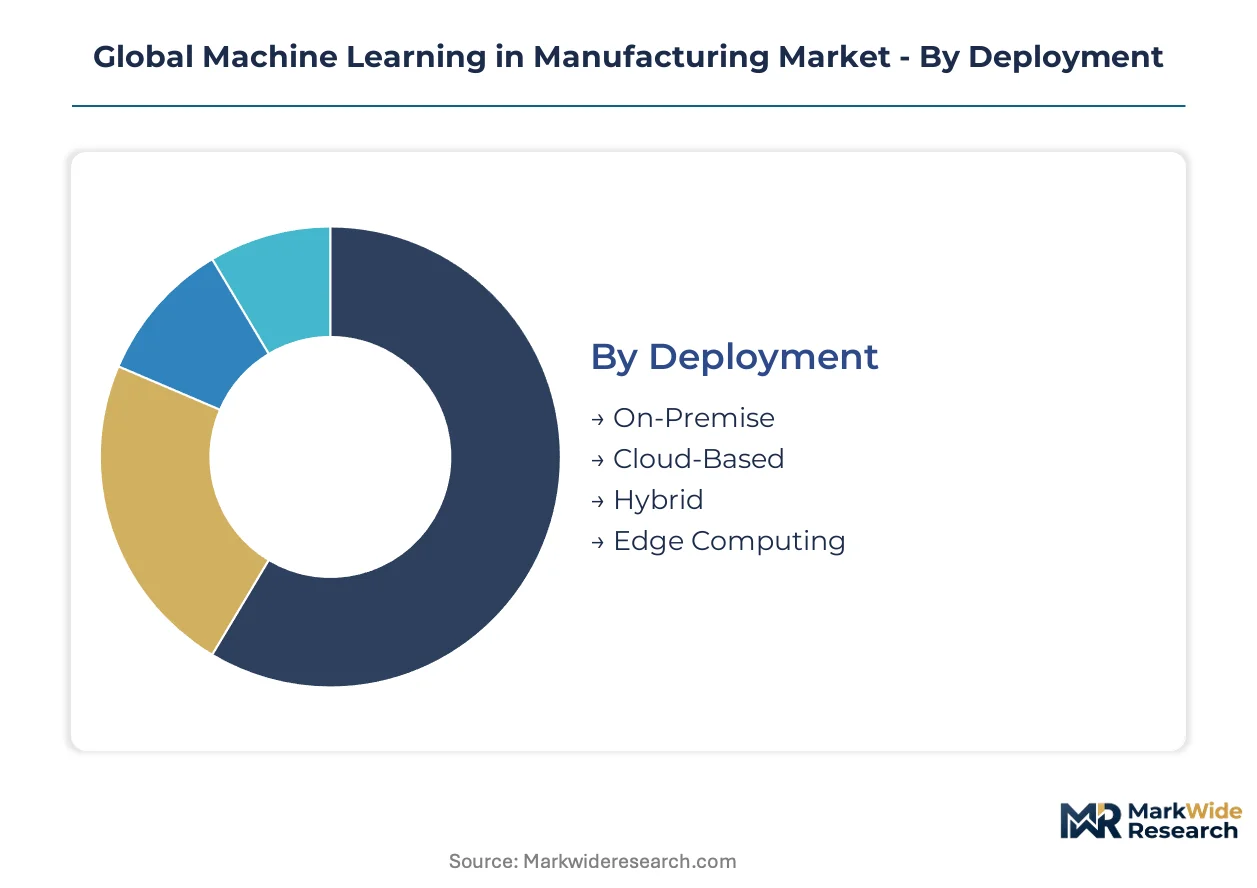
Deployment architecture determines latency thresholds and data sovereignty compliance for ML-driven manufacturing systems. Channel mix varies sharply across edge-native versus cloud-hybrid configurations, with procurement cycles and vendor qualification requirements diverging accordingly.
Deployment:
Channel mix splits between direct enterprise sales for on-premise installations and managed service providers for cloud-based subscriptions, with hybrid deployments flowing through systems integrators.
- Edge Computing:Sub-10 millisecond inference latency enables real-time defect classification in automotive stamping lines. Stuttgart-Munich corridor precision tooling manufacturers are standardizing on edge-native architectures to satisfy EU AI Act data localization requirements.
- Hybrid:Distributed training pipelines combine cloud-scale model development with edge inference execution. Pharmaceutical assemblers in Basel and Boston favor this architecture to balance FDA validation documentation needs with shop-floor responsiveness.
- On-Premise:Air-gapped installations serve defense contractors and nuclear component fabricators with strict operational technology isolation mandates.
- Cloud-Based:SaaS delivery dominates demand forecasting modules for consumer goods producers with distributed supplier networks.
On-Premise dominates installed base. Edge Computing is where expansion concentrates.
Solution Type:
Cost tier stratification places predictive maintenance at premium pricing due to measurable downtime ROI, while process automation competes on volume-driven license economics.
- Predictive Maintenance:Vibration telemetry fusion algorithms process accelerometer and acoustic emission spectra to forecast bearing failures. Aerospace turbine servicing operations in Toulouse and Hamburg specify uptime guarantees rather than feature checklists in procurement contracts.
- Quality Control:Surface defect classification using neuromorphic inference chips displaces legacy FPGA vision systems. Bavarian automotive stamping plants pilot event-driven processors for real-time anomaly detection with 90% reduction in feature engineering overhead.
- Process Automation:Closed-loop control systems integrate with OPC UA shop floor networks for continuous manufacturing optimization.
- Supply Chain Optimization:Demand sensing algorithms aggregate distributor point-of-sale data for electronics manufacturers managing semiconductor shortage volatility.
- Demand Forecasting:Statistical models consuming weather and macroeconomic indicators support seasonal production planning for food processing units.
Predictive Maintenance commands the largest revenue pool. Quality Control attracts the steepest expansion trajectory.
Application:
Volume concentration tracks capital intensity, with defect detection and equipment monitoring absorbing the majority of sensor infrastructure investment.
- Defect Detection:Thermal imaging and dimensional tolerance analysis operate at sub-millisecond latency for automated rejection decisions. China's GB standards mandate interoperability testing for AI-enabled vision systems qualifying for state procurement.
- Equipment Monitoring:Multi-sensor spectral analysis combines motor current signature analysis with ultrasonic testing. India's PLI scheme for advanced cell chemistry manufacturing is creating greenfield deployment opportunities in Gujarat and Tamil Nadu.
- Energy Management:EU Green Deal embedded carbon tracking mandates force Scope 3 emissions disclosure modules into baseline offerings.
- Production Scheduling:Physics-informed neural networks optimize batch sequencing in pharmaceutical continuous manufacturing.
- Inventory Management:Automated replenishment algorithms reduce safety stock holdings for consumer goods distributors.
Equipment Monitoring dominates installed base. Defect Detection is where expansion concentrates.
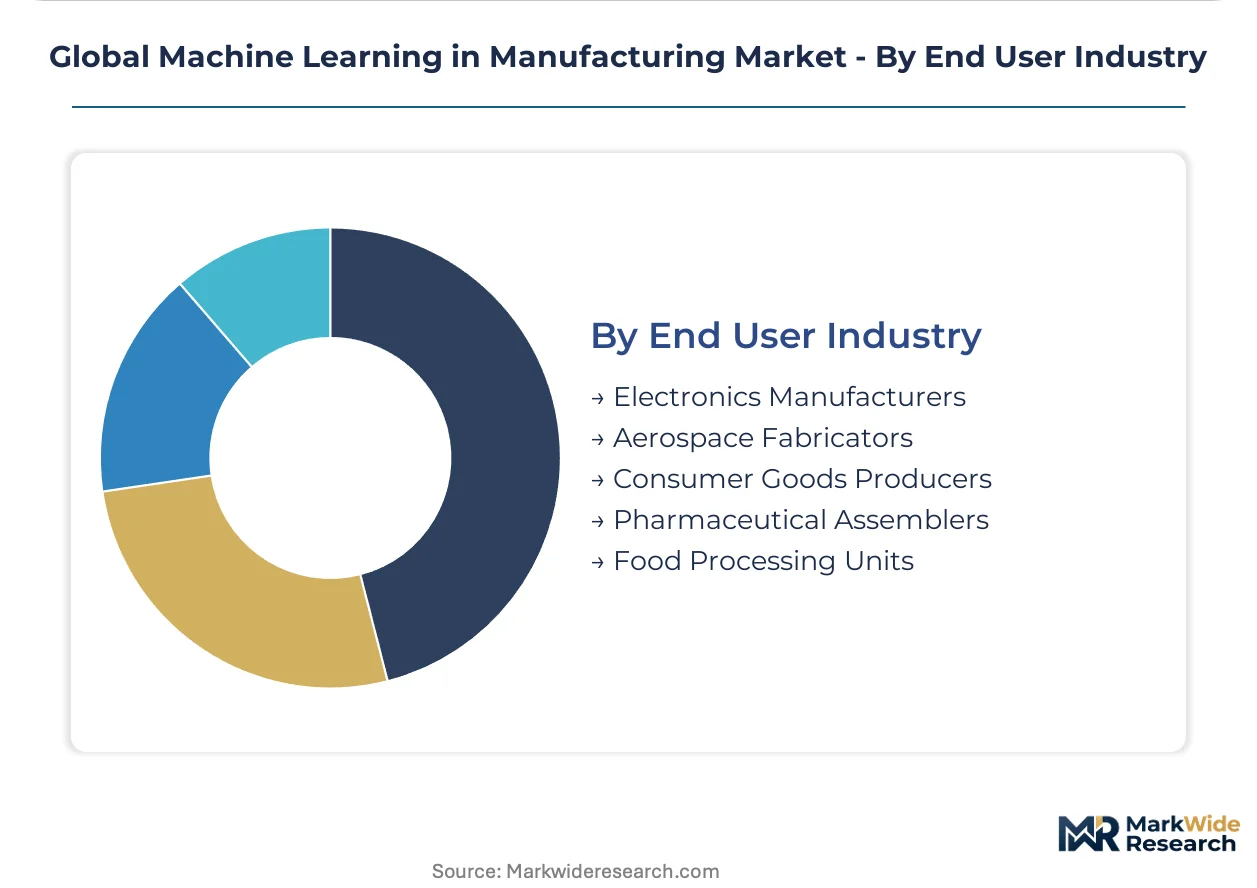
End User Industry:
Customer type segmentation reflects regulatory burden divergence, with pharmaceutical and aerospace buyers demanding ISO/IEC 23053 trustworthiness certification.
- Aerospace Fabricators:Traceability requirements exceed consumer goods thresholds, attracting premium pricing for quality control modules with full digital thread documentation. Maintenance, repair, and overhaul operators specify performance-based contracting with uptime penalties.
- Pharmaceutical Assemblers:FDA software-as-medical-device pathways and EMA algorithmic validation expectations create conflicting retraining documentation requirements for multi-jurisdictional deployments.
- Electronics Manufacturers:Semiconductor packaging lines in South Korea and Taiwan deploy real-time defect detection to manage yield loss from advanced node processes.
- Consumer Goods Producers:High-volume packaging operations prioritize throughput optimization over traceability depth.
- Food Processing Units:USDA and EFSA compliance drives hygiene monitoring applications with washdown-rated sensor hardware.
Aerospace Fabricators dominate premium pricing tiers. Pharmaceutical Assemblers is where regulatory-compliant solution expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes cluster around automotive OEMs seeking predictive maintenance, pharmaceutical assemblers navigating FDA-EMA validation divergence, and aerospace fabricators demanding traceability premiums. German precision tooling manufacturers and US Midwest industrial hubs anchor procurement volume. China's GB standards and India's PLI scheme are redrawing vendor qualification maps.
United States
Pharmaceutical assemblers in Boston and Research Triangle Park drive FDA software-as-medical-device pathway compliance for algorithmic process control. The IRA's domestic manufacturing incentives accelerate greenfield ML deployment in semiconductor packaging. Midwest manufacturing hubs spanning Michigan and Ohio face acute industrial data science talent scarcity at the metallurgy-MLOps intersection.
Germany
Automotive OEMs along the Stuttgart-Munich corridor standardize procurement on EU AI Act conformity assessments for risk-tiered algorithmic systems. KBA vehicle safety regulations intersect with ISO/IEC 23053 trustworthiness certification for industrial AI procurement. Bavarian automotive stamping plants pilot neuromorphic inference chips for sub-millisecond surface defect classification.
China
Domestic equipment vendors face GB standards mandating interoperability testing for AI-enabled process control systems qualifying for state procurement. MIIT intelligent manufacturing directives force localized joint venture structures upon foreign solution providers. Yangtze River Delta electronics manufacturers deploy real-time defect detection to manage advanced node yield loss.
India
Production-linked incentives for advanced cell chemistry and semiconductor packaging create greenfield ML deployment opportunities in Gujarat and Tamil Nadu. BIS standards for intelligent manufacturing systems elevate compliance requirements for cross-border equipment vendors. Tamil Nadu's automotive component clusters absorb edge-native predictive maintenance architectures for supplier network integration.
South Korea
Semiconductor packaging lines deploy real-time defect detection systems managing volatility in advanced node manufacturing processes. MFDS pharmaceutical manufacturing guidelines create parallel validation requirements for algorithmic process control in biologics production. Busan-Ulsan industrial complexes concentrate demand for vibration telemetry fusion in precision tooling operations.
Global Machine Learning in Manufacturing Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with embedded software divisions, cloud-native AI platforms seeking manufacturing verticalization, and specialized automation vendors with OPC UA integration depth. Three archetypes dominate: GPU-accelerated inference specialists, predictive maintenance suite providers, and shop-floor connectivity incumbents. Competitive moves center on strategic partnerships for edge-native architectures and portfolio diversification into physics-informed neural networks.
Among diversified technology conglomerates, NVIDIA Corporation and IBM Corporation exemplify contrasting verticalization strategies, while Siemens anchors the industrial automation incumbent tier. Microsoft Corporation occupies a position bridging cloud-scale model development with manufacturing-specific deployment tooling. Intel Corporation represents the semiconductor vendor archetype seeking to capture value from neuromorphic inference displacement of conventional GPU arrays. SAP SE sits within the enterprise software tier extending ERP data models into predictive maintenance workflows.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| IBM Corporation |
| Siemens |
| Microsoft Corporation |
| Rockwell Automation |
| Intel Corporation |
| SAP SE |
| ABB |
| Others |
Supply & Pricing Matrix
GPU foundry capacity utilization above 85 percent in Taiwan concentrates inference accelerator supply, compressing margins for edge-native ML deployment vendors while elevating price floors for real-time defect detection systems. This scale dynamic forces tiered procurement structures across German automotive OEMs and their supplier networks, where ISO/IEC 23053 certification tiers separate premium predictive maintenance contracts from economy-grade process automation licenses.
Pricing Analysis
Cost-plus contracts indexed to NVIDIA GPU spot pricing dominate predictive maintenance procurement in aerospace turbine servicing. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 23053-certified trustworthiness audits from uncertified software-only offerings. Price differentiation rests on OPC UA integration depth and vibration telemetry fusion algorithm performance. Cost compression in economy-tier process automation intensifies as Indian PLI scheme beneficiaries absorb volume-driven license economics. Consumer goods producers exhibit highest price sensitivity; pharmaceutical assemblers navigating FDA-EMA validation divergence accept premium positioning for documented retraining traceability.
Supply Chain Analysis
Taiwan Strait transit risk concentrates high-throughput inference accelerator supply, exposing real-time defect detection deployments to geopolitical disruption. GPU silicon fabrication centers on Taiwan and South Korea; neuromorphic inference chip prototyping localizes in Germany and the United States. Raw material dependencies span advanced node semiconductor wafers, rare earth elements for sensor telemetry hardware, and cobalt-bearing alloys for vibration monitoring equipment. Single-source vulnerability pervades Taiwan-based foundry relationships. Distribution runs through Siemens and Rockwell Automation channel partners for on-premise installations, cloud hyperscaler marketplaces for SaaS subscriptions, and systems integrators for hybrid architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where ISO/IEC 23053 certification entrenchment creates switching costs that lock pharmaceutical assemblers and aerospace fabricators into incumbent predictive maintenance ecosystems.
For Market Incumbents: Compound certification moats by embedding EU AI Act conformity assessments into baseline offerings before emerging cloud-native AI platforms achieve verticalization depth. Add captive GPU allocation capacity through foundry partnership structures in Taiwan and South Korea. Prioritize physics-informed neural network R&D to defend against neuromorphic inference chip displacement in sub-millisecond quality inspection stations. For New Entrants and Emerging Players: ISO/IEC 23053 fast-track certification partnerships with German TÜV bodies unlock aerospace MRO procurement channels in Toulouse and Hamburg currently constrained to incumbent predictive maintenance suites. Target India's PLI scheme greenfield deployments in Gujarat semiconductor packaging where brownfield OPC UA migration friction excludes established automation vendors. Lead with federated learning architectures that collapse cloud-edge hierarchy without legacy infrastructure overhaul. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-native inference specialists with neuromorphic chip pilot relationships over cloud-scale model development platforms facing manufacturing verticalization challenges. Long-term viability hinges on regulatory compliance automation capabilities spanning FDA software-as-medical-device pathways and EU AI Act risk-tiered assessments. Acquisition targets should demonstrate closed-loop pharmaceutical continuous manufacturing deployments with physics-informed neural network integration. Watch for GPU supply concentration easing as alternative foundry capacity in the United States and Japan crosses commercial viability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Neuromorphic Chip Partnership | Bavarian automotive stamping plants pilot event-driven processors for 90 percent feature engineering reduction. |
| EU AI Act Conformity Automation | Stuttgart-Munich corridor OEM procurement standardization accelerates vendor qualification cycles. |
| Physics-Informed Neural Network Integration | Pharmaceutical assemblers in Basel enable closed-loop process optimization for continuous manufacturing. |
| India PLI Scheme Localization | Gujarat and Tamil Nadu greenfield deployments absorb edge-native architectures without legacy migration burden. |
| ISO/IEC 23053 Certification Pre-Investment | Aerospace fabricators specify trustworthiness audits as table stakes for maintenance contract eligibility. |
Research Methodology
Operator-level perspectives from predictive maintenance directors, OPC UA integration specialists, pharmaceutical process validation leads, aerospace MRO procurement managers, and edge computing infrastructure architects anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA software-as-medical-device guidance documents, EU AI Act implementing acts, China's GB standards for intelligent manufacturing, SEC 10-K filings from industrial automation conglomerates, and customs data tracking GPU accelerator import flows. Bottom-up deployment architecture modeling triangulated against top-down solution-type revenue allocation across the analysis window.
Sensitivity analysis tested forecast robustness across edge computing penetration scenarios, GPU supply elasticity assumptions, and regulatory compliance cost trajectories. Segmentation dimensions spanned deployment architecture, solution type, application function, and end-user industry regulatory burden tier. CAGRs derived from polynomial trend fitting of historical adoption curves adjusted for technology substitution effects. Industry-specific inputs included vibration telemetry fusion algorithm performance benchmarks, neuromorphic inference chip power-efficiency trajectories, and EU Green Deal embedded carbon tracking mandate implementation timelines.
Decision-makers should treat outputs as directional under sustained GPU supply concentration and stable EU AI Act enforcement intensity; material deviation would warrant model refresh. Forecasts assume continued FDA-EMA validation divergence without harmonization protocol emergence. Revision becomes warranted when neuromorphic inference chip commercialization crosses cost-parity thresholds with conventional GPU arrays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Data Science Platform Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Natural Language Processing Market