
 AI and Advance Machine Learning in BFSI Market | 2026-2036
AI and Advance Machine Learning in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
AI and Advance Machine Learning in BFSI Market Analysis
Mid-sized retail banks is bifurcating away from large universal banks as the primary growth vector for AI procurement in BFSI. Microsoft Corporation leverages its Azure cloud infrastructure to anchor enterprise-grade machine learning deployments across North American banking networks. International Business Machines Corporation sustains competitive relevance through Watson's specialization in regulatory-compliant natural language processing for risk documentation. Amazon Web Services Inc. dominates cloud-based training environments that reduce inference latency for payment fraud detection pipelines.
AI and advance machine learning in BFSI encompasses algorithmic systems that process structured and unstructured financial data through neural architectures, reinforcement learning loops, and transformer-based natural language models to automate decision-making, pattern recognition, and predictive analytics across banking, insurance, and capital markets operations. The technology stack spans deep learning frameworks for anti-money laundering surveillance, natural language processing engines for customer service automation, and reinforcement learning models for algorithmic trading optimization. Fraud detection applications currently capture the largest deployment share as real-time transaction monitoring becomes mandatory, while customer service automation through conversational AI represents the fastest-expanding application segment as labor cost pressures mount. Cloud-based deployment leads in new installations due to elastic compute requirements for model training, though hybrid architectures retain strong traction among institutions managing sovereign data constraints.
The EU AI Act classifies credit-scoring and insurance pricing algorithms as high-risk systems, mandating human oversight and audit trails that reshape procurement specifications across European BFSI procurement. The SEC in the United States and the FCA in the United Kingdom have both issued guidance on algorithmic trading governance and model risk management, creating compliance layers that favor established vendors with documented validation frameworks. Stakeholders must monitor how divergent regulatory timelines between jurisdictions affect cross-border deployment strategies and whether explainability requirements fragment the addressable market for black-box deep learning solutions.
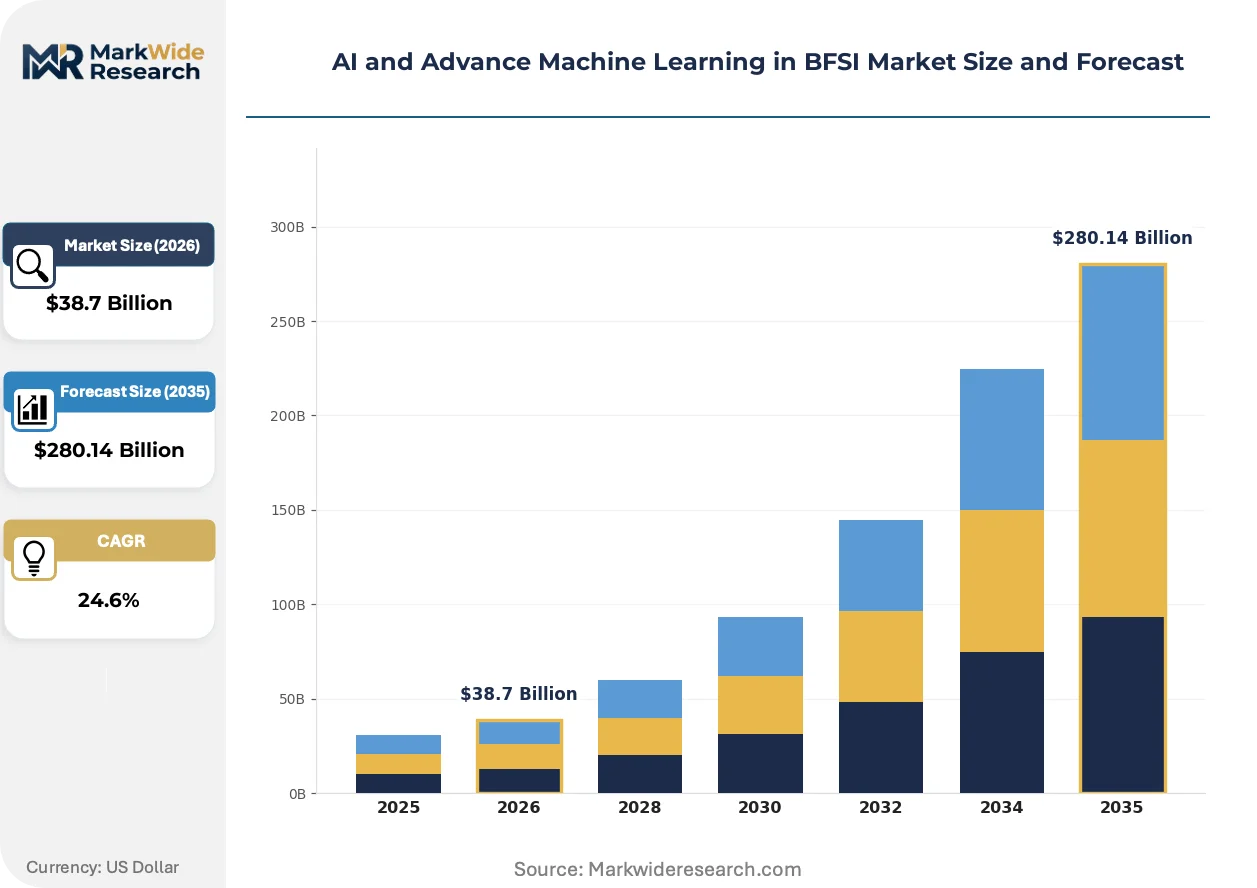
Market Dynamics
Explainability mandates from the EU AI Act and similar governance frameworks are forcing wholesale redesign of procurement specifications across retail banking and insurance, compressing deployment timelines for black-box neural architectures while elevating vendors with documented validation protocols.
Growth Catalysts
- EU AI Act high-risk classification:Credit-scoring and insurance pricing algorithms now require human oversight and audit trails, accelerating replacement cycles for non-compliant legacy systems across European retail banks.
- Real-time fraud detection infrastructure:Neural network deployment for transaction monitoring has become mandatory as payment velocity increases and synthetic identity fraud proliferates in digital banking channels.
- Cloud elasticity for model training:Elastic compute requirements for large language model fine-tuning are pulling tier-one investment firms toward cloud-based deployment architectures that reduce capital intensity.
Market Restraints
- Specialized talent scarcity:Deep expertise in regulatory-compliant machine learning engineering concentrates in Silicon Valley and London financial technology clusters, constraining deployment velocity elsewhere.
- Sovereign data constraints:Hybrid architecture requirements among institutions managing cross-border data residency rules fragment infrastructure standardization and elevate integration costs.
- Validation framework immaturity:Absence of standardized model risk management protocols outside established jurisdictions creates procurement friction for emerging market banks.
Strategic Opportunities
- Mid-sized retail bank automation:Regional banks in Germany, France, and the United States represent underpenetrated demand for conversational AI and customer service automation as labor cost pressures mount.
- Reinforcement learning convergence:Integration of reinforcement learning loops with transformer-based natural language models enables algorithmic trading optimization previously requiring separate infrastructure stacks.
- Explainable AI regulatory tailwind:Procurement specifications increasingly mandate interpretability features that favor vendors with established documentation frameworks, creating competitive moats.
Industry Challenges
- Model risk management skill gaps:Institutions struggle to hire validation engineers capable of documenting algorithmic decision pathways for regulatory examination, particularly for deep learning systems.
- Legacy core banking integration:Neural network deployment requires API layer construction atop decades-old mainframe architectures, extending implementation timelines and elevating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI and Advance Machine Learning in BFSI Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Deep Learning, Neural Networks, Natural Language Processing, Reinforcement Learning Application: Fraud Detection, Risk Assessment, Customer Service Automation, Personal Finance Management Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Retail Banks, Investment Firms, Insurance Companies, Payment Processors |
| Companies Covered | Amazon Web Services Inc., International Business Machines Corporation, Microsoft Corporation, SAP SE, Fair Isaac Corporation, Cisco Systems, Inc., Hewlett Packard Enterprise Development LP, SAS Institute Inc., Accenture PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI and Advance Machine Learning in BFSI Market Emerging Trajectories
Transformer-based architectures are actively restructuring competitive positioning across fraud detection and customer service automation, compressing incumbent advantages in natural language processing while opening white space for specialized reinforcement learning applications in capital markets.
Graph neural networks for anti-money laundering surveillance is supplanting rule-based transaction monitoring systems in tier-one investment firms. Deutsche Bank and JPMorgan Chase have accelerated deployment timelines from pilot to production within eighteen months. This technology is enabling pattern detection across multi-hop financial relationships that rule engines cannot capture, compressing false positive rates while expanding suspicious activity identification scope.
The EU AI Act's high-risk system classification for credit-scoring algorithms mandates human-in-the-loop oversight and comprehensive audit trail documentation. European retail banks must now renegotiate vendor contracts to incorporate explainability features and model lineage tracking. French and German institutions are responding by consolidating procurement around established vendors with pre-validated compliance frameworks, fragmenting addressable market access for emerging solution providers.
Outcome-based contracting for fraud detection performance is displacing traditional seat-license pricing among North American payment processors. Tier-two banks now demand guaranteed false positive rate thresholds and shared savings arrangements tied to fraud loss reduction. This shift is most visible in the United States, where cloud-native challengers are capturing mid-market share by accepting performance risk that incumbent vendors refuse.
AI and Advance Machine Learning in BFSI Market Segmentation
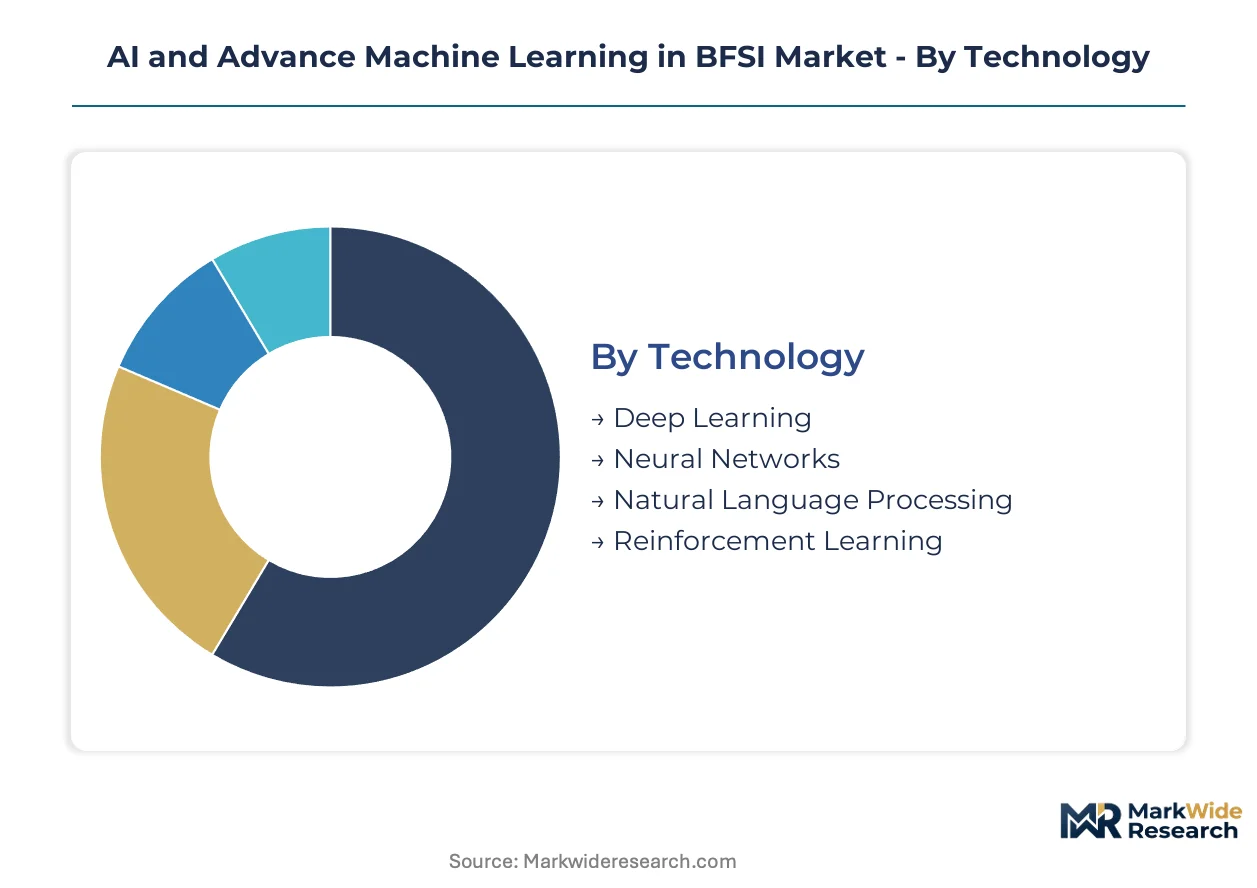
Segmentation reveals how procurement specifications diverge across technology maturity levels and regulatory exposure tiers in BFSI. Institutions select architectures based on explainability mandates, latency requirements, and core banking integration complexity rather than capability alone.
Technology:
Substitution pressure concentrates in rule-based systems and legacy statistical models as neural architectures achieve production-grade reliability in regulated environments.
- Deep Learning:Multi-layer neural architectures process unstructured financial data including document images and voice biometrics. Tier-one investment firms in the United States deploy these systems for algorithmic pattern recognition where latency tolerances permit cloud-based inference.
- Natural Language Processing:Transformer-based models automate contract analysis, regulatory filing extraction, and customer service interaction classification. European retail banks under EU AI Act compliance timelines concentrate procurement here for audit trail generation in credit-scoring workflows.
- Neural Networks:Feedforward and recurrent architectures power real-time transaction scoring engines.
- Reinforcement Learning:Agent-based systems optimize execution strategies in algorithmic trading environments.
Deep Learning anchors the volume base while Natural Language Processing gains share at the steepest rate.
Application:
Cost tier differentiation separates mandatory compliance deployments from discretionary automation investments across banking and insurance verticals.
- Fraud Detection:Real-time transaction monitoring systems deploy neural networks to flag synthetic identity fraud and authorized push payment scams. Payment processors in the United States mandate sub-100 millisecond inference latency, driving edge computing co-location strategies.
- Customer Service Automation:Conversational AI platforms handle account inquiries, payment disputes, and product recommendations through large language model fine-tuning. Mid-sized retail banks in Germany and France expand deployment fastest as labor cost pressures mount and branch networks contract.
- Risk Assessment:Credit-scoring and insurance pricing models face heightened regulatory scrutiny under EU AI Act high-risk classifications.
- Personal Finance Management:Predictive analytics engines deliver spending insights and savings recommendations to retail banking customers.
Fraud Detection captures the largest deployment share while Customer Service Automation expands most quickly.
Deployment:
Volume concentration follows elastic compute requirements for model training, with sovereign data constraints fragmenting architecture standardization.
- Cloud-Based:Elastic GPU clusters support large language model fine-tuning and batch inference at reduced capital intensity. Tier-one investment firms in the United States have standardized on multi-cloud strategies to avoid vendor lock-in.
- Hybrid:Split architectures keep sensitive training data on-premises while leveraging cloud inference for non-critical workloads. Institutions managing cross-border data residency rules in Europe and Asia-Pacific favor this model despite elevated integration costs.
- On-Premises:Air-gapped environments serve national security-sensitive financial institutions and central bank operations.
- Edge Computing:Sub-50 millisecond latency requirements for real-time payment authorization drive point-of-presence deployments.
Cloud-Based deployment leads new installations while Hybrid architectures retain strongest traction among institutions with sovereign data constraints.
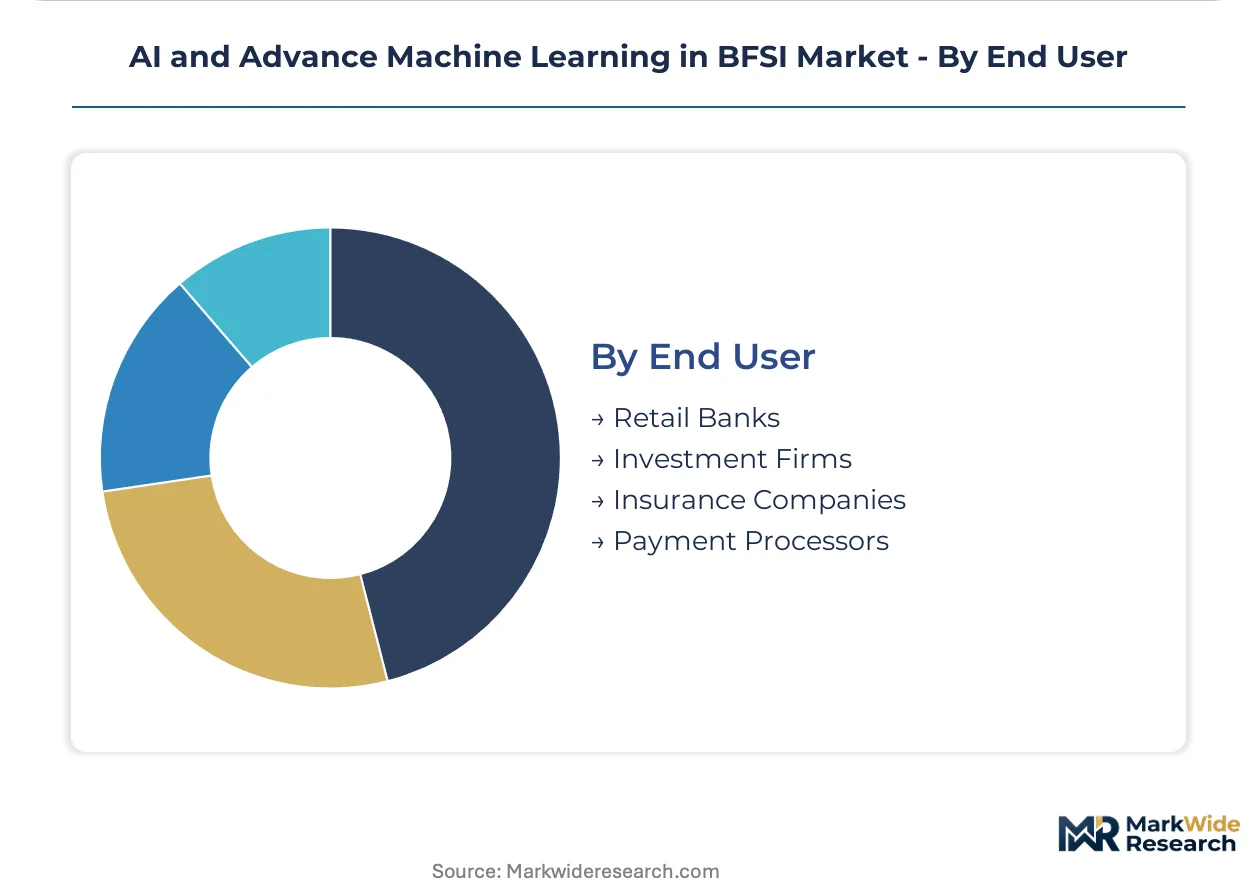
End User:
Customer type maturity separates early adopters with dedicated AI engineering teams from laggards dependent on vendor-managed solutions.
- Retail Banks:Universal and regional institutions deploy conversational AI, fraud detection, and credit-scoring automation at scale. Mid-sized banks in the United States, Germany, and France represent the fastest-expanding procurement segment as legacy modernization accelerates.
- Investment Firms:Hedge funds and asset managers apply reinforcement learning to execution optimization and natural language processing to sentiment analysis. Cloud-native deployment dominates as capital intensity constraints favor operational expenditure models.
- Insurance Companies:Pricing algorithms and claims automation face EU AI Act high-risk classification, mandating human oversight infrastructure.
- Payment Processors:Real-time transaction monitoring requirements drive specialized fraud detection procurement with guaranteed false positive rate thresholds.
Retail Banks anchor the volume base while Investment Firms show the steepest technology adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology transfer flows from United States cloud infrastructure providers into European and Asian banking networks dominate cross-border procurement patterns. American hyperscalers export elastic compute platforms to tier-one investment firms in London, Frankfurt, and Singapore. Regulatory divergence between jurisdictions fragments deployment architectures and elevates integration costs for multinational institutions.
United States
Tier-one investment firms in Manhattan and Chicago drive cloud-native machine learning procurement for algorithmic trading optimization. SEC guidance on model risk management mandates documented validation frameworks that favor established vendors with pre-existing compliance protocols. The Boston-San Francisco technology corridor concentrates specialized talent for regulatory-compliant AI engineering.
Germany
Regional retail banks in Bavaria and Baden-Württemberg accelerate conversational AI deployment as branch networks contract and labor costs escalate. The EU AI Act high-risk classification for credit-scoring algorithms forces renegotiation of vendor contracts to incorporate human-in-the-loop oversight. Frankfurt's financial district anchors procurement consolidation around explainable AI systems with pre-validated audit trails.
United Kingdom
London-based hedge funds apply reinforcement learning to execution optimization in high-frequency trading environments. FCA guidance on algorithmic trading governance creates compliance layers that elevate procurement specifications for model lineage tracking. The City of London and Canary Wharf clusters concentrate cloud-based training infrastructure for natural language processing applications.
France
Mid-sized retail banks in Île-de-France expand fraud detection procurement to address synthetic identity proliferation in digital channels. The EU AI Act mandates comprehensive documentation for insurance pricing algorithms, compressing deployment timelines for non-compliant legacy systems. Parisian financial institutions consolidate vendor relationships around established providers with documented explainability frameworks.
Japan
Tokyo-based megabanks deploy graph neural networks for anti-money laundering surveillance to reduce false positive rates in transaction monitoring. METI initiatives on trustworthy AI create procurement preferences for interpretable model architectures. The Kanto region concentrates specialized engineering talent for hybrid cloud deployments managing sovereign data constraints.
AI and Advance Machine Learning in BFSI Market Vendor Landscape
Player mix skews toward cloud infrastructure hyperscalers with adjacent machine learning platforms, creating a tiered structure where specialized financial services vendors occupy niche compliance segments. The competitive landscape separates into three archetypes: hyperscale cloud providers with financial services verticals, established enterprise software vendors with regulatory documentation expertise, and emerging challengers accepting outcome-based performance risk. Dominant competitive moves include strategic partnerships between cloud platforms and core banking system integrators, plus portfolio diversification into explainable AI modules that satisfy EU AI Act mandates.
Within the hyperscale tier, Amazon Web Services Inc. and Microsoft Corporation anchor cloud-based deployment architectures across North American and European banking networks. International Business Machines Corporation occupies a distinct position representing the established enterprise archetype with specialized regulatory compliance capabilities. These three entities exemplify how vendor selection increasingly hinges on pre-validated documentation frameworks rather than raw algorithmic performance.
| Leading Market Players |
|---|
| Amazon Web Services Inc. |
| International Business Machines Corporation |
| Microsoft Corporation |
| SAP SE |
| Fair Isaac Corporation |
| Cisco Systems, Inc. |
| Hewlett Packard Enterprise Development LP |
| SAS Institute Inc. |
| Accenture PLC |
| Others |
Supply Flow & Price Mechanics
Ninety-day implementation timelines for explainable AI modules now govern procurement velocity across European retail banking, compressing vendor margins while concentrating pricing power among hyperscalers with pre-validated compliance frameworks. This lead-time compression feeds directly into supply chain restructuring as tier-one institutions bypass emerging challengers for established providers with documented EU AI Act audit trails.
Pricing Analysis
Next-generation transformer-based architectures command substantial premiums over legacy rule-based systems and first-generation neural networks in BFSI procurement. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native deployments with guaranteed SLAs from self-managed installations and open-source alternatives. Price differentiation hinges on regulatory certification tier—EU AI Act-compliant explainability features versus black-box deployments—and customization depth for core banking integration. Cost compression in mid-market conversational AI is intensifying because cloud-native challengers accept outcome-based performance contracts that incumbent vendors refuse. Regional retail banks in Germany and France exhibit highest price sensitivity due to constrained IT budgets, while tier-one investment firms in Manhattan show lowest sensitivity given algorithmic trading optimization returns.
Supply Chain Analysis
GPU cluster availability in Northern Virginia and Frankfurt data centers constrains deployment velocity for large language model fine-tuning across North American and European banking networks. Supply concentrates in the United States for cloud infrastructure, Taiwan for advanced semiconductor fabrication, and Ireland for EU data residency-compliant hosting facilities. The technology stack draws from NVIDIA A100/H100 accelerators, proprietary transformer weights, and API-layer middleware for legacy mainframe integration. Single-source vulnerability in high-performance GPU supply creates procurement risk for institutions scaling training infrastructure. Distribution runs through direct enterprise sales teams for tier-one accounts and channel partners for mid-market regional banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one investment firms and universal banks as procurement consolidation around explainable AI frameworks reduces vendor count. This consolidation elevates incumbent hyperscalers while fragmenting access for emerging specialists lacking pre-validated compliance documentation.
For Market Incumbents: Consolidate regulatory documentation capabilities through acquisition of specialized model risk management consultancies, defending against cloud-native challengers accepting outcome-based pricing. Deepen vertical integration into core banking API layers to extend implementation timelines and elevate switching costs for institutional clients. Prioritize certification investment in EU AI Act high-risk system validation to maintain procurement access across European retail banking networks. For New Entrants and Emerging Players: ISO 27001 and SOC 2 Type II fast-tracks enable credibility building among mid-sized retail banks skeptical of unproven vendors. White-space targets include conversational AI for regional banks in France and Germany, plus edge computing inference for payment processors demanding sub-50 millisecond latency. Go-to-market execution should emphasize outcome-based contracting with guaranteed false positive rate thresholds to differentiate from incumbent seat-license models. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EU AI Act mandates and SEC model risk management guidance create durable demand for documented validation frameworks. Acquisition targets should exhibit specialized expertise in explainable AI modules for credit-scoring workflows and established relationships with core banking system integrators. Monitor divergence in regulatory timelines between jurisdictions as the critical inflection signal for cross-border deployment strategy viability.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Module Development | EU AI Act high-risk classification mandates human oversight documentation for credit-scoring algorithms. |
| Core Banking API Integration Partnership | Neural network deployment requires middleware construction atop decades-old mainframe architectures. |
| Outcome-Based Performance Contracting | Payment processors now demand guaranteed false positive rate thresholds and shared savings arrangements. |
| Regulatory Compliance Certification Investment | Pre-validated audit trail frameworks create competitive moats under SEC and FCA guidance. |
| Edge Computing Inference Infrastructure | Sub-100 millisecond latency requirements for real-time fraud detection drive point-of-presence deployments. |
Methodological Framework
The analysis maps deep learning frameworks, natural language processing engines, reinforcement learning systems, and graph neural networks, each validated through primary interviews with chief data officers, model risk management leads, regulatory compliance officers, and cloud procurement directors at tier-one investment firms and regional retail banks. Secondary validation draws from SEC algorithmic trading guidance filings, EU AI Act regulatory texts, FCA model risk management consultation papers, and hyperscaler financial services vertical revenue disclosures. Bottom-up deployment estimates triangulate against top-down market sizing across technology, application, deployment, and end-user dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by technology generation, application criticality, deployment architecture complexity, and institutional maturity tier. CAGRs derive from elasticity modeling of cloud compute consumption patterns and regulatory-driven replacement cycle acceleration. Industry-specific forecast inputs include GPU cluster utilization rates and EU AI Act implementation timeline assumptions.
Decision-makers should treat outputs as directional under sustained regulatory enforcement of explainable AI mandates and stable cloud infrastructure pricing; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as divergence in jurisdictional regulatory timelines and GPU supply constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Europe Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Machine Learning Operation Technology Market