
 Integrated Workplace Management System (IWMS) Market | 2026-2036
Integrated Workplace Management System (IWMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Workplace Management System (IWMS) Market Foresight
North American software engineering capacity is pivoting toward cloud-native IWMS architectures. Eptura leverages extensive integration partnerships to anchor enterprise accounts across diversified real estate portfolios. IBM Maximo Real Estate and Facilities sustains technology leadership through deep asset lifecycle functionality embedded in broader enterprise ecosystems. AssetWorks dominates public sector and educational verticals where long-term maintenance planning requirements create durable contract structures.
An Integrated Workplace Management System constitutes an enterprise software platform that unifies space utilization tracking, preventive maintenance scheduling, lease obligation management, and capital project oversight through centralized data models and IoT sensor feeds. Its primary commercial purpose centers on reducing facility operating expenditures while ensuring regulatory compliance across distributed real estate holdings. Space Management generates the largest current revenue pool as hybrid work patterns force continuous reconfiguration of physical footprints. Cloud-Based deployment represents the fastest-expanding structural category as IT departments prioritize subscription economics over capital-intensive on-premises infrastructure. Maintenance Management commands elevated margin profiles where predictive analytics modules justify premium pricing tiers.
The EU Energy Performance of Buildings Directive and OSHA workplace safety standards in the United States impose auditable documentation requirements that IWMS platforms automate. ISO 41001 facility management standards further shape procurement criteria for multinational organizations evaluating vendor qualifications. Facility executives must weigh interoperability commitments against emerging AI-driven optimization capabilities when selecting platforms for decade-long implementation horizons.
Market Dynamics
Cloud-native architectures are compressing deployment timelines from months to weeks, forcing incumbent vendors to restructure subscription economics and API-first integration strategies around real-time IoT telemetry streams.
Growth Catalysts
- EU Energy Performance of Buildings Directive:Mandatory efficiency audits across commercial portfolios above 1,000 square meters require automated compliance documentation that IWMS platforms deliver.
- Healthcare Facilities:Operating room scheduling complexity and medical equipment maintenance protocols drive digitization of facility operations across hospital networks.
- Predictive Maintenance Modules:Machine learning algorithms analyzing vibration and thermal sensor data reduce unplanned downtime in manufacturing campuses and data centers.
Market Restraints
- Implementation Cost Structure:Multi-year professional services engagements for data migration and change management consume 40-60 percent of total contract value.
- Technical Debt Burden:Decades-old CAFM databases with inconsistent asset hierarchies obstruct clean migration to modern data models.
- Substitution Risk from Point Solutions:Specialized vendors in space booking, maintenance ticketing, or lease accounting capture discrete budgets before enterprise platform consolidation.
Strategic Opportunities
- Underpenetrated Indian Commercial Real Estate:Rapid office stock expansion in Bengaluru and Hyderabad lacks integrated facility management infrastructure.
- AI-IoT Convergence:Computer vision occupancy sensors combined with generative AI assistants enable autonomous space reconfiguration recommendations.
- Subscription Channel Innovation:Marketplace models allowing mid-market buyers to compose modular capabilities without enterprise procurement cycles.
Industry Challenges
- Integration Architect:Scarce talent capable of bridging BACnet, Modbus, and REST API protocols across heterogeneous building automation systems.
- ISO 41001 Certification Timelines:Eighteen-month assessment periods delay competitive qualification for multinational facility management contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Workplace Management System (IWMS) Market |
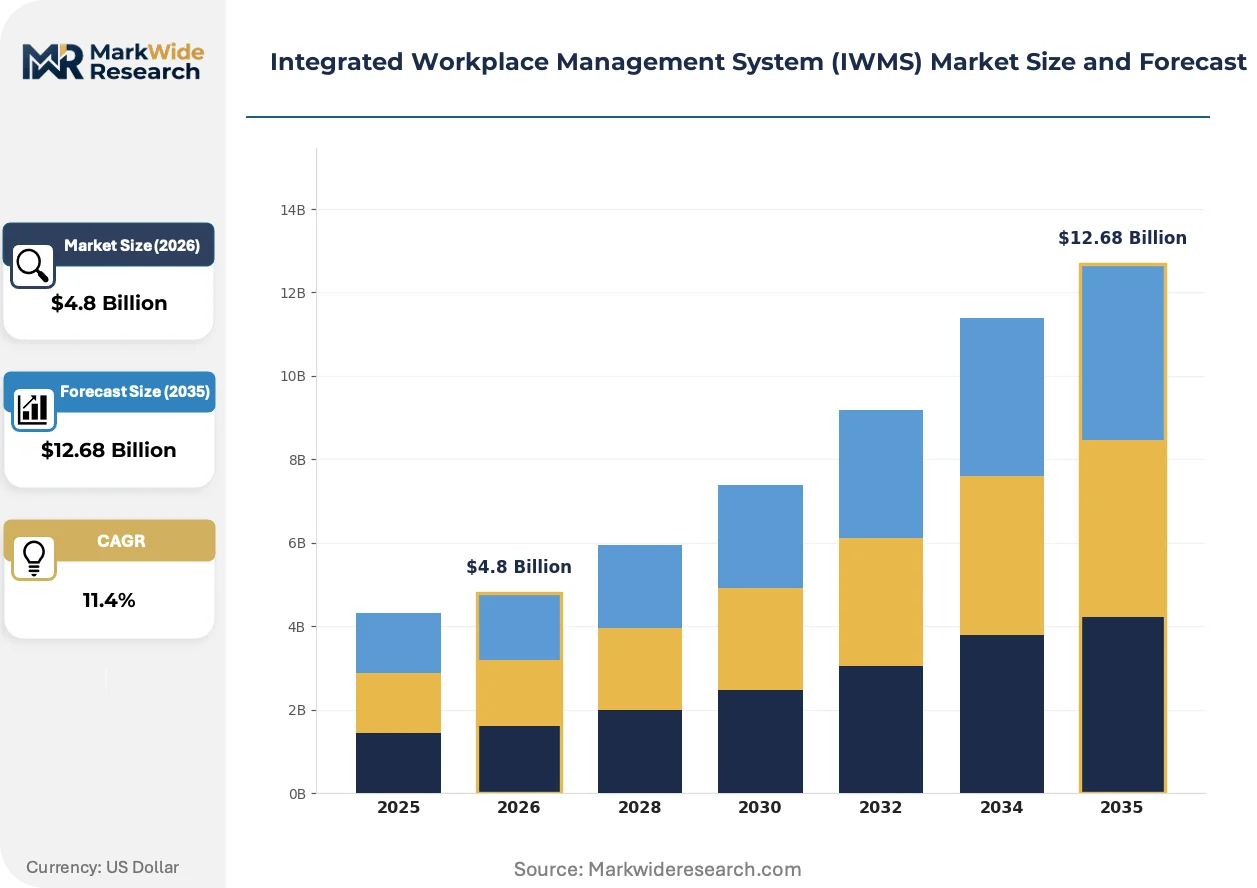
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Space Management, Maintenance Management, Lease Administration, Real Estate Management End User: Corporates, Educational Institutions, Healthcare Facilities, Government Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Service Type: Consulting, Integration, Optimization, Training |
| Companies Covered | AssetWorks, Archibus, IBM Maximo Real Estate and Facilities, iOffice, Baseworx, Eptura, Spaceti, SpaceIQ, FMS:Workplace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Workplace Management System (IWMS) Market Shifts & Advancements
Digital twin technology is collapsing the boundary between physical infrastructure and software representation, enabling real-time simulation of capital project outcomes before construction commitment.
Digital twin platforms are consolidating fragmented point solutions for space planning, asset visualization, and energy modeling into unified 3D environments. University campuses and airport authorities are deploying these systems fastest, driven by complex stakeholder coordination requirements. The technology is consolidating vendor competitive positions around data fidelity and rendering performance rather than standalone feature depth.
The EU Corporate Sustainability Reporting Directive mandates granular building-level emissions disclosure across leased and owned portfolios. Asset managers must now trace energy consumption to individual tenant spaces and capital improvements. European REITs and pension fund real estate arms are responding by embedding IWMS data pipelines directly into ESG reporting workflows.
Facility executives are bundling software procurement with outcome-based energy performance guarantees. Energy service companies are displacing traditional software resellers as the primary channel to large commercial portfolios. This pattern is most visible in Germany and the Netherlands where efficiency contracting models have mature regulatory frameworks.
Integrated Workplace Management System (IWMS) Market Segmentation
IWMS procurement patterns diverge sharply across organizational scale and technical maturity. Facility executives prioritize segment-specific capabilities—space analytics for hybrid workplaces, predictive maintenance for critical infrastructure—over bundled platform economics.
Product Type:
Capital-intensity varies dramatically across functional modules, with sensor-integrated systems demanding substantially higher upfront hardware investment than administrative software layers.
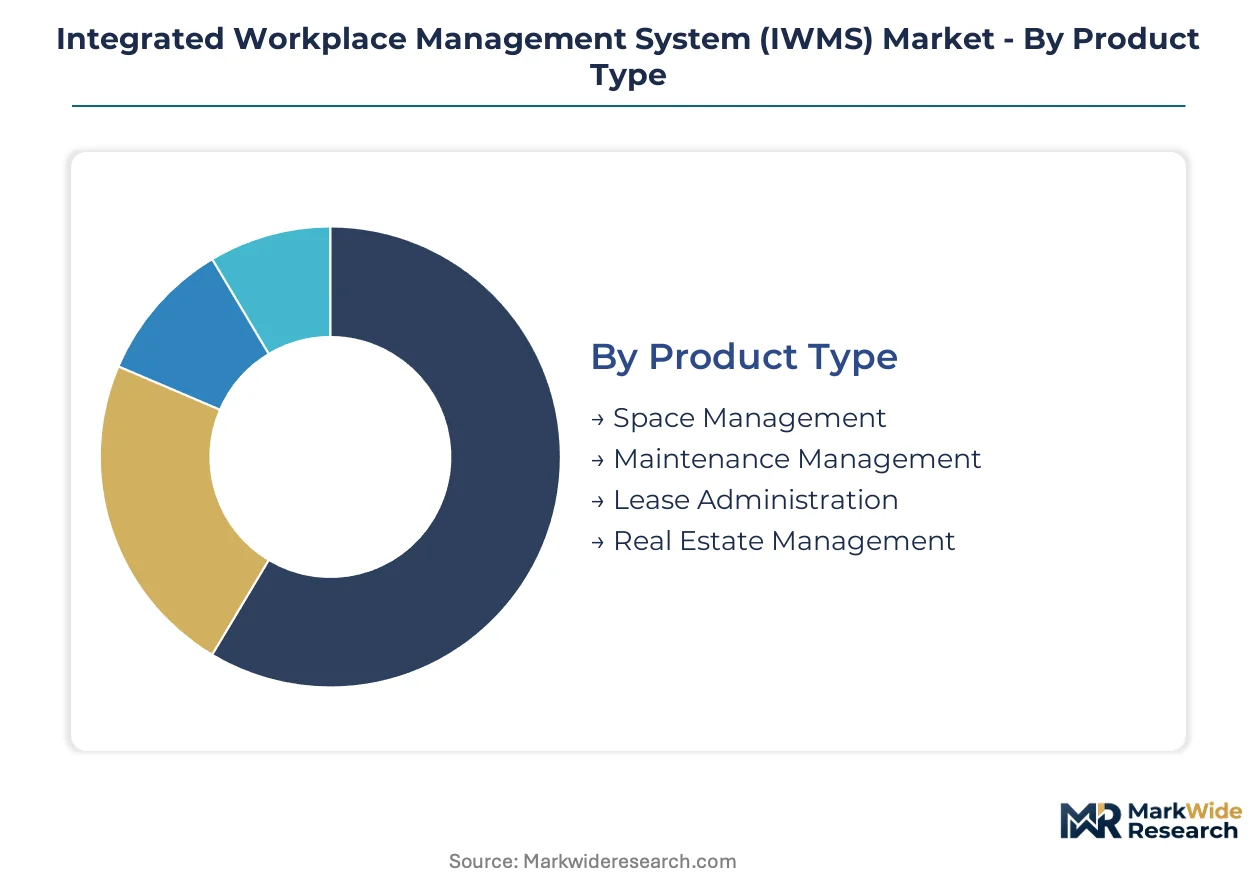
- Space Management:Occupancy sensors, desk booking algorithms, and floor plan visualization tools form the technical core. Corporate headquarters in the United States and Germany drive replacement cycles as return-to-office mandates force footprint recalibration.
- Maintenance Management:Work order automation, spare parts inventory tracking, and vendor dispatch systems reduce mean time to repair. Hospital networks and data center operators justify premium predictive modules analyzing vibration and thermal telemetry.
- Lease Administration:Critical date tracking, rent escalation calculations, and FASB/IFRS compliance documentation for lease accounting standards.
- Real Estate Management:Portfolio valuation tools, capital project budgeting, and scenario modeling for acquisition and disposition decisions.
Most installed capacity flows through Space Management. Expansion is steepest in Maintenance Management.
End User:
Customer archetypes shape procurement complexity, with regulated industries imposing security and audit requirements that extend implementation timelines.
- Corporates:Multi-site commercial tenants with distributed portfolios spanning headquarters, regional offices, and satellite locations. Technology and financial services verticals in the United States prioritize API-first architectures for rapid reconfiguration.
- Healthcare Facilities:Operating room scheduling systems, medical equipment maintenance protocols, and Joint Commission compliance documentation. Hospital networks digitize fastest where clinical operations depend on environmental controls.
- Educational Institutions:Campus-wide space scheduling, dormitory maintenance, and research facility asset tracking with grant-funded procurement cycles.
- Government Agencies:Federal modernization mandates and GSA schedule purchasing requirements with extended security clearance protocols.
Corporate deployments dominate current revenue. Healthcare Facilities are climbing the fastest.
Deployment:
Infrastructure ownership models determine total cost of ownership curves and upgrade flexibility across contract lifecycles.
- Cloud-Based:Multi-tenant SaaS architectures with automatic feature updates and consumption-based pricing. IT departments in the United States and Netherlands favor subscription economics over capital-intensive infrastructure ownership.
- On-Premises:Single-tenant installations behind organizational firewalls with full data sovereignty. Defense contractors and classified facilities mandate air-gapped deployments.
- Hybrid:Sensitive core systems on-premises with edge analytics and mobile interfaces cloud-hosted.
- Mobile:Native iOS and Android applications for field technicians and facility managers requiring offline functionality.
Cloud-Based environments host the majority of new implementations. Mobile capabilities are gaining share fastest.
Service Type:
Professional services attach rates correlate directly with platform complexity and organizational change management requirements.
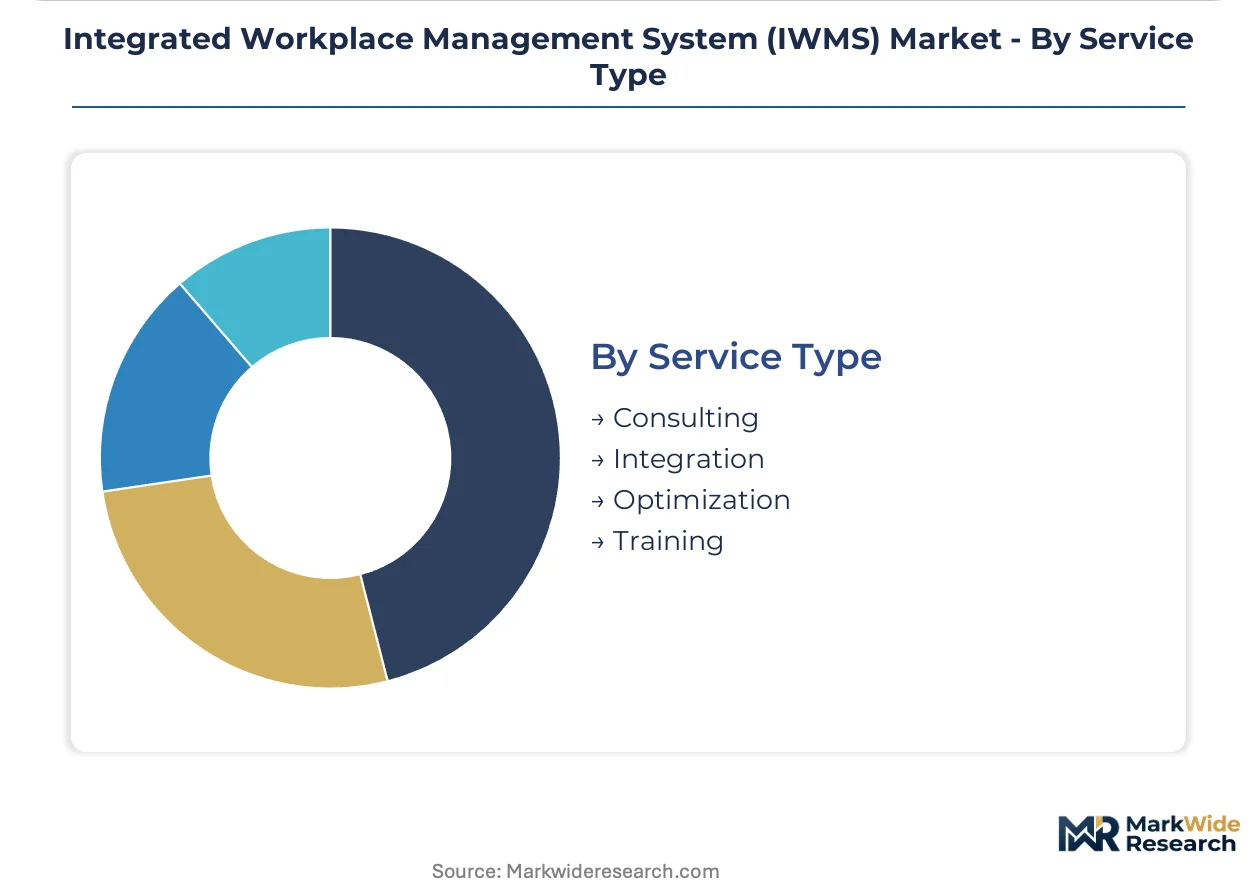
- Integration:BACnet and Modbus protocol bridging, legacy CAFM data migration, and ERP system connectors. European portfolios under EU Green Deal compliance deadlines accelerate integration spending.
- Consulting:Business process redesign, space utilization benchmarking, and IoT sensor placement strategy. Large corporate occupiers in the United States commission workplace transformation advisory.
- Optimization:Post-implementation tuning of predictive algorithms, energy analytics refinement, and user adoption analytics.
- Training:Role-based certification programs for facility managers, technicians, and executive dashboard users.
Integration services absorb the largest professional services budget. Optimization engagements are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping IWMS procurement as compliance cost differentials between jurisdictions drive platform selection. Facility executives migrate technology investments toward markets with mature efficiency mandates and transparent subsidy frameworks.
United States
Federal modernization directives and private sector return-to-office strategies dominate demand. OSHA workplace safety standards impose auditable documentation requirements that IWMS platforms automate. Corporate headquarters clusters in New York Metro and Silicon Valley accelerate replacement cycles as hybrid work patterns force footprint recalibration.
Germany
Energy service companies displace traditional software resellers through outcome-based performance guarantees. The EU Energy Performance of Buildings Directive mandates automated compliance documentation for commercial portfolios above 1,000 square meters. Industrial real estate concentrations in the Ruhr Valley and Bavaria embed IWMS data pipelines directly into ESG reporting workflows.
United Kingdom
Technology and financial services verticals prioritize API-first architectures for rapid workplace reconfiguration. The EU Corporate Sustainability Reporting Directive extends disclosure obligations to UK-based multinationals with European operations. London's financial district and Manchester's corporate hubs drive cloud-native deployment timelines from months to weeks.
India
Rapid office stock expansion in Bengaluru and Hyderabad lacks integrated facility management infrastructure. Central Electricity Authority building efficiency guidelines create procurement pressure for digitized energy monitoring. IT park developments in Hyderabad's HITEC City and Bengaluru's Electronic City attract mid-market SaaS implementations.
Netherlands
Efficiency contracting models with mature regulatory frameworks accelerate platform upgrades across commercial portfolios. The EU Green Deal's building efficiency mandates compress vendor selection cycles for real estate investment trusts. Amsterdam's Zuidas business district and Rotterdam port logistics facilities deploy predictive maintenance modules for critical infrastructure.
Integrated Workplace Management System (IWMS) Market Competitive Landscape
United States producers anchor the premium tier through cloud-native architectures and extensive integration partnerships; European specialists hold position around compliance automation and energy analytics. The vendor base stratifies across enterprise platform consolidators, vertical-specific module providers, and emerging AI-native entrants. Two dominant competitive moves define current positioning: incumbent restructuring of subscription economics around real-time IoT telemetry, and energy service companies capturing procurement channels through bundled performance guarantees.
Within the enterprise platform tier, Eptura and IBM Maximo Real Estate and Facilities exemplify divergent anchoring strategies. Eptura occupies a position emphasizing integration partnership breadth across diversified real estate portfolios. IBM Maximo represents the asset lifecycle functionality archetype embedded in broader enterprise ecosystems. AssetWorks sits within the public sector and educational vertical specialist tier where long-term maintenance planning requirements create durable contract structures.
| Leading Market Players |
|---|
| AssetWorks |
| Archibus |
| IBM Maximo Real Estate and Facilities |
| iOffice |
| Baseworx |
| Eptura |
| Spaceti |
| SpaceIQ |
| FMS:Workplace |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up software specialists dominate the IWMS vendor landscape, compressing channel margins through direct enterprise sales while enforcing pricing discipline via recurring-revenue covenants. This ownership structure accelerates cloud-native platform consolidation and restricts discounting flexibility across mid-market deployments.
Pricing Analysis
Distributor margins have collapsed to single-digit percentages as energy service companies and systems integrators capture direct procurement relationships. Three-tier pricing structure across premium, standard, and economy levels reflects predictive analytics module depth and IoT sensor integration density. Pricing pressure stems from outcome-based performance guarantees that shift revenue recognition toward energy savings realization. Corporate headquarters in the United States exhibit lowest price sensitivity; Indian IT park developers face acute budget constraints.
Supply Chain Analysis
ISO 41001 certification timelines and EU Green Deal compliance documentation create qualification bottlenecks for platform vendors seeking multinational facility management contracts. Hardware component sourcing concentrates in Taiwan, South Korea, and Germany for industrial-grade IoT sensors and edge computing devices. Cloud infrastructure draws from hyperscaler data centers in the United States, Ireland, and Singapore. Single-source vulnerability in BACnet protocol chipsets threatens deployment timelines. Distribution runs through energy service companies and systems integrators rather than traditional software resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IWMS market has matured into a late-cycle quality story where procurement committees prioritize ISO 41001-certified platforms with embedded AI-IoT convergence over cost-optimized point solutions. Healthcare facilities digitizing operating room scheduling represent the clearest demand-shift toward premium specifications.
For Market Incumbents: Extend predictive maintenance module capabilities through computer vision occupancy sensor integration to defend against specialized point solution vendors capturing discrete budgets. Strengthen API-first architecture investments to maintain interoperability leadership as energy service companies displace traditional resellers. Vertical integration into edge hardware manufacturing in Taiwan and Germany reduces supply chain vulnerability. For New Entrants and Emerging Players: Cloud-native marketplace models enabling modular capability composition without enterprise procurement cycles offer the lowest-friction entry path. Target underpenetrated Indian commercial real estate in Bengaluru and Hyderabad where rapid office stock expansion lacks integrated facility management infrastructure. Pursue outcome-based energy performance guarantee partnerships with European efficiency contractors as the primary channel strategy. For Investors and Strategic Acquirers: Energy service companies are the most active acquirer in this space, consolidating software procurement with performance contracting to capture long-term facility management relationships. Platform vendors with embedded ESG reporting workflows and EU Corporate Sustainability Reporting Directive compliance automation represent the highest-viability acquisition targets across a five-to-ten year window. Watch for inflection in ISO 41001 certification acceleration timelines as the signal for competitive qualification windows tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures from Eptura compress deployment timelines from months to weeks for corporate headquarters. |
| Acquisition of Specialist Firm | Energy service companies acquire predictive analytics vendors to bundle outcome-based guarantees with software subscriptions. |
| Strategic Partnership | IBM Maximo Real Estate and Facilities leverages enterprise ecosystem partnerships for asset lifecycle functionality depth. |
| Product Launch | Digital twin platforms from university campus deployments consolidate space planning and energy modeling into unified 3D environments. |
| Geographic Expansion | AssetWorks penetrates public sector and educational verticals where long-term maintenance planning creates durable contract structures. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facility executives, IT procurement officers, integration specialists, and energy service company account directors with secondary validation against SEC filings, EU Energy Performance of Buildings Directive compliance databases, and hyperscaler capex disclosures. Bottom-up deployment tracking across cloud-based, on-premises, and hybrid installations triangulated against top-down vendor revenue estimates.
Segment-weighting applied differential growth assumptions across deployment models, organization size tiers, and vertical adoption patterns including healthcare facilities, corporate portfolios, educational institutions, and government agencies. CAGRs derived from modeled subscription revenue trajectories and professional services attach rates, incorporating IoT sensor hardware shipment forecasts and building automation system upgrade cycles as industry-specific inputs across the projection horizon.
Regulatory enforcement delays, cloud infrastructure cost volatility, and enterprise IT budget contraction are the dominant revision risks to modeled outcomes. Deviation in EU Green Deal building efficiency mandate implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Managed Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Europe Managed Infrastructure Services Market