
 Sweden Data Center Cooling Market | 2026-2036
Sweden Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Cooling Market Insights
The EU Green Deal is rebalancing cooling procurement priorities across Swedish colocation and hyperscale facilities, pushing operators toward lower PUE targets and carbon-transparent supply chains. Schneider Electric SE leverages its integrated microgrid and thermal management portfolio to anchor large-scale deployments in Stockholm's data center corridor. Vertiv Group Corp competes through precision cooling architectures optimized for Nordic free-air cooling conditions. Munters Group AB specializes in evaporative and dehumidification systems that sustain energy efficiency during seasonal humidity variations.
Sweden data center cooling encompasses engineered thermal management systems designed to maintain IT equipment within operational temperature bands, typically delivering supply air between 18°C and 27°C per ASHRAE guidelines while dissipating heat loads ranging from sub-100 kW edge nodes to multi-megawatt hyperscale halls. Liquid cooling and immersion cooling segments are capturing disproportionate attention as GPU-intensive AI workloads push rack densities beyond 50 kW per cabinet, rendering traditional air-based methods thermally inadequate. Direct expansion technology retains installed-base dominance in legacy facilities, though chilled water architectures are gaining share among cloud providers seeking centralized plant efficiency and heat recovery integration.
Swedish operators must comply with Boverket building energy codes, EU Energy Efficiency Directive requirements, and national climate reporting frameworks administered by the Swedish Environmental Protection Agency, all of which mandate documented PUE thresholds and renewable energy sourcing disclosures. The Swedish Energy Agency enforces efficiency standards that shape equipment procurement specifications and retrofit timelines for existing facilities. Stakeholders should monitor how forthcoming EU AI Act infrastructure transparency rules intersect with national grid capacity allocation processes, as this regulatory convergence will determine cooling technology selection criteria and site approval velocity for next-generation deployments.
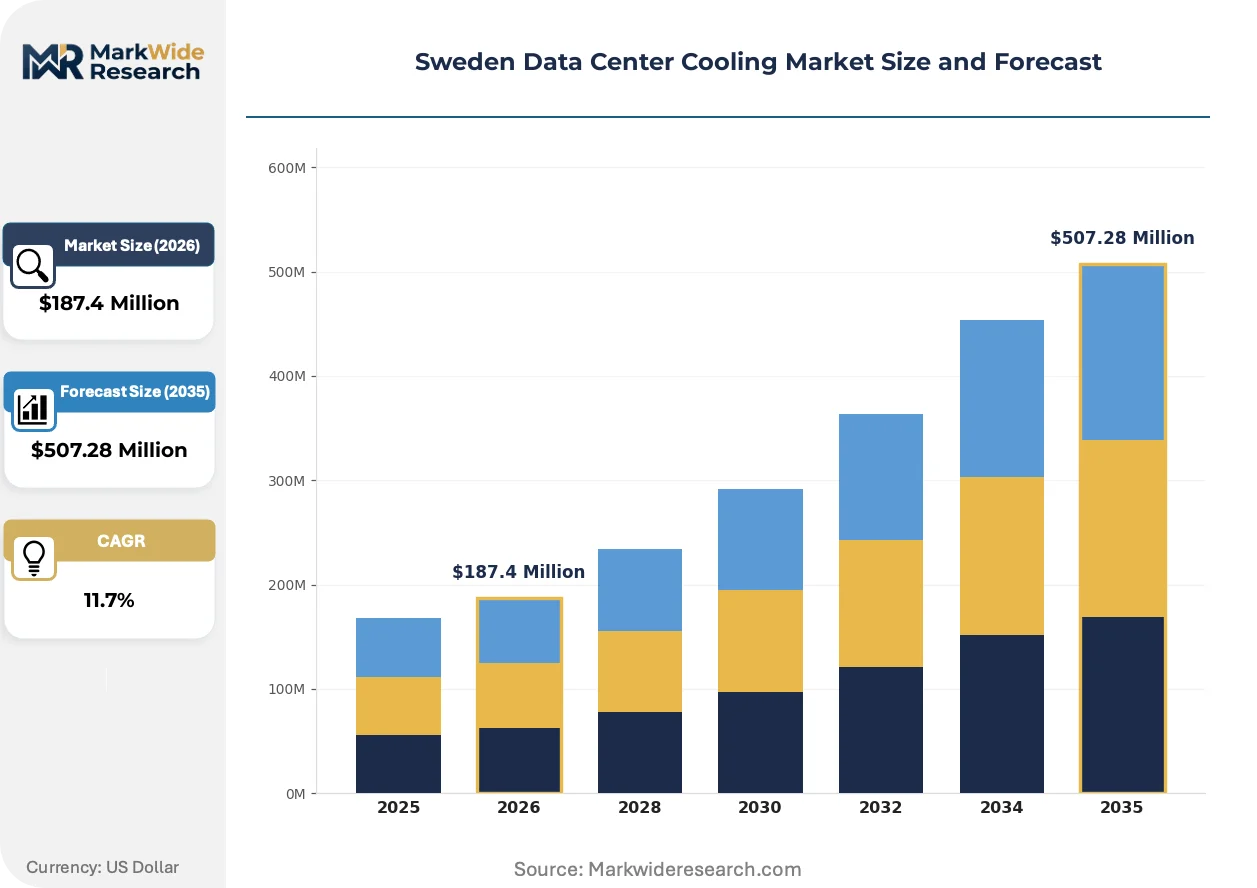
Market Dynamics
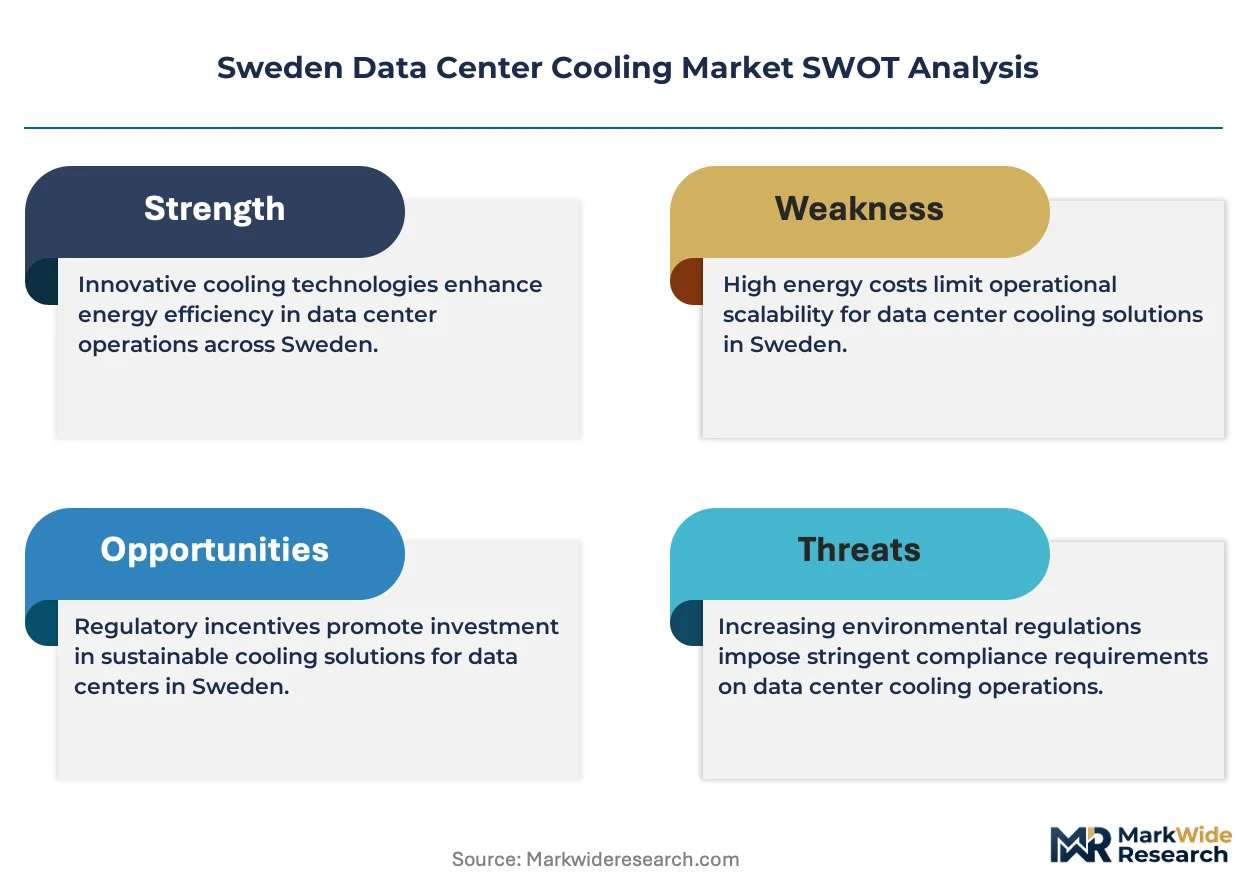
GPU-intensive AI workloads are compressing thermal design power thresholds across Swedish data center halls, forcing operators to abandon traditional air-cooled architectures before rack densities breach 50 kW per cabinet.
Growth Catalysts
- EU Green Deal decarbonization mandates:The framework accelerates liquid cooling procurement across Stockholm and Gothenburg facilities by binding PUE disclosures to operating licenses.
- Hyperscale cloud expansion:Major providers are establishing Nordic presences to exploit Sweden's renewable energy surplus and ambient temperature advantages for free-air cooling integration.
- Immersion cooling technology maturation:Dielectric fluid systems now handle AI training clusters that air-cooled infrastructure cannot thermally sustain.
Market Restraints
- Copper and aluminum input volatility:Chilled water plant construction faces material cost uncertainty that compresses project IRRs for colocation developers.
- Liquid cooling vendor concentration:Specialized component supply clusters in Germany and the Netherlands create single-source exposure for Swedish integrators.
- F-Gas Regulation phase-down schedules:Synthetic refrigerant restrictions limit retrofit options for legacy direct expansion systems in older Stockholm facilities.
Strategic Opportunities
- District heating network integration:Waste heat recovery partnerships with municipal utilities in Uppsala and Linköping unlock new revenue streams for hyperscale operators.
- Edge computing node deployment:Sub-100 kW facilities in northern Sweden's industrial zones address latency-sensitive manufacturing automation demand.
- EU AI Act infrastructure transparency rules:Pending disclosure requirements for compute-intensive systems will advantage early liquid cooling adopters with documented carbon intensity data.
Industry Challenges
- Thermal-fluid engineering talent scarcity:Immersion cooling deployment requires specialists conversant in both IT infrastructure and chemical handling protocols that Swedish technical institutes currently underproduce.
- Legacy air-cooled plant stranding risk:Operators with recent investments in raised-floor precision cooling face accelerated obsolescence before depreciation schedules complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Cooling Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Aired, Liquid Cooling, Immersion Cooling, Vapor Compression End User: Telecommunications, Government, Financial Institutions, Cloud Providers Cooling Capacity: Up to 100 kW, 101 kW to 500 kW, 501 kW to 1 MW, Above 1 MW Technology: Direct Expansion, Chilled Water, Evaporative Cooling, Heat Exchangers |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, ebm-papst Group, Daikin Applied Europe S.p.A, FlaktGroup Holding GmbH, STULZ GmbH, Rittal GmbH & Co. KG, Munters Group AB, Alfa Laval AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Cooling Market Trends and Innovations
Cooling architecture decisions in Sweden are increasingly inseparable from heat reuse economics and grid interconnection negotiations, compressing the traditional silo between facilities engineering and energy trading functions.
Direct-to-chip liquid cooling is electrifying competitive positioning among Stockholm colocation providers by enabling 80 kW rack densities that air-cooled rivals cannot match. Hyperscale AI training clusters are adopting this technology within eighteen-month procurement cycles. The shift is compressing addressable market share for traditional precision cooling vendors who lack pumped refrigerant expertise.
The EU Energy Efficiency Directive's revised PUE reporting thresholds are forcing Swedish operators to install sub-metering infrastructure that disaggregates cooling energy from IT load. Facilities must submit verified annual performance data to the Swedish Energy Agency. Cloud providers with centralized plant architectures are responding faster than retail colocation operators with distributed mechanical systems.
Buyers are consolidating vendor relationships around integrated thermal-electrical packages rather than procuring cooling and power infrastructure separately. This pattern compresses the addressable market for standalone precision cooling specialists while advantaging firms with microgrid and energy storage portfolios. The behavior is most visible among hyperscale entrants in the Stockholm data center corridor negotiating single-source EPC contracts.
Sweden Data Center Cooling Market Segmentation
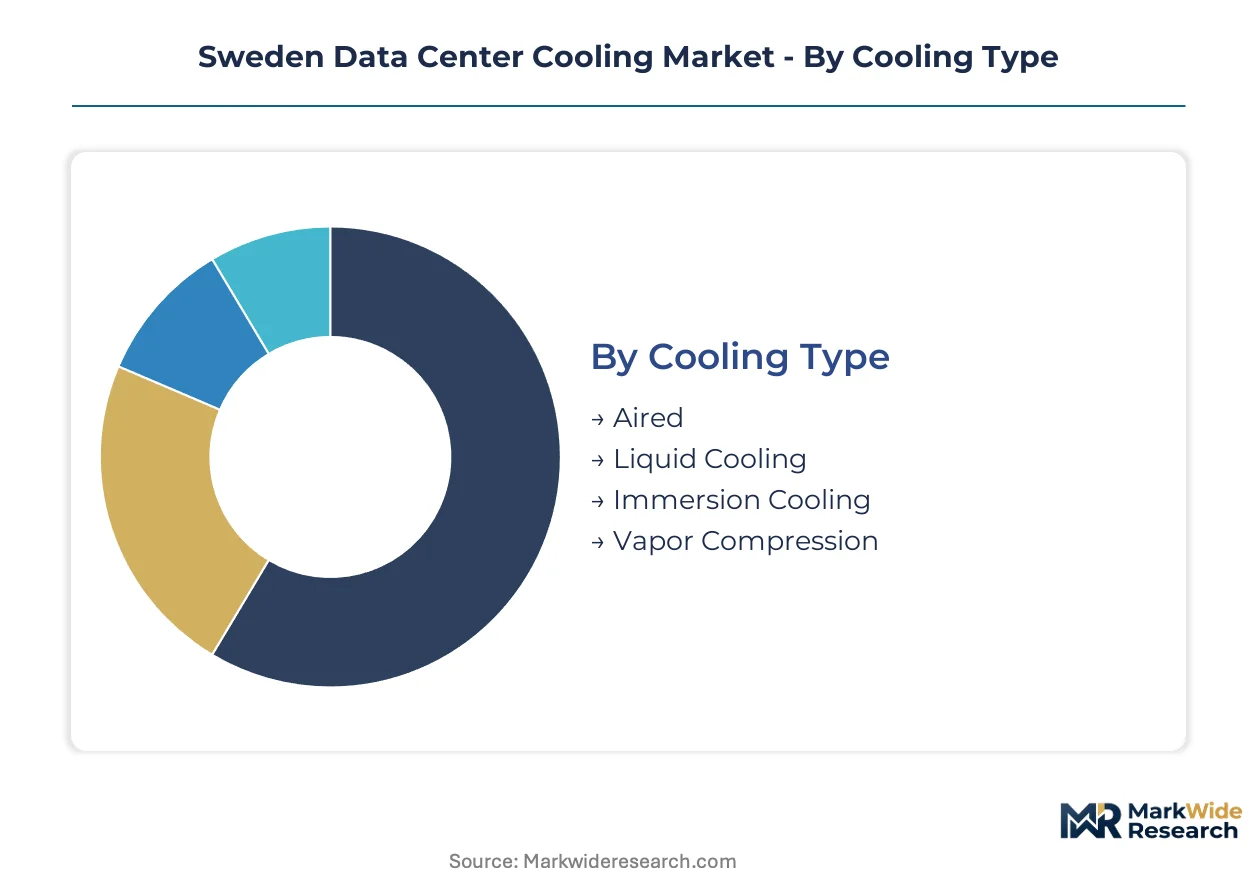
Cooling procurement patterns in Sweden diverge sharply by deployment scale and workload intensity. Segment boundaries increasingly determine vendor selection criteria, regulatory compliance pathways, and heat recovery economics across Stockholm's hyperscale corridor and regional edge nodes.
Cooling Type:
Supply concentration among Nordic free-air cooling specialists tilts procurement leverage toward integrated mechanical-electrical vendors with localized service networks.
- Liquid Cooling:Pumped refrigerant and direct-to-chip architectures handle AI training clusters exceeding 50 kW per rack. Cloud providers in Stockholm's data center corridor specify these systems for GPU-intensive workloads where air-cooled infrastructure fails thermally.
- Immersion Cooling:Dielectric fluid tanks submerge entire server assemblies, eliminating fans and enabling 100+ kW densities. Early adopters in Gothenburg's emerging AI cluster favor this technology for its heat recovery integration with municipal district heating networks.
- Aired:Conventional raised-floor precision cooling retains installed-base dominance in legacy facilities throughout older Stockholm suburbs.
- Vapor Compression:Direct expansion systems face F-Gas Regulation phase-down constraints that limit retrofit options for operators with recent capital commitments.
Today's leader: Liquid Cooling. Tomorrow's challenger: Immersion Cooling.
End User:
Application-specific thermal profiles reshape vendor engagement models, with latency tolerance and carbon disclosure obligations driving divergent specification requirements.
- Cloud Providers:Hyperscale operators negotiate centralized plant architectures with heat recovery integration. Their procurement cycles compress from 36 to 18 months as AI infrastructure demand accelerates.
- Telecommunications:Edge node deployments across northern Sweden's industrial zones prioritize sub-100 kW packaged units with minimal maintenance requirements.
- Financial Institutions:Stockholm-based banks and payment processors demand documented PUE thresholds for regulatory reporting to the Swedish Financial Supervisory Authority.
- Government:National agency data centers in Uppsala and Linköping emphasize Boverket building energy code compliance and renewable energy sourcing verification.
Cloud Providers command specification-setting power. Telecommunications represents the steepest expansion trajectory for packaged cooling units.
Cooling Capacity:
Margin structures compress below 100 kW where standardized units dominate, while above 1 MW deployments reward engineering-intensive custom plant design.
- Above 1 MW:Hyperscale halls require centralized chilled water plants with heat exchanger integration to municipal district heating networks. These facilities concentrate in Stockholm's data center corridor where grid interconnection agreements determine site viability.
- 501 kW to 1 MW:Mid-scale colocation operators face stranded asset risk as AI workloads migrate toward higher-density facilities.
- 101 kW to 500 kW:Regional enterprise data centers in Gothenburg and Malmö represent stable replacement demand for legacy air-cooled systems.
- Up to 100 kW:Edge computing nodes across Sweden's manufacturing automation zones specify packaged precision cooling with remote monitoring capabilities.
Above 1 MW captures capital deployment. Up to 100 kW is gaining share fastest as latency-sensitive applications proliferate.
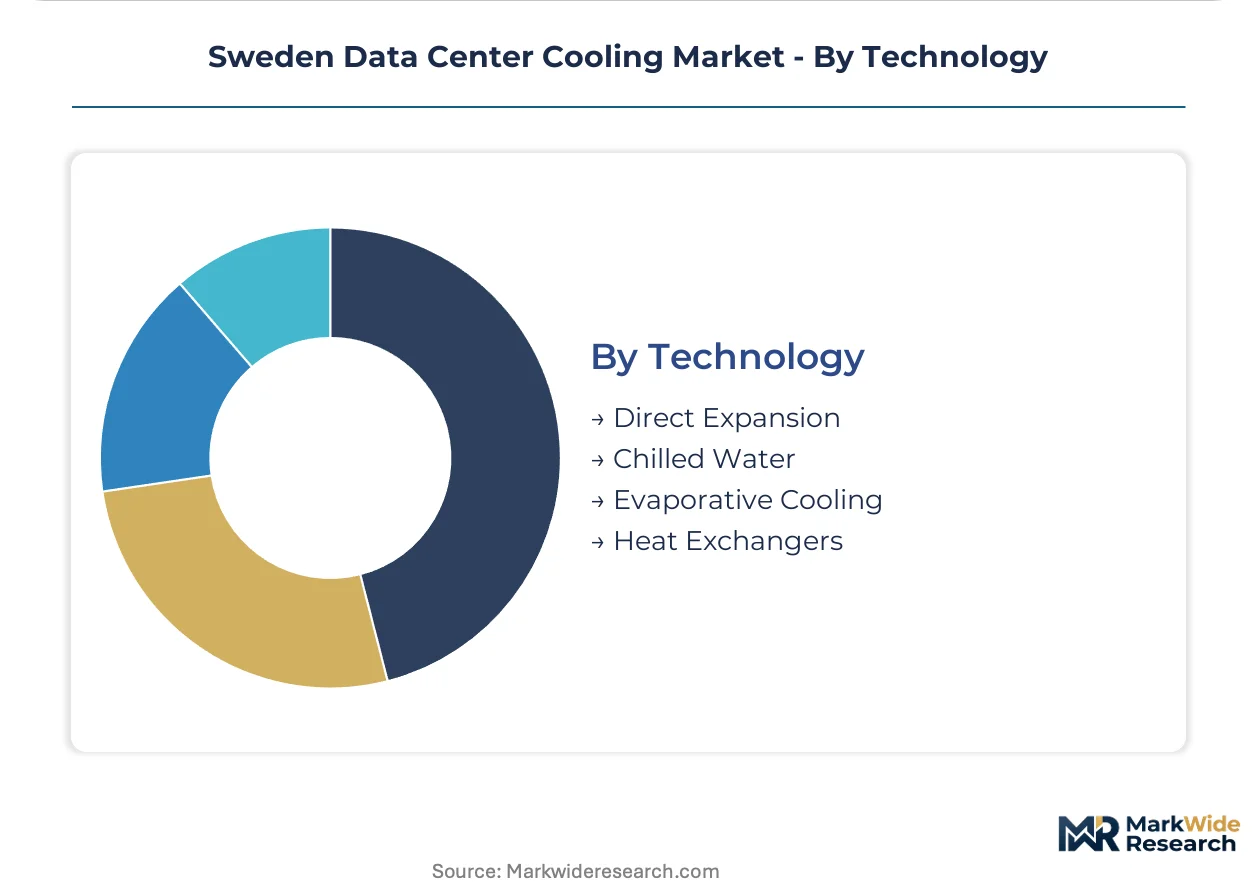
Technology:
Technology selection increasingly binds to heat reuse economics and EU Energy Efficiency Directive reporting infrastructure rather than standalone thermal performance.
- Chilled Water:Centralized plant architectures enable heat recovery integration and sub-metering compliance for PUE disclosure. Cloud providers specify these systems for new Stockholm corridor developments.
- Direct Expansion:Legacy installed base faces accelerated obsolescence as F-Gas Regulation restricts refrigerant availability for maintenance and expansion.
- Evaporative Cooling:Munters Group AB and Nordic specialists optimize these systems for seasonal humidity variations across Sweden's coastal and inland climate zones.
- Heat Exchangers:Plate-and-frame configurations facilitate waste heat recovery partnerships with municipal utilities in Uppsala and Linköping.
Chilled Water anchors new construction. Heat Exchangers are climbing the fastest as district heating integration becomes standard specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish thermal-fluid engineering talent concentrates in Stockholm and Gothenburg, anchoring Nordic data center cooling design expertise. This workforce distribution shapes regional deployment patterns across the country's data center corridor.
Stockholm
Hyperscale cloud providers drive liquid cooling demand in Stockholm's data center corridor, where free-air cooling integration maximizes operational efficiency. Boverket building energy codes mandate documented PUE thresholds for new facilities. The Kista Science City cluster hosts multiple AI training facilities adopting direct-to-chip architectures for GPU-intensive workloads.
Gothenburg
Gothenburg's emerging AI cluster favors immersion cooling systems for their district heating integration potential. The Swedish Energy Agency enforces efficiency standards that shape equipment procurement specifications across the region. Chalmers University partnerships accelerate thermal-fluid research commercialization in the city's Lindholmen Science Park.
Uppsala
Waste heat recovery partnerships with municipal utilities unlock revenue streams for hyperscale operators in Uppsala. EU Energy Efficiency Directive requirements bind PUE disclosures to operating licenses for facilities above 1 MW capacity. The Uppsala Science Park corridor concentrates mid-scale colocation operators retrofitting legacy air-cooled plants.
Linköping
Linköping's district heating network integration opportunities attract edge computing deployments addressing manufacturing automation demand. F-Gas Regulation phase-down schedules limit retrofit options for older direct expansion systems in the region. The Mjärdevi Science Park hosts sub-100 kW facilities specifying packaged precision cooling with remote monitoring capabilities.
Malmö
Malmö's regional enterprise data centers represent stable replacement demand for legacy air-cooled systems in the 101 kW to 500 kW range. The Swedish Environmental Protection Agency administers national climate reporting frameworks affecting facility retrofits. The Øresund region's cross-border grid interconnection agreements influence cooling technology selection for latency-sensitive applications.
Sweden Data Center Cooling Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Sweden's data center cooling market, creating a tiered structure where integrated infrastructure vendors hold procurement leverage. The market consolidates around firms with microgrid and thermal management portfolios that can negotiate single-source EPC contracts. Three archetypes dominate: integrated electrical-thermal platforms, precision cooling specialists, and Nordic climate-optimized system providers. M&A activity targets heat recovery integration capabilities, while capacity expansion concentrates in Stockholm's data center corridor.
Among integrated platform providers, Schneider Electric SE and Vertiv Group Corp occupy positions anchoring large-scale deployments through combined power and cooling infrastructure offerings. Munters Group AB exemplifies the Nordic climate-optimized archetype, specializing in evaporative systems calibrated for Sweden's seasonal humidity variations. These three firms represent distinct competitive vectors: electrical-thermal integration, precision architecture, and regional climate adaptation.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| ebm-papst Group |
| Daikin Applied Europe S.p.A |
| FlaktGroup Holding GmbH |
| STULZ GmbH |
| Rittal GmbH & Co. KG |
| Munters Group AB |
| Alfa Laval AB |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud providers consolidating vendor relationships around single-source EPC contracts are compressing procurement leverage for standalone cooling specialists and forcing integrated mechanical-electrical vendors to absorb margin pressure through bundled service offerings.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive positioning across Stockholm's data center corridor. Cloud providers negotiating integrated thermal-electrical packages command three-tier pricing structure across premium, standard, and economy levels, with premium tiers capturing heat recovery integration and sub-metering compliance. Price differentiation hinges on certification grade for EU Energy Efficiency Directive reporting and geographic delivery cost to Stockholm's grid-constrained zones. Cost compression in standard-tier precision cooling intensifies because F-Gas Regulation phase-down limits retrofit options for legacy direct expansion systems. Retail colocation operators with distributed mechanical systems exhibit highest price sensitivity, while hyperscale entrants with centralized plant architectures prioritize performance transparency over unit economics.
Supply Chain Analysis
EU local-content requirements under the Green Deal Industrial Plan are reshaping sourcing patterns for Swedish integrators, pressuring procurement teams to document domestic manufacturing shares for heat exchanger and pumping assemblies. Component manufacturing concentrates in Germany, the Netherlands, and Denmark, with specialized dielectric fluid production anchored in German chemical corridors. Raw material dependencies span copper for chilled water piping, aluminum for heat exchanger fins, and synthetic refrigerants facing F-Gas Regulation restrictions. Single-source vulnerability runs through precision pumping assemblies sourced from concentrated German component clusters. Distribution runs through Stockholm-based system integrators serving the Kista Science City cluster, with secondary logistics nodes in Gothenburg and Malmö.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's data center cooling market offers margin expansion through heat recovery monetization and premium-tier liquid cooling adoption, as district heating integration transforms thermal infrastructure from cost center to revenue generator.
For Market Incumbents: Acquire thermal-fluid engineering capabilities to address talent scarcity constraining immersion cooling deployment timelines. Incumbents must consolidate heat recovery integration expertise before specialized German and Dutch component suppliers backward integrate into system assembly. Priority moves include capacity addition in Stockholm's data center corridor to anchor single-source EPC negotiations, plus certification investment for EU AI Act infrastructure transparency pre-compliance. The threat of GPU-intensive workload migration toward hyperscale facilities with direct-to-chip architectures accelerates obsolescence risk for air-cooled installed bases. For New Entrants and Emerging Players: Begin with sub-100 kW edge computing nodes across northern Sweden's manufacturing automation zones, where latency-sensitive applications outstrip incumbent service coverage. The most penetrable segment sits in Linköping's Mjärdevi Science Park, where packaged precision cooling with remote monitoring capabilities addresses unmet industrial IoT demand. A specialized go-to-market angle centers on evaporative systems optimized for Sweden's seasonal humidity variations, leveraging Nordic climate expertise against generalized global vendors. For Investors and Strategic Acquirers: Asymmetric upside sits with thermal-fluid engineering specialists possessing both IT infrastructure and chemical handling protocols. Long-term viability over the five-to-ten year horizon favors acquisition targets with district heating network integration capabilities and documented PUE performance data. The specific signal to watch is EU AI Act infrastructure transparency rule finalization, which will trigger accelerated procurement cycles for compliant liquid cooling systems and compress valuation multiples for legacy air-cooled asset portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| District Heating Integration Partnership | Waste heat recovery agreements with Uppsala and Linköping municipal utilities unlock recurring revenue streams for hyperscale operators. |
| Thermal-Fluid Engineering Acquisition | Specialist talent pools in Stockholm and Gothenburg address deployment bottlenecks constraining immersion cooling adoption timelines. |
| EU AI Act Pre-Compliance Certification | Documented carbon intensity data positions early liquid cooling adopters for accelerated site approval under forthcoming transparency rules. |
| Centralized Plant Architecture Deployment | Chilled water systems with sub-metering infrastructure satisfy Swedish Energy Agency PUE disclosure mandates for cloud provider facilities. |
| Nordic Climate-Optimized System Development | Evaporative cooling calibrated for seasonal humidity variations captures procurement preference among cost-sensitive regional operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center engineering directors, facilities procurement managers, municipal utility partnership leads, and thermal-fluid research specialists at Chalmers University with secondary validation through Swedish Energy Agency efficiency standard filings, EU Energy Efficiency Directive implementation reports, Boverket building code documentation, and hyperscaler capital expenditure disclosures. Bottom-up facility-level capacity assessments and top-down market sizing triangulated volume estimates across cooling type, end user, and capacity tier segments.
Segment-weighting approaches distributed value proportionally across liquid cooling, immersion cooling, air-cooled, and vapor compression technologies, with further disaggregation by cloud provider, telecommunications, financial institution, and government end users. Modeled dimensions spanned cooling capacity tiers from edge nodes through hyperscale halls, technology selection binding to heat reuse economics, and regional clustering across Stockholm, Gothenburg, Uppsala, Linköping, and Malmö sub-markets. CAGRs derived from facility pipeline analysis, regulatory mandate timelines, and workload density projections for GPU-intensive AI training clusters.
Several conditions sit outside the modeled scope, including potential F-Gas Regulation acceleration, grid interconnection moratoria, and copper price volatility beyond historical bands. Forecasts reflect assumptions around continued hyperscale expansion, EU Green Deal enforcement consistency, and district heating network capacity availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market