
 Asia-Pacific Machine Learning As a Service Market | 2026-2036
Asia-Pacific Machine Learning As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Machine Learning As a Service Market Analytics
Competitive Landscape
ISO 27001 certification is bifurcating the competitive landscape between enterprise-ready providers and regional challengers lacking audit trails. Alibaba Cloud leverages its domestic data center footprint to anchor government and fintech workloads across mainland China. Microsoft competes through Azure OpenAI integrations that sustain premium positioning among multinational subsidiaries. SenseTime specializes in computer vision APIs, dominating smart city and surveillance contracts where facial recognition accuracy thresholds exceed generic alternatives.
Technology and Segmentation
Machine Learning As a Service denotes cloud-hosted delivery of algorithmic model development, training, and inference where providers manage GPU cluster orchestration, feature engineering pipelines, and auto-scaling APIs against customer data. The architecture eliminates capital expenditure on NVIDIA A100/H100 clusters while enabling sub-100 millisecond inference latency through edge node distribution. Public cloud deployment captures the majority of current workloads, though hybrid cloud configurations are expanding fastest among financial institutions subject to data residency mandates. Predictive analytics services command premium pricing relative to raw API access, as value concentrates in outcome-oriented fraud detection and demand forecasting applications rather than undifferentiated compute.
Regulatory Environment
China's MIIT cloud service licensing regime and India's MeitY data governance framework create divergent compliance thresholds that fragment cross-border service architecture. Japan's METI AI governance guidelines and South Korea's K-ISMS certification further layer operational requirements onto providers seeking multi-country coverage. Stakeholders must monitor whether emerging algorithmic accountability rules in Australia and Singapore will extend liability to MLaaS platforms for downstream model decisions.
Market Dynamics
China's MIIT cloud computing licensing regime and data localization mandates are fragmenting platform architectures across the Asia-Pacific, forcing providers to rebuild infrastructure country-by-country rather than operating unified regional stacks.
Growth Catalysts
- India's BFSI cloud migration:Financial institutions are abandoning on-premises GPU clusters for managed ML pipelines, accelerating subscription revenue for inference-as-a-service offerings.
- Japan's METI AI governance guidelines:The framework creates procurement clarity that reduces enterprise sales cycles and expands addressable spend among risk-averse manufacturers.
- Edge inference deployment:Sub-100 millisecond latency requirements for real-time fraud detection are distributing compute nodes closer to transaction origination points across Southeast Asian payment networks.
Market Restraints
- NVIDIA H100 supply concentration:Taiwan Semiconductor Manufacturing capacity constraints limit GPU cluster scaling for training workloads, creating 6-9 month provisioning delays.
- Cross-border data friction:China's data localization law and India's MeitY framework prevent unified model training across national boundaries, duplicating infrastructure costs.
- Substitution by open-source frameworks:Enterprises with internal data science teams are deploying self-managed Kubernetes ML pipelines using open tooling, bypassing commercial API fees.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:E-commerce platforms in these markets lack mature fraud detection infrastructure, creating first-mover advantage for computer vision API providers.
- Australia algorithmic accountability rules:Emerging liability frameworks will drive demand for audit-trail-enabled MLaaS platforms among financial services and healthcare buyers.
- Federated learning convergence:Privacy-preserving model training across siloed data sources without centralization addresses regulatory constraints while unlocking multi-party analytics contracts.
Industry Challenges
- MLOps engineering scarcity:Pipeline orchestration and feature store management expertise remains concentrated in Singapore and Bangalore, constraining delivery velocity for regional expansion.
- ISO 27001 certification timelines:12-18 month audit cycles delay market entry for new providers, entrenching incumbents with existing attestations.
- Legacy core banking integration:Mainframe transaction systems in Japanese and Australian banks require custom API middleware, inflating implementation costs and extending payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Machine Learning As a Service Market |
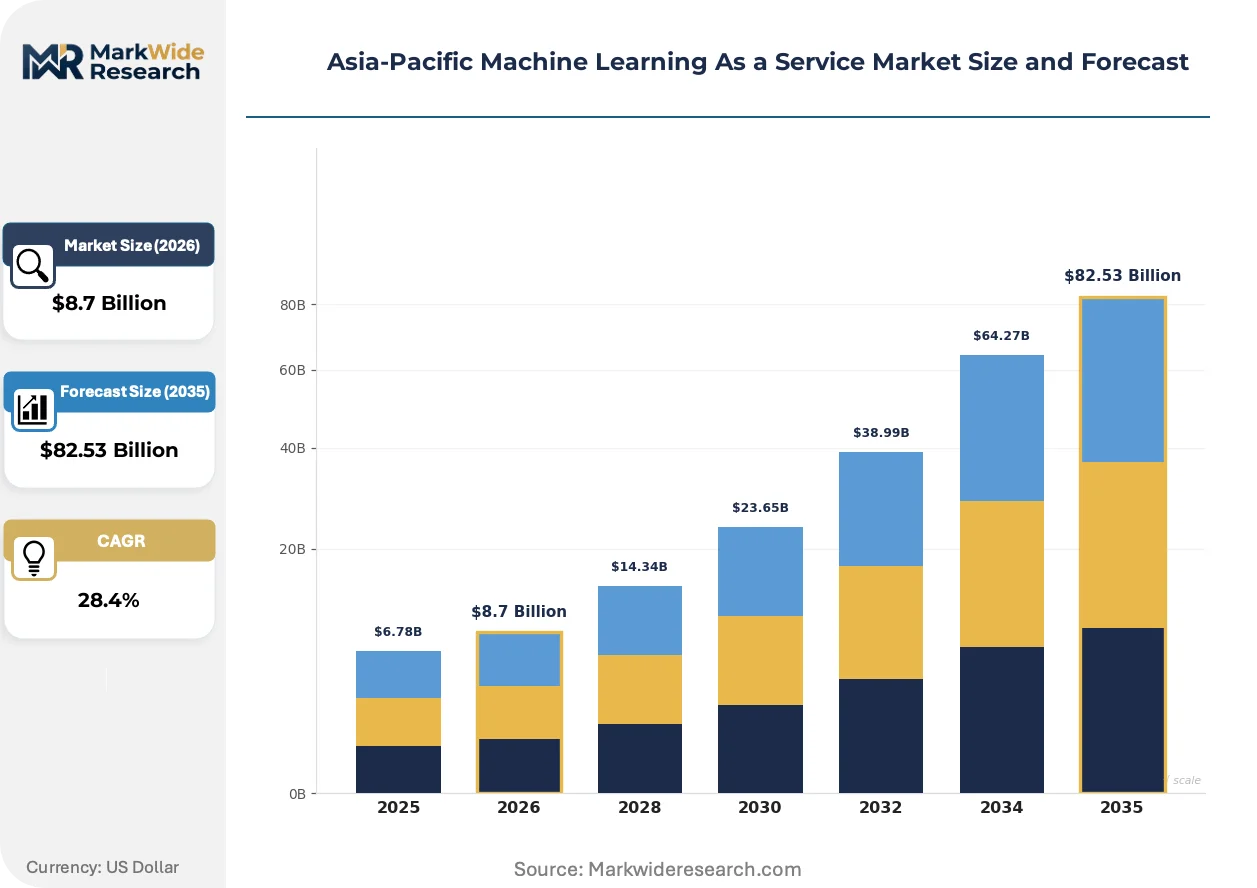
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Model Training, Data Processing, Predictive Analytics, API Access End User: Healthcare Providers, Retail Businesses, Financial Institutions, Telecommunications Solution Type: Natural Language Processing, Computer Vision, Speech Recognition, Recommendation Engines |
| Companies Covered | Alibaba Cloud, Baidu, Amazon Web Services, Microsoft, Google, IBM, Huawei, SenseTime, Tencent Cloud, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Machine Learning As a Service Market Evolving Landscape
Foundation model deployment patterns are shifting from centralized cloud training toward distributed inference architectures, compressing latency requirements while expanding regulatory surface area for compliance engineering.
GPU cluster orchestration software is miniaturizing from hyperscale data centers to metro-edge installations. Singaporean fintechs are deploying containerized inference nodes within domestic exchange facilities. This topology is miniaturizing the physical footprint required for sub-50 millisecond fraud scoring, collapsing the distinction between cloud and on-premise deployment categories.
India's MeitY data governance framework now mandates explicit consent logging for AI-driven credit decisions. The regulation forces MLaaS providers to implement immutable audit trails for model versioning and feature provenance. Non-banking financial companies in Mumbai and Delhi are selecting vendors based on native compliance tooling rather than raw inference pricing.
Enterprise buyers are unbundling model training from inference services, contracting specialized providers for each phase. Japanese automotive manufacturers now source foundation model development from domestic specialists while routing production inference through Alibaba Cloud's Osaka region. This bifurcation is visible most acutely in precision manufacturing verticals where IP protection concerns override single-vendor convenience.
Asia-Pacific Machine Learning As a Service Market Segmentation
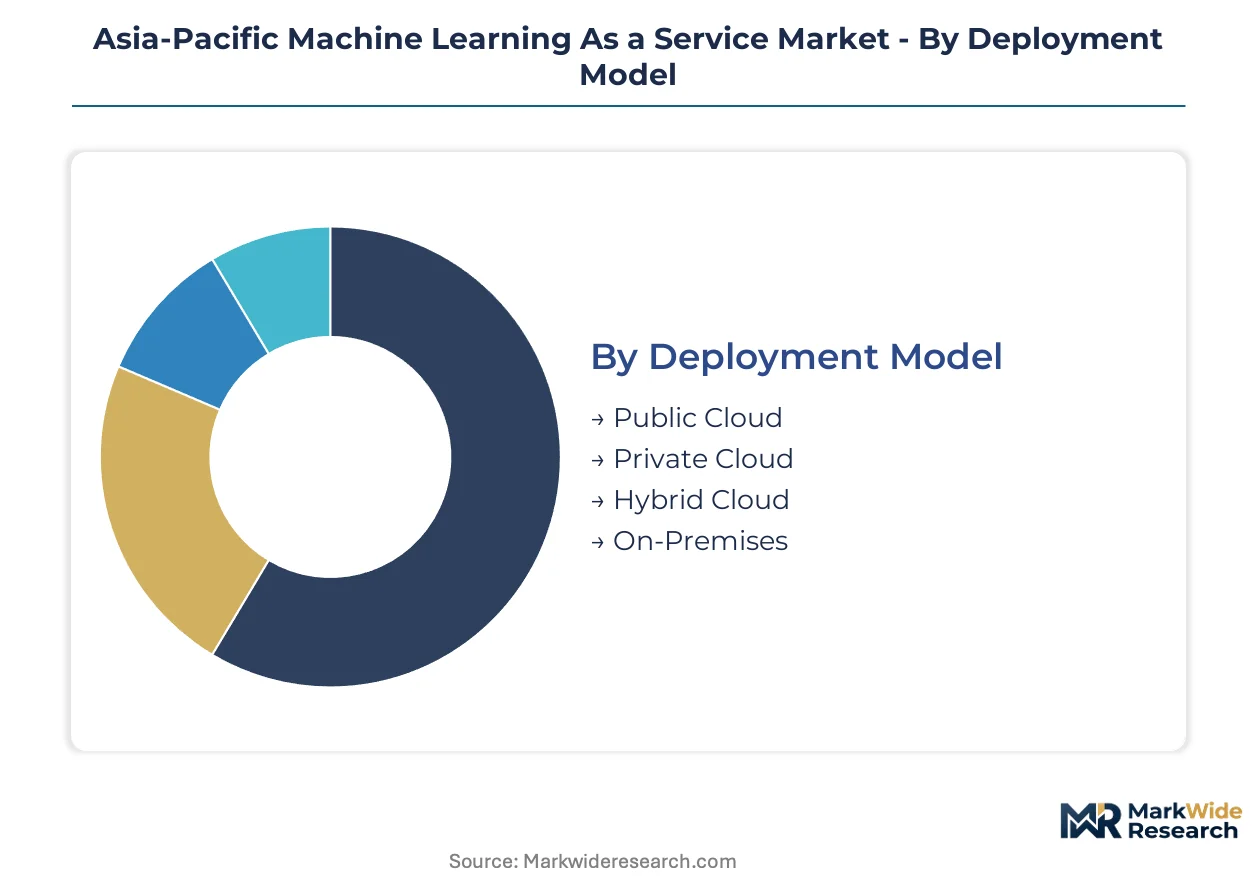
Segmentation in Asia-Pacific MLaaS reveals how procurement channels diverge across deployment models and service types. Understanding these splits exposes where infrastructure costs concentrate and which buyer categories command premium pricing for compliance-ready configurations.
Deployment Model:
Public cloud deployments flow through hyperscaler direct sales and marketplace channels, while private and hybrid configurations route through systems integrators with regulatory certification credentials.
- Public Cloud:Multi-tenant GPU clusters deliver auto-scaling inference APIs without capital expenditure. Indian e-commerce platforms and Southeast Asian fintechs are migrating transaction scoring workloads here to eliminate data center overhead.
- Hybrid Cloud:Sensitive training data remains on-premises while inference executes at cloud edge nodes. Japanese manufacturers and Australian banks are adopting this architecture to satisfy data residency mandates without sacrificing latency performance.
- Private Cloud:Dedicated single-tenant infrastructure with custom security boundaries. Singaporean government agencies and Chinese state-owned enterprises procure through certified domestic providers under MIIT licensing requirements.
- On-Premises:Fully captive GPU clusters with managed software layers. South Korean defense contractors and select Indian public sector banks maintain this deployment for air-gapped operational requirements.
Public cloud dominates installed base. Hybrid cloud is where expansion concentrates.
Service Type:
Cost tiering separates outcome-based predictive analytics from commodity API access, with model training occupying the premium tier due to scarce GPU cluster availability.
- Predictive Analytics:End-to-end fraud detection and demand forecasting solutions with SLA-guaranteed accuracy thresholds. Financial institutions across Mumbai, Bangkok, and Sydney pay premium subscriptions for outcome-based pricing tied to detected transaction anomalies.
- Model Training:Managed GPU cluster orchestration for custom foundation model development. Japanese automotive manufacturers and Chinese cloud gaming platforms consume H100-hour blocks through reservation contracts with 6-9 month lead times.
- Data Processing:Feature engineering pipelines and annotation services for raw data preparation. Indonesian e-commerce marketplaces leverage these services to structure unstructured product catalogs for recommendation engines.
- API Access:Raw inference endpoints priced per thousand calls. Vietnamese startup ecosystems and Philippine BPO operations access computer vision and NLP capabilities without pipeline management overhead.
Predictive analytics commands margin premiums. API access is gaining share fastest among price-sensitive mid-market buyers.
End User:
Application intensity varies sharply, with financial institutions driving inference volume while healthcare remains constrained by diagnostic liability frameworks.
- Financial Institutions:Real-time credit scoring, anti-money laundering, and algorithmic trading surveillance. India's non-banking financial companies and Singaporean digital banks are expanding fastest as RBI and MAS guidelines clarify AI governance requirements.
- Healthcare Providers:Medical imaging analysis and clinical decision support systems. Australian diagnostic networks and Japanese hospital groups are piloting computer vision APIs under TGA and PMDA sandbox frameworks.
- Retail Businesses:Demand forecasting, dynamic pricing, and inventory optimization. Southeast Asian marketplace platforms in Jakarta and Ho Chi Minh City deploy recommendation engines to reduce return rates and improve conversion.
- Telecommunications:Network anomaly detection and customer churn prediction. South Korean and Australian carriers use predictive models to optimize 5G infrastructure deployment and retention spending.
Financial institutions anchor current revenue. Healthcare providers represent the steepest expansion trajectory as regulatory sandboxes mature.
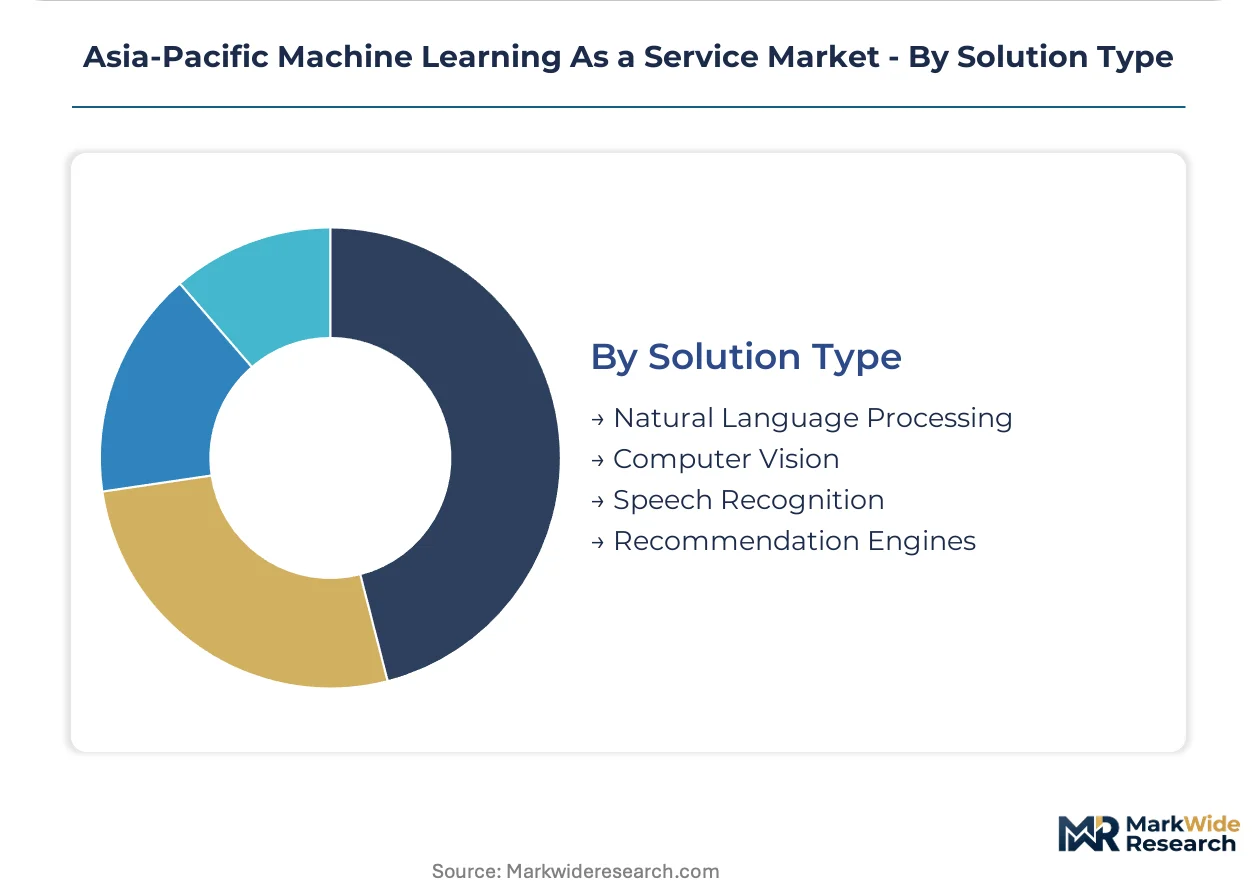
Solution Type:
Maturity curves separate established computer vision deployments from emerging speech recognition applications in multilingual Asian markets.
- Computer Vision:Facial recognition, defect detection, and satellite imagery analysis. Chinese smart city contracts and Australian mining operations drive volume, with accuracy thresholds exceeding 99.5% for surveillance and safety-critical applications.
- Natural Language Processing:Multilingual sentiment analysis, document extraction, and conversational agents. Indian BFSI and Philippine customer service outsourcers deploy mixed-language models for Hindi-English and Tagalog-English code-switching environments.
- Recommendation Engines:Collaborative filtering and content-based matching for e-commerce and streaming platforms. Indonesian and Vietnamese marketplaces are the primary demand centers as digital commerce penetration deepens.
- Speech Recognition:Real-time transcription and voice biometric authentication. Japanese call centers and South Korean smart device manufacturers are early adopters, with accuracy challenges remaining for tonal languages across Southeast Asia.
Computer vision dominates installed base. Speech recognition is climbing the fastest as edge deployment reduces latency for real-time applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT cloud licensing regime and India's MeitY data governance framework are fragmenting infrastructure deployment across the Asia-Pacific, forcing providers to architect country-specific stacks rather than unified regional platforms.
China
Domestic cloud providers anchor government and fintech workloads through MIIT-licensed data centers in Beijing and Shanghai. The ministry's data localization mandates prevent cross-border model training, compelling foreign entrants to rebuild infrastructure domestically. Alibaba Cloud leverages its mainland footprint to capture smart city contracts where facial recognition accuracy thresholds exceed 99.5 percent.
India
Non-banking financial companies in Mumbai and Delhi are migrating from on-premises GPU clusters to managed ML pipelines, accelerating subscription revenue for inference-as-a-service offerings. RBI guidelines clarify AI governance requirements, reducing enterprise procurement cycles. Bangalore anchors delivery velocity for regional expansion, though MLOps engineering scarcity constrains pipeline orchestration expertise.
Japan
Automotive manufacturers in Nagoya and Osaka source foundation model development from domestic specialists while routing production inference through cloud regions. METI AI governance guidelines create procurement clarity that expands addressable spend among risk-averse manufacturers. Hybrid cloud configurations satisfy data residency mandates without sacrificing latency performance for real-time defect detection.
Australia
Diagnostic networks in Sydney and Melbourne pilot computer vision APIs under TGA sandbox frameworks, representing the steepest expansion trajectory as regulatory environments mature. Emerging algorithmic accountability rules will drive demand for audit-trail-enabled platforms among financial services and healthcare buyers. Legacy core banking integration challenges inflate implementation costs for mainframe transaction systems.
Singapore
Fintechs deploy containerized inference nodes within domestic exchange facilities, compressing latency to sub-50 milliseconds for fraud scoring. MAS guidelines clarify AI governance for digital banks, accelerating procurement of predictive analytics with SLA-guaranteed accuracy thresholds. The city-state concentrates MLOps engineering expertise, constraining delivery velocity for regional expansion into underpenetrated Southeast Asian markets.
Asia-Pacific Machine Learning As a Service Market Competitive Landscape
Player mix skews toward hyperscale cloud providers with domestic data center footprints, creating a tiered structure where certification credentials separate enterprise-ready vendors from regional challengers. ISO 27001 attestation functions as a hard gate for financial institution procurement, entrenching incumbents with existing audit trails. Two strategic archetypes dominate: domestic champions leveraging regulatory compliance and multinational platforms integrating foundation model APIs. Competitive moves concentrate on geographic expansion through certified local partnerships and portfolio diversification into edge inference nodes.
Within the hyperscaler tier, Alibaba Cloud and Microsoft exemplify divergent positioning strategies. Alibaba anchors government and fintech workloads across mainland China through MIIT-licensed infrastructure. Microsoft sustains premium positioning among multinational subsidiaries through Azure OpenAI integrations. SenseTime occupies a specialist position in computer vision APIs, dominating smart city and surveillance contracts where accuracy thresholds exceed generic alternatives. These three represent how certification, geographic footprint, and vertical specialization fragment competitive positioning across national boundaries.
| Leading Market Players |
|---|
| Alibaba Cloud |
| Baidu |
| Amazon Web Services |
| Microsoft |
| IBM |
| Huawei |
| SenseTime |
| Tencent Cloud |
| Others |
Value Network & Pricing Analysis
GPU cluster utilization rates at Taiwan Semiconductor Manufacturing anchor cost structures across the Asia-Pacific MLaaS landscape, concentrating supply-side leverage among hyperscalers with advance wafer allocations while compressing margin floors for second-tier providers competing on inference pricing alone.
Pricing Analysis
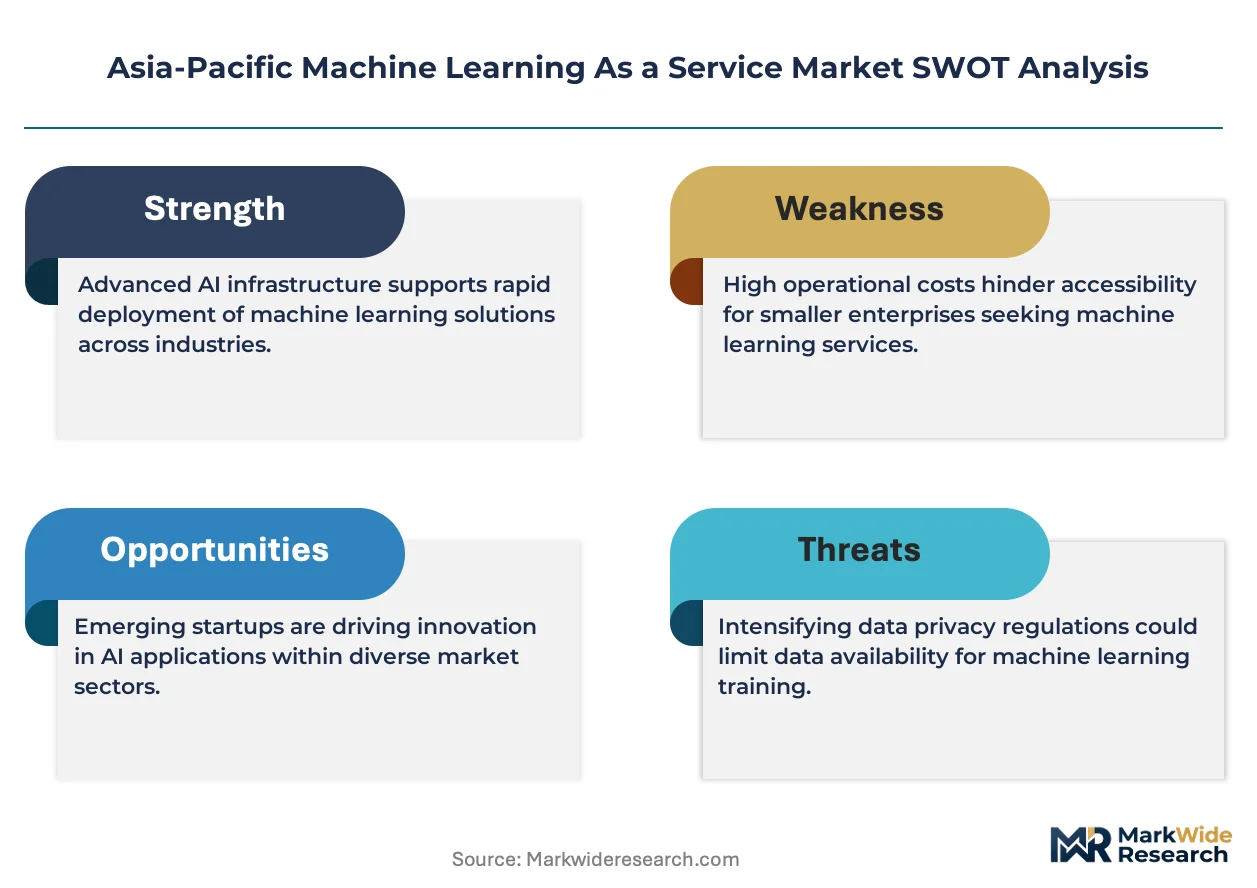
Certification level creates the primary spread between enterprise-ready and challenger tiers, with ISO 27001 attestation commanding subscription premiums from Mumbai financial institutions and Singaporean government agencies. Three-tier pricing structure separates audit-trail-enabled predictive analytics from raw API access and self-managed training clusters, with outcome-based fraud detection subscriptions carrying the highest margins. Pricing pressure stems from open-source Kubernetes pipelines displacing commercial API contracts among Indian e-commerce platforms with internal data science teams. Mid-market buyers in Vietnam and Indonesia exhibit greatest price sensitivity, while Australian banks and Japanese manufacturers prioritize compliance tooling over per-call economics.
Supply Chain Analysis
Six-to-nine month lead times for NVIDIA H100 clusters concentrate supply risk at the Taiwan-South Korea-USA nexus, where foundry capacity constraints propagate through cloud provider reservation queues. Infrastructure hardware draws from TSMC advanced packaging, Samsung HBM memory, and domestic Chinese GPU alternatives under MIIT localization mandates. Single-source vulnerability in Taiwan semiconductor fabrication exposes provisioning timelines to geopolitical disruption. Distribution runs through hyperscaler direct sales for public cloud workloads and certified systems integrators for hybrid configurations subject to data residency requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed MLOps services and compliance-as-a-service layers are expanding faster than raw compute provisioning, creating attach-rate opportunities for providers bundling pipeline orchestration with inference capacity.
For Market Incumbents: Fortify certification moats by accelerating ISO 27001 audit cycles and embedding immutable consent logging for India's MeitY credit-scoring mandates. Expand edge node footprints within domestic exchange facilities to compress latency below 50 milliseconds for Southeast Asian payment networks. Defend against open-source substitution by integrating feature store management and auto-scaling orchestration into subscription tiers that internal Kubernetes deployments cannot replicate without scarce engineering talent. For New Entrants and Emerging Players: Federated learning infrastructure gaps in cross-border financial services present first-mover openings where incumbents lack privacy-preserving training architectures. Target Vietnamese and Indonesian e-commerce platforms with computer vision APIs for fraud detection, where mature infrastructure remains underdeveloped. Lead with MLOps engineering services rather than raw compute to bypass GPU procurement queues that entrench hyperscale incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized computer vision providers with government certification credentials over undifferentiated infrastructure plays. Long-term viability hinges on regulatory compliance tooling that deepens customer switching costs as algorithmic accountability frameworks mature across Australia and Singapore. Watch for MIIT licensing expansions that force foreign hyperscalers into domestic joint ventures, signaling consolidation windows for certified local operators.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Platform Development | Privacy-preserving training unlocks multi-party contracts across China's data localization boundaries. |
| Edge Inference Node Deployment | Containerized metro-edge installations compress fraud-scoring latency for Singaporean fintechs. |
| ISO 27001 Certification Acceleration | Audit-trail attestation gates procurement from RBI-regulated non-banking financial companies. |
| Compliance-as-a-Service Integration | Native MeitY consent logging differentiates offerings from raw API competitors in Mumbai. |
| Specialist Computer Vision Acquisition | Smart city contracts demand accuracy thresholds exceeding generic hyperscaler alternatives. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud platform engineers, MLOps specialists, regulatory compliance officers at financial institutions, and procurement leads at Southeast Asian e-commerce platforms; and secondary validation through MIIT licensing disclosures, RBI circulars on AI governance, hyperscaler capex filings, and trade data on GPU cluster imports. Bottom-up triangulation against top-down market sizing ensured segmentation integrity across deployment models and service types.
Across the analysis window, the forecasting framework modeled deployment model splits, service type tiering, end-user vertical intensity, and solution type maturity curves. CAGRs derived from GPU cluster provisioning trajectories, cloud migration velocity in India's BFSI sector, and regulatory sandbox expansion timelines in Australian healthcare. Inference volume projections incorporated edge node distribution patterns and federated learning adoption curves.
Underlying assumptions cover sustained Taiwan semiconductor fabrication capacity, stable data localization enforcement across China and India, and gradual algorithmic accountability rule emergence in Australia and Singapore, with deviation risk concentrated in export control expansions affecting H100 availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Machine Learning Operation Technology Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Machine Learning (ML) Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Europe Machine Learning As a Service Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
Automated Machine Learning Market
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Semantic Knowledge Graphing Market
Machine Learning and Data Science
Artificial Intelligence and Advanced Machine Learning Market