
 Robotics for NDT Market | 2026-2036
Robotics for NDT Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics for NDT Market Insights
Software-defined inspection planning is realigning how NDT robotics vendors monetize hardware deployments. DEKRA SE leverages its certification authority to bundle analytics subscriptions with robotic system leases. Waygate Technologies anchors its growth on remote-operated ultrasonic platforms that integrate cloud-based defect classification. MISTRAS Group competes through specialized robotic crawlers designed for refinery turnaround schedules.
Robotics for NDT encompasses autonomous and teleoperated machines that deploy non-destructive testing payloads—ultrasonic transducers, eddy current probes, thermal cameras, or laser scanners—to assess material integrity without specimen destruction. These systems typically operate at temperatures from minus twenty to plus three hundred fifty degrees Celsius and traverse surfaces via magnetic adhesion, tracks, or aerial propulsion to detect cracks, corrosion, or wall-thinning in inaccessible structures. Inspection drones dominate product-type revenue as offshore wind and flare stack applications multiply. Ultrasonic testing leads technology adoption for subsea pipeline and pressure-vessel work, while eddy current systems penetrate aerospace fastener and turbine-blade inspection where conductivity differentials reveal fatigue cracks. Maintenance inspection commands the largest application share because operators schedule robotic interventions during planned outages to minimize downtime.
OSHA process safety management rules and API 510/570 inspection codes in the United States compel facility operators to document repeatable, traceable examination records that robotic NDT systems generate automatically. The EU Machinery Directive and ATEX certification requirements constrain robot design for explosive atmospheres, creating compliance barriers for uncertified entrants. Stakeholders must weigh capital intensity against labor arbitrage as skilled NDT technician shortages persist across heavy industry.
Market Dynamics
Software-defined inspection planning is compressing hardware margins and forcing vendors toward recurring-revenue models anchored on analytics subscriptions and certification bundling.
Growth Catalysts
- OSHA Process Safety Management rules:US facility operators must document repeatable, traceable examination records that robotic NDT systems generate automatically. This compliance pull accelerates crawler deployment in refineries and chemical plants.
- Offshore wind expansion:European operators deploy inspection drones for turbine blade and flare stack assessment where rope access technicians face safety constraints and weather windows.
- Magnetic adhesion robotics:Crawlers traverse storage tank walls and ship hulls without scaffolding, cutting inspection downtime from weeks to days in petrochemical clusters.
Market Restraints
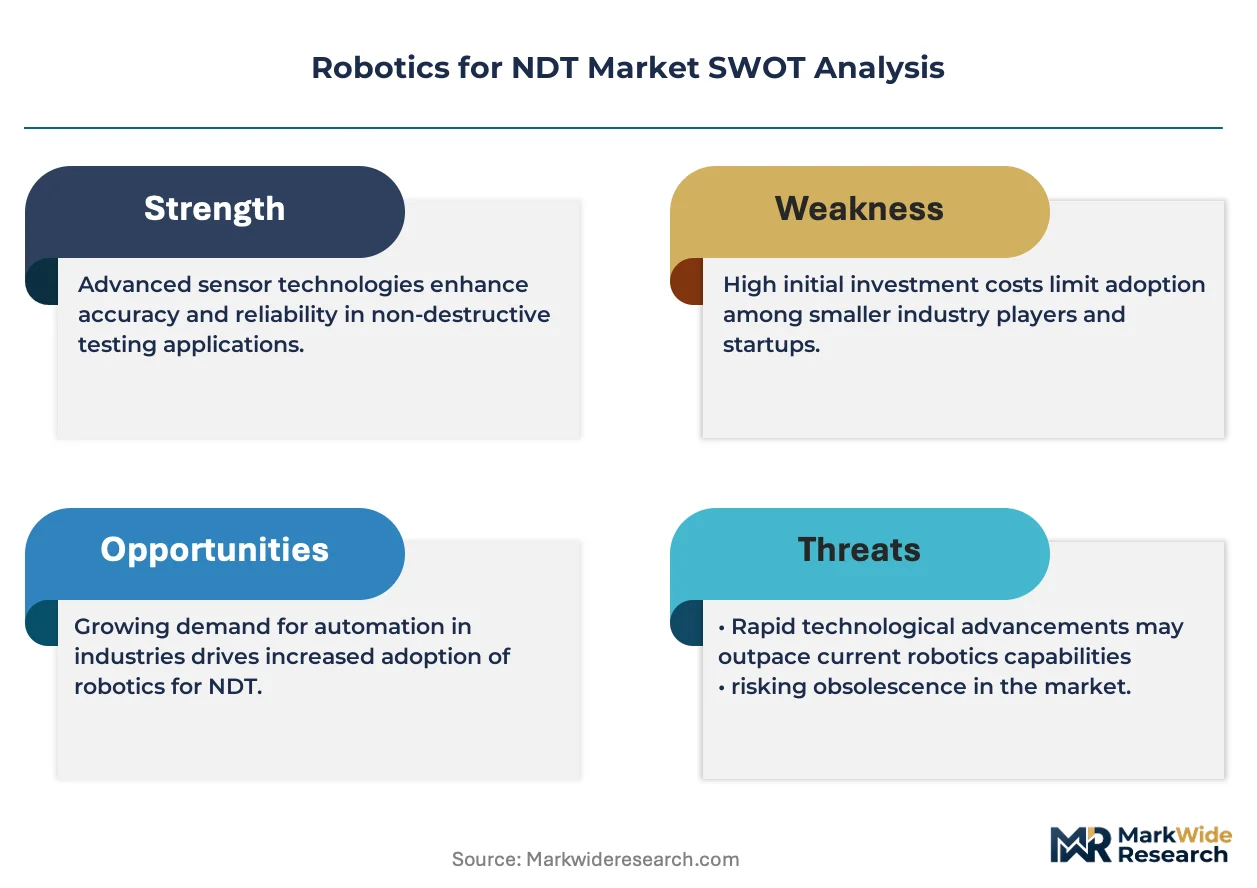
- ATEX certification barriers:EU Machinery Directive and explosive atmosphere standards constrain robot design, creating compliance friction for uncertified entrants targeting North Sea platforms.
- Skilled technician scarcity:Heavy industry faces persistent shortages of NDT-certified engineers capable of programming complex robotic trajectories and interpreting multi-modal sensor data.
- High capital intensity:Magnetic crawler systems with integrated phased-array ultrasonic payloads require six-figure investments that small inspection contractors cannot absorb without lease financing.
Strategic Opportunities
- Subsea pipeline robotics:Norway's offshore infrastructure requires autonomous inspection vehicles capable of operating at kilometer depths where tethered systems fail.
- Cloud-based defect classification:Integration of edge-computing crawlers with centralized analytics platforms enables predictive maintenance models that inspection firms monetize as subscriptions.
- India's petrochemical buildout:Reliance Industries and public-sector refiners are commissioning robotic inspection capabilities for new crackers and aromatic complexes.
Industry Challenges
- Multi-sensor calibration complexity:Operators struggle to synchronize ultrasonic, eddy current, and thermal payloads on single robotic platforms without cross-interference degrading data quality.
- Legacy system integration:Plant historians and maintenance management databases often lack APIs that robotic inspection data streams require, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotics for NDT Market |
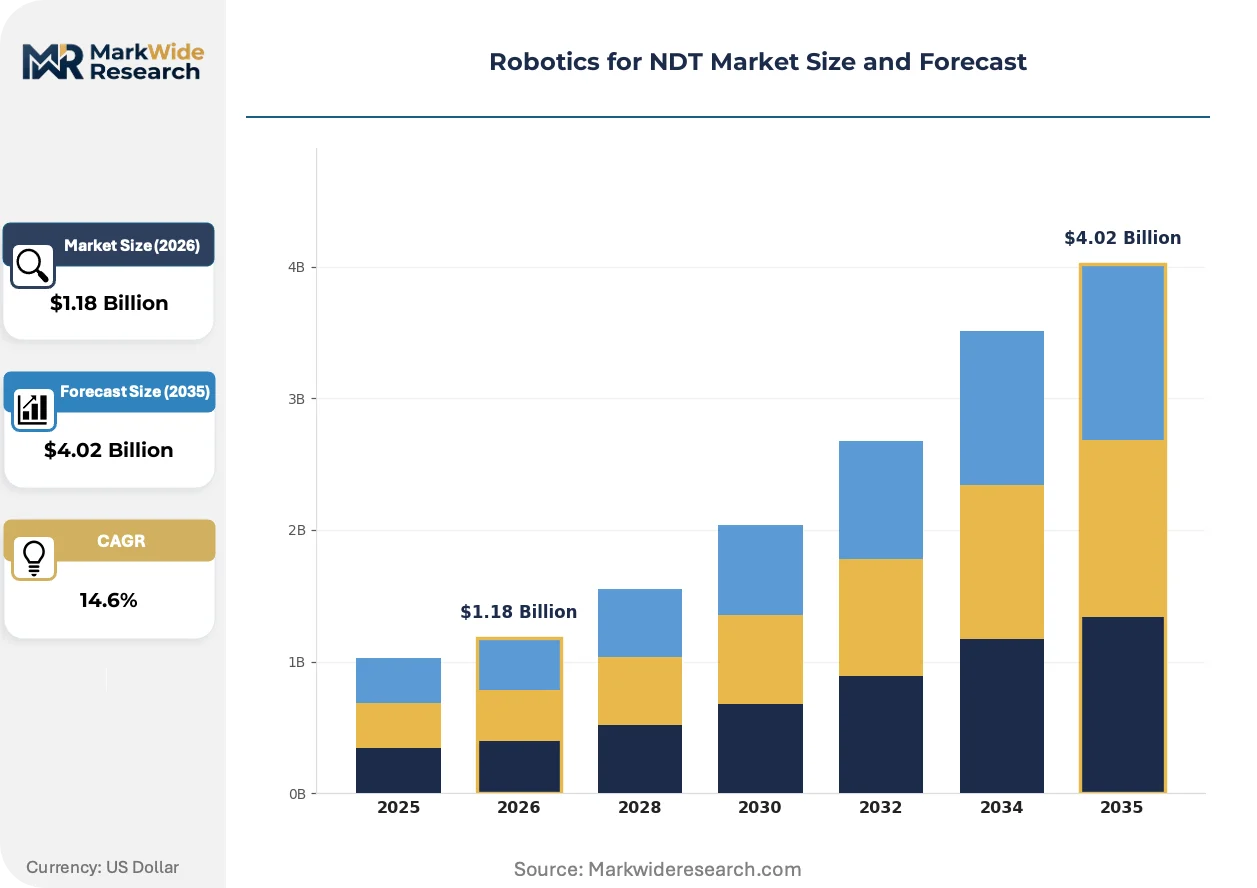
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $4.02 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inspection Drones, Robotic Arms, Automated Vehicles, Scanning Systems End User: Aerospace, Manufacturing, Oil & Gas, Power Generation Technology: Ultrasonic Testing, Eddy Current, Thermal Imaging, Laser Scanning Application: Structural Analysis, Maintenance Inspection, Quality Control, Safety Compliance |
| Companies Covered | DEKRA SE, MISTRAS Group, Waygate Technologies, Ashtead Technology, Olympus Corporation, Zetec Inc., Intertek Group plc, Applus Services S.A., Eddyfi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics for NDT Market Trends and Innovations
Remote operation architectures and AI-augmented defect recognition are displacing on-site technician presence and compressing inspection cycle times across hazardous environments.
Phased-array ultrasonic testing is consolidating around robotic deployment platforms that automate beam steering and focal law calculations. Refinery operators in the US Gulf Coast and Rotterdam-Antwerp corridor adopt these systems for pressure-vessel and piping inspections during scheduled turnarounds. The technology is consolidating vendor offerings around integrated hardware-software bundles that reduce procurement complexity.
EU Machinery Directive updates and ATEX certification requirements are tightening safety standards for robots operating in explosive atmospheres. German TÜV operators now mandate third-party validation of autonomous navigation algorithms before certifying systems for refinery deployment. Offshore wind inspection drones face heightened electromagnetic compatibility testing under these frameworks.
Asset operators increasingly unbundle inspection services from equipment ownership, preferring per-meter or per-finding pricing over capital purchases. This consumption-pattern shift favors robotics-as-a-service providers with certified technician networks. The model concentrates in North Sea oil platforms and German chemical parks where balance-sheet constraints and skills gaps coincide.
Robotics for NDT Market Segmentation
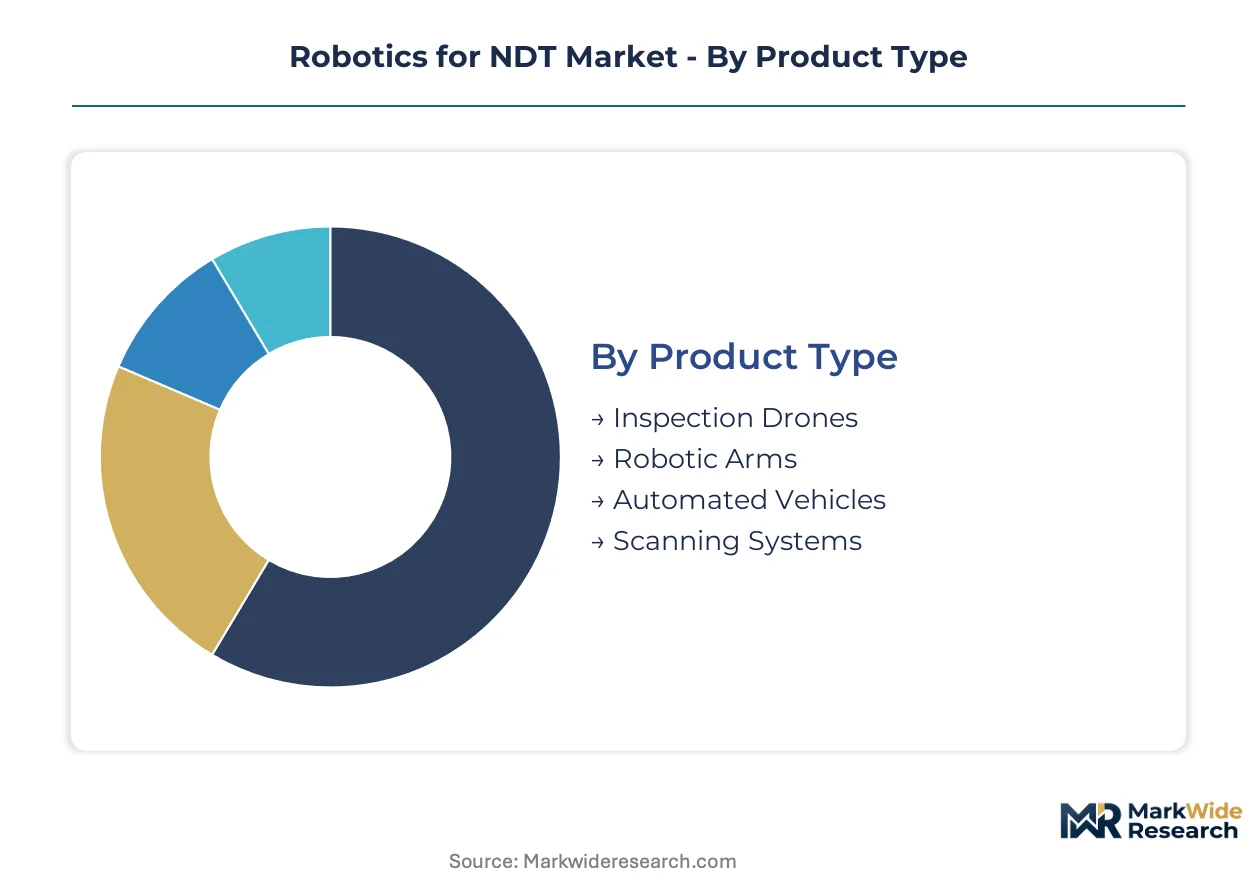
Segmentation in robotics for NDT reveals how inspection buyers prioritize mobility, payload precision, and environmental resilience differently across hazardous infrastructure. Procurement patterns diverge sharply between asset owners seeking autonomous turnaround solutions and regulators mandating traceable documentation protocols.
Product Type:
Buyers differentiate primarily by access geometry and surface adhesion requirements rather than sensor capability alone.
- Inspection Drones:Aerial platforms carry ultrasonic transducers and thermal cameras to flare stacks, wind turbine blades, and elevated piping where rope access poses fatality risks. European offshore wind operators in the North Sea and German chemical parks deploy these systems to compress inspection windows from weeks to days.
- Robotic Arms:Articulated manipulators with six-plus degrees of freedom position eddy current probes against complex geometries in aerospace fastener inspection and turbine blade root examination. Aerospace manufacturers in Toulouse and Hamburg anchor demand for sub-millimeter positioning repeatability.
- Automated Vehicles:Ground-based platforms traverse refinery roadways and tank farm perimeters carrying phased-array ultrasonic payloads for pipeline corridor surveys.
- Scanning Systems:Rail-mounted or gantry-fixed configurations perform volumetric mapping of pressure vessels and storage tanks during scheduled outages.
Volume sits with inspection drones; growth tilts toward robotic arms.
End User:
Capital intensity and regulatory exposure shape procurement sophistication across verticals.
- Oil & Gas:Pipeline operators and refinery asset managers deploy magnetic adhesion crawlers and subsea autonomous vehicles to satisfy API 510/570 inspection codes. OSHA process safety management rules in the US Gulf Coast and Rotterdam-Antwerp corridor compel automated documentation systems that manual methods cannot replicate.
- Aerospace:OEMs and MRO facilities require eddy current and ultrasonic robotic platforms for turbine blade fatigue detection and fastener hole inspection where conductivity differentials reveal crack initiation. Certification authorities EASA and FAA mandate traceable NDT records that robotic systems generate automatically.
- Power Generation:Nuclear and combined-cycle plant operators schedule robotic interventions during refueling outages to minimize capacity factor losses.
- Manufacturing:Automotive and heavy equipment producers integrate inline robotic inspection for weld quality verification and casting defect detection.
Procurement sophistication concentrates in oil and gas; aerospace represents the steepest expansion trajectory.
Technology:
Physics of defect detection and material properties dictate payload selection.
- Ultrasonic Testing:Phased-array and time-of-flight diffraction systems dominate subsea pipeline and pressure-vessel inspection where volumetric wall-thinning assessment is critical. Beam steering automation via robotic platforms eliminates manual transducer manipulation errors.
- Eddy Current:Conductivity-based crack detection penetrates aerospace fastener inspection and heat exchanger tube assessment where ferromagnetic interference is absent.
- Thermal Imaging:Infrared cameras mounted on drones and crawlers identify insulation degradation and refractory lining failures in fired heaters and flare systems.
- Laser Scanning:Structured light and LiDAR payloads generate high-fidelity geometric models for corrosion mapping and deformation monitoring in storage tanks and ship hulls.
Ultrasonic testing commands current deployment scale; eddy current systems are gaining share fastest in aerospace certification programs.
Application:
Timing of inspection relative to asset operation determines robot specification and commercial model.
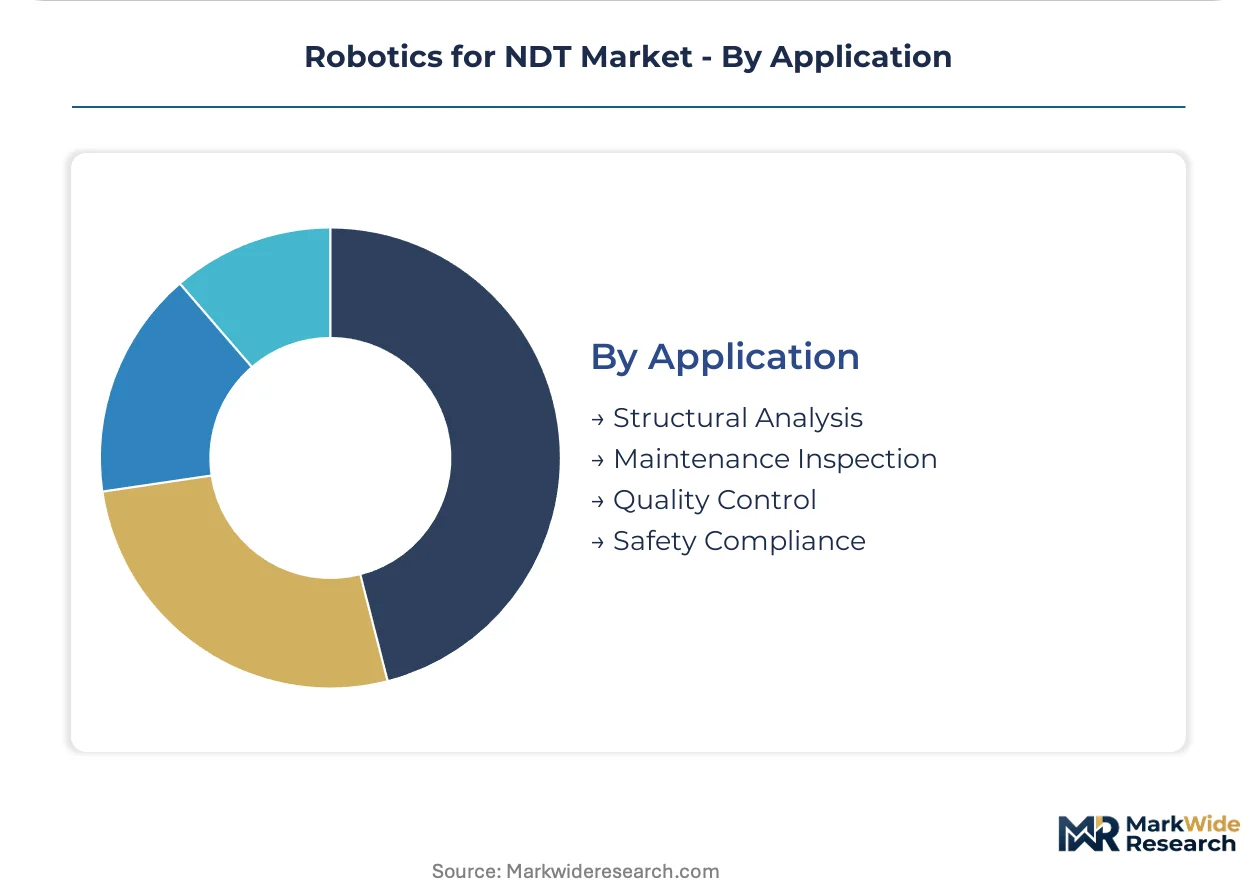
- Maintenance Inspection:Scheduled turnaround and outage work drives the largest equipment deployment as operators minimize production losses. Refinery and chemical plant owners in Germany's Ruhr Valley and US Texas Gulf Coast lease robotic systems with certified technician crews.
- Safety Compliance:Regulatory-mandated examination protocols under OSHA, EU Machinery Directive, and ATEX standards require repeatable, traceable records that robotic NDT generates automatically. Compliance pull accelerates crawler adoption ahead of regulatory deadlines.
- Structural Analysis:Engineering assessment of bridges, offshore platforms, and storage tanks employs drones and magnetic crawlers for geometric surveying and defect localization.
- Quality Control:Manufacturing inline inspection deploys robotic arms and scanning systems for weld verification and dimensional conformance.
Maintenance inspection absorbs the majority of current equipment hours; safety compliance applications are climbing the fastest as regulatory deadlines tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of robotic NDT systems concentrates in Germany and the United States, while consumption spreads across petrochemical clusters in the Gulf Coast, Rotterdam-Antwerp corridor, and emerging Asian refining centers.
United States
OSHA process safety management rules and API 510/570 inspection codes compel Gulf Coast refiners to deploy magnetic adhesion crawlers and phased-array ultrasonic platforms. The Texas-Louisiana petrochemical corridor accounts for concentrated crawler leasing activity during scheduled turnarounds. Houston-based inspection contractors bundle certified technician crews with robotic system rentals to satisfy documentation mandates.
Germany
DEKRA SE and TÜV operators drive certified robotic inspection adoption across the Ruhr Valley petrochemical cluster. EU Machinery Directive and ATEX certification requirements constrain robot design for explosive atmospheres, creating compliance barriers for uncertified entrants. Bavarian and North Rhine-Westphalia chemical parks deploy inspection drones for flare stack assessment where rope access faces weather window constraints.
Norway
Subsea pipeline operators require autonomous inspection vehicles capable of operating at kilometer depths where tethered systems fail. The country's offshore regulator mandates traceable examination records for aging North Sea infrastructure. Stavanger and Bergen anchor concentrated demand for subsea robotic platforms serving Equinor and international oil company assets.
China
State-owned refiners and emerging private petrochemical complexes commission robotic inspection capabilities for new crackers and aromatic complexes. GB standards and MIIT directives shape equipment certification requirements for explosive atmosphere deployment. The Yangtze River Delta and Shandong Peninsula concentrate demand as Sinopec and private operators expand capacity.
India
Reliance Industries and public-sector refiners build robotic inspection capabilities for Jamnagar and new greenfield complexes. The country's national industrial regulator pushes traceable documentation protocols that manual methods struggle to satisfy. Gujarat and Maharashtra petrochemical clusters absorb initial crawler deployments during commissioning phases.
Robotics for NDT Market Competitive Landscape
Top-tier vendors anchor certification-bundled service models, while mid-tier equipment specialists compete on payload integration and regional lease networks. The vendor base stratifies across three tiers: integrated inspection service providers with certification authority, hardware-focused robotic platform manufacturers, and regional leasing contractors with technician networks. Two dominant competitive moves are reshaping positioning: M&A activity consolidating inspection service capabilities, and strategic partnerships pairing hardware vendors with cloud analytics platforms.
Within the integrated inspection service tier, DEKRA SE and MISTRAS Group occupy positions that exemplify certification-bundled robotics deployment. Among hardware-focused platform vendors, Waygate Technologies and Eddyfi Technologies represent archetypes of sensor-integrated robotic system supply. Olympus Corporation and Zetec Inc. sit within the precision instrumentation tier that feeds payload components across multiple robotic integrators.
| Leading Market Players |
|---|
| DEKRA SE |
| MISTRAS Group |
| Waygate Technologies |
| Ashtead Technology |
| Olympus Corporation |
| Zetec Inc. |
| Intertek Group plc |
| Applus Services S.A. |
| Eddyfi Technologies |
| Others |
Pricing and Supply Chain Analysis
Certified NDT technician concentrations in Germany's Ruhr Valley and Houston's petrochemical corridor feed directly into pricing-tier spreads, with labor-cost differentials separating premium analytics-bundled leases from bare-equipment rentals in emerging markets.
Pricing Analysis
Margin tightening in mid-tier robotic crawler leases reflects software-defined inspection bundling by DEKRA SE and MISTRAS Group. Three-tier pricing structure across premium certification-bundled, standard lease-with-technician, and economy bare-equipment rentals separates buyers by compliance urgency. Price differentiation hinges on ATEX certification grade and volume-scale commitment. Cost-down pressure on economy tiers accelerates because Indian and Chinese inspection contractors prioritize capital avoidance over feature depth. Small regional contractors exhibit highest price sensitivity; integrated oil majors show least.
Supply Chain Analysis
Freight costs for magnetic adhesion crawler systems from Germany to Southeast Asian petrochemical clusters add fifteen to twenty percent to landed equipment costs, compressing distributor margins. Component manufacturing concentrates in Germany, the United States, and Japan. Phased-array ultrasonic transducers, high-temperature servo motors, and explosion-proof sensor housings constitute critical input dependencies. Single-source vulnerability sits with specialized magnetic wheel assemblies from Bavarian precision engineering suppliers. Distribution runs through certified inspection service providers with captive technician networks rather than open equipment resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotics for NDT operates as a supply-constrained market where certified technician availability props pricing power and extends contract backlogs for integrated service providers.
For Market Incumbents: Hedge against software margin compression by deepening in-house production of phased-array ultrasonic payloads and magnetic drive systems. Acquire regional leasing contractors in India's Gujarat corridor to lock technician capacity before Reliance Industries scales internal programs. Certification investment in China's GB standards compliance represents the priority defensive lever against emerging domestic competitors. For New Entrants and Emerging Players: Begin with subsea autonomous vehicle white space in Norway's North Sea infrastructure, where kilometer-depth requirements exceed tethered system capabilities and Equinor's procurement favors specialist vendors. India's petrochemical buildout offers the most penetrable geography, with Jamnagar complex expansion creating first-mover windows ahead of state-owned refiner commissioning. Go-to-market through robotics-as-a-service subscriptions with per-finding pricing appeals to balance-sheet-constrained contractors. For Investors and Strategic Acquirers: The window for entry favors mid-tier hardware specialists with ATEX certification assets and established lease networks in the North Sea or German chemical parks. Long-term viability rests on analytics platform integration capability rather than pure equipment manufacturing. Watch cloud-based defect classification adoption rates among Rotterdam-Antwerp corridor operators as the inflection signal for recurring-revenue model maturation.| Strategic Initiative | Industry Significance |
|---|---|
| ATEX Certification Investment | EU Machinery Directive compliance unlocks refinery deployment contracts with TÜV-mandated validation requirements. |
| Cloud Analytics Platform Integration | Edge-computing crawler data feeds predictive maintenance models that inspection firms monetize as recurring subscriptions. |
| Regional Leasing Network Expansion | Certified technician crews bundled with robotic rentals satisfy OSHA documentation mandates in US Gulf Coast turnarounds. |
| Subsea Autonomous Vehicle Development | Kilometer-depth capability addresses Norway's aging North Sea infrastructure where tethered systems fail operationally. |
| Phased-Array Ultrasonic Payload Integration | Automated beam steering eliminates manual transducer manipulation errors in pressure-vessel inspection cycles. |
Research Methodology
Multi-period observation of robotic crawler deployment hours, inspection drone flight cycles, and certified technician headcounts anchored the trend analysis, supplemented by interviews with maintenance directors at Gulf Coast refineries, NDT certification body technical leads, robotics OEM product managers, and inspection contractor operations heads. Secondary validation drew from OSHA enforcement data, API standards documentation, EU Machinery Directive implementation guidance, and customs records for magnetic adhesion system imports. Bottom-up equipment shipment tracking and top-down petrochemical maintenance spending estimates provided triangulation checks.
The input-output matrix mapped robotic platform specifications against inspection application requirements across product type, end user vertical, technology payload, and geographic regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to equipment lease volumes and service contract values. Industry-specific forecast inputs included refinery turnaround schedules in the Rotterdam-Antwerp corridor and offshore wind turbine commissioning timelines in the North Sea.
Underlying measurement precision varies by segment; maintenance inspection applications carry tighter precision than emerging quality control deployments due to established procurement reporting. Forecasts reflect modeling assumptions about regulatory deadline adherence and technician training pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Harvesting Robot Market