
 Robot Charging Station Market | 2026-2036
Robot Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Charging Station Market Analytics
Skilled robotics integration engineers is rotating from automotive assembly lines into warehouse automation projects, tightening talent pools for charging station deployment. ABB Ltd leverages its industrial electrification heritage to anchor European manufacturing plant installations. WiBotic specializes in wireless power transfer systems for aerial and ground robots, occupying a defensible technology niche. ROCSYS competes on autonomous robotic arm connectors that eliminate human intervention in high-throughput logistics environments.
A robot charging station is an electromechanical system that delivers controlled electrical energy to autonomous robot batteries, typically operating at voltages from 24V to 800V with power outputs ranging from 1kW to 350kW depending on robot class and duty cycle. Its primary commercial purpose is eliminating manual battery swap labor while maximizing fleet uptime through automated energy replenishment. Fast chargers command the dominant share of current revenue in warehouse operations where downtime carries steep opportunity costs. Smart charging systems represent the fastest-expanding technology segment as fleet operators demand load balancing, predictive maintenance integration, and energy cost optimization across multiple robot platforms.
The EU AI Act, CE marking under the Machinery Directive, and IEC 62443 cybersecurity standards collectively shape product certification requirements and market access conditions for robot charging station vendors. OSHA electrical safety regulations in the United States and Japan's METI energy efficiency directives add compliance layers that influence hardware design and software architecture decisions. Stakeholders must monitor how evolving interoperability standards between charging infrastructure and robot fleet management software determine competitive positioning in multi-vendor deployments.
Market Dynamics
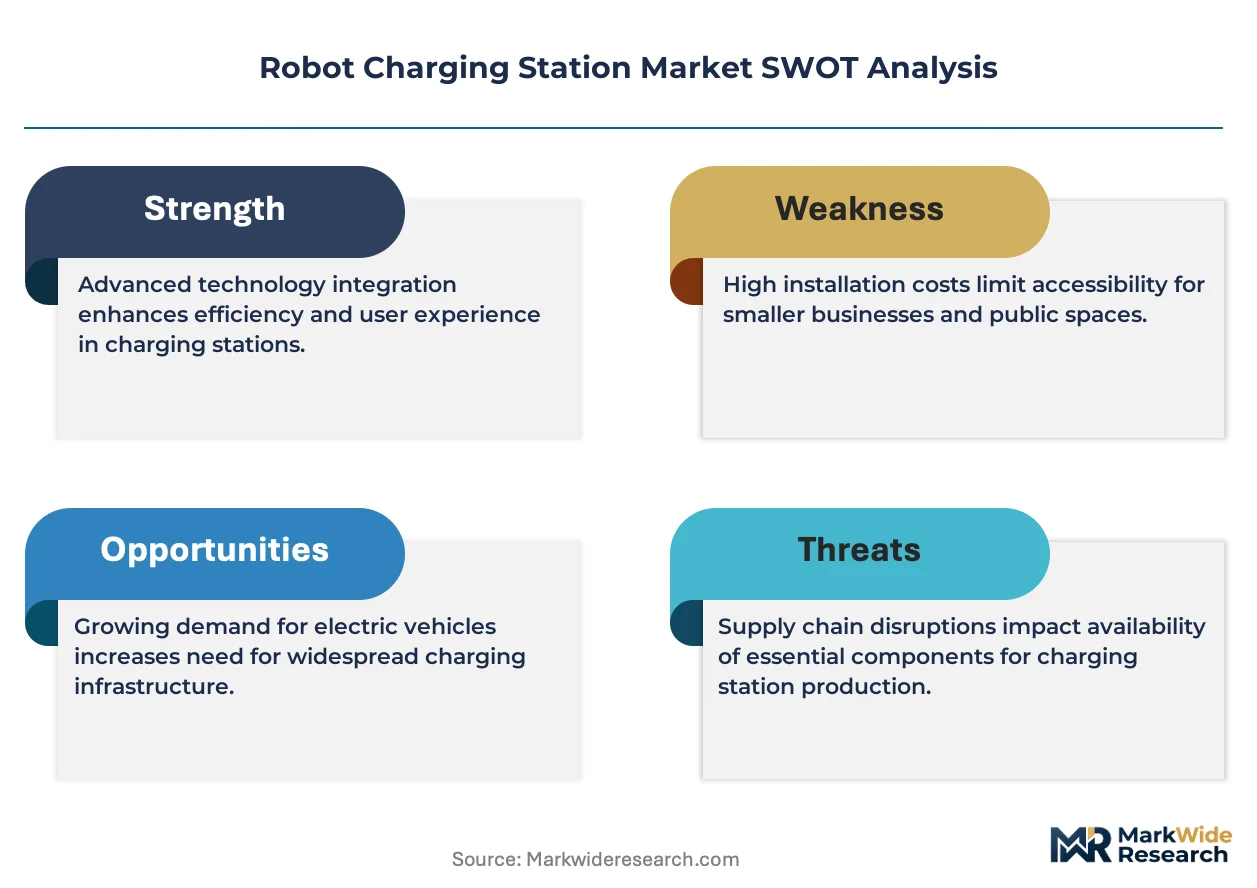
Warehouse operators are deploying autonomous mobile robot fleets faster than charging infrastructure can physically install, creating a structural bottleneck where energy replenishment capacity constrains fleet expansion rather than capital or software.
Growth Catalysts
- The EU AI Act:Mandatory conformity assessments for autonomous charging systems are accelerating vendor certification investments and filtering out non-compliant hardware suppliers from European logistics deployments.
- Automotive OEM smart factory architectures:German manufacturers are embedding robot charging into production line designs, creating specification pull-through that shapes procurement standards across supplier tiers.
- Wireless power transfer:Inductive and resonant charging systems are eliminating mechanical wear in high-cycle warehouse environments, extending hardware lifespan and reducing maintenance labor.
Market Restraints
- Copper and silicon carbide price volatility:Power electronics and cabling constitute 35-45% of bill-of-materials costs, exposing margins to commodity swings that vendors cannot fully pass through under fixed-price installation contracts.
- South Korean and Chinese battery supplier concentration:Cell chemistry standardization around Asian manufacturers creates charging protocol lock-in that constrains European and North American hardware differentiation.
- IEC 62443 cybersecurity certification timelines:Multi-stage industrial security assessments extend product launch cycles by 8-14 months, delaying revenue recognition for software-enabled charging platforms.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery production incentives are creating demand for localized charging infrastructure that matches indigenous voltage and form factor specifications.
- Convergence of fleet management software with energy management systems:Unified platforms that orchestrate robot task scheduling against real-time electricity pricing are opening recurring revenue streams beyond hardware sales.
- Third-party logistics provider channel expansion:Charging-as-a-service models are penetrating mid-market warehouse operators that lack capital budgets for owned infrastructure but require fleet automation.
Industry Challenges
- Robotics integration engineer scarcity:Talent migration from automotive assembly to warehouse automation projects is lengthening deployment timelines and inflating implementation costs for charging station integrators.
- CE marking under the Machinery Directive:Evolving safety requirements for collaborative robot environments are forcing hardware redesigns mid-certification, eroding development budget efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Charging Station Market |
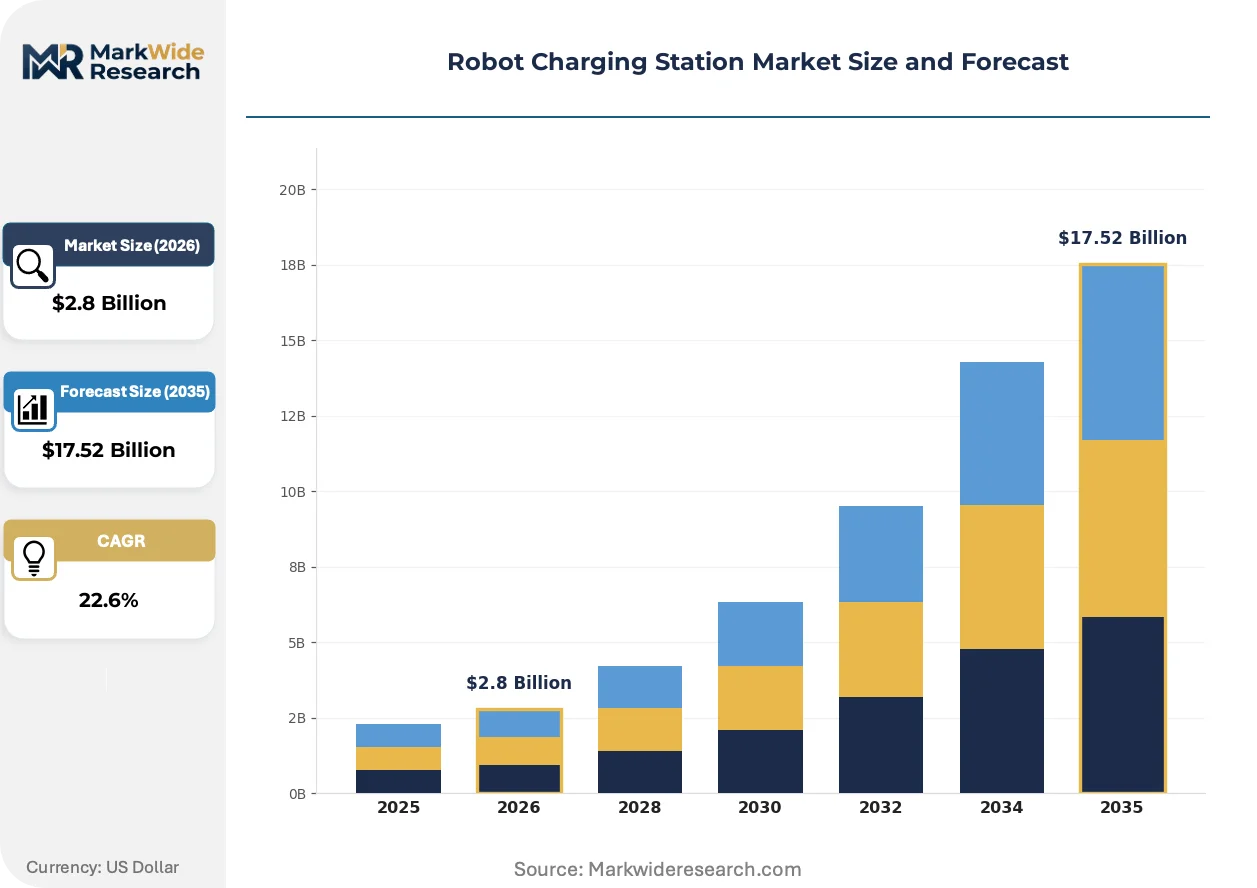
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.52 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Chargers, Standard Chargers, Inductive Chargers, Solar Chargers Technology: Wireless Charging, Autonomous Charging, Dual Charging, Smart Charging End User: Warehouse Operations, Hospitals, Retail Environments, Manufacturing Plants Installation: Indoor Setup, Outdoor Setup, Wall-Mounted, Portable Units |
| Companies Covered | Hyundai Motor Group, Volkswagen AG, ABB Ltd, Clearpath Robotics Inc., Fetch Robotics Inc., EV Safe Charge Inc., SMP Robotics Systems Corp., ROCSYS, WiBotic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Charging Station Market Evolving Landscape
Autonomous charging infrastructure is fragmenting into specialized hardware configurations as end-use verticals diverge in power requirements, duty cycles, and physical integration constraints.
Modular power converter architectures are decomposing the traditional monolithic charging cabinet into distributed, hot-swappable subsystems. Automotive OEMs in Germany and Japan are specifying these configurations for flexible manufacturing lines. This decomposition is compressing vendor margin structures by commoditizing power electronics while elevating software and integration services as value capture points.
The EU AI Act's risk classification framework for autonomous systems is mandating human oversight protocols for unsupervised charging operations. Industrial facilities must now document decision logic for connector engagement and fault recovery. High-throughput logistics centers in the Netherlands and Belgium are responding by hybridizing autonomous arms with supervised charging bays during transition periods.
Buyer preference is gravitating toward performance-guaranteed service contracts that bundle hardware, energy, and uptime commitments. Third-party logistics operators are displacing capital purchase models with operational expenditure structures that transfer utilization risk to charging vendors. This shift is most pronounced in the United States, where warehouse REITs favor off-balance-sheet arrangements that preserve borrowing capacity for core real estate.
Robot Charging Station Market Segmentation
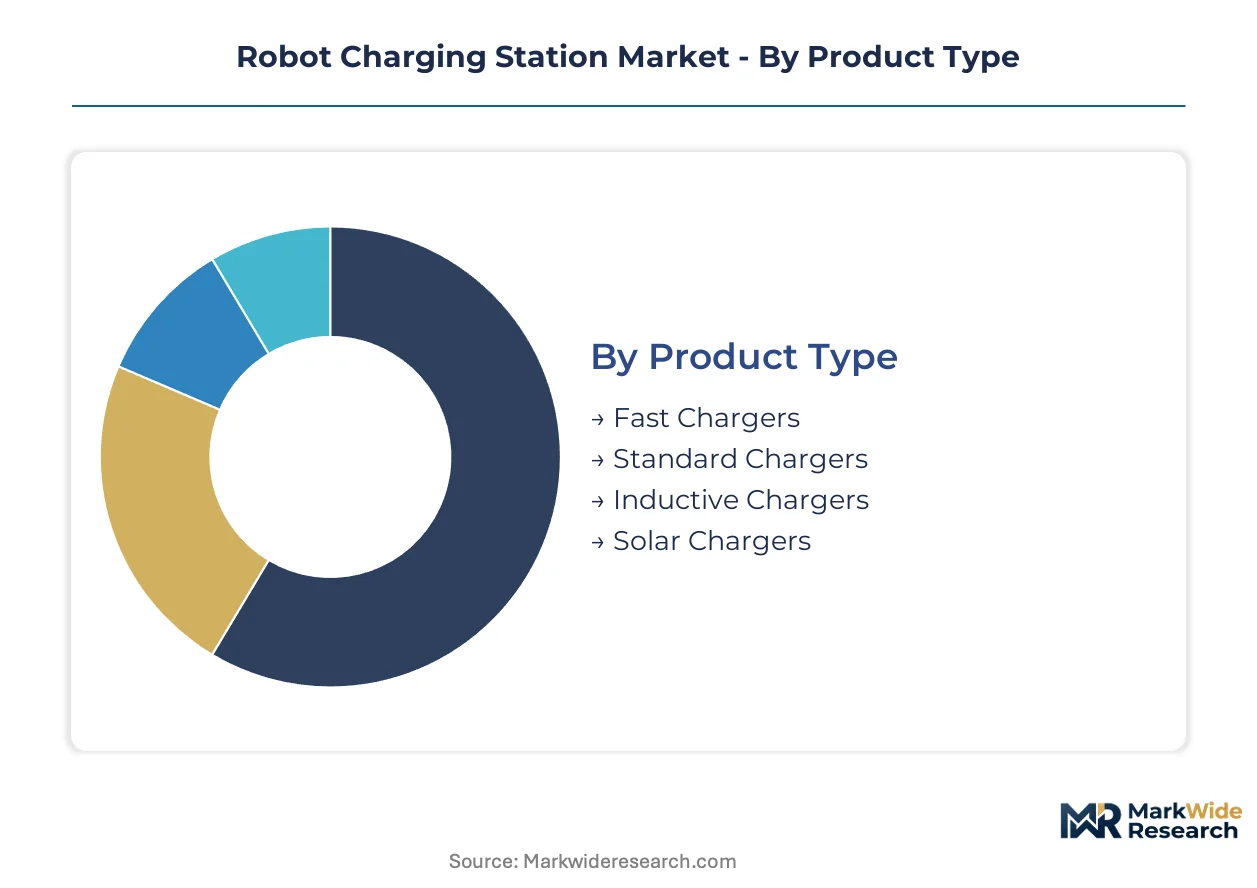
Robot charging station segmentation reveals how hardware configurations align with operational constraints across power requirements, physical environments, and fleet management complexity. Channel strategies diverge sharply between standardized fast chargers sold through industrial distributors versus engineered autonomous systems deployed through systems integrators.
Product Type:
Fast chargers and standard units flow through electrical supply distributors serving warehouse operators, while inductive and solar configurations require direct vendor engagement for site engineering.
- Fast Chargers:These systems deliver 50kW to 350kW output for high-duty-cycle autonomous mobile robots in 24/7 logistics operations. Demand concentrates in German automotive supplier parks where line-side robot fleets require sub-30-minute replenishment cycles to maintain production cadence.
- Standard Chargers:Operating at 1kW to 15kW, these units serve intermittent-duty robots in hospital corridors and retail backrooms. Procurement runs through medical equipment and commercial building supply channels rather than industrial automation distributors.
- Inductive Chargers:Coil-based systems eliminate connector wear in high-cycle environments through resonant magnetic coupling.
- Solar Chargers:Photovoltaic-integrated units serve outdoor agricultural and security robot deployments with intermittent grid access.
By volume, standard chargers lead due to broad compatibility across robot classes. By growth pace, fast chargers are climbing the fastest as warehouse fleet densities intensify.
Technology:
Cost tiering separates wireless and autonomous systems commanding premium pricing from dual and smart charging platforms competing on operational expenditure reduction.
- Wireless Charging:Inductive and capacitive power transfer eliminates mechanical alignment in dusty warehouse floors. Dutch distribution centers are specifying these systems to reduce connector maintenance labor in high-throughput environments.
- Autonomous Charging:Robotic arm connectors self-align with robot charging ports without human intervention. Japanese automotive plants are embedding these into flexible manufacturing cells where robot models change per production batch.
- Dual Charging:Simultaneous multi-robot replenishment architectures reduce infrastructure footprint in space-constrained facilities.
- Smart Charging:Load-balancing algorithms integrate with facility energy management systems to minimize electricity demand charges.
By installed base, smart charging dominates current procurement. By expansion trajectory, autonomous charging is gaining share fastest as labor costs rise in developed economies.
End User:
Application requirements fragment procurement specifications across hygiene protocols in healthcare, uptime guarantees in logistics, and cycle-time constraints in manufacturing.
- Warehouse Operations:High-throughput distribution centers demand charging infrastructure that matches AMR fleet rotation schedules. Belgian e-commerce fulfillment hubs are deploying contactless charging to eliminate connector damage from 24/7 operation cycles.
- Manufacturing Plants:Production line integration requires charging systems certified for collaborative robot environments under CE marking protocols. German OEMs are specifying charging bays with safety-rated monitored stop functions.
- Hospitals:Infection control requirements drive sealed, wipeable charging station enclosures for medical service robots.
- Retail Environments:Customer-facing deployments prioritize compact footprints and aesthetic integration with store design.
By deployment count, warehouse operations lead. By specification complexity, manufacturing plants are expanding most quickly as safety certification requirements deepen.
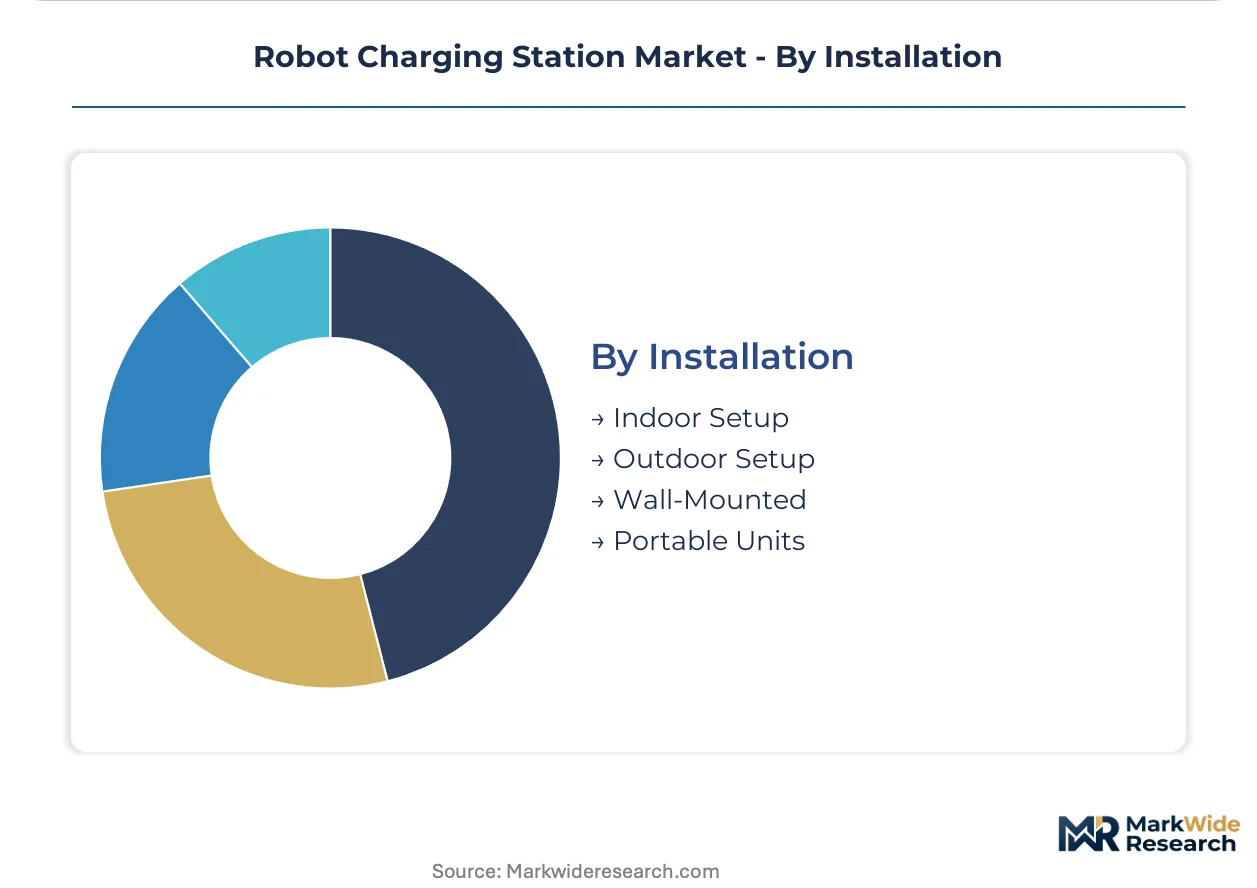
Installation:
Physical mounting configurations determine site preparation costs and relocation flexibility, with portable units commanding rental channel premiums over fixed infrastructure.
- Indoor Setup:Climate-controlled installations dominate in pharmaceutical and electronics manufacturing where temperature stability preserves battery chemistry. These configurations require HVAC-integrated ventilation for high-power charging cabinets.
- Wall-Mounted:Vertical installations maximize floor space in narrow warehouse aisles and hospital corridors. US third-party logistics providers favor these for rapid deployment in leased facilities with minimal structural modification.
- Outdoor Setup:Weatherproof enclosures with IP65+ ratings serve construction and agricultural robot fleets.
- Portable Units:Mobile charging trailers support temporary deployments and disaster response robot teams.
By shipment volume, indoor setups dominate. By margin structure, portable units command the steepest premium due to integrated power conditioning and mobility subsystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European demand for certified autonomous charging systems, while manufacturing automation in Asia-Pacific and North America drives parallel infrastructure buildouts. Warehouse operators in Germany, Japan, and the United States currently deploy the highest densities of robot charging stations.
Germany
Automotive OEM smart factory architectures specify charging infrastructure for flexible production lines. CE marking under the Machinery Directive and EU AI Act conformity assessments filter hardware suppliers for collaborative robot environments. Stuttgart and Wolfsburg clusters embed autonomous charging bays with safety-rated monitored stop functions.
United States
Third-party logistics providers favor charging-as-a-service models to preserve capital budgets. OSHA electrical safety regulations shape enclosure designs and fault protection architectures. Chicago and Dallas-Fort Worth distribution hubs deploy wall-mounted units for rapid installation in leased facilities.
Japan
METI energy efficiency directives influence load-balancing software requirements for industrial charging platforms. Automotive plants in Nagoya and Toyota City integrate robotic arm connectors for flexible manufacturing cells. Domestic vendors supply precision alignment systems for high-mix production environments.
China
MIIT standards for industrial automation equipment accelerate domestic certification timelines for charging hardware. Yangtze River Delta electronics manufacturers deploy high-power fast chargers for 24/7 AMR fleets. Shenzhen and Shanghai clusters concentrate systems integrators with robotics deployment expertise.
Netherlands
Belgian and Dutch distribution centers specify contactless charging to eliminate connector damage from continuous operation cycles. ECHA chemical safety regulations affect enclosure material selection for warehouse deployments. Rotterdam and Eindhoven logistics hubs pilot inductive systems for high-throughput e-commerce fulfillment.
Robot Charging Station Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with industrial electrification heritage separating premium-positioned vendors from commodity hardware suppliers. The upper tier commands specification influence through direct OEM relationships, while mid-tier players compete on installation speed and regional service density. Strategic archetypes include wireless power transfer specialists, autonomous connector developers, and industrial automation conglomerates with captive charging portfolios. Dominant competitive moves encompass certification pre-emption under evolving EU AI Act timelines and energy management software integration with third-party fleet platforms.
Among the named players, ABB Ltd represents the integrated industrial conglomerate archetype with electrification heritage spanning factory infrastructure. WiBotic occupies a position within the wireless power transfer specialist tier, while ROCSYS exemplifies autonomous robotic arm connector development for unsupervised logistics environments. Hyundai Motor Group and Volkswagen AG anchor automotive OEM captive demand, sourcing charging infrastructure for proprietary smart factory deployments. Clearpath Robotics Inc., Fetch Robotics Inc., and SMP Robotics Systems Corp. sit within the robotics systems integrator tier, bundling charging hardware with fleet management software. EV Safe Charge Inc. represents the North American service-model specialist, targeting operational expenditure structures for warehouse REITs.
| Leading Market Players |
|---|
| Hyundai Motor Group |
| Volkswagen AG |
| ABB Ltd |
| Clearpath Robotics Inc. |
| Fetch Robotics Inc. |
| EV Safe Charge Inc. |
| SMP Robotics Systems Corp. |
| ROCSYS |
| WiBotic |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Japanese power electronics fabs shapes margin structures across the robot charging station value chain, concentrating supply-side pricing power among integrated industrial electrification vendors while compressing price floors for commodity hardware assemblers. Fixed-price installation contracts prevent full commodity cost pass-through, forcing vendors to absorb copper and silicon carbide volatility through design standardization.
Pricing Analysis
German automotive OEMs pay 40-60% premiums over US warehouse operators for CE-marked autonomous charging systems with Machinery Directive safety ratings. Pricing stratifies across premium autonomous arms, standard fast chargers, and economy wall-mounted units, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the standard charger tier is intensifying because South Korean battery protocol standardization limits hardware interoperability premiums. Third-party logistics providers exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for sealed, wipeable enclosures.
Supply Chain Analysis
China and South Korea anchor power semiconductor and battery cell production, with Taiwan supplying precision connector components for high-alignment robotic arms. Raw material dependencies center on copper cabling, silicon carbide MOSFETs, and rare-earth magnetic materials for inductive coils. Single-source vulnerability concentrates in South Korean battery management system ICs, where two suppliers dominate protocol licensing. Distribution runs through industrial automation distributors for standardized units and systems integrators for engineered autonomous configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's mandatory conformity assessments for autonomous charging systems create a regulatory inflection that will filter non-compliant vendors from European logistics deployments within two certification cycles. This disruption window favors prepared incumbents and fast-following entrants with pre-submitted technical documentation.
For Market Incumbents: Consolidate certification pre-emption investments by locking CE marking and IEC 62443 cybersecurity assessments ahead of EU AI Act enforcement deadlines. Acquire wireless power transfer specialists to neutralize inductive charging substitution threats from Dutch and Belgian distribution center pilots. Prioritize captive supply of silicon carbide power modules through backward integration into semiconductor packaging partnerships.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission opens procurement access to German automotive OEM smart factory architectures before full regulatory enforcement. Target India's PLI scheme for advanced chemistry cell manufacturing as the most penetrable geography, where localized voltage specifications create indigenous demand unmatched by incumbent global platforms. Deploy charging-as-a-service operational expenditure models to displace capital purchase structures among US warehouse REITs.
For Investors and Strategic Acquirers: Autonomous robotic arm connector developers with proven unsupervised logistics deployments represent the highest-conviction acquisition archetype for long-term viability across the 5-10 year automation horizon. Signal to watch: METI energy efficiency directive alignment in Japanese automotive plants, which will indicate whether precision alignment technology transfers to global manufacturing standards or remains regionally captive.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Submission | EU AI Act compliance timelines filter hardware suppliers from Stuttgart and Wolfsburg automotive clusters. |
| Wireless Power Transfer Acquisition | Inductive charging capabilities capture Dutch distribution center demand for connector-free maintenance reduction. |
| Charging-as-a-Service Launch | Operational expenditure structures displace capital purchases among US third-party logistics providers. |
| Silicon Carbide Backward Integration | In-house power module supply insulates margins from commodity volatility under fixed-price contracts. |
| India PLI Scheme Localization | Domestic voltage specification matching captures emerging demand from indigenous battery manufacturing. |
Research Methodology
Operator-level perspectives from warehouse fleet managers, automotive OEM platform engineers, robotics integration specialists, and industrial electrification procurement leads anchored the qualitative base. Primary interview insights combined with secondary validation from IEC 62443 certification databases, EU AI Act implementation guidance, METI energy efficiency directive filings, and customs trade data for power electronics imports. Bottom-up shipment analysis across charging station configurations triangulated with top-down facility automation capex tracking.
Sensitivity analysis tested forecast robustness across copper price volatility bands, EU AI Act enforcement timeline scenarios, and AMR fleet penetration rates in logistics versus manufacturing verticals. The analytical framework modeled volume and value across product type, technology, end-use application, and installation configuration throughout the projection horizon. CAGRs derived from segment-level adoption curves weighted by facility automation investment cycles and battery chemistry standardization trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained warehouse automation capex and EU regulatory enforcement continuity; material deviation in commodity input costs or certification timeline delays would warrant model refresh. Recalibration cycles align with material shifts in EU AI Act implementation guidance and South Korean battery protocol licensing developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Assistive Robotics Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Global Robotic Grippers Market