
 Mobile Robot Charging Station Market | 2026-2036
Mobile Robot Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Robot Charging Station Market Intelligence
Direct-to-facility distribution is rewriting how charging station vendors reach end users in the mobile robot ecosystem. ABB leverages its industrial automation footprint to bundle charging hardware with robot deployment contracts. WiBotic specializes in wireless power systems for aerial and ground robots, sustaining R&D intensity in resonant inductive architectures. Wiferion anchors European supply through its focus on standardized contactless modules for intralogistics fleets.
A mobile robot charging station is an electromechanical system that replenishes onboard energy storage through conductive pins, inductive coils, or photovoltaic arrays, typically operating at voltages from 24 V to 800 V DC depending on robot class and duty cycle. Its primary purpose is to eliminate manual battery swaps and extend autonomous operational uptime in continuous-flow environments. Docking stations still occupy the largest installed base due to mechanical simplicity and retrofit compatibility, though wireless chargers represent the fastest-expanding margin pool as fleet operators prioritize reduced contact wear. Manufacturing facilities lead end-user demand, while warehouse deployments are accelerating fastest where seasonal volume spikes strain conventional plug-in routines.
FCC Part 18 governs industrial RF heating and power equipment in the United States, shaping inductive charger certification timelines and electromagnetic compatibility thresholds. The EU Machinery Directive and CE marking requirements enforce functional safety validation for autonomous docking systems sold across member states. OSHA electrical safety standards influence conductive charger grounding and enclosure specifications in American industrial settings. Stakeholders must monitor how evolving wireless power efficiency standards and building code amendments alter retrofit economics versus new-installation design choices.
Market Dynamics
Wireless power transfer architectures are compressing deployment timelines for mobile robot fleets, while EU building efficiency codes and OSHA electrical safety mandates reshape hardware specifications across industrial facilities.
Growth Catalysts
- EU Green Deal energy mandates:Facility managers in Germany and France face binding efficiency targets that accelerate contactless charging retrofits over conductive plug-in systems.
- Automotive plant automation:German automotive OEMs are expanding autonomous mobile robot fleets for just-in-time parts delivery, creating concentrated demand for high-voltage charging infrastructure.
- Resonant inductive coupling:Advances in coil alignment tolerance and power conversion efficiency enable wireless chargers to serve heavier payload classes previously restricted to mechanical docking.
Market Restraints
- Copper and ferrite supply concentration:Inductive coil manufacturing depends on Chinese-processed rare earth ferrites and Chilean copper cathodes, exposing vendors to input cost volatility and geopolitical supply disruptions.
- CE marking validation timelines:The EU Machinery Directive requires extensive functional safety documentation for autonomous docking systems, extending product launch cycles by 8-14 months for non-European suppliers.
- Conductive pin reliability:Mechanical contact charging retains cost advantages for low-duty-cycle deployments, slowing wireless adoption in price-sensitive warehouse segments.
Strategic Opportunities
- Third-party logistics cold chain:Temperature-controlled warehouses in the Netherlands and Belgium present underpenetrated demand for sealed, contactless charging systems that eliminate corrosion risks from condensation.
- Photovoltaic-integrated charging:Convergence of rooftop solar arrays with DC microgrids enables off-grid charging stations for outdoor agricultural and security robot deployments.
- Direct-to-facility distribution:Bypassing traditional industrial distributor networks allows charging hardware vendors to capture margin and bundle installation services with equipment sales.
Industry Challenges
- Electromagnetic compatibility certification:FCC Part 18 compliance for industrial RF power equipment requires specialized testing facilities and engineering expertise that constrains vendor expansion in the United States.
- Legacy warehouse management system integration:Charging station APIs must interface with proprietary fleet orchestration software from multiple robot OEMs, creating customization burdens and support complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Robot Charging Station Market |
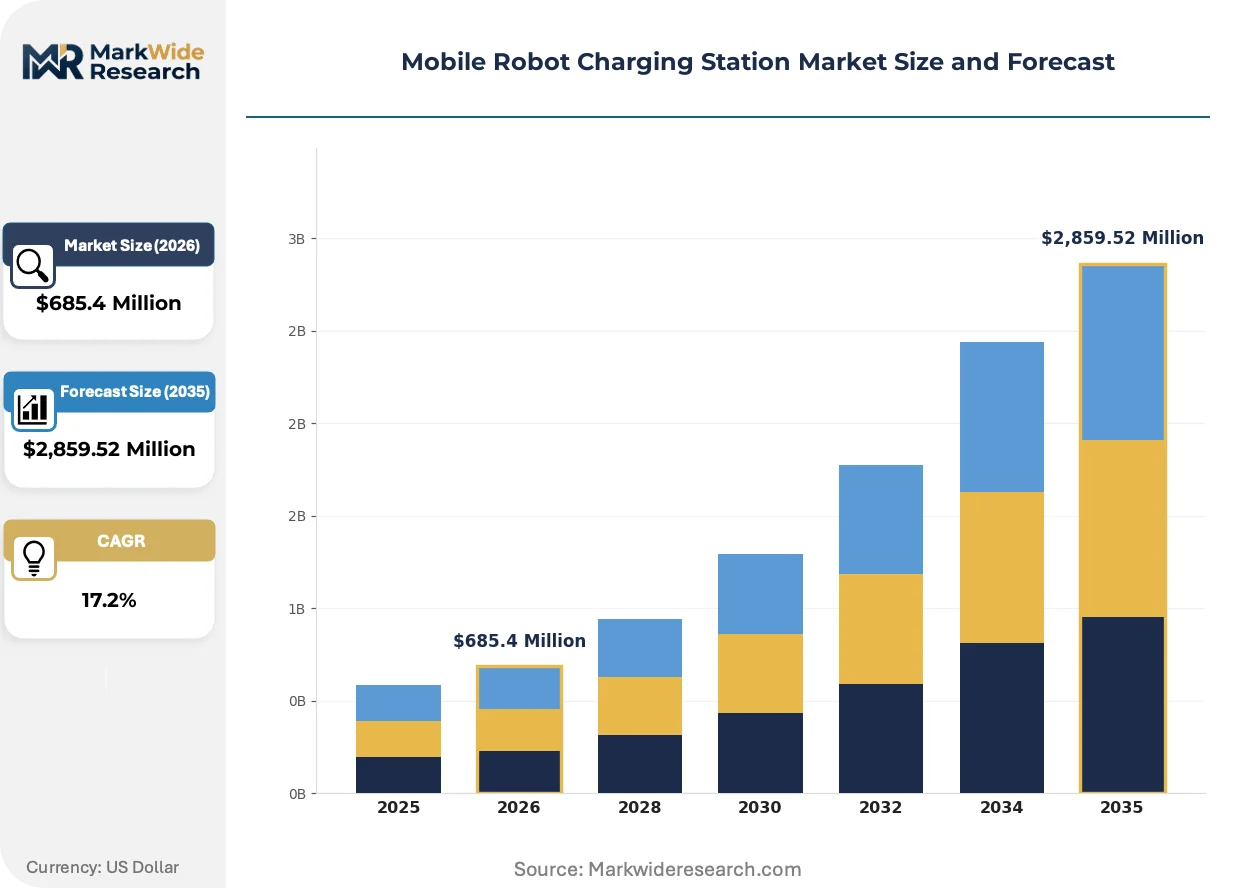
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,859.52 Million |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Docking Station, Wireless Charger, Rapid Charger, Solar Station Technology: Inductive Charging, Conductive Charging, Autonomous Navigation, Grid Power End User: Manufacturing Facilities, Warehouses, Hospitals, Retail Stores Installation: Indoor Systems, Outdoor Systems, Custom Installations, Temporary Solutions |
| Companies Covered | Omron, WiBotic, ABB, NaaS Technology, Mobile Industrial Robots, Volkswagen, Clearpath Robotics, Wiferion, Hyundai Motor Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Robot Charging Station Market Strategic Shifts & Innovations
Power electronics miniaturization and resonant frequency tuning are enabling charger designs that serve broader robot voltage classes without hardware swaps. These developments compress fleet standardization cycles and alter vendor R&D priorities.
Resonant inductive architectures are migrating from low-power material handling robots toward heavy-duty autonomous forklifts operating at 400-800 V DC. German automotive plants and Korean electronics manufacturers are piloting these systems for continuous-flow assembly lines. The technology is migrating from niche aerial drone applications into ground-based intralogistics, collapsing the historical segmentation between wireless and conductive charging markets.
OSHA electrical safety standards in the United States now require enhanced ground-fault protection and IP-rated enclosures for conductive charging stations in wet industrial environments. This regulatory pressure is accelerating enclosure redesigns and third-party validation investments among hardware suppliers. American food processing and chemical handling facilities face the steepest compliance costs, driving preference toward fully sealed inductive alternatives.
Fleet operators are consolidating charging infrastructure procurement under central engineering departments rather than distributed facility management. This purchasing centralization favors vendors offering multi-site service contracts and predictive maintenance analytics over transactional equipment sales. The shift is most pronounced in North American third-party logistics networks managing seasonal volume volatility across regional warehouse clusters.
Mobile Robot Charging Station Market Segmentation
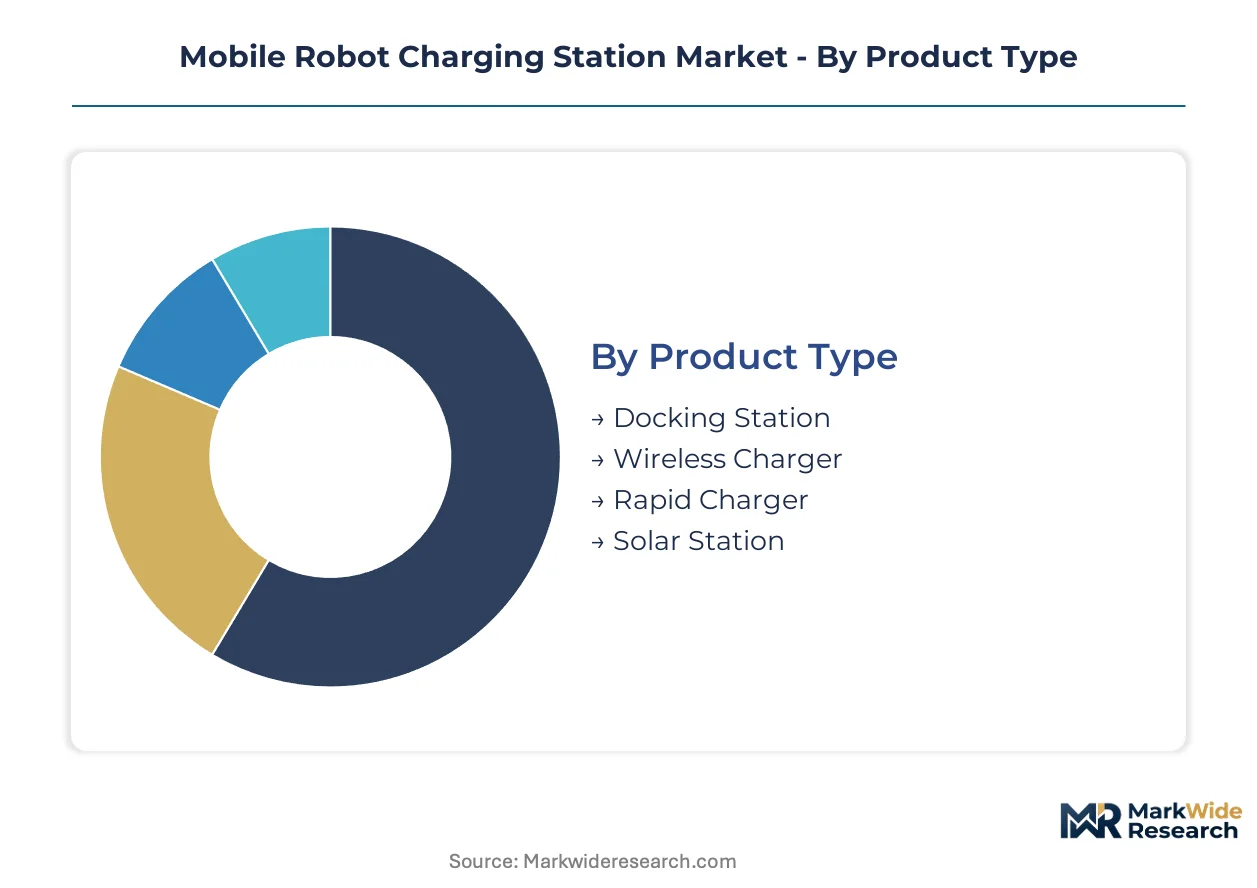
Charging infrastructure segmentation reveals divergent replacement cycles across product architectures. Docking stations and conductive systems installed in legacy facilities face 7-10 year refresh timelines, while wireless and rapid charging modules turn over every 3-5 years as efficiency standards tighten.
Product Type:
Cycle times vary sharply: rapid chargers and wireless units refresh fastest on efficiency gains, while docking stations and solar stations persist longer due to capital recovery schedules and weatherproofing investments.
- Docking Station:Mechanical pin-and-socket systems operating at 24-48 V DC dominate legacy manufacturing floors. German automotive plants and North American third-party logistics providers retain these for retrofit compatibility despite contact wear issues.
- Wireless Charger:Resonant inductive architectures at 100-300 kHz eliminate physical connectors. EU Green Deal efficiency mandates in France and Germany accelerate replacement of conductive systems with contactless alternatives in temperature-controlled warehouses.
- Rapid Charger:High-current conductive systems delivering 10-30 minute cycle times for continuous-flow operations. Korean electronics manufacturers deploy these for autonomous forklift fleets in high-throughput assembly environments.
- Solar Station:Photovoltaic-integrated DC microgrids enabling off-grid deployment for outdoor agricultural and perimeter security robots. Belgian and Dutch cold-chain facilities pilot these for condensation-resistant sealed charging.
Docking stations dominate installed base. Wireless chargers represent where expansion concentrates most steeply.
Technology:
Cost tiers separate mature conductive architectures from premium inductive systems, with navigation and grid-power layers adding incremental value capture.
- Inductive Charging:Coil-based power transfer using magnetic resonance at 85-300 kHz. Advances in alignment tolerance from WiBotic and Wiferion enable heavier payload classes previously restricted to mechanical docking.
- Conductive Charging:Direct electrical contact through spring-loaded pins or sliding collectors. OSHA electrical safety standards now mandate enhanced ground-fault protection and IP-rated enclosures, raising compliance costs for American food processing facilities.
- Autonomous Navigation:Docking algorithms integrating lidar or vision-based positioning for precision alignment. CE marking requirements under the EU Machinery Directive extend validation timelines for non-European suppliers.
- Grid Power:Utility-connected AC-DC conversion systems with power factor correction. FCC Part 18 compliance for industrial RF equipment constrains vendor expansion in United States markets.
Conductive charging retains volume leadership on installed base. Inductive architectures are climbing the fastest on new-build specifications.
End User:
Application intensity drives segmentation, with manufacturing and warehouse deployments leading on unit economics while healthcare and retail present niche specifications.
- Manufacturing Facilities:High-voltage infrastructure at 400-800 V DC for autonomous mobile robots in just-in-time parts delivery. German automotive OEMs concentrate demand for standardized contactless modules.
- Warehouses:Seasonal volume spikes strain conventional plug-in routines, accelerating fleet standardization cycles. North American third-party logistics networks centralize procurement under engineering departments.
- Hospitals:Sealed charging systems for medical supply delivery robots requiring sterilization compatibility.
- Retail Stores:Compact footprint stations for inventory scanning and customer service robots in constrained floor plans.
Manufacturing facilities anchor revenue concentration. Warehouses represent the steepest expansion trajectory on fleet automation.
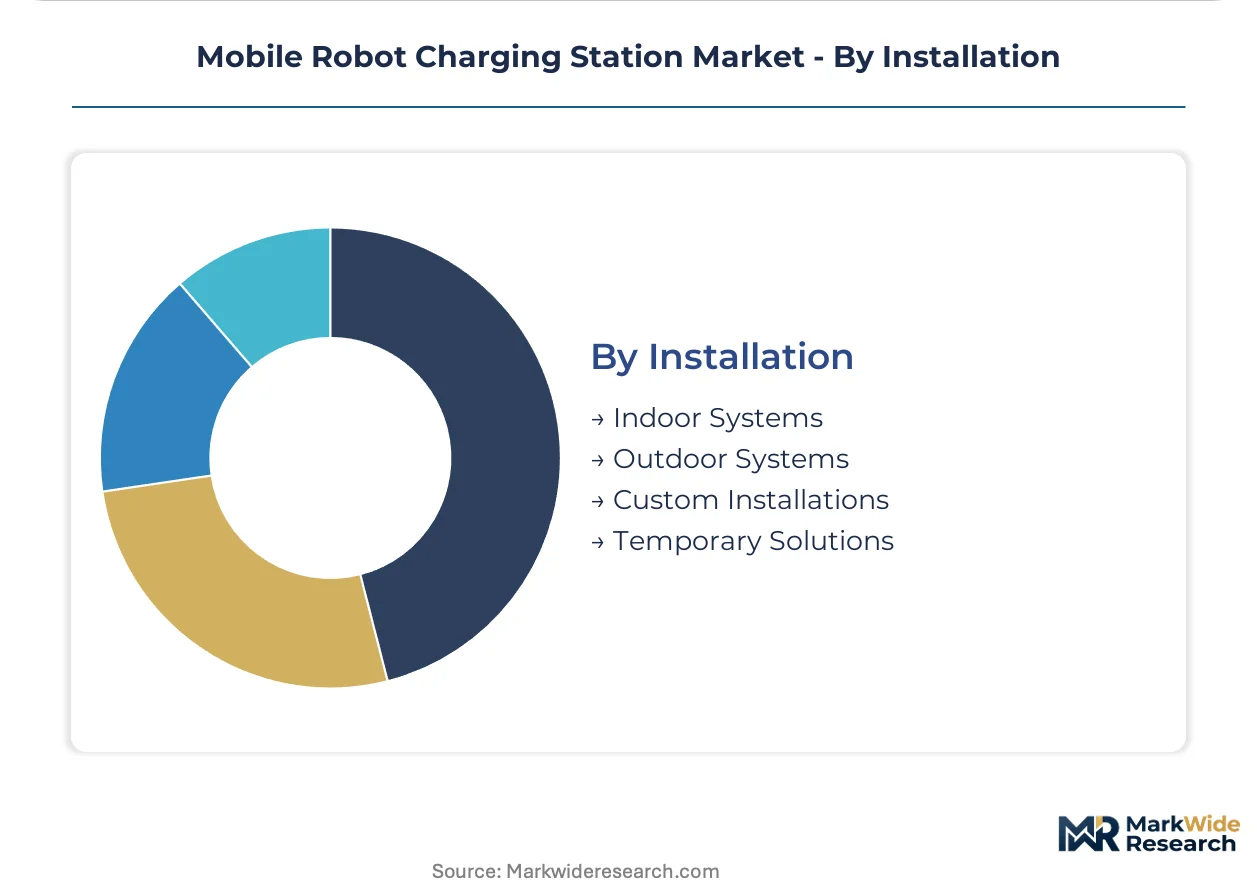
Installation:
Customer type and deployment flexibility shape this dimension, from permanent infrastructure to seasonal scalability.
- Indoor Systems:Climate-controlled installations with standard IP54 enclosures for material handling environments. EU building efficiency codes pressure facility managers toward low-energy contactless retrofits.
- Outdoor Systems:Weatherproofed NEMA 4X or IP67 enclosures with temperature-compensated charging curves for agricultural and security applications.
- Custom Installations:Site-specific engineering for legacy warehouse management system integration, creating API customization burdens.
- Temporary Solutions:Mobile charging trailers for peak-season warehouse capacity or construction site robotics.
Indoor systems dominate procurement volume. Outdoor systems are gaining share fastest on agricultural automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where automotive OEMs standardize high-voltage contactless modules, while warehouse operators in the United States absorb premium costs for rapid-charging infrastructure to meet seasonal throughput targets.
Germany
Automotive plants in Stuttgart and Wolfsburg expand autonomous mobile robot fleets for just-in-time parts delivery, creating concentrated demand for 400-800 V DC charging infrastructure. The EU Green Deal and national building efficiency codes pressure facility managers toward low-energy contactless retrofits. Bavarian automotive clusters and third-party logistics providers in North Rhine-Westphalia are retrofitting existing floors with resonant inductive systems to eliminate conductive pin maintenance.
United States
North American third-party logistics networks centralize charging infrastructure procurement under engineering departments to manage seasonal volume volatility across regional warehouse clusters. OSHA electrical safety standards mandate enhanced ground-fault protection and IP-rated enclosures for conductive stations in wet industrial environments. Greater Chicago and Dallas-Fort Worth distribution hubs are deploying sealed inductive alternatives to avoid compliance costs in food processing and chemical handling facilities.
China
Electronics manufacturers in Shenzhen and Shanghai pilot high-current rapid chargers for autonomous forklift fleets in high-throughput assembly environments. GB standards and MIIT regulations shape electromagnetic compatibility thresholds for industrial RF power equipment. Yangtze River Delta industrial zones are integrating photovoltaic-integrated DC microgrids for outdoor agricultural and security robot deployments.
South Korea
Electronics manufacturers deploy rapid charging systems for continuous-flow assembly lines serving memory chip and display panel production. MFDS-equivalent industrial safety regulations and national smart factory initiatives accelerate standardization of autonomous docking protocols. Busan-Ulsan manufacturing corridors are testing resonant inductive architectures for heavy-duty payload classes previously restricted to mechanical docking.
Netherlands
Temperature-controlled warehouses in Rotterdam and Venlo present underpenetrated demand for sealed, contactless charging systems that eliminate corrosion risks from condensation. EU Machinery Directive CE marking requirements enforce functional safety validation for autonomous docking systems. Dutch cold-chain facilities are piloting solar-integrated charging stations to meet binding efficiency targets under national building codes implementing EU Green Deal mandates.
Mobile Robot Charging Station Market Key Industry Players
Industrial automation conglomerates and wireless power specialists split the market between bundled hardware-deployment contracts and pure-play resonant inductive architectures. The vendor base stratifies across three tiers: diversified automation platforms with captive charging divisions, focused wireless technology developers, and automotive OEMs with captive fleet charging needs. Consolidation pressures favor vendors offering multi-site service contracts and predictive maintenance analytics over transactional equipment sales. Geographic expansion and technology licensing represent the dominant competitive vectors as regional certification requirements fragment market entry pathways.
Within the diversified automation tier, ABB anchors European supply through industrial automation footprints that bundle charging hardware with robot deployment contracts. WiBotic occupies a position exemplifying focused wireless power specialists sustaining R&D intensity in resonant inductive architectures. Wiferion represents standardized contactless module developers targeting intralogistics fleet standardization cycles in German-speaking markets.
| Leading Market Players |
|---|
| Omron |
| WiBotic |
| ABB |
| NaaS Technology |
| Mobile Industrial Robots |
| Volkswagen |
| Clearpath Robotics |
| Wiferion |
| Hyundai Motor Group |
| Others |
Cost & Logistics Intelligence
Chinese-processed rare earth ferrites and Chilean copper cathodes concentrate upstream input supply, tethering charger manufacturing costs to volatile commodity flows while margin pools accumulate in aftermarket service contracts and predictive maintenance software layers. This dependency structure forces hardware vendors to absorb input cost swings or push pricing pressure downstream toward fleet operators with limited alternative sourcing options.
Pricing Analysis
The customization-premium spread separates standard contactless modules from configured-to-order high-voltage systems for automotive plants. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales bundling, with CE-marked autonomous docking systems commanding substantial premiums over basic conductive pin alternatives. Cost compression in entry-level warehouse segments is intensifying because mechanical docking retains retrofit compatibility advantages. Third-party logistics networks in North America demonstrate highest price sensitivity due to seasonal volume volatility, while German automotive OEMs prioritize standardization over unit cost minimization.
Supply Chain Analysis
Export-control regimes on high-frequency power electronics and rare earth processing constrain component flows from China into Western charger assembly operations. Manufacturing draws from Chinese ferrite processing, Chilean copper refining, and German precision coil winding for resonant inductive architectures. Single-source vulnerability concentrates in rare earth magnet supply chains, where processing capacity clusters in Chinese industrial zones. Distribution runs through direct-to-facility channels that bypass traditional industrial distributors, enabling vendors to bundle installation services with hardware sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile robot charging station market functions as a service-attach opportunity where predictive maintenance analytics and multi-site service contracts expand faster than transactional hardware revenue. Recurring software layers for fleet energy optimization and charger health monitoring now outpace equipment sales growth in vendor income statements.
For Market Incumbents: Entrench position through backward integration into resonant coil manufacturing and captive supply of ferrite cores to offset Chinese input volatility. ABB and WiBotic should deepen R&D investment in alignment-tolerant architectures that extend wireless power to heavier payload classes previously restricted to mechanical docking. Defensive patenting around FCC Part 18 compliance methodologies creates barriers against emerging wireless power specialists seeking US market entry.
For New Entrants and Emerging Players: Build out presence in Dutch and Belgian cold-chain logistics corridors where sealed contactless systems address condensation corrosion risks in temperature-controlled warehouses. Photovoltaic-integrated charging for outdoor agricultural robotics presents underpenetrated white space with limited incumbent specialization. Partner with regional system integrators possessing established relationships with warehouse management software vendors to circumvent API customization burdens.
For Investors and Strategic Acquirers: Capital is best deployed toward pure-play wireless power developers with validated resonant inductive architectures and established CE marking documentation, as regulatory compliance assets appreciate in scarcity value across the projection horizon. Acquisition targets should demonstrate functional safety validation under EU Machinery Directive protocols and installed base traction in German automotive or Korean electronics manufacturing corridors. Watch for inflection signals in GB standard harmonization with international wireless power efficiency benchmarks, which would accelerate Chinese domestic market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Resonant Inductive Architecture R&D | Extends wireless power to 400-800 V DC autonomous forklifts in German automotive assembly plants. |
| CE Marking Pre-Validation Investment | Compresses product launch timelines by 8-14 months for non-European suppliers under EU Machinery Directive. |
| Direct-to-Facility Channel Buildout | Captures margin and installation service revenue by bypassing traditional industrial distributor networks. |
| Predictive Maintenance Platform Launch | Addresses procurement centralization under North American third-party logistics engineering departments. |
| Photovoltaic-Integrated Charging Development | Enables off-grid deployment for outdoor agricultural robots in Yangtze River Delta pilot zones. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industrial automation vendor disclosures. Primary interviews engaged fleet operations managers at third-party logistics networks, plant engineers at German automotive OEMs, procurement leads at Korean electronics manufacturers, and aftermarket service heads at charging infrastructure vendors. Secondary validation drew from FCC Part 18 equipment authorization databases, EU Machinery Directive notified body documentation, OSHA electrical safety standard interpretations, and SEC filings from diversified automation conglomerates. Bottom-up unit deployment estimates triangulate against top-down addressable facility calculations across manufacturing and warehouse verticals.
Forecast inputs incorporate charging station replacement cycles by product architecture, efficiency standard tightening trajectories, and fleet automation adoption curves across end-use segments. Segmentation dimensions model product type, technology layer, end-user industry, and installation environment across the analysis window. CAGRs derive from installed base growth, refresh rate acceleration, and average revenue per unit expansion in software-attach layers. Industry-specific inputs include EU Green Deal implementation timelines for building efficiency codes and resonant inductive coupling efficiency improvement curves.
Sensitivities concentrate around rare earth supply disruptions, CE marking validation timeline extensions, and wireless power efficiency standard harmonization. Forecasts reflect assumptions on copper price stability, automotive plant automation continuity, and warehouse management system API openness. Material shifts in Chinese export controls on ferrite processing, EU Machinery Directive enforcement intensity, or OSHA electrical safety standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Collaborative Robots Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
Europe AUV and ROV Market