
 Aerospace Service Robotics Market | 2026-2036
Aerospace Service Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Service Robotics Market Analysis
Direct sales channels between robot OEMs and aerospace manufacturers is narrowing as tier-one suppliers consolidate procurement under long-term service agreements. ABB leverages its integrated force-control architecture to sustain dominance in precision drilling and fastening applications for airframe assembly. KUKA AG anchors its position through captive supply of heavy-payload platforms optimized for wing handling and fuselage transport.
Aerospace service robotics encompasses electromechanical systems engineered for precision manipulation, non-destructive inspection, and autonomous mobility within confined aircraft structures, typically operating with positional accuracy below 0.1 millimeter and payload capacities spanning 5 to 500 kilograms to execute maintenance, cleaning, and logistics tasks without airframe disassembly. Inspection robots lead product type demand as airlines face escalating pressure to reduce aircraft-on-ground intervals while maintaining zero-defect standards for composite and metallic structures. AI-based robots represent the fastest-expanding technology segment, with sensor fusion architectures enabling real-time crack detection and predictive corrosion mapping that shifts maintenance from scheduled to condition-based protocols.
FAA airworthiness regulations and EASA Part-145 maintenance organization standards govern robotic tool calibration, traceability, and operator certification, while ISO 10218 safety requirements constrain collaborative robot deployment near human technicians in hangar environments. Stakeholders must monitor evolving MDR and CE marking obligations in Europe alongside China's GB standard harmonization for imported automated ground support equipment. The decisive variable ahead involves whether military end users or commercial airlines will set the dominant performance specification for autonomous refueling and de-icing platforms.
Market Dynamics
The aerospace service robotics sector is experiencing a fundamental reconfiguration as tier-one suppliers consolidate procurement under long-term service agreements, compressing traditional direct sales channels between robot OEMs and airframe manufacturers.
Growth Catalysts
- FAA Airworthiness Directives:Tightening compliance requirements for automated ground equipment are mandating robotic traceability systems that accelerate replacement cycles for legacy inspection tools across US-based MRO facilities.
- Composite airframe proliferation:Boeing and Airbus production lines for carbon-fiber fuselages require precision drilling robots with force-control architectures that maintain zero-defect standards during fastener installation.
- China's GB standard harmonization:Import regulations for automated ground support equipment are creating certified supplier status for foreign robot OEMs that achieve early compliance with national safety protocols.
Market Restraints
- High-precision sensor costs:Lidar and tactile sensor arrays for confined-space navigation represent 35-40% of total robot bill-of-materials, creating margin pressure for mid-tier system integrators.
- German supplier concentration:Heavy-payload linear actuator production clusters around Stuttgart and Munich, exposing buyers to single-source risk for wing-handling platforms above 200 kilograms.
- EASA Part-145 certification timelines:Maintenance organization approval for robotic tool calibration extends 18-24 months, delaying deployment for airlines seeking immediate AOG interval reduction.
Strategic Opportunities
- India MRO expansion:Bangalore and Hyderabad maintenance hubs lack automated inspection capacity for narrow-body fleets, creating first-mover advantage for mobile crawler robots with AI-based crack detection.
- Dual carbon goals in China:National emissions targets are incentivizing electric ground support equipment, opening procurement channels for battery-powered autonomous refueling prototypes.
- Laser-ultrasonic fusion:Convergence of laser excitation with phased-array ultrasonic testing enables through-thickness corrosion mapping without surface preparation, shifting maintenance protocols from scheduled to condition-based.
Industry Challenges
- Mechatronics talent scarcity:Hangar technicians require cross-training in ISO 10218 safety protocols and robot teach-pendant operation, straining workforce development programs at major US carriers.
- Legacy system integration:Proprietary MRO software platforms from the 1990s lack API architectures for real-time robot telemetry, forcing expensive middleware development for predictive maintenance dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Service Robotics Market |
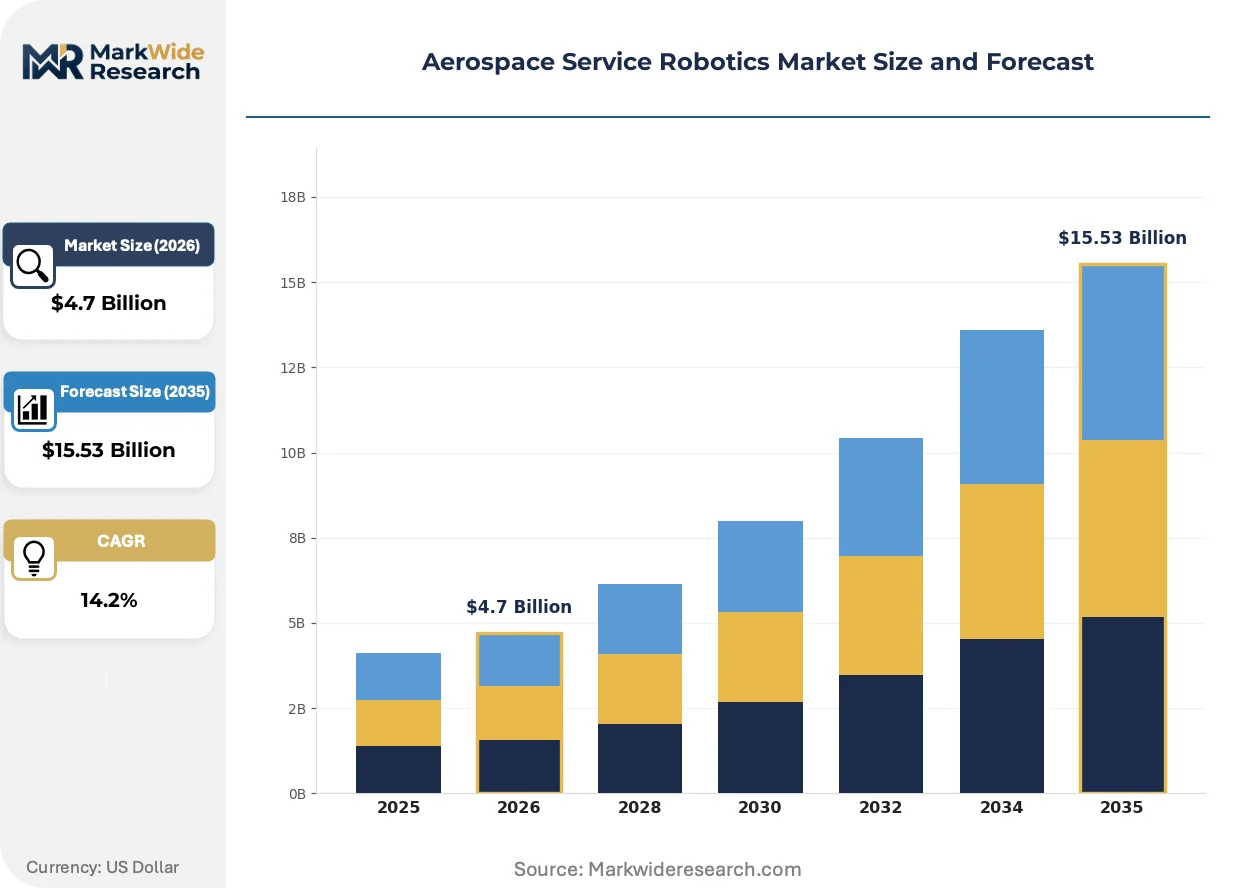
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inspection Robots, Maintenance Robots, Transportation Robots, Cleaning Robots Technology: AI-Based Robots, Autonomous Navigation, Teleoperated Systems, Sensor Fusion Application: Aircraft Maintenance, Ground Support Operations, Surveillance, Logistics End User: Airlines, Military, Airports, Aerospace Manufacturers |
| Companies Covered | ABB, Fanuc Corporation, KUKA AG, Electroimpact Inc., AV&R, JH Robotics, Inc., Universal Robots A/S, Yaskawa Electric Corporation, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Service Robotics Market Emerging Trajectories
Sensor fusion architectures are collapsing the traditional separation between inspection and repair workflows, enabling real-time decision loops that compress aircraft-on-ground intervals from days to hours.
Force-controlled drilling systems with integrated torque-feedback loops are collapsing the error tolerance gap between manual and automated fastening in composite airframe assembly. Airbus and Boeing tier-one suppliers in Germany and the United States are retrofitting existing gantry systems with these modules at accelerated capex cycles. The technology is collapsing the historical trade-off between production speed and defect rates that constrained earlier automation waves.
EU AI Act risk-classification frameworks for autonomous mobile robots are triggering mandatory conformity assessments for inspection platforms operating in collaborative hangar environments. EASA is aligning Part-145 maintenance organization standards with these AI governance requirements, creating dual-certification burdens for European MRO providers. Composite inspection robots with embedded neural networks face the steepest compliance costs, pushing developers toward edge-computing architectures that limit on-device model complexity.
Airline technical procurement teams are consolidating vendor relationships under outcome-based service contracts that tie robot availability to guaranteed AOG reduction metrics. Long-term agreements now span 7-10 years with penalty clauses for system downtime, displacing traditional equipment purchase models. This restructuring is most visible among US legacy carriers with centralized maintenance operations in Dallas-Fort Worth and Atlanta hubs.
Aerospace Service Robotics Market Segmentation
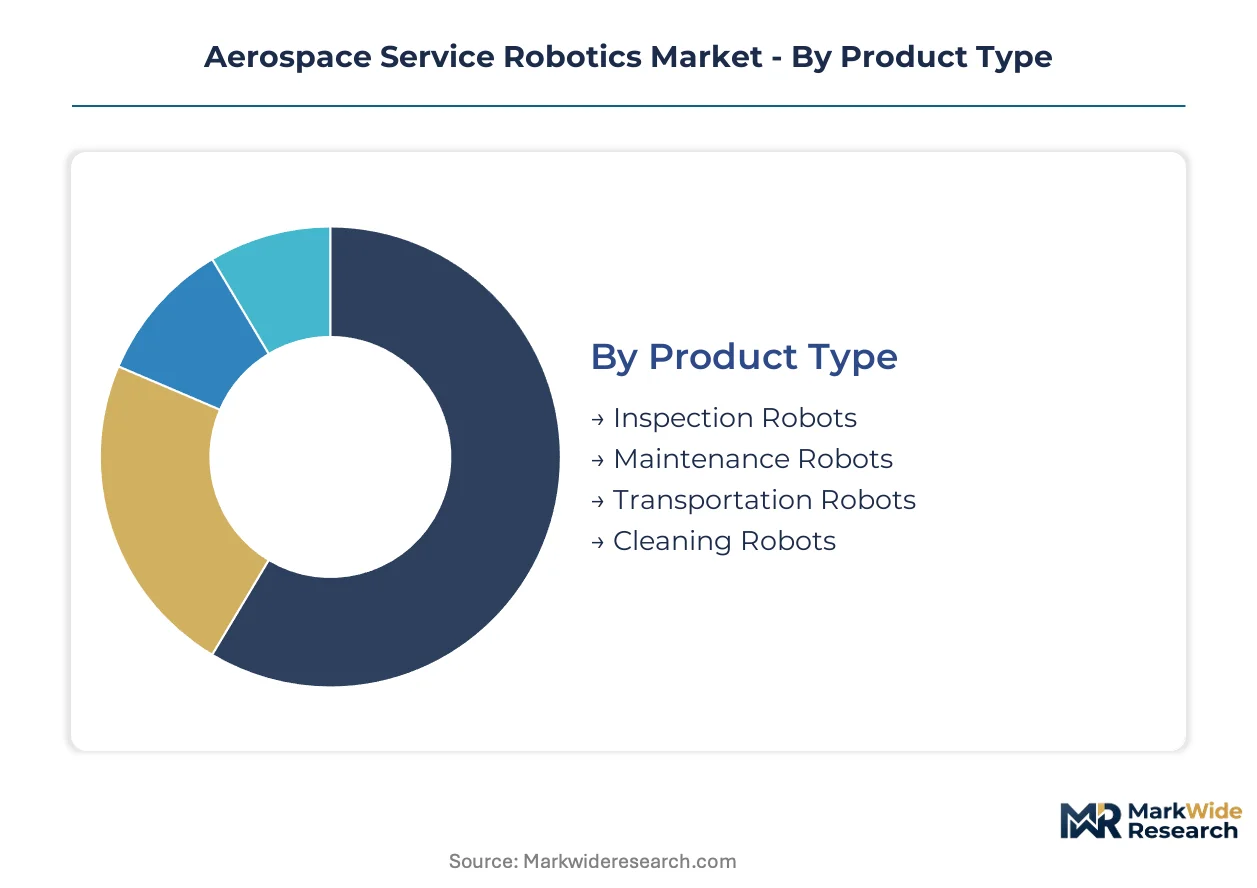
Aerospace service robotics vendors structure their portfolios around distinct product architectures and operational modes. Each segment carries unique service intensity profiles, calibration requirements, and certification burdens that shape margin structures and customer lock-in potential.
Product Type:
After-sales service intensity varies sharply across product categories, with inspection platforms demanding continuous sensor recalibration and software updates while transportation robots require primarily mechanical maintenance.
- Inspection Robots:Electromechanical systems equipped with phased-array ultrasonic transducers, eddy current probes, and machine vision arrays for detecting subsurface cracks and corrosion in composite and metallic airframes. Demand concentrates among US legacy carriers operating centralized MRO hubs in Dallas-Fort Worth and Atlanta, driven by FAA airworthiness directive compliance timelines that mandate traceable inspection records. Airlines face escalating pressure to reduce aircraft-on-ground intervals while maintaining zero-defect standards.
- Maintenance Robots:Force-controlled platforms executing precision drilling, fastening, and sealing operations with positional accuracy below 0.1 millimeter and integrated torque-feedback loops. German tier-one suppliers retrofitting Airbus and Boeing production lines in Hamburg and Charleston drive procurement, as carbon-fiber fuselage assembly requires automated fastening to eliminate manual defect rates.
- Transportation Robots:Heavy-payload autonomous guided vehicles and linear actuator systems for wing handling and fuselage transport.
- Cleaning Robots:Mobile crawler platforms equipped with high-pressure nozzles and non-abrasive media delivery for exterior washing and decontamination.
Inspection robots hold the largest share; momentum sits with maintenance robots as composite airframe proliferation accelerates.
Technology:
Technology selection determines the boundary between scheduled and condition-based maintenance protocols, with AI architectures enabling predictive analytics that shift airline capital allocation from reactive to preemptive spending.
- AI-Based Robots:Neural network architectures embedded in edge-computing hardware for real-time crack detection, corrosion mapping, and maintenance decision automation. Commercial airlines in China pursuing dual carbon goals prioritize these systems for fuel efficiency optimization through predictive engine maintenance. EU AI Act risk-classification frameworks impose mandatory conformity assessments, pushing developers toward simplified on-device models.
- Autonomous Navigation:Lidar and SLAM-based mobility systems for confined-space operation within aircraft structures and hangar environments.
- Teleoperated Systems:Human-in-the-loop control architectures for high-risk repair operations requiring technician judgment.
- Sensor Fusion:Integrated multi-modal perception combining tactile, visual, and ultrasonic inputs for comprehensive defect characterization.
AI-based robots command premium pricing; autonomous navigation is expanding most quickly as safety certification pathways mature.
Application:
Application focus shapes the competitive landscape, with aircraft maintenance demanding precision certification and ground support operations rewarding scale and fleet standardization.
- Aircraft Maintenance:Precision manipulation and non-destructive inspection tasks executed without airframe disassembly, spanning engine borescope access, structural repair, and component replacement. US-based MRO facilities face compressed deployment timelines as EASA Part-145 certification for robotic tool calibration extends 18-24 months, creating backlog advantages for early adopters.
- Ground Support Operations:Autonomous refueling, de-icing, and cargo handling on airport aprons.
- Surveillance:Perimeter monitoring and security patrol applications with limited aerospace specificity.
- Logistics:Intra-facility material transport and inventory management within manufacturing and MRO complexes.
Aircraft maintenance dominates revenue contribution; ground support operations are gaining share fastest as airports automate turnaround processes.
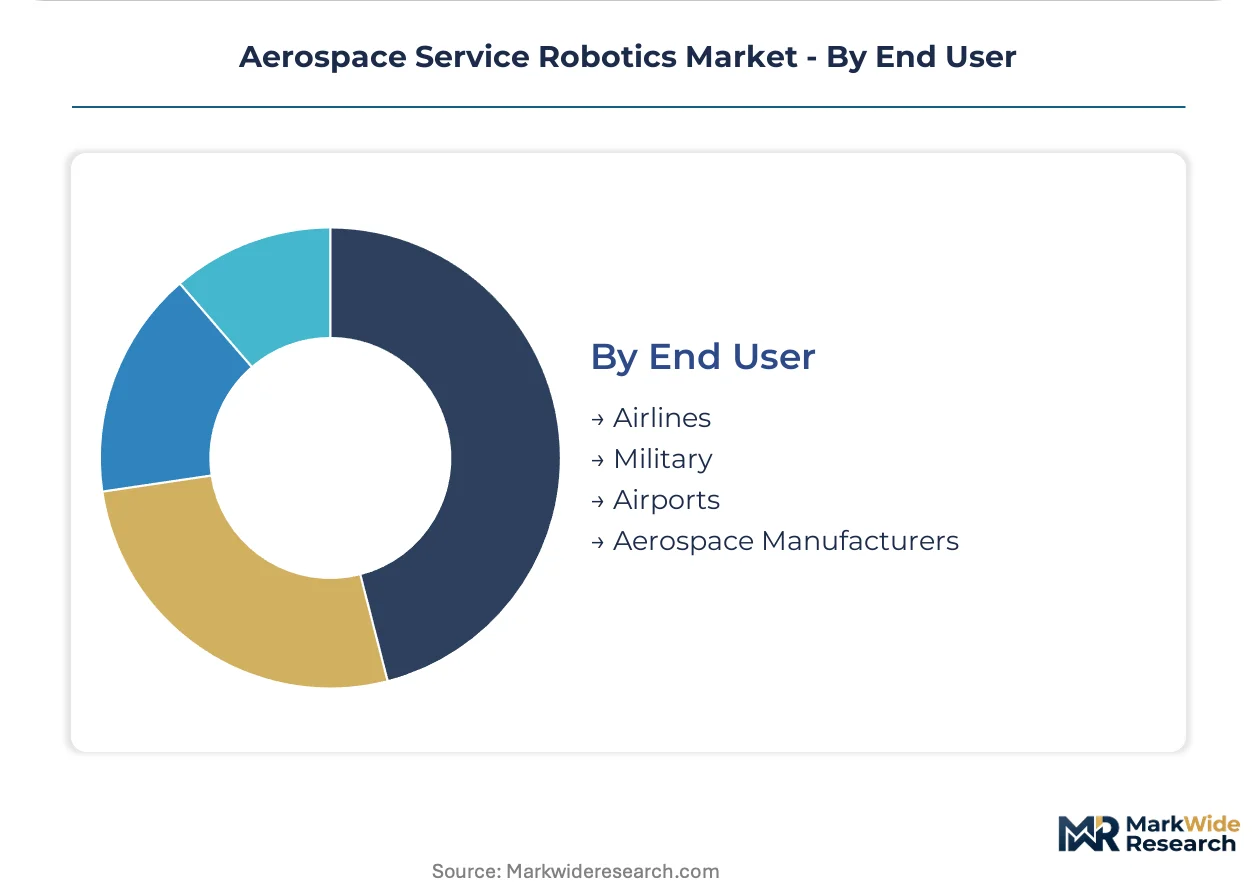
End User:
End-user concentration determines specification authority, with military procurement cycles setting durability benchmarks that commercial airlines later adopt at reduced cost points.
- Airlines:Commercial carriers operating narrow-body and wide-body fleets with centralized technical procurement teams. US legacy carriers consolidate vendor relationships under 7-10 year outcome-based service contracts tying robot availability to guaranteed AOG reduction metrics, displacing traditional equipment purchase models.
- Military:Defense agencies requiring hardened platforms for expeditionary maintenance and contested environment operations.
- Airports:Ground handling operators and airport authorities managing apron automation infrastructure.
- Aerospace Manufacturers:Boeing, Airbus, and tier-one suppliers integrating robots into greenfield and retrofit assembly lines.
Airlines represent the largest addressable base; military end users set the dominant performance specification for autonomous refueling platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor the United States as the dominant geography, with EASA certification standards and China's GB harmonization creating parallel compliance ecosystems that reshape procurement patterns across major aerospace clusters.
United States
Legacy carriers operating centralized MRO hubs in Dallas-Fort Worth and Atlanta drive inspection robot procurement under 7-10 year outcome-based service contracts. FAA airworthiness directives mandate robotic traceability systems that accelerate replacement cycles for legacy inspection tools. Charleston and Wichita manufacturing clusters absorb precision drilling platforms for Boeing and tier-one supplier assembly lines.
Germany
Airbus production lines in Hamburg and tier-one supplier networks across Baden-Württemberg absorb force-controlled fastening systems for carbon-fiber fuselage assembly. EASA Part-145 maintenance organization standards govern robotic tool calibration and operator certification timelines extending 18-24 months. Stuttgart and Munich production clusters concentrate heavy-payload linear actuator manufacturing for wing-handling platforms above 200 kilograms.
China
Commercial airlines pursuing dual carbon goals prioritize AI-based robots for predictive engine maintenance and fuel efficiency optimization. GB standard harmonization for imported automated ground support equipment creates certified supplier status for foreign robot OEMs achieving early compliance. Shanghai and Xi'an MRO hubs lack automated inspection capacity for narrow-body fleets, opening procurement channels for mobile crawler platforms.
Japan
Precision sensor manufacturers supply lidar and tactile arrays that represent 35-40% of total robot bill-of-materials for confined-space navigation systems. METI industrial policy supports collaborative robot deployment in manufacturing environments through ISO 10218 safety alignment. Nagoya aerospace corridor integrates inspection platforms into Toyota-affiliated supplier maintenance workflows.
India
Bangalore and Hyderabad maintenance hubs face capacity constraints for narrow-body fleet inspection, creating first-mover advantage for AI-based crack detection systems. PLI scheme incentives for advanced manufacturing equipment reduce import duty burdens for automated ground support platforms. Delhi-NCR technical procurement teams evaluate outcome-based service contracts modeled on US legacy carrier structures.
Aerospace Service Robotics Market Vendor Landscape
Integrated automation conglomerates and specialized aerospace system houses split the market into distinct capability tiers. The vendor base concentrates around precision manipulation expertise and heavy-payload platform engineering rather than general-purpose robotics. Three archetypes dominate: force-control specialists serving airframe assembly, sensor fusion developers enabling predictive maintenance, and autonomous navigation providers for ground support operations. Competitive dynamics center on long-term service agreement consolidation and captive supply chain integration for critical actuator components.
Among European automation conglomerates, ABB and KUKA AG occupy positions as structural anchors for precision drilling and heavy-payload applications respectively. ABB leverages integrated force-control architectures that sustain dominance in airframe fastening workflows. KUKA AG anchors its market presence through captive supply of platforms optimized for wing handling and fuselage transport above 200 kilograms. Japanese conglomerates including Fanuc Corporation and Yaskawa Electric Corporation represent the precision-motion archetype, supplying servo systems and articulated arm architectures that underpin competitor platforms. These four entities exemplify the split between European system integration depth and Japanese component-level precision that defines competitive positioning.
| Leading Market Players |
|---|
| ABB |
| Fanuc Corporation |
| KUKA AG |
| Electroimpact Inc. |
| AV&R |
| JH Robotics, Inc. |
| Universal Robots A/S |
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Stuttgart heavy-payload actuator production clusters is pressuring OEM margins while compressing procurement timelines for tier-one aerospace suppliers seeking long-term service agreements. This utilization imbalance forces German manufacturers to absorb sensor cost inflation while extending payment terms to defend market share in wing-handling platform segments.
Pricing Analysis
Price spreads between US and Chinese inspection robot contracts exceed 40% for equivalent force-control specifications, reflecting divergent certification burdens under FAA airworthiness directives versus GB standard harmonization protocols. Pricing stratifies across EASA Part-145 certified premium tiers, ISO 10218 compliant standard tiers, and uncertified economy platforms for non-critical logistics applications. Cost compression in mid-tier sensor fusion architectures is intensifying because Japanese lidar array suppliers face yield constraints. Commercial airlines with centralized MRO operations exhibit lowest price sensitivity due to outcome-based contract structures, while regional Indian maintenance hubs remain highly price-sensitive.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement contracts for heavy-payload linear actuators, with supply-chain finance facilities increasingly provided by German component banks to sustain Stuttgart production clusters. Manufacturing concentration rests on Germany for precision drilling systems, Japan for tactile sensor arrays, and China for battery-powered autonomous ground support prototypes. Critical dependencies include phased-array ultrasonic transducers, force-control servo motors, and edge-computing neural network processors. Single-source vulnerability concentrates in Baden-Württemberg linear actuator production above 200 kilograms. Distribution runs through tier-one aerospace supplier networks rather than direct robot OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among US legacy carriers consolidating vendor relationships under 7-10 year outcome-based service contracts, fragmenting pricing leverage for mid-tier system integrators unable to guarantee AOG reduction metrics.
For Market Incumbents: Harden force-control IP portfolios through captive supply of torque-feedback servo architectures to block emerging Chinese entrants from GB-certified supplier status. Anchor long-term service agreements with penalty clauses for system downtime that replicate US legacy carrier contract structures. Vertical integration into edge-computing hardware reduces exposure to EU AI Act conformity assessment delays for neural network-equipped inspection platforms. For New Entrants and Emerging Players: Build out AI-based crack detection capabilities for Bangalore and Hyderabad narrow-body MRO hubs where automated inspection capacity remains underdeveloped. Target mobile crawler robot segments in Chinese commercial airlines pursuing dual carbon goals through predictive engine maintenance contracts. Penetrate via outcome-based service agreements modeled on US carrier structures rather than equipment sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among inspection robot vendors with continuous sensor recalibration contracts and software update subscriptions tied to FAA traceability mandates. Long-term viability hinges on regulatory certification moats rather than hardware differentiation. Monitor EASA Part-145 approval timelines as inflection indicator for European MRO deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Force-Control Architecture Patent Expansion | Secures dominance in Airbus and Boeing carbon-fiber fuselage fastening workflows against emerging competitors. |
| GB Standard Harmonization Certification | Unlocks certified supplier status for foreign OEMs in China's automated ground support equipment procurement channels. |
| Outcome-Based Service Contract Launch | Ties robot availability to guaranteed AOG reduction metrics, displacing traditional equipment purchase models among US carriers. |
| Edge-Computing Neural Network Simplification | Reduces EU AI Act conformity assessment burdens for inspection platforms in collaborative hangar environments. |
| India MRO Hub Partnership Development | Captures first-mover advantage in Bangalore and Hyderabad narrow-body fleet inspection capacity expansion. |
Methodological Framework
Initial hypotheses were tested against primary input from MRO operations directors, aerospace manufacturing procurement leads, robotic system integration engineers, and FAA certification specialists, then refined against secondary validation from EASA Part-145 maintenance organization filings, FAA airworthiness directive databases, SEC 10-K automation segment disclosures, and customs records for automated ground support equipment imports. Bottom-up triangulation across robot OEM shipment data and top-down validation against airline capital expenditure disclosures anchored volume estimates.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by inspection, maintenance, transportation, and cleaning architectures; technology tiers spanning AI-based, autonomous navigation, teleoperated, and sensor fusion systems; and end-user concentration among airlines, military procurement agencies, airports, and aerospace manufacturers. CAGRs derived from regression analysis against aircraft fleet expansion rates and composite airframe production schedules, with sensitivity testing for EASA certification timeline variations and Chinese GB standard implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed automation conglomerates would shift outcomes beyond modeled bounds. Macroeconomic deviation in commercial aviation recovery trajectories, regulatory acceleration in EU AI Act enforcement, or breakthrough advances in laser-ultrasonic fusion corrosion mapping would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Germany Cloud Robotics Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
United States Articulated Robot Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Thailand Cloud Robotics Market