
 Europe Cloud Robotics Market | 2026-2036
Europe Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cloud Robotics Market Analytics
Subscription-based software-defined control is shifting how European robot vendors monetize hardware deployments. Siemens leverages its digital twin portfolio to anchor recurring revenue streams across factory automation contracts. KUKA AG competes through deep specialization in cloud-native collaborative robot architectures for automotive clients. NVIDIA Corporation extends its position by supplying GPU-accelerated edge-to-cloud inference platforms that power real-time robotic decision-making.
Cloud robotics denotes distributed robot systems that offload computation, data storage, and machine learning model training to remote cloud infrastructure via low-latency connectivity, typically requiring sub-50ms response times for safe human-robot collaboration. Industrial robots dominate current deployment value, though mobile robots represent the fastest-expanding category as warehouse operators retrofit fulfillment centers across the Netherlands and Poland. Hybrid cloud deployments command premium pricing due to data sovereignty requirements, while public cloud adoption accelerates among SMEs seeking reduced capital expenditure.
The EU AI Act and CE marking under the Machinery Directive shape product certification timelines, forcing vendors to embed explainability and safety documentation before market release. EMA guidelines on cloud-based medical device software and GDPR data localization rules further constrain how healthcare robotics applications transmit patient data across borders. Stakeholders must monitor evolving harmonized standards under the EU Green Deal, as energy efficiency metrics for cloud data centers increasingly factor into public procurement criteria for robotic automation projects.
Market Dynamics
Subscription-based software-defined control architectures are restructuring how European robot vendors capture value from hardware deployments, decoupling recurring revenue from one-time equipment sales.
Growth Catalysts
- EU AI Act compliance mandates:The regulation's risk-classification framework for autonomous systems is accelerating vendor investment in explainable AI and safety documentation pipelines.
- Automotive assembly automation:German and French manufacturers are expanding cloud-connected collaborative robot deployments across powertrain and battery pack assembly lines.
- GDPR data localization:Strict cross-border transmission rules for industrial telemetry are driving demand for sovereign cloud infrastructure and hybrid edge-cloud architectures.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in accelerated inference silicon creates procurement bottlenecks for real-time robotic decision-making systems.
- CE marking timeline friction:Machinery Directive conformity assessment procedures extend product certification cycles by 8-14 months for novel cloud-integrated robot designs.
- Latency infrastructure gaps:Sub-50 millisecond connectivity requirements for safe human-robot collaboration remain unavailable across Eastern European industrial zones.
Strategic Opportunities
- Polish warehouse automation:E-commerce fulfillment center retrofits present untapped demand for mobile cloud robotics in Central European logistics corridors.
- EU Green Deal procurement criteria:Energy efficiency metrics for cloud data centers are embedding robotic automation into public infrastructure tenders.
- Digital twin convergence:Integration of physics simulation with live cloud inference is enabling predictive maintenance contracts for automotive OEMs.
Industry Challenges
- Mechatronics-cloud skill scarcity:The intersection of embedded systems engineering and distributed infrastructure architecture lacks qualified practitioners across European technical universities.
- Legacy PLC integration complexity:Brownfield manufacturing environments require costly protocol translation layers to connect proprietary automation controllers with cloud-native robot fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cloud Robotics Market |
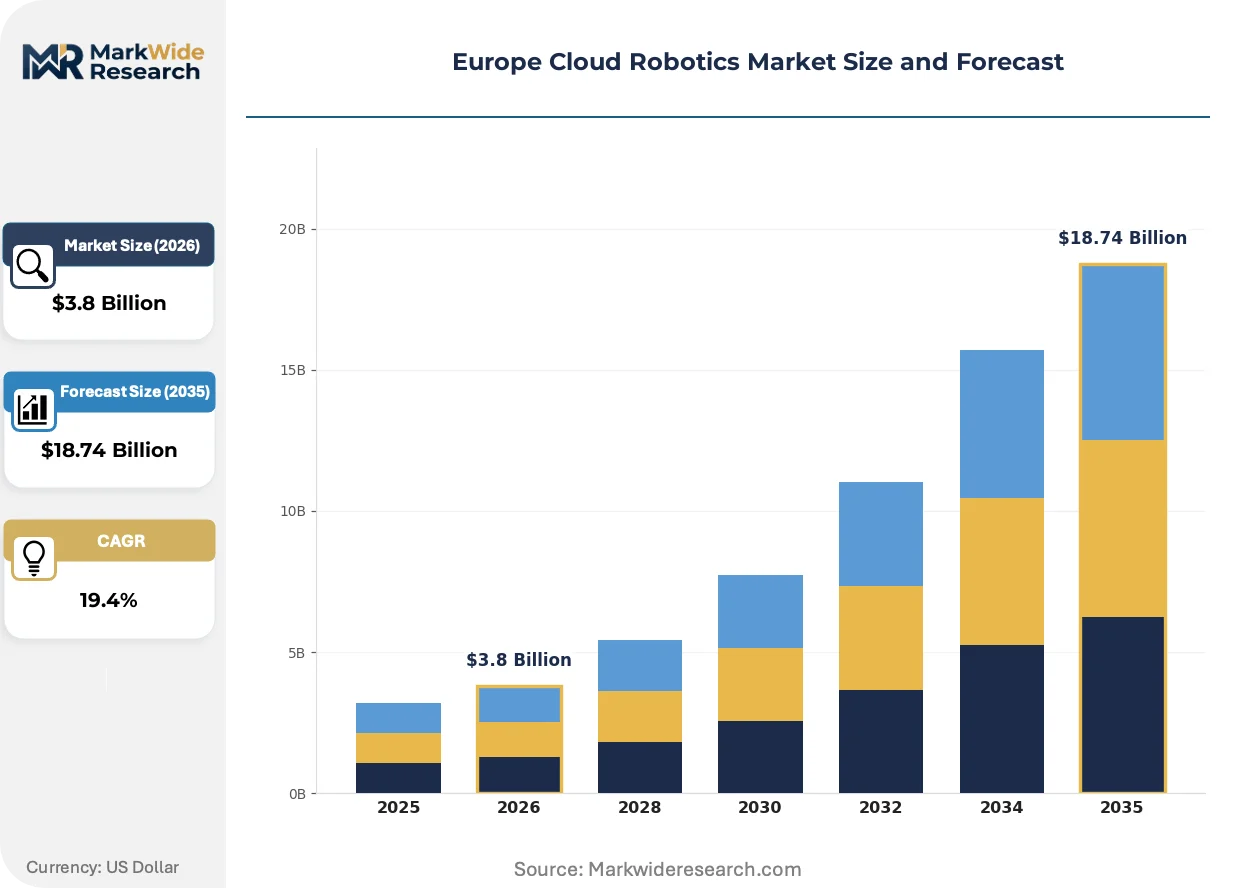
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Robots, Industrial Robots, Mobile Robots, Collaborative Robots Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Application: Healthcare, Logistics, Manufacturing, Agriculture End User: Enterprises, SMEs, Government Bodies, Educational Institutions |
| Companies Covered | Siemens, ABB, KUKA AG, Adept Technology, Rockwell Automation, NVIDIA Corporation, IBM Corporation, Microsoft Corporation, Universal Robots, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cloud Robotics Market Evolving Landscape
Edge-to-cloud inference architectures are compressing decision latency for safety-critical robotic applications while redistributing computational loads across factory networks.
GPU-accelerated edge nodes are electrifying real-time path planning and collision avoidance in collaborative robot arms. Automotive tier-one suppliers in Stuttgart and Munich are deploying these systems at pilot scale. The technology is electrifying competitive differentiation among vendors seeking to displace rule-based safety controllers.
The EU AI Act's high-risk system obligations are mandating human oversight interfaces and algorithmic audit trails for autonomous mobile robots. Industrial integrators must embed documentation workflows before CE marking submission. Healthcare robotics applications face additional EMA scrutiny on cloud-based medical device software, slowing cross-border patient data processing.
Robot-as-a-service contracting is unbundling capital expenditure from operational technology budgets among Dutch and Belgian SME manufacturers. Traditional equipment financing channels are losing share to usage-based pricing models. This shift concentrates most visibly in Benelux metal fabrication and food processing verticals.
Europe Cloud Robotics Market Segmentation
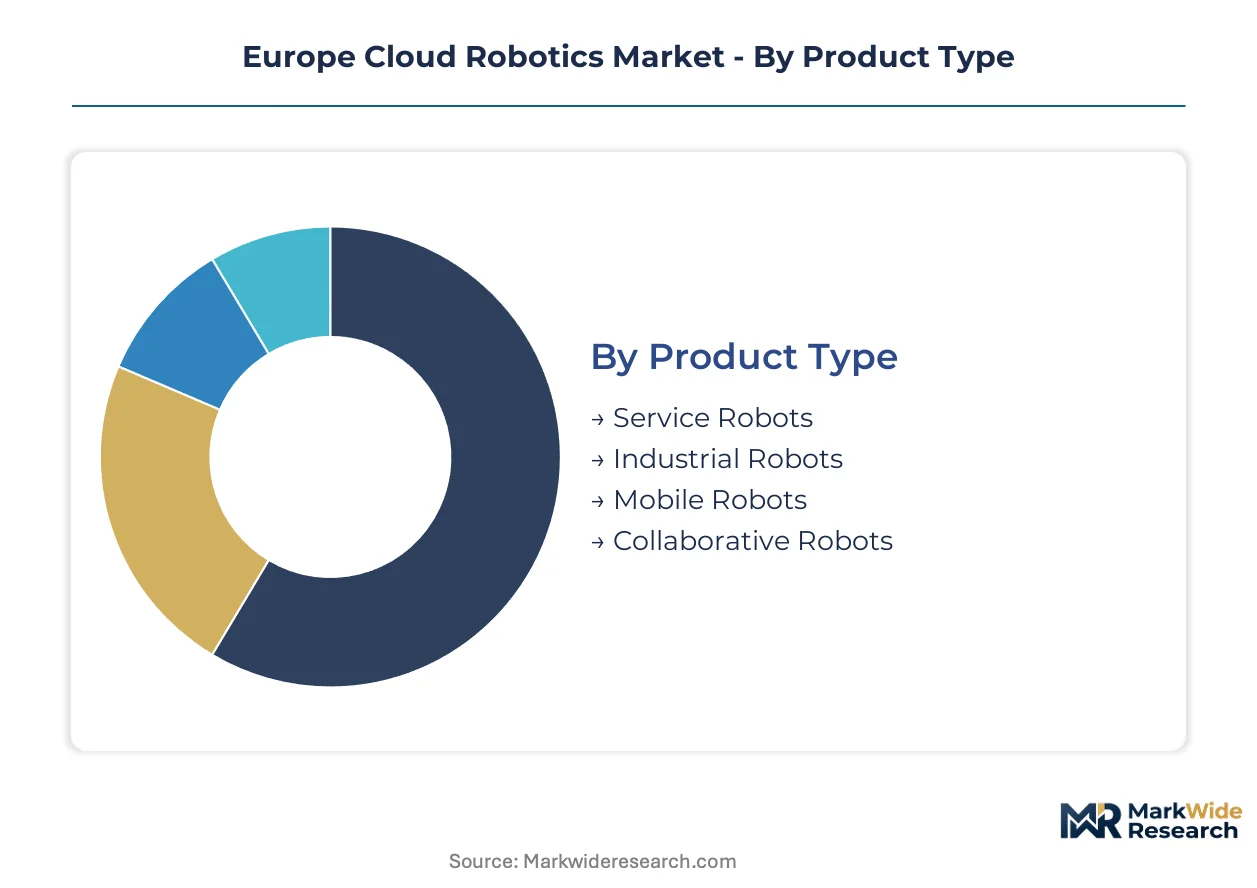
Cloud robotics segmentation in Europe reveals how computational offloading architectures, regulatory compliance tiers, and end-user sophistication levels create distinct commercial battlegrounds. Vendors configure pricing and service models around deployment sovereignty requirements and application risk classifications rather than hardware specifications alone.
Product Type:
Supply concentration in precision motion control hardware and GPU-accelerated inference chips shapes competitive dynamics across robot categories, with German and Italian component suppliers anchoring upstream value capture.
- Industrial Robots:Six-axis articulated arms and SCARA systems dominate factory floor cloud connectivity for powertrain assembly and battery pack production. German automotive OEMs in Stuttgart and Wolfsburg drive specification requirements for sub-50 millisecond latency in human-robot collaboration zones.
- Mobile Robots:Autonomous mobile robots (AMRs) with lidar-based navigation and fleet management software represent the steepest expansion trajectory in European warehousing. Dutch and Polish e-commerce fulfillment operators retrofit aging distribution centers with cloud-coordinated robot swarms.
- Service Robots:Non-industrial units for hospitality and facility management carry lighter computational loads with intermittent connectivity.
- Collaborative Robots:Force-limited arms with embedded safety sensors target SME manufacturers seeking plug-and-play automation without dedicated guarding infrastructure.
Today's leader: Industrial Robots. Tomorrow's challenger: Mobile Robots.
Deployment:
GDPR data localization mandates and sector-specific sovereignty requirements fragment cloud architecture preferences across European member states, creating pricing premiums for compliant configurations.
- Hybrid Cloud:Split processing between on-premise edge nodes and remote cloud infrastructure commands premium positioning in automotive and pharmaceutical verticals. French and German manufacturers pay surcharge rates for data residency guarantees under national cybersecurity frameworks.
- Public Cloud:Fully offloaded computation accelerates adoption among Benelux SMEs seeking zero capital expenditure models for seasonal production scaling.
- Private Cloud:Captive data center deployments satisfy defense and aerospace contractors with classified operational technology environments.
- Multi-Cloud:Redundant orchestration across AWS, Azure, and sovereign European providers mitigates vendor lock-in for critical infrastructure operators.
Hybrid Cloud captures current margin pools. Public Cloud expands addressable market breadth fastest.
Application:
Regulatory risk classifications under the EU AI Act segment addressable markets by compliance burden intensity, with high-risk autonomous systems facing extended certification timelines.
- Manufacturing:Cloud-connected production lines in Germany's industrial corridor generate the largest installed base, with predictive maintenance and digital twin convergence driving recurring software revenue.
- Logistics:Warehouse automation across Netherlands and Poland fulfillment networks climbs fastest as e-commerce operators compete on same-day delivery promises.
- Healthcare:Surgical and diagnostic robotics face EMA scrutiny on cloud-based medical device software, constraining cross-border patient data architectures.
- Agriculture:Precision farming robots with satellite-guided field mapping remain nascent in Southern European markets with fragmented land ownership patterns.
Manufacturing commands present revenue concentration. Logistics offers the steepest growth slope.
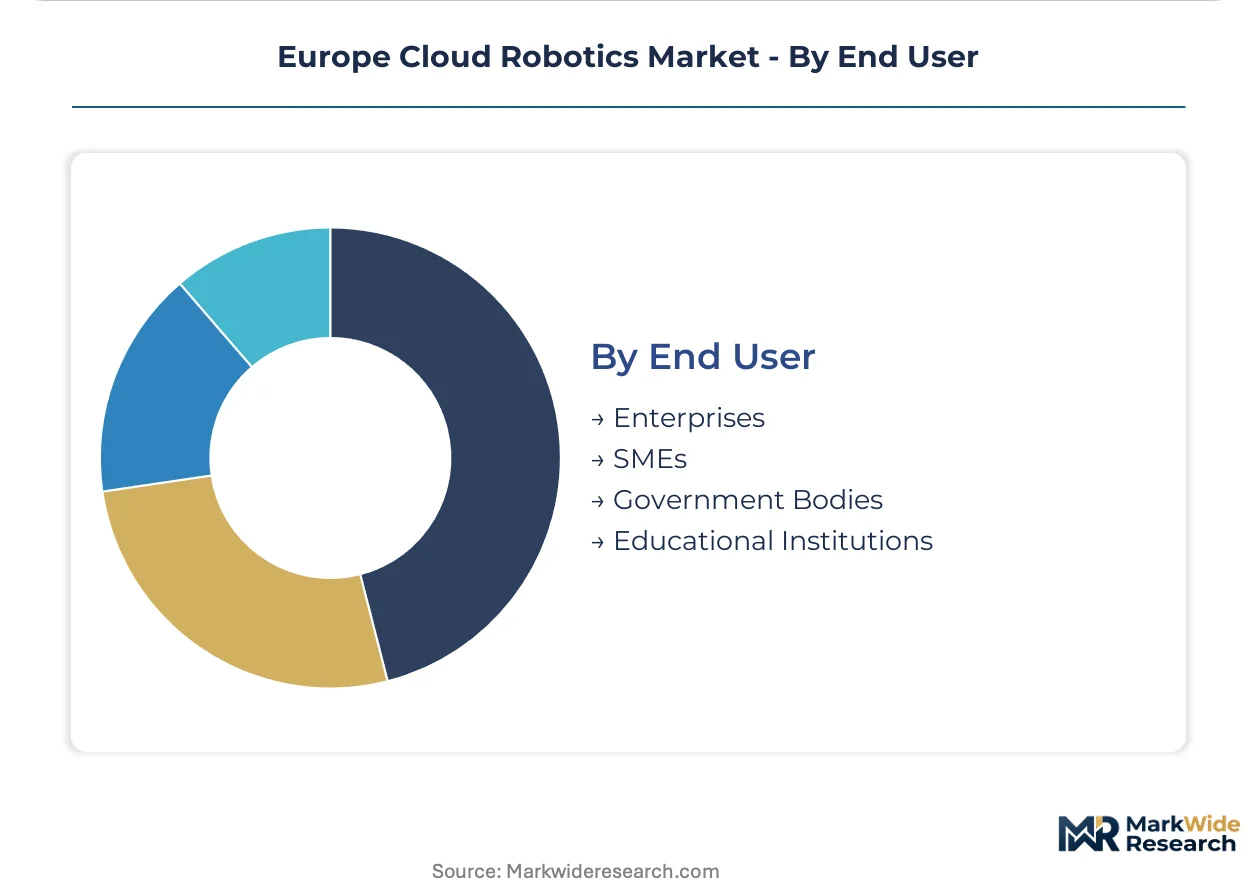
End User:
Procurement sophistication and balance sheet capacity determine contracting structure preferences, with robot-as-a-service models penetrating below the large-enterprise threshold.
- Enterprises:Multinational manufacturers with dedicated automation engineering teams negotiate multi-year digital twin contracts bundling hardware, software, and predictive analytics.
- SMEs:Usage-based pricing and rapid deployment timelines attract Dutch and Belgian metal fabrication and food processing operators lacking in-house robotics expertise.
- Government Bodies:Public infrastructure tenders under EU Green Deal procurement criteria embed energy efficiency metrics for cloud data center selection.
- Educational Institutions:Research universities in Munich and Zurich pilot human-robot interaction studies with subsidized cloud compute grants.
Enterprises anchor contract value. SMEs multiply addressable account density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where cloud robotics vendors concentrate compliance investments, with cost-of-compliance gaps between member states redirecting pilot deployments toward jurisdictions offering faster CE marking pathways under the Machinery Directive.
Germany
Automotive OEMs in Stuttgart, Munich, and Wolfsburg drive specification requirements for sub-50 millisecond latency in human-robot collaboration zones. The KBA and national cybersecurity frameworks mandate data residency guarantees for production telemetry. Baden-Württemberg's industrial corridor hosts the densest concentration of cloud-connected collaborative robot deployments on powertrain assembly lines.
France
Battery pack manufacturers near Paris and Lyon are expanding cloud-connected robot fleets for electric vehicle production scaling. ANSM and CNIL oversight on cross-border data flows complicates multi-site orchestration for pharmaceutical robotics. The Île-de-France region anchors sovereign cloud infrastructure investments serving aerospace and defense contractors with classified operational technology requirements.
Netherlands
E-commerce fulfillment operators in Rotterdam and Eindhoven retrofit aging distribution centers with cloud-coordinated autonomous mobile robot swarms. GDPR enforcement by the national data protection authority accelerates demand for hybrid edge-cloud architectures with localized inference nodes. The Randstad logistics corridor generates the steepest mobile robot deployment trajectory in Benelux.
Poland
Warehouse automation demand concentrates in Warsaw and Krakow as third-party logistics providers compete on same-day delivery promises. EU structural funds subsidize edge infrastructure buildout in industrial zones lacking sub-50 millisecond connectivity. The Central European logistics corridor presents untapped demand for mobile cloud robotics serving German and Austrian supply chain networks.
Italy
Metal fabrication SMEs in Lombardy and Emilia-Romagna adopt robot-as-a-service contracts to avoid capital expenditure concentration. CE marking timeline friction under the Machinery Directive extends product certification cycles for cloud-integrated designs originating from Italian integrators. The Northern Italy manufacturing belt pilots subscription-based software-defined control for seasonal production scaling.
Europe Cloud Robotics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with industrial automation incumbents commanding premium positioning in automotive verticals while software-native entrants capture SME adoption through usage-based pricing. The vendor landscape organizes around three strategic archetypes: diversified industrial conglomerates with digital twin portfolios, pure-play collaborative robot specialists, and GPU-accelerated inference platform suppliers. Consolidation pressure concentrates among mid-tier integrators lacking sovereign cloud capabilities. Dominant competitive moves include vertical integration into precision motion control hardware and strategic partnerships with sovereign cloud infrastructure providers.
Among diversified industrial conglomerates, Siemens and ABB exemplify archetypes anchoring recurring revenue through bundled hardware-software-service contracts. KUKA AG occupies a position within the pure-play collaborative robot specialist tier, representing deep specialization in cloud-native architectures for automotive human-robot collaboration zones. NVIDIA Corporation sits within the accelerated computing supplier archetype, supplying inference silicon that enables real-time robotic decision-making across vendor ecosystems.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| KUKA AG |
| Adept Technology |
| Rockwell Automation |
| NVIDIA Corporation |
| IBM Corporation |
| Microsoft Corporation |
| Universal Robots |
| Others |
Value Network & Pricing Analysis
EU Green Deal energy efficiency metrics for cloud data centers gate qualified supply and premium-tier pricing access for robotic automation projects, as vendors must demonstrate compliance with carbon intensity thresholds to compete for public infrastructure tenders in Germany and France.
Pricing Analysis
Capacity additions in Netherlands and Poland are reshaping price floors for mobile robot fleet deployments as e-commerce fulfillment operators scale same-day delivery infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEMs with digital twin bundling from SME manufacturers on usage-based contracts and commodity hardware resellers. Pricing pressure stems from GPU supply concentration as NVIDIA's dominance in accelerated inference silicon constrains procurement options for real-time decision-making systems. SMEs exhibit highest price sensitivity, while German automotive manufacturers absorb premium surcharges for data residency guarantees under KBA cybersecurity frameworks.
Supply Chain Analysis
Mechatronics-cloud engineering talent scarcity across Stuttgart, Munich, and Milan constrains component assembly capacity for precision motion control hardware. Supply concentration rests on German and Italian suppliers for precision motion control hardware, Taiwanese foundries for GPU-accelerated inference chips, and Dutch integrators for fleet management software. Dependencies include rare earth magnets for servo motors, high-purity silicon for edge computing nodes, and specialized optical sensors for collaborative robot safety systems. Single-source vulnerability in NVIDIA's GPU architecture creates procurement bottlenecks. Distribution runs through systems integrators with sovereign cloud partnerships for hybrid edge-cloud deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European cloud robotics hinges on subscription-based software-defined control architectures decoupling recurring revenue from capital equipment cycles.
For Market Incumbents: Lock in automotive OEM relationships through multi-year digital twin contracts bundling predictive maintenance analytics with hardware refresh cycles. Deepen backward integration into precision motion control hardware to displace Italian component suppliers. CE marking timeline friction under the Machinery Directive threatens margin compression for vendors lacking embedded safety documentation pipelines. For New Entrants and Emerging Players: Enter via Polish warehouse automation corridors where EU structural funds subsidize edge infrastructure buildout and third-party logistics providers compete on delivery velocity. Target SME manufacturers in Benelux metal fabrication and food processing verticals with robot-as-a-service pricing that eliminates capital expenditure concentration. Lead with rapid deployment timelines and usage-based contracting to displace traditional equipment financing channels. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier systems integrators lacking sovereign cloud capabilities because GDPR data localization mandates fragment procurement decisions across member states. Five-to-ten year viability favors vendors with hybrid edge-cloud architectures serving automotive and pharmaceutical verticals. Watch CE marking approval velocity under the Machinery Directive as inflection indicator for product certification cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | GDPR compliance under CNIL and KBA frameworks unlocks German and French public infrastructure tenders. |
| GPU-Accelerated Edge Node Deployment | NVIDIA inference silicon enables sub-50 millisecond response times for safe human-robot collaboration zones. |
| Digital Twin Platform Integration | Siemens physics simulation convergence anchors recurring revenue across automotive OEM maintenance contracts. |
| CE Marking Pathway Investment | Machinery Directive conformity assessment compression reduces 8-14 month certification cycles for novel designs. |
| Robot-as-a-Service Launch | Usage-based pricing penetrates Dutch and Belgian SME manufacturers lacking in-house robotics expertise. |
Research Methodology
Bottom-up manufacturing and logistics modeling reconciled against top-down GPU supply and cloud infrastructure tracking forms the analytical core of this study. Primary interviews with plant engineers at German automotive OEMs, procurement leads at Dutch e-commerce fulfillment operators, robotics integration specialists, and EMA regulatory affairs officers combined with secondary validation from CE marking databases, EU structural fund disbursement records, hyperscaler capex disclosures, and customs trade data for precision motion control components.
Input-output matrices mapped cloud robotics deployment volumes against segmentation dimensions including robot category, deployment architecture sovereignty tier, application risk classification under the EU AI Act, and end-user procurement sophistication. CAGRs derived from elasticity modeling of software subscription attach rates and hardware replacement cycles across the projection horizon. Industry-specific forecast inputs incorporated edge infrastructure buildout timelines in Polish industrial zones and CE marking approval velocity under the Machinery Directive.
Inputs from EMA guidance documents and KBA cybersecurity frameworks were available through the study window; gaps in real-time latency infrastructure deployment across Eastern European industrial zones introduce uncertainty bands around mobile robot adoption trajectories. Forecasts reflect documented assumptions regarding GDPR enforcement consistency and GPU supply availability. Material deviation in EU AI Act implementation timelines or NVIDIA foundry capacity allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market