
 Exoskeleton Systems Market | 2026-2036
Exoskeleton Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Exoskeleton Systems Market Analysis
Project finance and equipment-leasing structures is fragmenting competitive access across the exoskeleton sector, lowering capital barriers for rehabilitation clinics and mid-sized industrial buyers. Ekso Bionics leverages hospital partnerships to sustain recurring revenue streams in neurorehabilitation. Ottobock anchors European distribution through its established orthotics channel network. Lockheed Martin Corporation dominates defense-sector prototyping with ONYX load-bearing systems for infantry applications.
Exoskeleton systems are wearable robotic frameworks incorporating electric motors, pneumatic actuators, or passive spring mechanisms to augment, assist, or restore human movement, typically weighing 12–25 kg for rigid industrial units and under 3 kg for soft textile-based designs. Their primary purpose spans mobility restoration for paraplegic patients, repetitive-task endurance for manufacturing workers, and load redistribution for military personnel carrying 45–90 kg combat payloads. Rigid exoskeletons currently occupy the largest installed base in healthcare rehabilitation centers, while soft exoskeletons represent the fastest-expanding category due to lower unit costs and reduced calibration requirements. Active exoskeletons command premium pricing positions where battery density and sensor fusion enable real-time gait adaptation, whereas passive systems compete on maintenance simplicity in construction and logistics settings.
FDA breakthrough device designation and ISO 13485 quality management standards shape product development timelines and market access thresholds for medical-grade systems in the United States. Japan's PMDA and Germany's national reimbursement frameworks determine adoption velocity for neurological and geriatric applications across their respective health systems. Stakeholders must monitor evolving workers' compensation precedents in industrial jurisdictions, as liability allocation between employers and exoskeleton suppliers remains unresolved in most legal codes.
Market Dynamics
Load-bearing military exoskeleton procurement programs and FDA breakthrough device pathways are compressing clinical validation timelines while fragmenting capital access across rehabilitation and industrial buyer segments.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for wearable rehabilitation systems shorten time-to-market for spinal cord injury and stroke recovery applications in the United States.
- Battery energy density improvements:Lithium-sulfur and solid-state cell architectures extend operational endurance for active exoskeletons beyond four hours per charge cycle.
- Japan's national reimbursement framework:PMDA-approved HAL systems receive full insurance coverage for neurological rehabilitation, establishing precedent for payer acceptance.
Market Restraints
- High-grade titanium and carbon fiber input costs:Aerospace-grade material pricing volatility constrains margins for rigid-frame industrial exoskeleton manufacturers.
- Single-source actuator supply concentration:Precision harmonic drive production concentrates in German and Japanese specialty manufacturers, creating procurement bottlenecks.
- ISO 13485 certification timelines:Medical device quality management audits extend 12–18 months for first-time entrants, delaying market access.
Strategic Opportunities
- Soft exoskeleton penetration in logistics:Textile-based assistive suits address repetitive lifting injuries in warehouse operations with sub-$10,000 unit economics.
- Convergence of sensor fusion and edge AI:Real-time gait prediction algorithms enable anticipatory motor assistance without explicit user input commands.
- Germany's BMAS occupational safety incentives:Federal subsidies for workplace ergonomic equipment reduce employer capex barriers for industrial exoskeleton adoption.
Industry Challenges
- Biomechanical calibration expertise scarcity:Shortage of rehabilitation engineers trained in neuromuscular interface tuning limits clinical deployment velocity.
- Legacy EMR integration complexity:Proprietary data protocols from exoskeleton gait analytics resist seamless incorporation into hospital electronic medical record systems.
- Cross-jurisdictional liability allocation:Workers' compensation precedents remain unsettled regarding fault determination between equipment suppliers and deploying employers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exoskeleton Systems Market |
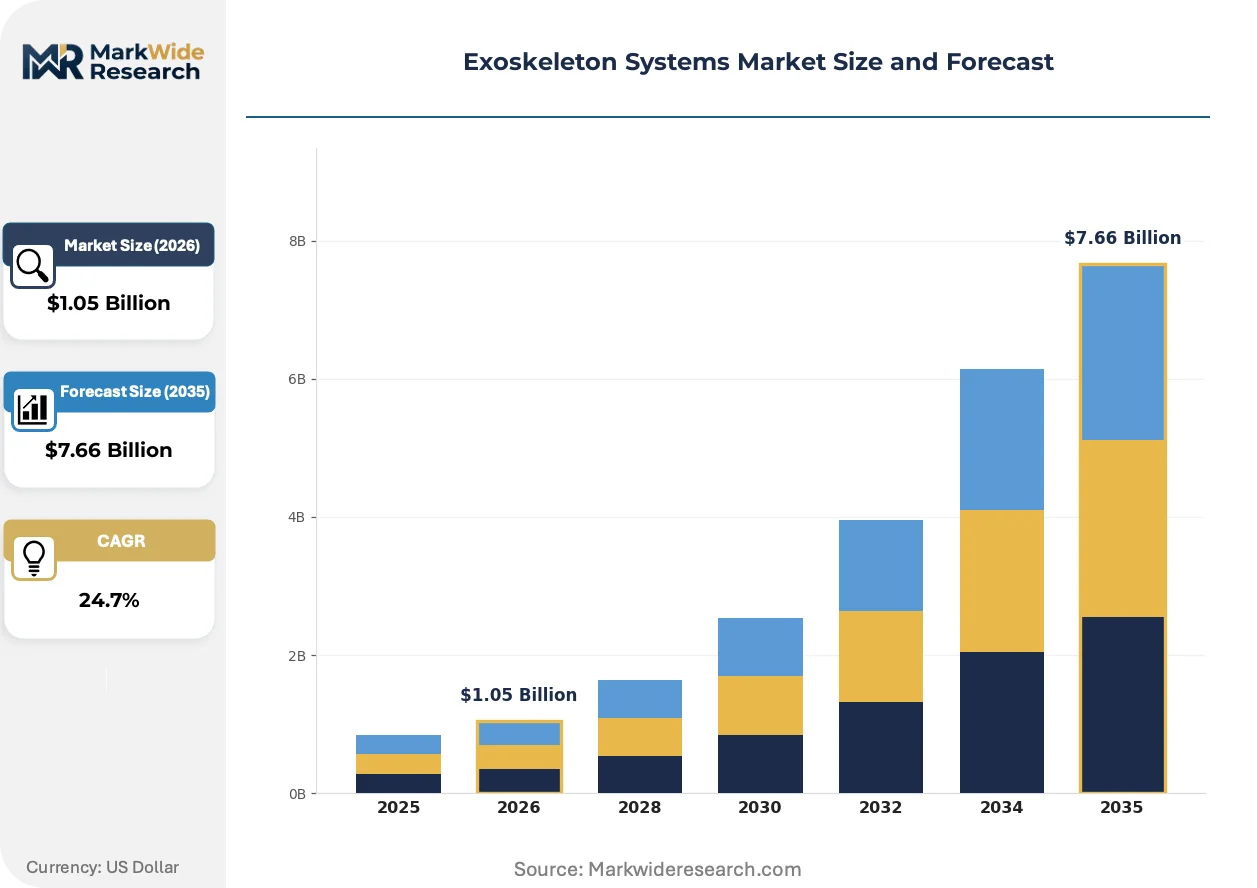
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $7.66 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Exoskeletons, Soft Exoskeletons, Active Exoskeletons, Passive Exoskeletons Industry Vertical: Healthcare, Military, Construction, Manufacturing End User: Soldiers, Workers, Patients, Rehabilitation Centers Functionality: Mobility Assistance, Rehabilitation Support, Load-bearing, Motion Enhancement |
| Companies Covered | Ekso Bionics, Ottobock, Cyberdyne Inc., Lockheed Martin Corporation, Parker Hannifin Corporation, Sarcos Technology and Robotics Corporation, ReWalk Robotics, Rex Bionics Plc., Hocoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exoskeleton Systems Market Emerging Trajectories
Control architectures are migrating from centralized processing to distributed edge computing, compressing latency for real-time movement assistance while enabling lighter onboard hardware configurations.
Sensor fusion is migrating from inertial measurement units alone to multimodal arrays incorporating surface electromyography and pressure mapping. Rehabilitation clinics in the United States are adopting these enhanced systems for stroke patient gait retraining. The technology is migrating from laboratory settings to outpatient facilities, compressing the calibration overhead per patient session.
EU MDR Class IIa classification requirements for active therapeutic devices are forcing redesigns of powered lower-limb systems intended for European commercialization. Manufacturers must demonstrate clinical equivalence through notified body review, extending documentation burdens. German and French orthopedic distributors are prioritizing CE-marked inventory over unregistered alternatives, reshaping supplier qualification criteria.
Hospital procurement departments are unbundling hardware acquisition from maintenance and software update subscriptions. Neurorehabilitation centers in Japan and the United States now negotiate three-year total cost of ownership contracts rather than capital purchase agreements. This behavioral shift compresses vendor cash conversion cycles while elevating service revenue visibility as a competitive differentiator.
Exoskeleton Systems Market Segmentation
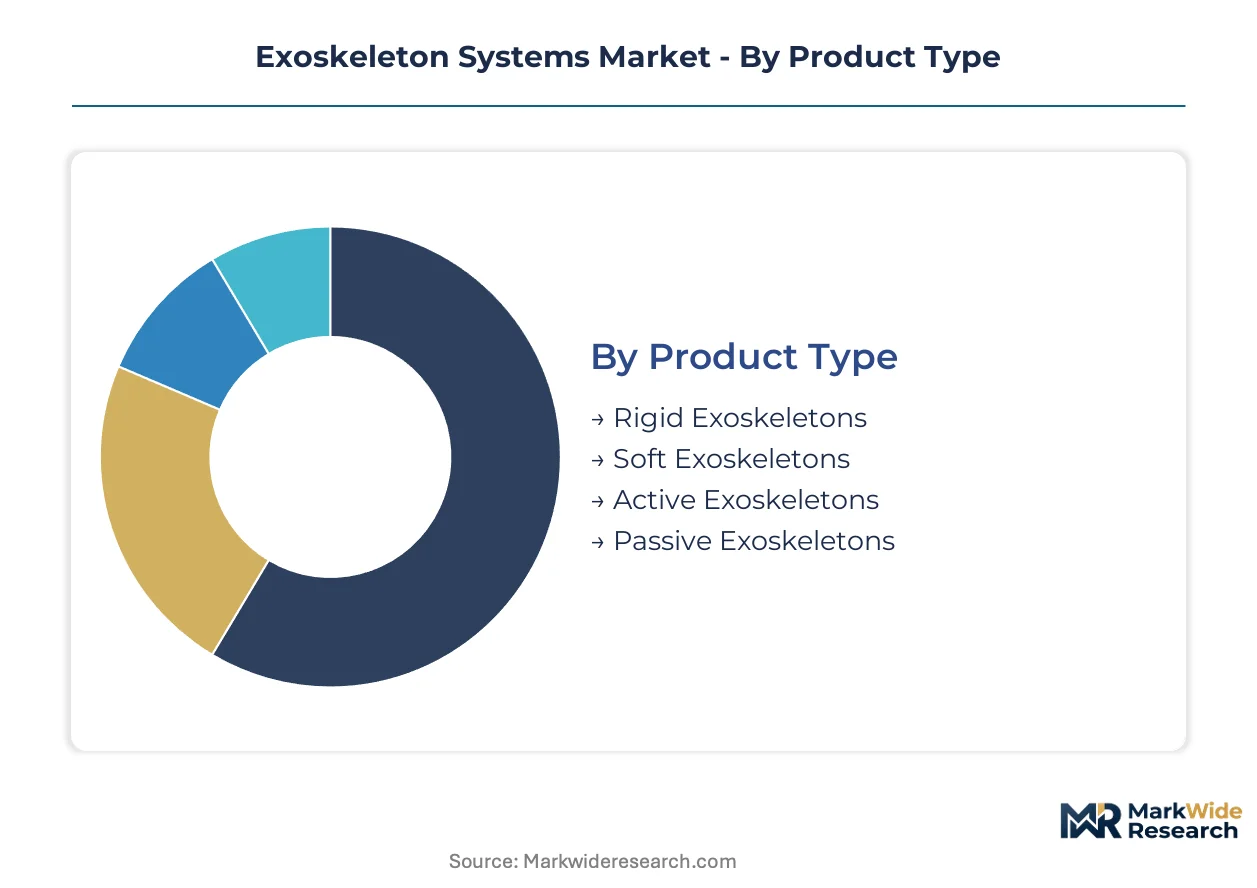
Segmentation in the exoskeleton sector reveals divergent replacement cycles across product architectures. Rigid systems in rehabilitation settings operate on 7-10 year depreciation schedules, while soft textile-based units in logistics turn over every 2-3 years due to wear and lower capital commitment.
Product Type:
Cycle times stretch from multi-year healthcare installations to rapid industrial refresh schedules, with passive systems outlasting active alternatives due to battery lifecycle constraints.
- Rigid Exoskeletons:Titanium and carbon fiber frames with electric motor arrays weigh 12-25 kg and require clinical calibration protocols. Demand concentrates in United States rehabilitation centers where FDA breakthrough device pathways accelerate reimbursement negotiations, though ISO 13485 certification timelines delay first-time vendor entry.
- Soft Exoskeletons:Textile-based designs with pneumatic actuation or elastic assistance weigh under 3 kg and deploy without structural mounting. Japanese logistics operators and German warehouse networks drive procurement for repetitive lifting injury prevention, with unit economics below $10,000 enabling fleet-scale adoption.
- Active Exoskeletons:Battery-powered systems with real-time sensor fusion and gait adaptation algorithms command premium positioning in neurorehabilitation.
- Passive Exoskeletons:Spring and counterbalance mechanisms redistribute load without power dependency, dominating construction and military logistics applications.
Rigid exoskeletons dominate installed base. Soft exoskeletons are where expansion concentrates.
Industry Vertical:
Cost tiers stratify sharply, with military procurement absorbing unit prices 4-5x above industrial segments due to performance specifications and battlefield reliability requirements.
- Healthcare:Spinal cord injury therapy and stroke rehabilitation drive demand for FDA and PMDA-approved systems with clinical validation requirements. United States neurorehabilitation centers and Japanese hospitals with HAL system reimbursement coverage represent concentrated demand pools, though biomechanical calibration expertise scarcity limits deployment velocity.
- Military:Load-bearing systems for 45-90 kg combat payloads require ONYX-class prototypes with infantry mobility specifications. United States procurement programs anchor development funding, with Lockheed Martin Corporation securing defense-sector prototyping contracts for extended endurance missions.
- Construction:Ergonomic load redistribution for overhead work and material handling addresses repetitive strain injury costs.
- Manufacturing:Assembly line endurance extension for repetitive task operations targets automotive and electronics production facilities.
Healthcare captures premium pricing tiers. Manufacturing is climbing the fastest on volume scaling.
End User:
Customer sophistication varies from institutional procurement departments with total cost of ownership modeling to individual patient financing through medical leasing structures.
- Soldiers:Military personnel require load-bearing augmentation for extended patrol endurance and injury prevention during heavy equipment transport.
- Workers:Industrial operators in logistics and construction deploy assistive systems for shift-long ergonomic protection, with Germany's BMAS occupational safety incentives reducing employer capex barriers.
- Patients:Individuals with spinal cord injuries, stroke survivors, and neurological condition patients access systems through rehabilitation prescriptions and national reimbursement frameworks.
- Rehabilitation Centers:Institutional buyers negotiate unbundled hardware and service contracts, with United States and Japanese facilities shifting from capital purchase to three-year subscription agreements.
Rehabilitation centers dominate institutional procurement volume. Workers represent the steepest expansion trajectory as industrial adoption accelerates.
Functionality:
Application maturity spans decades of clinical research in mobility restoration versus emerging demand for motion enhancement in performance-oriented settings.
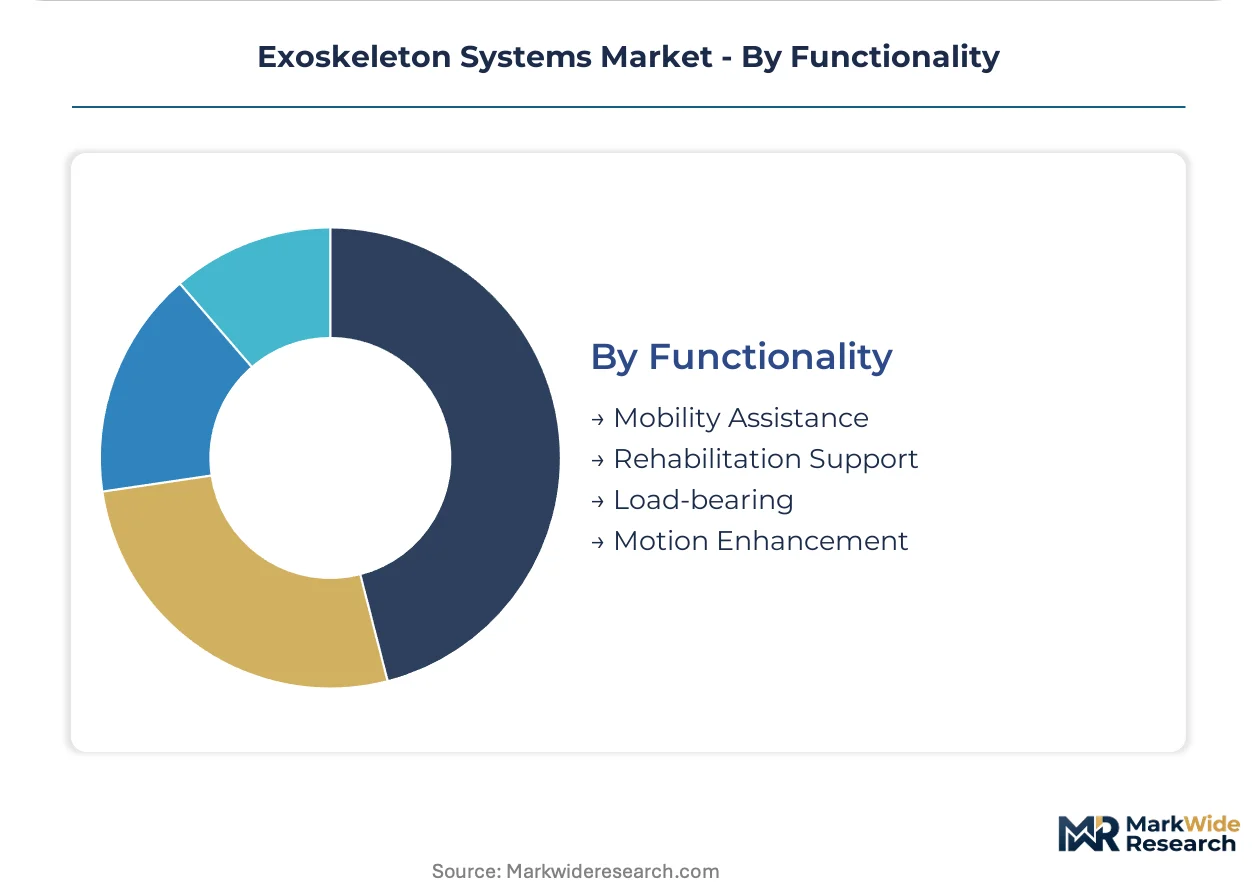
- Mobility Assistance:Paraplegic ambulation and gait restoration for spinal cord injury patients requires precise motor control and safety redundancy systems.
- Rehabilitation Support:Post-stroke gait retraining and neuromuscular recovery protocols leverage sensor fusion with surface electromyography integration in United States outpatient facilities.
- Load-bearing:Weight redistribution for military combat payloads and industrial material handling addresses musculoskeletal injury prevention.
- Motion Enhancement:Performance augmentation for extended endurance and strength multiplication targets specialized military and industrial applications.
Rehabilitation support holds established clinical protocols. Motion enhancement is gaining share fastest from defense R&D spillover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA reimbursement framework for HAL systems established the first national insurance coverage precedent for robotic rehabilitation, prompting Germany's BMAS and the US FDA to accelerate parallel incentive structures for clinical and industrial exoskeleton adoption.
United States
Military procurement programs through the Defense Advanced Research Projects Agency drive load-bearing system development for 45-90 kg combat payloads. FDA breakthrough device designation pathways compress clinical validation timelines for wearable rehabilitation systems from 36 to 18 months. Neurorehabilitation centers in Boston and San Francisco unbundle hardware acquisition from three-year service subscriptions, elevating recurring revenue visibility for vendors.
Germany
BMAS occupational safety incentives subsidize workplace ergonomic equipment, reducing employer capex barriers for logistics and construction exoskeleton deployment. EU MDR Class IIa classification requirements force redesigns of powered lower-limb systems, extending documentation burdens through notified body review. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate automotive assembly line trials for repetitive-task endurance systems.
Japan
PMDA-approved HAL systems receive full national health insurance coverage for spinal cord injury therapy, establishing the world's first comprehensive payer acceptance model for robotic rehabilitation. METI funding programs support soft exoskeleton development for aging workforce assistance. Tokyo and Osaka rehabilitation hospitals operate the largest installed base of clinical-grade active systems outside the United States.
China
NMPA medical device registration requirements create 14-24 month approval timelines for imported rehabilitation systems, favoring domestic manufacturers with abbreviated review pathways. MIIT industrial robotics initiatives channel subsidies toward manufacturing exoskeleton pilots in automotive and electronics sectors. Yangtze River Delta logistics operators trial sub-$10,000 textile-based assistive suits for warehouse injury prevention.
South Korea
MFDS fast-track designation for breakthrough rehabilitation devices mirrors FDA pathways, accelerating market access for stroke recovery applications. National robotics R&D programs under the Ministry of Trade, Industry and Energy fund motion enhancement prototypes for industrial and defense spillover. Seoul Capital Area rehabilitation centers adopt sensor fusion systems with surface electromyography integration for outpatient gait retraining.
Exoskeleton Systems Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: defense contractors with military prototyping relationships, established medical device manufacturers with orthotics distribution networks, and venture-backed specialists in soft textile systems. Strategic archetypes include platform-integrated hardware vendors, component subsystem suppliers, and software-centric gait analytics providers. Competitive moves concentrate on hospital partnership structures for recurring revenue and European distribution channel qualification under EU MDR requirements.
Among defense-sector contractors, Lockheed Martin Corporation anchors military load-bearing development through ONYX-class infantry prototypes. Ekso Bionics and Cyberdyne Inc. occupy positions within the medical-grade rehabilitation tier, with the former leveraging United States hospital network partnerships and the latter securing Japan's national reimbursement precedent. Ottobock represents the orthotics-integrated archetype, distributing through established European clinical channels.
| Leading Market Players |
|---|
| Ekso Bionics |
| Ottobock |
| Cyberdyne Inc. |
| Lockheed Martin Corporation |
| Parker Hannifin Corporation |
| Sarcos Technology and Robotics Corporation |
| ReWalk Robotics |
| Rex Bionics Plc. |
| Hocoma |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into landed pricing for German-manufactured harmonic drives and Japanese carbon fiber prepregs, compressing margins for rigid-frame producers while amplifying price spreads between FDA-certified medical systems and uncertified industrial alternatives. Buyers in United States rehabilitation centers and Japanese logistics operators face divergent total cost of ownership calculations as certification premiums widen.
Pricing Analysis
Certification grade creates the primary spread across exoskeleton pricing tiers, with ISO 13485 and FDA breakthrough-designated systems commanding substantial premiums over CE-marked industrial alternatives. The dominant structure combines hardware acquisition with mandatory service subscriptions, particularly in neurorehabilitation where three-year total cost of ownership contracts now prevail. Price differentiation rests on clinical validation depth and battery energy density specifications. Cost compression in soft textile systems is intensifying as Chinese manufacturers scale pneumatic actuator production. Industrial buyers in German logistics represent the most price-sensitive segment, while United States military procurement shows minimal elasticity for load-bearing performance specifications.
Supply Chain Analysis
Aerospace-grade titanium feedstock from Japanese and Russian smelters anchors rigid exoskeleton frame production, with carbon fiber prepregs sourcing from Toray's Japanese and South Korean facilities. Precision harmonic drives for active systems concentrate in German and Japanese specialty manufacturers, creating single-source vulnerability for gait adaptation mechanisms. Battery cell architectures draw from South Korean and Chinese suppliers, with solid-state prototypes tethered to Japanese pilot production lines. Distribution runs through established orthotics channels in Europe and direct hospital system contracts in the United States, with emerging logistics fleet sales bypassing traditional clinical intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States hospital procurement consortia and Japanese national health insurance administrators, fragmenting vendor pricing leverage as institutional purchasers unbundle hardware from service subscriptions.
For Market Incumbents: Pre-empt emerging soft exoskeleton specialists by acquiring textile actuator technology or licensing pneumatic assistance patents before logistics fleet adoption scales. Lockheed Martin's defense-sector prototyping relationships and Ekso Bionics' hospital network partnerships illustrate channel control leverage that newcomers cannot replicate quickly. Invest in ISO 13485 certification maintenance as EU MDR documentation burdens extend competitive moats against undercapitalized entrants. For New Entrants and Emerging Players: Mid-market German automotive assembly plants represent the most penetrable entry point for repetitive-task endurance systems, with BMAS occupational safety subsidies reducing employer capex barriers and Ottobock's orthotics channel presence leaving gaps in direct OEM sales. South Korean stroke rehabilitation clinics adopting surface electromyography-integrated systems offer a secondary beachhead through MFDS fast-track designation pathways. A software-centric go-to-market angle—gait analytics without hardware manufacturing—circumvents capital-intensive frame production while capturing recurring revenue from sensor fusion subscriptions. For Investors and Strategic Acquirers: Component subsystem suppliers with captive harmonic drive or battery management expertise present acquisition targets with defensive positioning as supply concentration intensifies. Long-term viability in this market hinges on reimbursement strategy execution rather than hardware innovation alone, given Japan's HAL precedent and FDA breakthrough pathway acceleration. Watch for PMDA or FDA decisions on soft exoskeleton national coverage as the signal indicating inflection from pilot deployment to fleet-scale industrial adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Ekso Bionics' recurring revenue model with United States neurorehabilitation centers demonstrates subscription economics viability. |
| Reimbursement Strategy | Cyberdyne's PMDA-approved HAL coverage established precedent for payer acceptance in spinal cord injury therapy. |
| CE Marking Pathway | EU MDR Class IIa classification forces redesigns that reshape supplier qualification criteria for German distributors. |
| Software Companion Development | Real-time gait prediction algorithms enable anticipatory motor assistance without explicit user input commands. |
| Backward Integration into Actuators | In-house harmonic drive production mitigates single-source vulnerability from German and Japanese specialty manufacturers. |
Methodological Framework
Cross-validation between primary interviews with rehabilitation engineers, hospital procurement managers, biomedical engineers, and GPO contracts managers and secondary sources including FDA 510(k) filings, PMDA approval databases, EU MDR notified body decisions, and hospital procurement contract records anchors the qualitative findings. Bottom-up unit economics modeling for soft versus rigid system architectures triangulates against top-down market sizing from defense procurement disclosures and national reimbursement expenditure data.
Calibration against historical adoption curves for Class II medical devices and industrial robotics penetration rates informs the projection framework across the analysis window. Segmentation dimensions include product architecture, functionality application, end-user sophistication, and regional regulatory cluster. CAGR derivation incorporates battery energy density improvement trajectories, ISO 13485 certification timeline distributions, and workers' compensation precedent evolution in industrial jurisdictions.
Practitioners should monitor FDA breakthrough device designation grant rates, PMDA reimbursement expansion decisions, and German BMAS subsidy program renewals for early signals requiring forecast revision. Cross-checking against disclosed defense R&D budgets and automotive assembly line automation capex is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
North America Cloud Robotics Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Airport Robots Market
Robotics and Automation
Quadruped Robot Market