
 Soft Exoskeleton Market | 2026-2036
Soft Exoskeleton Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Exoskeleton Market Analysis
ISO 13485 certification is redrawing competitive boundaries for soft exoskeleton manufacturers seeking healthcare market access. Ekso Bionics leverages its rehabilitation specialization to sustain clinical trial partnerships across North American and European hospital networks. Cyberdyne anchors its position through upstream control over hybrid assistive limb neuromuscular signal processing, while Ottobock competes via its established orthotics distribution infrastructure and payer relationships.
Soft exoskeletons are textile-based wearable structures integrating elastomeric actuators, conductive sensing fabrics, and closed-loop control systems to augment, assist, or restore human biomechanical function without rigid skeletal frames. These devices typically operate at power-to-weight ratios below 50 W/kg and rely on pneumatic artificial muscles or cable-driven mechanisms to reduce metabolic cost during repetitive or load-bearing tasks. Assistive and rehabilitation product types currently command the deepest reimbursement pathways, while industrial applications in heavy lifting are attracting the fastest-growing enterprise procurement budgets as OSHA-recordable musculoskeletal disorder claims drive employer liability. Wearable sensors and soft materials technologies concentrate the most active patent filings, though actuation systems capture the highest unit margins due to specialized pneumatic valve and miniature motor supply constraints.
FDA 510(k) clearance timelines and the EU Medical Device Regulation's Class IIa classification requirements shape product development roadmaps and capital allocation for soft exoskeleton developers. Japan's PMDA and METI coordinate on conditional early approval frameworks for nursing care robotics, accelerating domestic adoption while creating template regulatory precedents. Stakeholders must monitor evolving reimbursement codes for wearable therapeutic devices across national health technology assessment bodies.
Market Dynamics
ISO 13485 certification requirements and EU MDR Class IIa conformity assessments are restructuring competitive access for soft exoskeleton manufacturers, forcing capital reallocation toward quality management systems and clinical validation infrastructure ahead of product commercialization.
Growth Catalysts
- MDR pathway harmonization:EU Medical Device Regulation's standardized Class IIa classification for powered wearables reduces regulatory fragmentation across Germany, France, and Italy, accelerating multi-market deployment timelines for compliant manufacturers.
- Pneumatic artificial muscle advances:Elastomeric actuator energy density improvements above 40 W/kg enable lighter industrial assistive devices, expanding addressable tasks in construction and logistics material handling.
- Japan's nursing care robotics framework:METI and PMDA conditional early approval mechanisms compress time-to-revenue for stroke rehabilitation devices, establishing regulatory templates adopted by South Korean and Australian assessment bodies.
Market Restraints
- Specialized valve supply concentration:Miniature pneumatic valve manufacturing concentrates among German and Japanese precision component suppliers, creating single-source vulnerability for actuation system producers.
- FDA 510(k) timeline variability:Rehabilitation device clearance durations fluctuate based on predicate device availability, delaying capital recovery for developers without established clinical trial partnerships.
- Conductive fabric cost structure:Silver-coated nylon sensing textiles face precious metal price volatility, compressing margins for textile-integrated soft exoskeleton producers at volume scale.
Strategic Opportunities
- OSHA-recordable claim reduction:US employers facing rising musculoskeletal disorder liability premiums are piloting industrial soft exoskeleton leasing programs, creating outcome-based procurement models tied to incident rate reductions.
- Closed-loop control convergence:Integration of surface electromyography with inertial measurement units enables intent-predictive assistance, opening premium positioning for hybrid signal processing architectures in rehabilitation settings.
- Construction workforce aging:Japan's 65-plus worker demographic concentration drives public procurement of mobility support devices for load-bearing tasks, with transferable deployment models for Germany and South Korea aging workforces.
Industry Challenges
- Biomechanist talent scarcity:Human movement modeling expertise required for control algorithm development concentrates within academic research institutions, forcing manufacturers into costly university partnership structures.
- Multi-site clinical validation costs:ISO 14155-compliant trials across three or more hospital networks demand seven-figure capital commitments before MDR technical documentation submission.
- Legacy EMR integration complexity:Rehabilitation device data streams require HL7 FHIR interface development for electronic medical record compatibility, extending deployment timelines within hospital procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Exoskeleton Market |
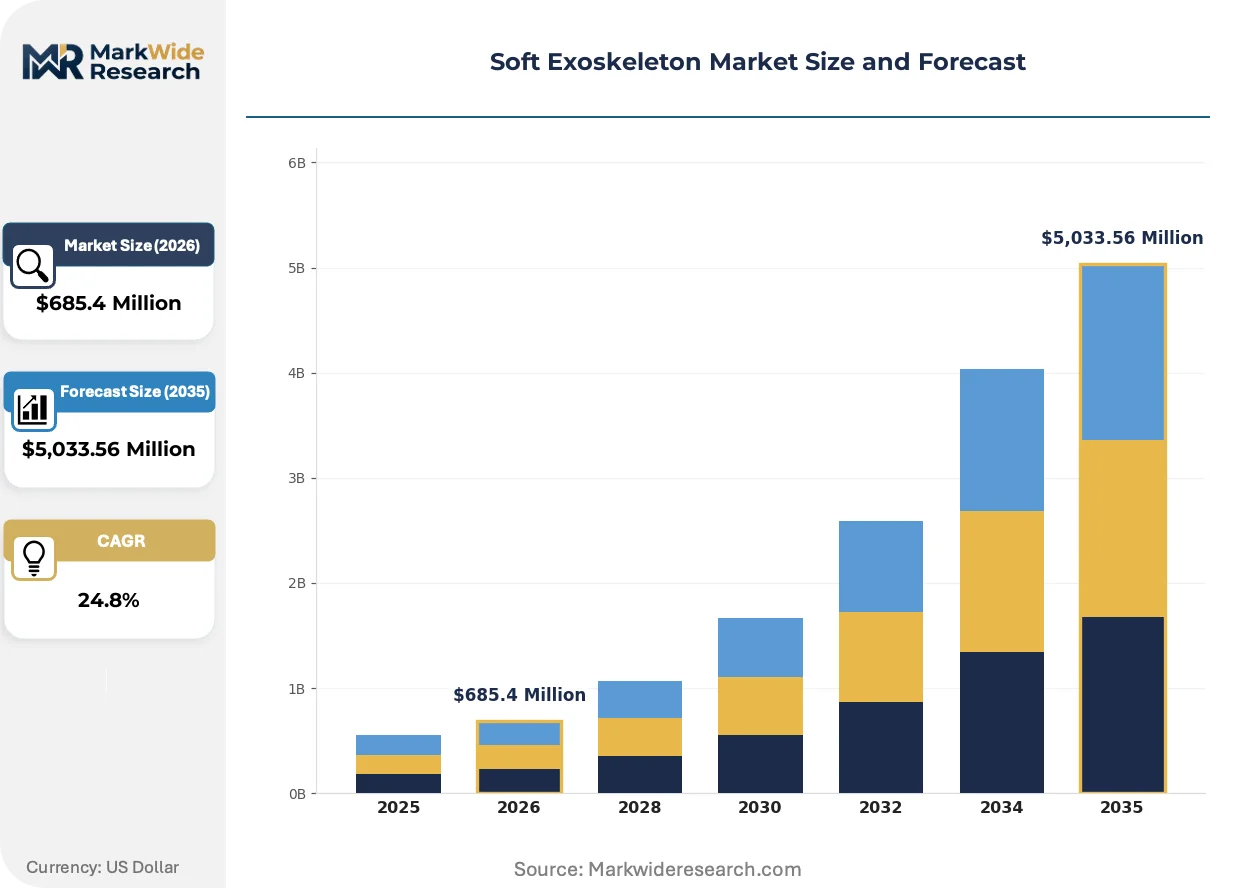
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $5,033.56 Million |
| CAGR (2026 – 2036) | 24.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assistive, Rehabilitation, Industrial, Military End User: Healthcare, Manufacturing, Defense, Agriculture Technology: Wearable Sensors, Actuation Systems, Control Algorithms, Soft Materials Application: Mobility Assistance, Heavy Lifting, Surgical Support, Physical Therapy |
| Companies Covered | Ekso Bionics, ReWalk Robotics, Bioservo Technologies, Roam Robotics, SuitX, Lockheed Martin, Cyberdyne, Panasonic, Ottobock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Exoskeleton Market Emerging Trajectories
Soft exoskeleton architecture is fragmenting into modular subsystems, with specialized suppliers capturing value from integrated manufacturers through component-level innovation in sensing, actuation, and control layers.
Textile-based sensing infrastructure is decomposing traditional rigid sensor arrays. Conductive fabric electrode arrays now capture surface electromyography and motion data through garment-integrated form factors. Rehabilitation clinics in Germany and Japan are adopting these systems for outpatient stroke therapy programs. This technology is decomposing the historical dominance of laboratory-grade motion capture systems in clinical gait analysis.
EU Medical Device Regulation's post-market surveillance requirements are intensifying clinical evidence obligations. Manufacturers must now maintain systematic literature review processes and periodic safety update reports across product lifecycles. Rehabilitation device categories face the steepest compliance cost escalation, driving consolidation among developers without dedicated regulatory affairs functions.
Leasing arrangements are displacing capital purchase models in industrial applications. Employers in US construction and logistics sectors prefer per-operator monthly fees inclusive of maintenance and training. This structure transfers obsolescence risk to manufacturers while accelerating fleet refresh cycles. Germany's Mittelstand manufacturing sector shows parallel adoption patterns for workplace assistive technology procurement.
Soft Exoskeleton Market Segmentation
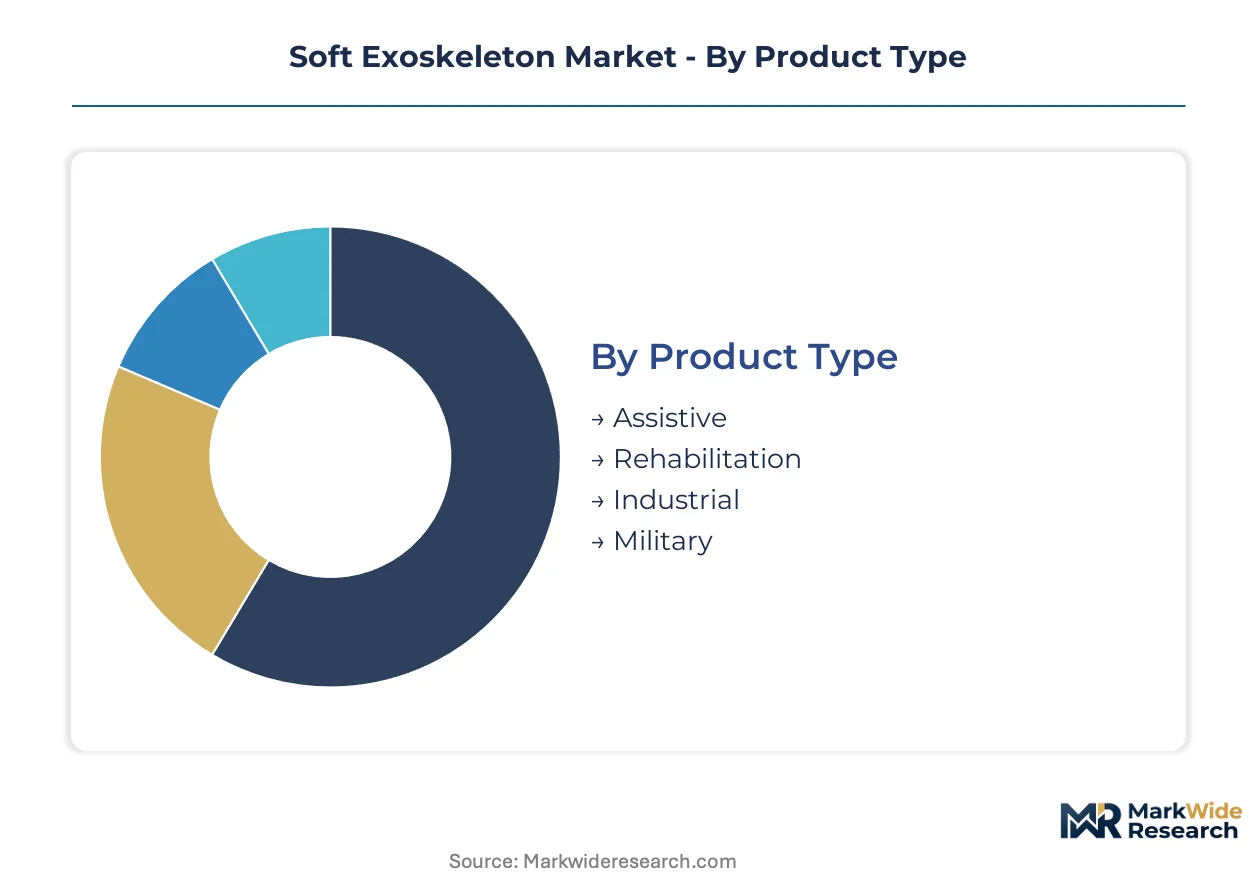
Segmentation reveals how soft exoskeleton architectures diverge across clinical, industrial, and defense procurement channels. Each dimension exposes distinct technical specifications, regulatory pathways, and pricing thresholds that reshape competitive positioning.
Product Type:
Assistive and rehabilitation devices concentrate demand within domestic healthcare systems, while industrial and military procurement increasingly sources through export-oriented manufacturers.
- Assistive:Textile-integrated structures with pneumatic artificial muscles augment ambulation for neurological impairment patients. German hospital networks and Japanese nursing care facilities drive procurement volume through statutory reimbursement frameworks.
- Rehabilitation:Closed-loop systems combining surface electromyography with cable-driven mechanisms restore motor function post-stroke. North American and European clinic chains prioritize FDA 510(k) and EU MDR Class IIa cleared devices for outpatient therapy programs.
- Industrial:Load-bearing frames reduce spinal compression during repetitive material handling. US construction firms and German Mittelstand manufacturers pilot leasing models tied to OSHA-recordable incident reduction.
- Military:Battery-powered tactical systems extend endurance during load carriage operations. Procurement concentrates within defense ministries seeking ISO 13485 certified suppliers with ITAR compliance infrastructure.
Assistive devices command the established base. The steepest expansion runs through industrial applications.
End User:
Cost tier stratification separates premium clinical systems from volume industrial deployments and specialized defense contracts.
- Healthcare:Hospital networks and outpatient clinics demand ISO 14155 validated clinical evidence for stroke and spinal cord injury applications. Reimbursement coding evolution across national health technology assessment bodies shapes procurement timelines.
- Manufacturing:Automotive assembly lines and logistics warehouses deploy passive and powered systems to reduce musculoskeletal disorder claims. German and Japanese employers lead enterprise adoption through workplace safety budget reallocation.
- Defense:Infantry load carriage and maintenance operations drive specifications for ruggedized, field-repairable architectures. Procurement emphasizes supply chain security and domestic component sourcing.
- Agriculture:Harvesting and livestock handling applications emerge in labor-constrained regions. Systems prioritize dust resistance and simplified maintenance protocols over precision control.
Healthcare captures premium pricing. Manufacturing delivers volume scaling.
Technology:
Patent filing intensity concentrates in sensing and materials layers, while actuation systems extract highest unit margins through specialized component supply constraints.
- Wearable Sensors:Conductive fabric electrode arrays capture surface electromyography and motion data through garment-integrated form factors. Silver-coated nylon textiles face precious metal price volatility that compresses margins at production scale.
- Actuation Systems:Pneumatic artificial muscles and miniature cable-drive mechanisms operate at power-to-weight ratios below 50 W/kg. German and Japanese precision valve suppliers concentrate manufacturing capacity, creating single-source vulnerability.
- Control Algorithms:Intent-predictive assistance models integrate surface electromyography with inertial measurement units. Development requires scarce biomechanist expertise concentrated within academic research institutions.
- Soft Materials:Elastomeric composites and textile substrates enable compliant, anthropomorphic fit. Silicone and thermoplastic polyurethane formulations balance durability against skin-contact biocompatibility requirements.
Actuation systems defend margin position. Wearable sensors gain patent share fastest.
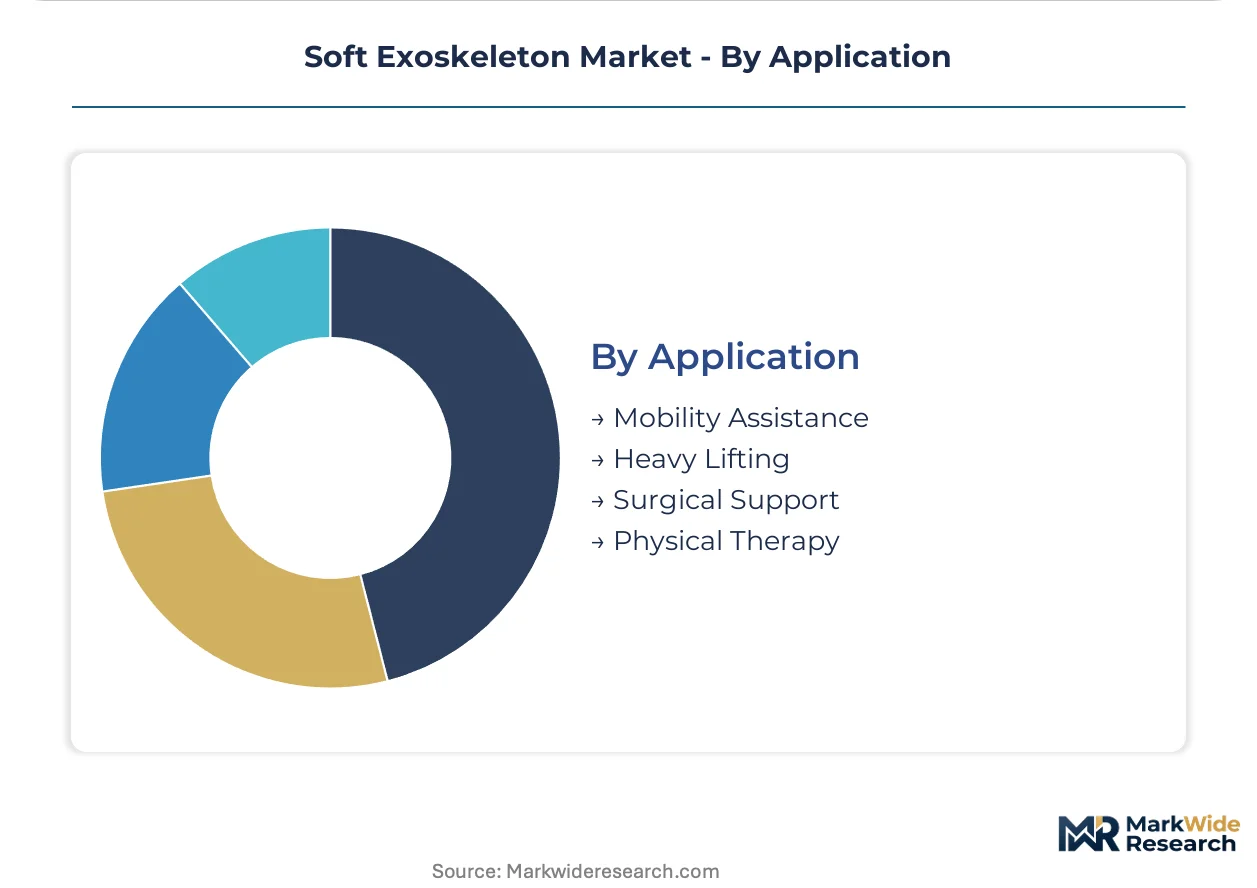
Application:
Volume concentration separates high-frequency rehabilitation sessions from episodic surgical support and emerging agricultural deployments.
- Mobility Assistance:Gait support systems for ambulation-impaired patients integrate closed-loop balance control. Japanese METI funding and German statutory health insurance reimbursement accelerate domestic adoption curves.
- Heavy Lifting:Spinal unloading during repetitive load handling targets construction and logistics workforces. US employers facing liability premium escalation pilot outcome-based leasing structures.
- Surgical Support:Surgeon posture maintenance during prolonged procedures represents nascent commercialization. Regulatory classification ambiguity delays reimbursement pathway establishment.
- Physical Therapy:Outpatient rehabilitation programs deploy resistive and assistive modes for motor relearning. HL7 FHIR electronic medical record integration requirements extend hospital procurement cycles.
Mobility assistance anchors clinical revenue. Heavy lifting scales industrial penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI funding for nursing care robotics and Germany's statutory health insurance reimbursement for assistive devices are accelerating procurement across hospital networks and industrial workplaces. The EU Medical Device Regulation's Class IIa classification harmonizes compliance requirements across multiple jurisdictions. FDA 510(k) pathways in the United States shape clinical trial investment priorities for rehabilitation device developers.
United States
OSHA-recordable musculoskeletal disorder claims drive employer liability premiums upward, prompting construction and logistics firms to pilot soft exoskeleton leasing programs. FDA 510(k) clearance timelines fluctuate based on predicate device availability, compressing capital recovery schedules for early-stage developers. Rehabilitation clinics in the Greater Boston and Pacific Northwest clusters prioritize outpatient therapy systems with HL7 FHIR electronic medical record integration.
Germany
Hospital networks expand procurement of stroke rehabilitation devices through statutory health insurance reimbursement frameworks. EU Medical Device Regulation conformity assessments and ISO 13485 certification requirements force capital reallocation toward quality management infrastructure. The Mittelstand manufacturing sector in Bavaria and Baden-Württemberg pilots workplace assistive technology leasing tied to incident rate reduction metrics.
Japan
PMDA and METI coordinate conditional early approval frameworks for nursing care robotics, compressing time-to-revenue for mobility support developers. Construction workforce aging concentrates demand for load-bearing assistive devices among 65-plus workers. Rehabilitation facilities in Tokyo and Osaka adopt textile-integrated sensing systems for outpatient gait therapy programs.
South Korea
Assessment bodies adopt regulatory templates from Japan's conditional approval frameworks for therapeutic robotics. Workplace safety budget reallocation accelerates enterprise procurement of industrial assistive devices for manufacturing assembly lines. Seoul Capital Area and Busan-Ulsan clusters concentrate pilot deployments for logistics material handling applications.
Australia
TGA assessment pathways for powered wearable devices align with EU Medical Device Regulation technical documentation standards. Healthcare procurement concentrates in New South Wales and Victoria hospital networks seeking ISO 14155-validated clinical evidence. Agricultural applications emerge in labor-constrained regions prioritizing dust-resistant maintenance protocols over precision control systems.
Soft Exoskeleton Market Vendor Landscape
Player mix skews toward rehabilitation specialists and industrial assistive developers, with defense contractors occupying a narrower procurement channel. The competitive structure fragments across ISO 13485-certified healthcare suppliers, METI-funded Japanese developers, and OSHA-focused American industrial providers. Strategic archetypes include clinical trial partnership builders, upstream component controllers, and orthotics distribution leverage players. Dominant competitive moves center on regulatory pre-certification investments and university biomechanist partnership structures.
Within the rehabilitation-specialist tier, Ekso Bionics and Cyberdyne exemplify contrasting geographic anchoring strategies. Ekso Bionics occupies a position tied to North American and European hospital network clinical trial partnerships. Cyberdyne represents upstream control over hybrid assistive limb neuromuscular signal processing architectures. Ottobock sits within the orthotics distribution leverage archetype, drawing on established payer relationships and rehabilitation clinic procurement channels. Panasonic and Lockheed Martin illustrate diversified corporate entries from adjacent electronics and defense sectors.
| Leading Market Players |
|---|
| Ekso Bionics |
| ReWalk Robotics |
| Bioservo Technologies |
| Roam Robotics |
| SuitX |
| Lockheed Martin |
| Cyberdyne |
| Panasonic |
| Ottobock |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Japanese precision valve manufacturers sits above 80 percent, compressing lead times for pneumatic artificial muscle suppliers and establishing price floors that cascade through actuation system tiers. This scale concentration forces soft exoskeleton developers to pre-commit volume or absorb premium spot pricing, particularly for ISO 13485-certified production lots destined for EU MDR Class IIa compliance.
Pricing Analysis
Certification level creates the primary spread across soft exoskeleton price tiers, with FDA 510(k)-cleared and EU MDR Class IIa-certified devices commanding substantial premiums over uncertified industrial prototypes. Three-tier pricing structure separates premium rehabilitation systems with closed-loop EMG control from standard assistive garments and economy-tier passive frames. Cost compression in the economy tier intensifies because silver-coated nylon textile suppliers face precious metal volatility. Healthcare procurement committees show lowest price sensitivity due to statutory reimbursement, while construction sector buyers negotiate aggressively on per-operator leasing rates.
Supply Chain Analysis
Inventory cycles for miniature pneumatic valves stretch 16-20 weeks, forcing soft exoskeleton manufacturers to hold strategic buffer stock or accept production delays. Component sourcing concentrates in Germany, Japan, and South Korea for precision valves, conductive textiles, and inertial measurement units. Elastomeric actuators, silver-coated sensing fabrics, and miniature cable-drive mechanisms anchor bill-of-materials costs. Single-source vulnerability runs through German valve suppliers serving multiple tier-one exoskeleton developers. Distribution runs through orthotics distributors for healthcare channels and direct enterprise sales for industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soft exoskeleton incumbents face substitution pressure from rigid-frame powered orthotics and autonomous mobile robots in material handling, requiring defensive positioning around clinical validation assets and regulatory pre-certification.
For Market Incumbents: Fortify regulatory moats by accelerating EU MDR technical documentation submissions ahead of notified body capacity constraints. Deepen upstream control over pneumatic valve supply through exclusive capacity agreements with German precision component manufacturers. Defend against emerging rigid-frame competitors by embedding textile-integrated sensing as the default clinical standard. For New Entrants and Emerging Players: Lead with agricultural applications in labor-constrained regions, where dust-resistant maintenance protocols and simplified control architectures face lower regulatory barriers than healthcare or defense channels. Target Australian and South Korean assessment bodies adopting Japan's conditional early approval templates. Pursue outcome-based leasing models with construction employers seeking OSHA-recordable incident reduction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with captive biomechanist talent pools and established ISO 14155 clinical trial partnerships. Long-term viability hinges on reimbursement code expansion across national health technology assessment bodies. Watch for inflection signals in HL7 FHIR electronic medical record integration mandates, which will consolidate procurement around data-compatible platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Accelerates multi-market deployment across German, French, and Italian hospital networks. |
| Pneumatic Valve Supply Agreement | Secures production capacity from German precision component manufacturers facing allocation constraints. |
| Hospital System Partnership | Establishes ISO 14155 clinical trial sites for stroke rehabilitation device validation. |
| Software Companion Development | Enables HL7 FHIR electronic medical record integration for extended procurement cycles. |
| Reimbursement Strategy | Aligns product positioning with evolving national health technology assessment body codes. |
Methodological Framework
The analysis maps assistive, rehabilitation, industrial, and military sub-sectors, each validated through biomechanist researchers, hospital purchasing committee members, GPO contracts managers, and industrial safety officers. Primary interviews with rehabilitation clinic directors and construction firm procurement leads combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, METI nursing care robotics program disclosures, and hospital procurement records. Bottom-up unit economics and top-down reimbursement flow models were triangulated for consistency.
Forecasts were validated against external benchmarks including regulatory approval trajectories and statutory reimbursement expansion timelines. Segmentation dimensions modeled include product architecture, end-user procurement channel, technology layer, and application intensity across the projection horizon. CAGRs were derived from installed base growth, replacement cycle compression, and pricing trajectory assumptions. Workforce aging demographics and OSHA-recordable musculoskeletal disorder claim patterns served as industry-specific demand inputs.
The analysis sits within stated boundaries; outcomes outside sustained METI funding levels, EU MDR notified body capacity expansion, or stable silver commodity pricing would require recalibration. Forecasts reflect documented assumptions about regulatory pathway harmonization and reimbursement code evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Healthcare Companion Robots Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Global IT Robotic Automation Market